Project Initiation Plan - Subsidiaries without Public Accountability - Disclosures
Project Type: Influencing Project Scope: Significant
Overview
1 SI/2019/685(5)(b)1 requires the UKEB to be responsible for "participating in and contributing to the development of a single set of international accounting standards.” The proposed project contributes to this work.
2 The IASB's Exposure Draft (ED) Subsidiaries without Public Accountability: Disclosures seeks to develop an accounting standard that would permits eligible subsidiaries to apply reduced disclosure requirements so long as they apply the recognition, measurement and presentation requirements in IFRS Standards.
3 This project forms part of IASB's Disclosure Initiative, a portfolio of projects exploring how to improve the effectiveness of disclosures in financial reporting. In particular, the IASB added the reduced-disclosure IFRS Standard project to its research pipeline in response to feedback from stakeholders (mainly preparers) on the Request for Views—2015 Agenda Consultation.
4 The IASB's ED was published on 26 July 2021 with a comment deadline of 31 January 2022.
5 The ED proposes:
- disclosure requirements for a subsidiary that elects to apply the Standard; and
- specifies the disclosure requirements in other IFRS Standards that are disapplied and are replaced if a subsidiary elects to apply the draft Standard.
6 In the UK, FRS 101 Reduced Disclosure Framework sets out an optional reduced disclosure framework which addresses the financial reporting requirements and disclosure exemptions for the individual financial statements of subsidiaries and ultimate parents that otherwise apply the recognition, measurement and disclosure requirements of UK-adopted international accounting standards (UK-IAS). FRS 101 is widely used in the UK. However, the impact of IASB's proposal for subsidiaries without public accountability is likely to be significant including the impact on companies applying FRS 101.
7 Additionally, it is important that the UKEB considers the ED proposals carefully as the reduced-disclosure IFRS Standard, when issued by the IASB, would be part of IFRS Standards and will need to be considered for endorsement and adoption in the UK. Ensuring the IASB has the opportunity to consider views of UK stakeholders during the standard's development is key to minimising new concerns being identified during the endorsement criteria assessment process.
8 Our outreach on IASB's Request for Information Third Agenda Consultation indicated strong interest from UK preparers in the IASB's Reduced Disclosures for Subsidiaries Without Public Accountability project, due to anticipated cost savings and reductions in complexity.
Objective of the project
9 As noted above this project forms part of IASB's Disclosure Initiative, a portfolio of projects exploring how to improve the effectiveness of disclosures in financial reporting. It specifically responds to the feedback that groups would prefer their subsidiaries without public accountability to prepare their financial statements applying IFRS Standards, but with reduced disclosure requirements.
10 The objective of the project, as set out in the ED, is to develop an IFRS Standard that would permit subsidiaries to apply IFRS Standards with reduced disclosure requirements. Such a Standard should: (i) reduce costs for subsidiaries without public accountability that report for consolidation purposes to a parent applying IFRS Standards; and (ii) maintain the usefulness of financial statements for users of those subsidiaries' financial statements.
Scope of the project
11 The ED proposes that an entity would be eligible to apply the draft Standard in its consolidated, separate or individual financial statements if and only if, at the end of its reporting period, it:
- is a subsidiary (as defined in IFRS 10 Consolidated Financial Statements);
- does not have public accountability2; and
- has an ultimate or intermediate parent that produces consolidated financial statements available for public use that comply with IFRS Standards.
12 Most insurance companies would be outside the scope of the ED. Nonetheless, some entities that issue insurance contracts within the scope of IFRS 17 could be eligible to apply the draft Standard. For example, a subsidiary that insures only the risks of its parent or its fellow subsidiaries (sometimes called a 'captive insurer'), and is not otherwise publicly accountable, might be eligible to apply the draft Standard. However, the disclosure requirements in IFRS 17 is unchanged for such a subsidiary applying the draft Standard. Furthermore, treasury subsidiaries would potentially be eligible to apply the draft Standard if they do not have public accountability.
Developing the disclosure requirements
13 In developing the disclosure requirements in the ED, the IASB started with the disclosure requirements in the IFRS for SMEs Standard as they are already tailored to the needs of the users of the financial statements of companies without public accountability and incorporate cost-benefit considerations. Consequently, the ED uses the disclosure requirements in the IFRS for SMEs Standard as a starting point but
- align terms and language with IFRS Standards; and
- update paragraph cross-references with the applicable paragraphs.
14 In addition, the IASB compared the recognition and measurement requirements in IFRS Standards and in the IFRS for SMEs Standard to identify differences. Where differences are identified, the ED tailors the disclosure requirements in IFRS Standards by applying the principles in paragraph BC157 of the IFRS for SMEs Standard. These principles identify the information that users find important and include:
- short-term cash flows and obligations, commitments or contingencies, whether or not recognised as liabilities;
- liquidity and solvency;
- measurement uncertainties; and
- disaggregations of amounts presented in the financial statements.
15 The ED includes reduced disclosures for all IFRS Standards issued as at 28 February 2021 and exposure drafts published as at 1 January 2021, except Exposure Draft ED/2019/7 General Presentation and Disclosures. However, not all disclosure requirements are removed. If a subsidiary applying the draft Standard chooses to:
- disclose earnings per share in its financial statements, it would be required to apply the disclosure requirements in IAS 33 Earnings per Share.
- apply IFRS 8 Operating Segment, it is not exempted from IFRS 8 disclosure requirements.
16 Disclosure requirements about transition included in a new or amended IFRS Standard would be required when applying the draft Standard.
Initial identification of issues
17 Our initial desk-based review of the standard and its requirements has identified some high-level issues related to the scope and applicability of the standard.
Scope and Applicability
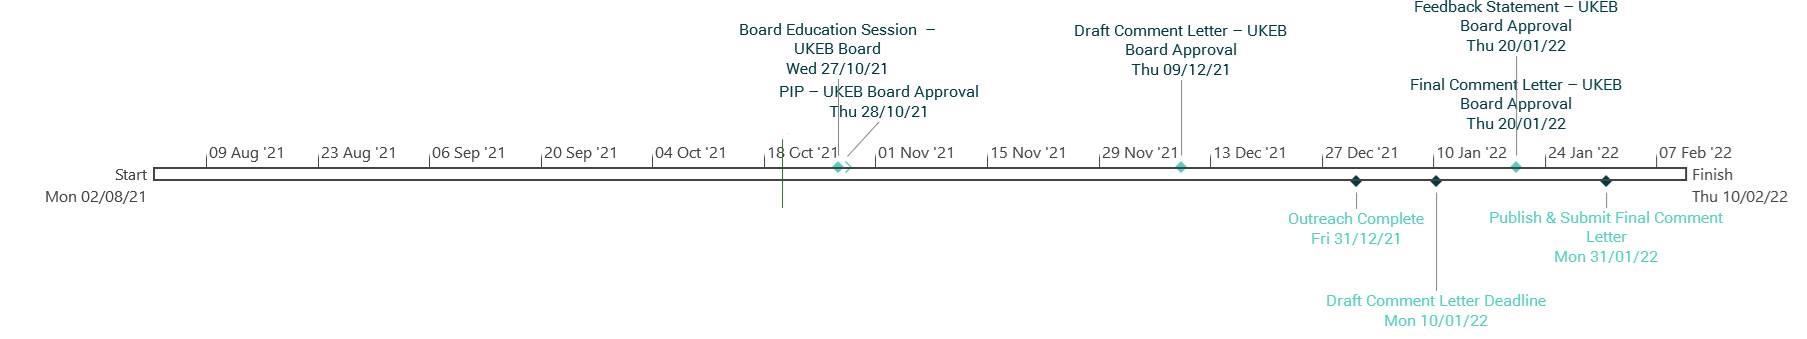
18 Stakeholders have questioned whether the ED is compatible with the legislation in the UK. Initial analysis indicates no incompatibilities between the IASB's proposals included in the ED and the Companies Act 2006. The draft Standard would be part of IFRS Standards and financial statements prepared applying the draft Standard would be IAS individual or group accounts and not companies Act accounts. Section 395 and 403 of the Companies Act 2006 already permit a company's individual and group accounts (respectively) to be prepared in accordance with international accounting standard.
19 Many jurisdictions support a wider scope of entities to which the ED could be applicable, for example all entities without public accountability (similar to the alternative view in the ED). For instance, EFRAG in its Draft Comment Letter cautiously agree with the IASB's proposed scope and recognise that there is also support for widening the scope to all entities without public accountability. Consequently, EFRAG is seeking constituents' input on the scope of the ED.
The proposed disclosure requirements
20 Paragraphs 22-213 of the ED set out the proposed disclosure requirements for an entity that applies the draft Standard. Nonetheless, some disclosures might need to be added on the basis of users' information needs and for some IFRS Standards further reductions in disclosure requirements could be considered by the IASB ie IFRS 7 Financial Instruments. Disclosures.3 Feedback from outreach activities would provide more input on disclosures that could be added or removed and whether the reduced disclosure requirements would maintain the usefulness of the financial statements to the users of those subsidiaries' financial statements.
Comparability
21 The draft Standard would be optional for eligible entities. Consequently, the financial statements of two similar subsidiaries that apply IFRS Standards could be different if only one applied the draft Standard. The two subsidiaries' financial statements are unlikely to provide the same disclosures, but both financial statements would still comply with IFRS Standards.
Cost-benefit considerations
22 In developing the proposed disclosure requirements, the ED used the principles in paragraph BC157 of the IFRS for SMEs Standard as outlined above. However, these key principles considered by the IASB excludes cost-benefit considerations. This appears inconsistent with the objective of the ED, which is to reduce cost of financial reporting for subsidiaries.
Key planning assumptions, constraints and timeline
Comment deadline and resource capacity
23 We have commenced activities related to this project and will provide stakeholders sufficient time to provide feedback on the ED. We are alive to the likely significant impact for potentially large number of UK entities and intend to maximise engagement with stakeholders.
24 In addition, we plan to leverage the outreach conducted on the project Disclosure Initiative—Targeted Standards-level Review of Disclosures to reach out to stakeholder and maximise responses on the ED.
25 After the Exposure Draft was published in July 2021, we undertook the following activities during August and September:
- Reach out to the IASB project team to seek clarification on some aspects of the ED.
- Compare the disclosure requirements in the ED with FRS 101 and outreach to the relevant team at the Financial Reporting Council for initial discussion about the impact of the ED on use of FRS 101.
- Obtain data about the number of UK companies applying FRS 101.
- Assess any incompatibilities between the IASB's proposals and UK legislation.
- Develop a survey.
- Investigate key concerns with the proposals in the ED in other jurisdictions.
Assumptions
26 We have made the following assumptions in developing this project plan:
- The work will be mainly focused on outreach with stakeholders.
- Outreach will be focused on preparers to better understand the benefits of reduced disclosures and assess the appetite for the draft Standard.
- That a draft comment letter will be presented for Board approval at the 9 December 2021 meeting and will be open to stakeholder comment for a period of four weeks to allow stakeholders sufficient time to engage prior to a final comment letter being presented to the Board.
- That the Board will approve the final comment letter at its January 2022 meeting to ensure the final comment letter can be submitted to the IASB on 31 January 2022.
Outreach
UK stakeholders
27 The ED proposals permitting eligible subsidiaries to provide reduced disclosures in their financial statements is likely to impact a wide range of stakeholders, but mainly preparers and users of financial statements. Therefore, our outreach strategy is focused on identifying potentially affected entities to discuss the impact of the IASB's proposals on their financial reporting.
28 Other outreach activities would include an educational video in conjunction with IASB with the aim of exploring key elements of the proposals, raise awareness of the proposals and encourage stakeholders to provide their feedback to the UKEB or the IASB or both.
29 In addition, we will develop a survey aimed at preparers of subsidiary financial statements to understand the implications of the ED. The survey will help us to better understand any specific issues with the disclosure requirements, the transition to the reduced-disclosure IFRS Standard, and whether the ED achieves its objective of reducing costs of financial reporting for preparers. The survey will also help us better understand the UK entities in the scope of the ED that issue insurance contracts and the disclosures that would be relevant to them. We will directly approach and request completion of the survey by the preparers identified as having an interest in adopting the draft reduced-disclosure IFRS Standard as well as publishing it on our website. The survey may also help us identify stakeholders willing to participate in roundtables to obtain more in-depth feedback on the ED.
30 These views will be used to inform our draft comment letter. During the period that the draft comment letter is open to consultation we will aim to undertake further interviews with users and other individual stakeholders if the opportunities arise.
31 Other stakeholders that could be contacted include Technical Partners of accounting firms focusing on clients that that apply FRS 101, to help us identify entities that are likely to adopt the reduced-disclosure IFRS Standard.
32 We have commenced discussion with the relevant team at the Financial Reporting Council. We understand that they have closely followed the development of the proposals in the ED and intend to respond to the IASB to share their experience of development of FRS 101. We aim to maintain an ongoing dialogue with the team to understand their view of the requirements proposed in the ED and whether there are overlaps with issues we identify during our outreach.
International stakeholders
33 We are already in touch with the IASB's project team and have a plan in place to record a joint educational video on the ED, which will be hosted on the UKEB website.
34 EFRAG issued its draft comment letter on the IASB's ED on 30 September 2021 and has a comment deadline of 26 January 2022. The Australian Accounting Standards Board (AASB) issued the ED in September 2021 to invite comment on IASB's proposals, including the ‘AASB Specific Matters for Comment’ and has a comment deadline of 1 November 2021. We have reached out to EFRAG and AASB project teams to discuss their key areas of concern and views of the disclosure requirements proposed in the ED.
35 We have also reached out to the Malaysian Accounting Standards Board to discuss their concerns on the proposals in the ED.
36 Outreach work is planned to occur between November and December.
Project closure
37 Consistent with the proposals in the draft Due Process Handbook, the Feedback statement should be approved by the Board at the same time as the comment letter.
Project timeline
38 The proposed high-level project timeline is as follows:
| Date | Responsible Body | Milestones |
|---|---|---|
| 28 October | Board | Approve PIP |
| 9 December | Board | Approve draft comment letter |
| 13 December | Publish draft comment letter | |
| 10 January | Deadline for stakeholder responses to UKEB DCL | |
| 20 January | Board meeting | Approve final comment letter & feedback statement |
| 31 January | Submit final comment letter to IASB |
Footnotes
Footnotes
-
The International Accounting Standards and European Public Limited-Liability Company (Amendment etc.) (EU Exit) Regulations 2019: https://www.legislation.gov.uk/uksi/2019/685/made ↩
-
An entity has public accountability if:
- ↩
-
For example, FRS 101 exempts a qualifying entity from the requirements of IFRS 7 Financial Instruments. Disclosures, provided that equivalent disclosures are included in the consolidated financial statements of the group in which the entity is consolidated. A qualifying entity which is a financial institution is not exempted from the requirements of IFRS 7. ↩
-