Report on the carrying out of functions designated under The International Accounting Standards (Delegation of Functions) 2022-23
Report on the carrying out of functions designated under the International Accounting Standards (Delegation of Functions) EU Exit) Regulations 2021
Presented to Parliament pursuant to Regulation 17 of the International Accounting Standards and European Public Limited-Liability Company (Amendment etc.) (EU Exit) Regulations 2019
OGL © copyright 2023
This publication is licensed under the terms of the Open Government Licence v3.0 except where otherwise stated. To view this licence, visit nationalarchives.gov.uk/doc/open-government-licence/version/3.
Where we have identified any third party copyright information you will need to obtain permission from the copyright holders concerned.
This publication is available at: www.gov.uk/official-documents.
Any enquiries regarding this publication should be sent to the UK Endorsement Board, 6th Floor, 10 South Colonnade, London, E14 4PU or [email protected].
- About the UKEB
- Our Legal Remit and Reporting on Technical Work
- Endorsement and Adoption Criteria
- Mission, Vision, Values and Legislative Criteria
- UKEB Highlights for the Year
- UKEB Technical Work on Financial Reporting
- Influencing Development of IFRS Accounting Standards
- Endorsement and adoption
- Completed Projects
- IFRS 17 Insurance Contracts (Effective date: 1 January 2023)
- Narrow-scope Amendments 2020 (Effective date: 1 January 2022)
- Narrow-scope Amendments 2021 (Effective date: 1 January 2023)
- IFRS 17 Insurance Contracts: adopted on 16 May 2022 and published 17 May 2022
- Narrow-scope Amendments 2020: adopted on 12 April 2022 and published on 13 April 2022
- Narrow-scope Amendments 2021: adopted on 30 November 2022 and published on 2 December 2022
- Current Active Projects – adoption decision likely in 2023/24
- UKEB Technical Work on Sustainability Reporting
- Working with Other International Organisations
- Organisational Structure and Our People
- Governance and Transparency
About the UKEB
Background
1The Companies Act 2006 sets out the duty for UK registered entities to produce individual and group accounts, and the applicable accounting framework to be used.
2Public companies listed on a regulated market in the UK must use UK-adopted international accounting standards for their group accounts. Private companies, above the small company threshold, may also choose to produce their accounts using international accounting standards. An estimated 14,000 UK registered private companies reported under these standards in 2022/23, on a voluntary basis.
3All remaining private UK registered companies are required to produce their annual accounts using domestic accounting standards, known as UK GAAP (Generally Accepted Accounting Principles). UK GAAP is based on UK-adopted international accounting standards and may generally be seen as a less complex version.
4Before the UK's exit from the EU, the EU Commission was responsible for IFRS Accounting Standards being adopted for use by companies in all Member States. After EU Exit, the Government set up the UK Accounting Standards Endorsement Board (‘UKEB'), an independent body, with specific delegated powers.
5Currently, 144 jurisdictions require IFRS-based Standards for all or most companies, including the UK and all EU countries. The major exception is the United States, which uses its own national standards known as US GAAP.
Our Purpose
6The UKEB is responsible for the endorsement and adoption of new or amended international accounting standards, known as IFRS Accounting Standards, issued by the International Accounting Standards Board (‘IASB') for use by UK companies, in accordance with the statutory criteria.
7The UKEB is also responsible for influencing the development of a single set of global international financial reporting standards.
8The UKEB consults publicly with stakeholders that have an interest in financial reporting in the UK so that it can develop and represent evidence-based UK views with the aim of acting as the UK's voice on IFRS financial reporting.
Our Legal Remit and Reporting on Technical Work
9Chapter 3 of The International Accounting Standards and European Public Limited Liability Company (Amendment etc.) (EU Exit) Regulations 2019 (SI 2019/685) confers on the Secretary of State for Business, Energy and Industrial Strategy ('BEIS')1 functions relating to the adoption of IFRS for application in the UK.
10The Secretary of State exercised the power, conferred by Chapter 4 of those Regulations, to delegate the functions specified in The International Accounting Standards (Delegation of Functions) (EU Exit) Regulations 2021 (SI 2021/609) to the UKEB. This delegation of powers came into force on 22 May 2021.
11Regulation 12 of 2019/685 sets out the requirement of the Secretary of State to lay a report before Parliament, on the carrying out of the responsibilities set out in the regulations, annually.
12The UKEB Terms of Reference state, at paragraph 3.4(b), that the UKEB Chair is responsible for reporting to the Secretary of State on how the UKEB is discharging its functions.
13This report fulfils the above stated annual reporting requirement, covering the period from 1 April 2022 to 31 March 2023.
Endorsement and Adoption Criteria
14The UKEB may only adopt an international accounting standard if the standard is not contrary to the principles set out in the legislation and if the Board decides that use of the standard is likely to be conducive to the long term public good in the UK.
In accordance with regulation 7(1) of Statutory Instrument 2019/685, the adoption criteria are:
- the standard is not contrary to either of the following principles-
- an undertaking's accounts must give a true and fair view of the undertaking's assets, liabilities, financial position and profit or loss;
- consolidated accounts must give a true and fair view of the assets, liabilities, financial position and profit or loss of the undertakings included in the accounts taken as a whole, so far as concerns members of the undertaking;
- the use of the standard is likely to be conducive to the long term public good in the United Kingdom; and
- the standard meets the criteria of understandability, relevance, reliability and comparability required of the financial information needed for making economic decisions and assessing the stewardship of management.
In deciding whether the use of the standard is likely to be conducive to the long term public good in the United Kingdom, the Board is required to consider:
- whether the quality of financial reporting is likely to be improved;
- the costs and benefits; and,
- whether an adverse effect on the UK economy, including economic growth, is likely.
Mission, Vision, Values and Legislative Criteria
15The UKEB was established with a specific mission and vision, to be achieved via a core set of values, as outlined below:
Mission
To serve the UK public good by leading the development and synthesis of UK views on financial reporting and representing them in the international arena, ensuring that the UK's voice is influential in the development of high-quality international accounting standards that are suitable for adoption in the UK.
Vision
To maintain the high quality of UK financial reporting that underpins confidence in the UK's capital markets and reinforces its reputation for transparency.
Values
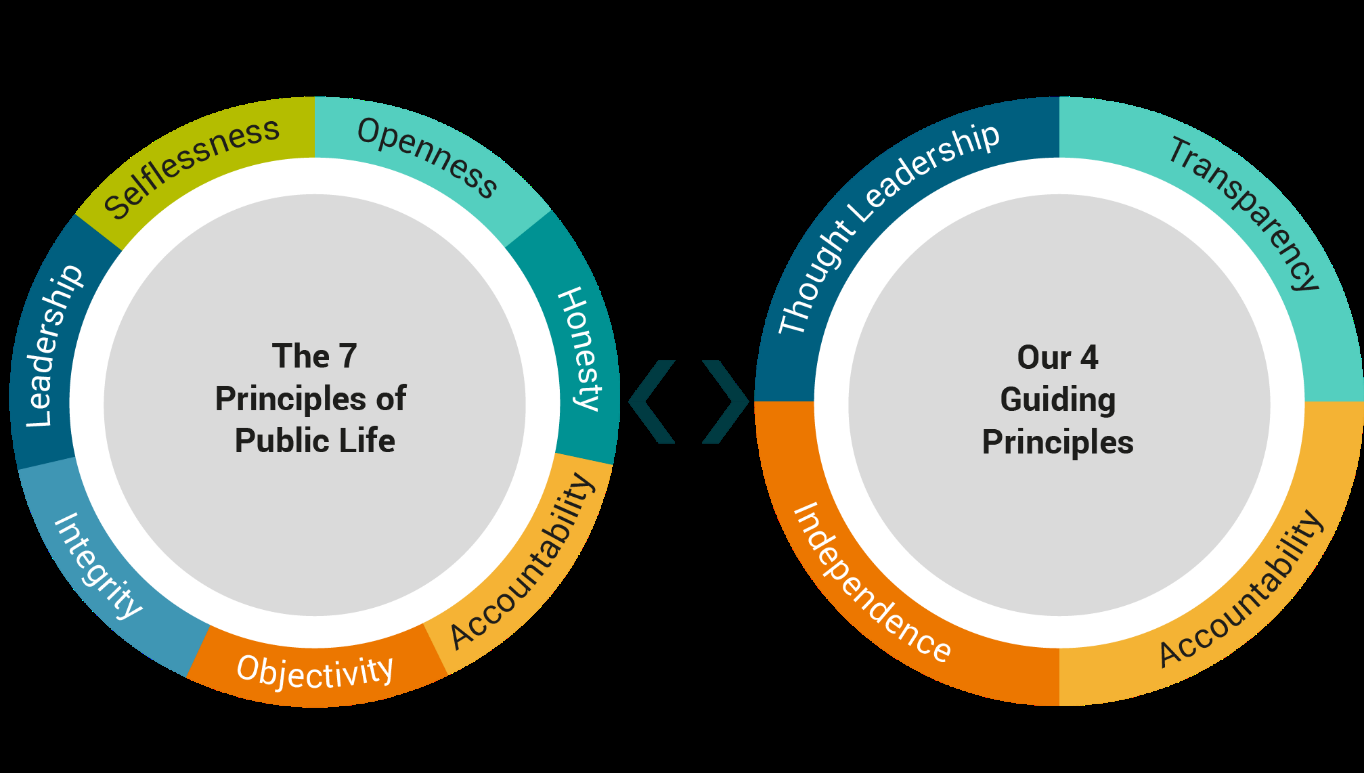
The UKEB operates in the public interest, following the seven principles of public life and our four guiding principles: Independence, Accountability, Thought Leadership, and Transparency.
Legislative Criteria
The UKEB must consider each new standard or amendment against criteria set out in legislation.
UKEB Standard Endorsement Process
This diagram illustrates the process of how the UKEB influences the IASB, and how the UKEB considers a standard for adoption once the IASB issues it.
UKEB influences the IASB (Pre-standard issuance): * Conducts research * Consults stakeholders * Regular engagement with IASB * Responds to Discussion Papers/Exposure Drafts * IASB develops standard
IASB issues standard
UKEB considers standard for adoption: * Applies criteria in IAS Statutory Instrument * Develops draft Endorsement Criteria Assessment and consults stakeholders * Formally adopts the standard for use in the UK
UKEB influences the IASB (Post-implementation): * Conducts research * Consults stakeholders * Engages with and issues recommendations to IASB * IASB Post-Implementation Review
UKEB Highlights for the Year
UKEB 2022/23 Highlights
The diagram outlines the key achievements of the UKEB in 2022/23 across four categories:
Structural: * 2 new Board Members appointed * Advisory and Working Groups established
Research published: * 'Subsequent Measurement of Goodwill: a Hybrid Model' * 'Accounting for Intangibles: UK Stakeholders' Views'
Influencing: * Outreach with UK stakeholders * 3 Comment Letters (to IASB & ISSB) * Presentations at ASAF and IFASS: Goodwill Research and IASB/ISSB Connectivity Papers
Endorsements: * IFRS 17 – Insurance Contracts * 6 narrow-scope amendments * 3 minor annual improvements
UKEB Technical Work on Financial Reporting
Early Stage Influencing – Research
16Research projects relate directly to the UKEB guiding principle of thought leadership. They also relate to the other UKEB guiding principles, as follows:
- Accountability: Research projects allow for early engagement with stakeholders. They also provide a wider range of evidence to support later decision making. All of which supports greater accountability to stakeholders.
- Independence: The UKEB assesses projects independently and acts independently in the UK's long-term public good.
- Transparency: Research is discussed in public at UKEB Board meetings, may be published as a report or paper, and forms the basis of presentations and outreach. This provides transparent engagement with the evidence and findings.
17Research projects build on, and complement, the UKEB's influencing strategy. The objective of research projects is to influence and improve financial reporting both in the UK and globally which meets the statutory requirements to contribute to the development of a single set of international accounting standards.
18The UKEB's research projects are aimed at:
- identifying, and promoting new ways of thinking about and solving, deficiencies in financial reporting, new and emerging issues, and complex financial reporting problems;
- influencing the long-term agenda and development of IFRS Standards;
- informing Board deliberations on accounting matters through the provision of wider evidence; and,
- supporting the work of the IFRS Foundation and others responsible for IFRS Standards.
Goodwill Research Project
19The UKEB commenced its Goodwill Research Project on 20 January 2022. The research report Subsequent Measurement of Goodwill: a Hybrid Model was published on 26 September 2022. The report contributes to the ongoing international debate on the subsequent measurement of goodwill.
20The report explores the effects of the application of the impairment-only model for UK IFRS reporters from 2005 to 2021 and explores the practical implications of a potential transition to a hybrid model for subsequent measurement of goodwill that combines impairment testing with annual amortisation.
21The report presents the results of a survey, field test and stakeholder outreach which explored the implications of a transition to a hybrid model for subsequent measurement of goodwill.
22The research indicates that a transition to a hybrid model would be practically feasible as:
- A useful life for goodwill may be estimated through consideration of a range of relevant factors.
- Suitable transition arrangements could be provided for legacy goodwill.
- No significant adverse consequences for financial stability or for processes, operations or costs were identified.
Intangibles Research Project
23Accounting for intangible items is expected to form a key part of the IASB's future standard setting agenda. The UKEB is undertaking a comprehensive research project to consider how the accounting for, and reporting of, intangible items could be improved to provide investors with more useful general purpose financial statements to assist them to make better informed decisions.
24The UKEB published its report 'Accounting for Intangibles: UK Stakeholders' Views' in March 2023. It sets out stakeholder views on the accounting for intangibles under international accounting standards within the context of the wider economic impact of intangibles in the UK.
25UK stakeholders, interviewed for the report, highlighted concerns about current IFRS Accounting Standards, including limited recognition, inconsistent accounting, and disclosure of intangibles; though some stakeholders expressed support for maintaining the current approach. The report also identifies a range of possible enhancements suggested by stakeholders. Investors predominantly focused on enhancing disclosures about intangibles.
26While the report does not reflect an official position of the UKEB, it will inform its future work, including further research and engagement with the IASB, and help it to ensure that any future international accounting standard reflects the views of UK stakeholders.
27The UKEB is currently conducting further research looking at reporting on intangibles in UK financial statements and the views of users of financial statements on accounting for intangibles.
Influencing Development of IFRS Accounting Standards
28The UKEB's influencing activities contribute to the development of international financial reporting standards that:
- support the efficient allocation of capital and help to maintain the UK's position as a leading capital market;
- improve the quality of information reported by UK entities;
- address emerging issues in the UK financial reporting environment; and,
- take account of the costs and benefits of financial reporting standards for UK stakeholders.
29The UKEB's values are demonstrated through a proactive approach to research and outreach and in the publication of feedback statements explaining how the UKEB has responded to stakeholder input for each major influencing project.
30The UKEB influences the IASB by contributing to its research agenda and responding to their due process documents. The UKEB's influencing activities also include seeking views from UK stakeholders on emerging issues; engaging with other national standard setters; and, conducting outreach activities on current projects.
31The type of outreach activities the UKEB carries out include surveys, roundtables, panel events, public consultation on draft comment letters, and field testing.
32During this year, the UKEB completed two such projects, one on the IASB's proposals on non-current liabilities with covenants and a second one on supplier finance arrangements. A third project on the international tax reform - Pillar Two model rules was commenced during this reporting period but completed during the following reporting period.
Non-Current Liabilities with Covenants (Proposed Amendments to IAS 1)
33In November 2021 the IASB published its Exposure Draft ED/2021/9 Non-current Liabilities with Covenants (Proposed Amendments to IAS 1).
34The Exposure Draft ('ED') aims to improve the information an entity provides when its right to defer settlement of a liability for at least twelve months is subject to compliance with conditions (e.g. covenants), in addition to addressing concerns about the classification of such a liability as current or non-current.
35The proposed amendments would specify that conditions with which an entity must comply within twelve months after the reporting period do not affect classification of a liability as current or non-current. Instead, entities would present separately, and disclose information about, non-current liabilities subject to such conditions.
36The ED also proposes deferring the effective date of the amendment Classification of Liabilities as Current or Non-Current (Amendments to IAS 1) to at least 1 January 2024.
Outreach
37The UKEB's outreach on this project included discussions with stakeholders, including representative bodies, and public consultation on our draft comment letter.
Final Comment Letter
38The UKEB published its Final Comment Letter on 22 March 2022. The letter was supportive of a number of the proposals in the ED as they will lead to clearer classification and disclosure of non-current liabilities with covenants that will assist users' decision making. However, the Board raised concerns about some of the proposals in the ED leading to unintended consequences.
39The Board recommended that further standard setting should happen only if there is evidence of significant diversity in practice.
40The Due Process Compliance Statement for this project was approved and published during April 2022.
Supplier Finance Arrangements (Proposed Amendments to IAS7 and IFRS 7)
41In November 2021, the IASB published an Exposure Draft (‘ED') on Supplier Finance Arrangements proposing amendments to IAS 7 Statement of Cash Flows and IFRS 7 Financial Instruments: Disclosures.
42The proposals were intended to complement the existing disclosure requirements in IFRS Standards that apply to supplier finance arrangements. The ED used 'supplier finance arrangement' to refer to a reverse factoring or similar arrangement.
43The proposed amendments would affect an entity that, as a buyer, enters into one or more supplier finance arrangements, under which the entity, or its suppliers, can access financing for amounts the entity owes its suppliers.
44The proposals aimed to provide users of financial statements with the information that enables them to assess the effect of supplier finance arrangements on an entity's liabilities and cash flows, as well as on its liquidity risk and risk management.
Outreach
45The UKEB's outreach on this project included discussions with stakeholders, including representative bodies, and public consultation on our draft comment letter.
Final Comment Letter
46The UKEB published its Final Comment Letter on 28 March 2022. The letter was supportive of the proposals in the ED as they will improve transparency and enhance the ability of users of accounts to assess the effects of these arrangements on an entity's liabilities and cash flows, as well as on its liquidity risk and risk management. However, recommendations to enhance the proposals in the ED were also provided.
47The Due Process Compliance Statement for this project was approved and published during April 2022.
International Tax Reform – Pillar Two Model Rules (Proposed amendments to IAS 12)
48The UKEB also commenced a project on the IASB's proposals regarding the international tax reform - Pillar Two model rules.
49The IASB published the Exposure Draft International Tax Reform—Pillar Two Model Rules in January 2023. The Exposure Draft was open for comment until 10 March 2023.
50A special ad hoc Board meeting was held on 7 March 2023 to approve the UKEB Final Comment Letter.
51The full details of this project will be included in the UKEB’s 2023/24 Annual Report to the Secretary of State on its technical work as this project was completed after the reporting period.
Endorsement and adoption
52The UKEB assesses an international accounting standard against statutory criteria. A standard may only be adopted if it is not contrary to the principles set out in the legislation2 and if the Board decides that use of the standard is likely to be conducive to the long term public good in the UK.
53The following diagram is the high-level process the UKEB follows to adopt a standard for use in the UK. It includes the requirement for decisions to be published within 3 days.
UKEB Standard Endorsement Process
This flowchart illustrates the high-level steps for the UKEB to adopt an international accounting standard for use in the UK:
- IFRS Issued
- Assess IFRS against Endorsement Criteria (refer to page 4 for criteria)
- Draft Endorsement Criteria Assessment (DECA)
- Public Consultation
- Final Endorsement Criteria Assessment (ECA)
- Tentative vote to adopt - in a public meeting
- Final written vote
- ADOPTED
- Standard Posted to UKEB website within 3 days
Completed Projects
54During the year the UKEB completed a number of projects to adopt into UK-adopted IFRS, available for the use of UK companies. These included one significant new standard on accounting for insurance contracts, namely IFRS 17 Insurance Contracts, and nine narrow-scope amendments.
IFRS 17 Insurance Contracts (Effective date: 1 January 2023)
- IFRS 17 Insurance Contracts
Narrow-scope Amendments 2020 (Effective date: 1 January 2022)
- Amendment to IFRS 1 First-time Adoption of International Financial Reporting Standards – Subsidiary as a First-time Adopter (Annual Improvements to IFRS 2018–2020)
- Amendment to IFRS 9 Financial Instruments – Fees in the '10 per cent' Test for Derecognition of Financial Liabilities (Annual Improvements to IFRS 2018–2020)
- Amendment to IAS 41 Agriculture – Taxation in Fair Value Measurements (Annual Improvements to IFRS 2018-2020)
- Onerous Contracts – Cost of Fulfilling a Contract (Amendments to IAS 37)
- Property, Plant and Equipment: Proceeds before Intended Use (Amendments to IAS 16)
- Reference to the Conceptual Framework (Amendments to IFRS 3)
Narrow-scope Amendments 2021 (Effective date: 1 January 2023)
- Disclosure of Accounting Policies (Amendments to IAS 1 Presentation of Financial Statements and to IFRS Practice Statement 2 Making Materiality Judgements)
- Definition of Accounting Estimates (Amendments to IAS 8 Accounting Policies, Changes in Accounting Estimates and Errors)
- Deferred Tax related to Assets and Liabilities arising from a Single Transaction (Amendments to IAS 12 Income Taxes)
IFRS 17 Insurance Contracts: adopted on 16 May 2022 and published 17 May 2022
55The IASB published IFRS 17 Insurance Contracts (IFRS 17) in May 2017. IFRS 17 is a fundamental overhaul of insurance accounting which will ensure that an entity provides relevant information to its investors that faithfully represents those insurance contracts. It replaces an interim standard which does not prescribe requirements for the recognition, measurement or presentation of insurance contracts and allows entities to use a wide variety of accounting practices, thereby impairing comparability between similar companies.
56IFRS 17 requires entities that issue insurance contracts to use updated estimates and assumptions that reflect the timing of cash flows and any uncertainty relating to insurance contracts. Profits are only recognised as the entity delivers services, and entities must provide information about insurance contract profits they expect to recognise in the future.
57Although IFRS 17 was published by the IASB before the UK's Exit from the EU, the EU's process for adoption of the standard had not been completed by that date. As a result, IFRS 17 was not incorporated into Domestic UK law as UK-adopted international accounting standard at the end of the Implementation Period on 31 December 2020.
58Subsequent to the publication of IFRS 17, the IASB published two further amendments to the standard: "Amendments to IFRS 17" in June 2020 and "Initial Application of IFRS 17 and IFRS 9-Comparative Information" in December 2021. These two amendments have been included in the UKEB's assessment of IFRS 17.
59The UKEB assessed IFRS 17 against the adoption criteria set out in Regulation 7 of the IAS Regulations. Given the significant change in accounting, the UKEB held extensive discussions with a broad range of stakeholders, in accordance with Regulation 8 of the IAS Regulations. The work to support the IFRS 17 endorsement assessment spanned many months and was responsive to stakeholder input throughout. The UKEB's assessment work included:
- desktop analysis of the standard, the basis for its requirements, and of commentaries and technical analyses issued by, for example, accounting firms and professional bodies;
- consideration of feedback from UK stakeholders on IFRS 17 as issued in 2017 and their input to the amendments finalised in 2020, including comment letters submitted to the IASB;
- a review of submissions to EFRAG from UK stakeholders, discussions with EFRAG staff and a review of EFRAG's Draft and Final Endorsement Advice given that EFRAG's work occurred on behalf of the UK until the UK's Exit from the EU;
- discussions with insurance companies, Lloyd's of London and the Association of British Insurers, and a survey of UK insurers;
- consideration of investor and analyst views expressed to the IASB during its outreach work, discussions with UK-based analysts and ratings agencies and a survey of users of insurance company accounts;
- the establishment of an Insurance Technical Advisory Group, which assisted the UKEB Secretariat in developing the group's work plan and forward agenda, and undertook detailed technical consideration of potential UK endorsement issues; and,
- further technical input from auditors, accountants and actuaries, as appropriate, in relation to specific endorsement issues.
60The UKEB was satisfied that IFRS 17 meets the criteria in Regulation 7. The UKEB, therefore, approved IFRS 17 for adoption for use in the UK on 16 May 2022.
61Application of IFRS 17 is mandatory for financial years beginning on or after 1 January 2023. Early application is permitted if an entity also applies IFRS 9 Financial Instruments on or before the date of initial application of IFRS 17.
62Regulation 11 of the IAS Regulations requires a review of the impact of the adoption of a standard where that standard is considered to be a "significant change in accounting practice". The UKEB's policy on the meaning of a "significant change in accounting practice" is set out at 8.6 and 8.7 of the UKEB's Due Process Handbook. Implementation of IFRS 17 has been assessed by the UKEB as a significant change in accounting practice. Therefore, the impact of IFRS 17 will be reviewed under Regulation 11 before 31 December 2027.
63Further information, including the UKEB's Endorsement Criteria Assessment, Feedback Statement and Adoption Statement, is available on the UKEB's website: here.
Narrow-scope Amendments 2020: adopted on 12 April 2022 and published on 13 April 2022
64The 2020 Amendments ('the Amendments') are comprised of three Annual Improvements amendments (from the IASB's Annual Improvements to IFRS® Standards 2018–2020) and three narrow-scope amendments.
65Although the Amendments were published by the IASB before the end of the Implementation Period, the EU's process for adoption of these amendments had not been completed by that date. As a result, they were not incorporated into Domestic UK law as UK-adopted international accounting standards at the end of the Implementation Period on 31 December 2020.
66The IASB issues amendments to international accounting standards as part of its continuous effort to maintain and improve IFRS Standards and to support consistent application. Narrow-scope amendments address concerns about a specific aspect of a standard without causing major or significant changes in practice.
Annual Improvements to IFRS® Standards 2018–2020
67The IASB published the amendments “Annual Improvements to IFRS® Standards 2018-2020” (Annual Improvements) in May 2020. The Annual Improvements comprise of three amendments:
- Amendment to IFRS 1 First-time Adoption of International Financial Reporting Standards—“Subsidiary as a First-time Adopter” (Subsidiary as a First-time Adopter).
- Amendment to IFRS 9 Financial Instruments—“Fees in the ‘10 per cent' Test for Derecognition of Financial Liabilities” (Fees in the ‘10 per cent' Test).
- Amendment to IAS 41 Agriculture—“Taxation in Fair Value Measurements" (Taxation in Fair Value Measurements).
68Annual Improvements are amendments that are sufficiently minor or narrow in scope and are bundled together in a single document (even though the amendments are unrelated). These amendments are limited to changes that clarify the wording in the standards, or correct relatively minor unintended consequences, oversights or conflicts between existing requirements.
69The amendment “Subsidiary as a First-time Adopter” was published to permit subsidiary entities that apply the exemption in paragraph D16(a) of IFRS 1 to measure cumulative translation differences for all foreign operations at the carrying amount that would be included in the parent's consolidated financial statements, based on the parent's date of transition to IFRS standards.
70The amendment "Fees in the '10 per cent' test” was published to clarify which fees an entity includes when it applies the '10 per cent' test in paragraph B3.3.6 of IFRS 9 in assessing whether to derecognise a financial liability. The borrower includes only fees paid or received between the borrower and the lender, including fees paid or received by either the entity or the lender on the other's behalf.
71The amendment “Taxation in Fair Value Measurements” removes the requirement in paragraph 22 of IAS 41 to exclude cash flows for taxation when measuring the fair value of a biological asset using a present value technique. This is to ensure consistency with the requirements in IFRS 13 “Fair Value Measurement".
Onerous Contracts – Cost of Fulfilling a Contract (Amendments to IAS 37)
72The IASB published the amendments “Onerous Contracts—Cost of Fulfilling a Contract (Amendments to IAS 37)” (Onerous Contracts) in May 2020.
73The Onerous Contracts amendments specify that the 'cost of fulfilling' a contract comprises the 'costs that relate directly to the contract'. These costs can either be incremental costs of fulfilling that contract or an allocation of other costs that relate directly to fulfilling contracts.
Property, Plant and Equipment: Proceeds before Intended Use (Amendments to IAS 16)
74The IASB published the amendments “Property, Plant and Equipment: Proceeds before Intended Use (Amendments to IAS 16)” (Proceeds before Intended Use) in May 2020.
75The Proceeds before Intended Use amendments prohibit an entity from deducting from the cost of property, plant and equipment, any proceeds received from selling items produced while bringing that asset to the location and condition necessary for it to be capable of operating in the manner intended by management. Instead, an entity recognises the proceeds from selling such items and related cost, in profit or loss.
Updating a Reference to the Conceptual Framework (Amendments to IFRS 3)
76The IASB published the amendments “Reference to the Conceptual Framework (Amendments to IFRS 3)" (Reference to the Conceptual Framework) in May 2020.
77The Reference to the Conceptual Framework amendments was to update IFRS 3 to require an entity to refer instead to the “Conceptual Framework” published by the IASB in March 2018. The amendments also added an exception to its requirement for an entity to refer to the “Conceptual Framework” for some types of liabilities and contingent liabilities, an entity applying IFRS 3 should instead refer to IAS 37 “Provisions, Contingent Liabilities and Contingent Assets” or IFRIC 21 "Levies".
Assessment and Endorsement of the 2020 Narrow-scope Amendments
78The UKEB assessed the 2020 Narrow-scope Amendments against each of the criteria under the basis for adoption in Regulation 7 of the IAS Regulations. The UKEB also consulted a representative range of stakeholders interested in the quality and availability of accounts in accordance with Regulation 8 of the IAS Regulations.
79The Board were satisfied that the Amendments meet the criteria in Regulation 7. Their decision, therefore, was to adopt the 2020 Narrow-scope Amendments on 12 April 2022.
80Application of the Amendments to UK-adopted international accounting standards is mandatory for financial years beginning on or after 1 January 2022, and application to financial years beginning before 1 January 2022 is permitted.
81The 2020 Amendments are not likely to lead to a significant change in accounting practice and do not meet the criteria for a post-implementation review under Regulation 11 in SI 2019/685.
82Further information, including the UKEB's Endorsement Criteria Assessment, Feedback Statement and Adoption Statement, is available on the UKEB's website here.
Narrow-scope Amendments 2021: adopted on 30 November 2022 and published on 2 December 2022
83The 2021 Amendments are narrow-scope amendments to international accounting standards that were issued by the IASB and exposed separately for public comment as the IASB considered they merited separate consultation and outreach.
84The UKEB was not able to directly influence the 2021 Amendments as they were developed before the creation of the UKEB. The 2021 Amendments were finalised and published by the IASB after EU exit and were subject to public consultation. The UKEB Secretariat's research indicated that comments from UK stakeholders were submitted directly to the IASB and/or to the European Financial Reporting Advisory Group (EFRAG) and were considered by the IASB when finalising those amendments.
85The IASB issues amendments to international accounting standards as part of its continuous effort to maintain and improve IFRS Standards and to support consistent application. Narrow-scope amendments address concerns about a specific aspect of a standard without causing major or significant changes in practice.
Disclosure of Accounting Policies (Amendments to IAS 1 and IFRS Practice Statement 2)
86The Disclosure of Accounting Policies (Amendments to IAS 1 Disclosure of Accounting Policies and IFRS Practice Statement 2 Making Materiality Judgements) amendments were published by the IASB on 12 February 2021.
87The amendments require companies to disclose their material accounting policy information rather than their significant accounting policies; and indicate that accounting policy information is material if, when considered together with other information included in an entity's financial statements, it can reasonably be expected to influence the decisions of primary users about the entity.
88To support this amendment the IASB also amended IFRS Practice Statement 2 Making Materiality Judgements (Materiality Practice Statement) to explain and demonstrate the application of the ‘four-step materiality process' to accounting policy disclosures.
Definition of Accounting Estimates (Amendments to IAS 8)
89The Definition of Accounting Estimates (Amendments to IAS 8) amendments were published by the IASB on 12 February 2021.
90The amendments introduce a definition of 'accounting estimates' which is anchored in the concept of 'measurement uncertainty' in the IASB's Conceptual Framework; and, include other amendments to IAS 8 to help entities distinguish changes in accounting policies from changes in accounting estimates.
Deferred Taxes related to Assets and Liabilities arising from a Single Transaction (Amendments to IAS 12)
91The Deferred Taxes related to Assets and Liabilities arising from a Single Transaction (Amendments to IAS 12) amendments were published by the IASB on 7 May 2021.
92The amendments narrow the scope of the initial recognition exemption so it does not apply to transactions that, on initial recognition, give rise to equal and offsetting amounts of taxable and deductible temporary differences. These amendments result in entities recognising deferred taxes by applying the general requirements in IAS 12.
Assessment and Endorsement of the 2021 Narrow-scope Amendments
93The UKEB assessed the 2021 Narrow-scope Amendments against each of the criteria under the basis for adoption in Regulation 7 of the IAS Regulations. The UKEB also consulted a representative range of stakeholders interested in the quality and availability of accounts in accordance with Regulation 8 of the IAS Regulations.
94The Board were satisfied that the Amendments meet the criteria in Regulation 7. Their decision, therefore, was to adopt the 2021 Narrow-scope Amendments on 30 November 2022.
95Application of the three amendments to UK-adopted international accounting standards is mandatory for financial years beginning on or after 1 January 2023, and application to financial years beginning before 1 January 2023 is permitted.
96The 2021 Amendments are not likely to lead to a significant change in accounting practice and do not meet the criteria for a post-implementation review under Regulation 11 in SI 2019/685.
97Further information, including the UKEB's Endorsement Criteria Assessment, Feedback Statement and Adoption Statement, is available on the UKEB's website here.
Current Active Projects – adoption decision likely in 2023/24
IAS 1 Narrow-scope Amendments 2020 and 2022 (Effective date: 1 January 2024)
The 2020 Amendments: Classification of Liabilities as Current or Non-Current were published, by the IASB, in January 2020. The Amendments specify an entity's right to defer settlement of a liability and clarify classification issues.
The 2022 Amendments: Non-current Liabilities with Covenants were published, by the IASB, on 31 October 2022. The Amendments aim to improve the information companies provide about long-term debt with covenants.
The UKEB published a Draft Endorsement Criteria Assessment on 9 March 2023. The public consultation closes on 8 June 2023.
IFRS 16 Amendments (Effective date: 1 January 2024)
Lease Liability in a Sale and Leaseback – Amendments to IFRS 16, was published, by the IASB, on 22 September 2022. The Amendments add subsequent measurement requirements for sale and leaseback transactions to improve the requirements for such transactions.
The UKEB published a Draft Endorsement Criteria Assessment on 5 January 2023. The public consultation closed on 5 April 2023.
UKEB Technical Work on Sustainability Reporting
Our remit
98The Memorandum of Understanding between the UKEB, the Secretary of State for Business, Energy and Industrial Strategy (BEIS) and the Financial Reporting Council (FRC) requires the UKEB to consider any additional areas of work when requested to do so by the Secretary of State. During the year, the Secretary of State asked the UKEB to respond to the International Sustainability Standards Board (ISSB) on its Exposure Drafts (EDs) (IFRS S1 and S2) and to provide views from our perspective as the body responsible for endorsing and adopting international accounting standards in the UK.
99The UKEB's work focused on how the sustainability standards issued by the ISSB interact with accounting standards issued by the IASB. Specifically, whether their combined effect will result in sustainability disclosures provided by companies that are connected to the information presented in the financial statements and are decision-useful for investors.
Early stage influencing – Research
Connectivity Between Sustainability and Accounting Standards
100A research project on reporting climate-related matters in financial statements was approved for commencement by the UKEB at the February 2023 UKEB Board meeting.
101The evidence gathered will help the UKEB to provide evidence-based responses to both the IASB and the ISSB on relevant future projects.
UKEB Secretariat Papers on Potential Connectivity Issues
102As part of the UKEB's work to better understand the issues and key matters in relation to connectivity between the IFRS Sustainability Disclosure Standards and International Accounting Standards, the UKEB Secretariat has been developing papers for the Board's consideration.
Research Underway
103The UKEB is carrying out a review of existing reports and articles in order to understand issues already identified regarding the reporting of climate-related matters in financial statements. A report of the key findings will be published in due course.
104The UKEB is also analysing a sample of FTSE 350 annual reports to compare TCFD3 and SECR4 narrative disclosures, in the front half of the reports, to the financial effects reported in the financial statements, based on IFRS Accounting Standards, and to consider whether any disconnects identified would be addressed by the adoption of IFRS S1 and IFRS S2.
Influencing IFRS Sustainability Disclosure Standards development
ISSB Exposure Drafts IFRS S1 and IFRS S2
105In March 2022, the International Sustainability Standards Board (ISSB) issued its first two EDs, [draft] IFRS S1 General Requirements for Disclosure of Sustainability-related Financial Information and [draft] IFRS S2 Climate-related Disclosures. The standards aim to serve as a comprehensive global baseline of sustainability disclosures for the capital markets.
106IFRS S1 sets out proposed sustainability-related disclosure requirements to enable investors to understand the risks and opportunities while IFRS S2 focuses on identification and measurement of climate related risks.
107The Project Initiation Plan was approved by the UKEB Board at their April 2022 public meeting. The plan focussed on consideration of the overlap between IFRS Accounting Standards and IFRS Sustainability Disclosure Standards and included plans for discussion with relevant stakeholders.
Outreach
108More than 200 stakeholders representing over 90 organisations were engaged, including via a virtual cross-government outreach event.
Final Comment Letter
109The UKEB published its Final Comment Letter on 27 July 2022. Due to the close association between the two EDs, the UKEB considered them as part of a single project and published a single comment letter addressing both EDs.
110The letter welcomes the EDs and strongly supports a general requirements framework for sustainability-related information, and the alignment of the climate ED with the Task Force on Climate-related Financial Disclosures (TCFD) recommendations.
111The UKEB acknowledges the many areas of alignment with the IASB's Conceptual Framework for Financial Reporting, IAS 1 Presentation of Financial Statements and IAS 8 Accounting Policies, Changes in Accounting Estimates and Errors, to improve connectivity with financial reports and help stakeholders to better understand how the information presented is underpinned by financial reporting. The letter also makes several recommendations to enhance the proposals.
Working with Other International Organisations
Working with ASAF
112The Accounting Standards Advisory Forum (ASAF) is an advisory body of the IASB. ASAF enables the IASB to obtain a broad range of national and regional input on major technical issues related to the IASB's standard setting activities.
113Its membership is limited to 12 members, plus the Chair. The membership represents a balance of national standard-setters and regional standard-setting bodies from the major economic regions of the world. The UKEB was appointed, as one of the three members from Europe, in June 2021.
114Pauline Wallace, Chair of the UKEB, represents the UKEB at ASAF. Seema Jamil-O'Neill, Technical Director of the UK Endorsement Board, is her named alternate.
115Although ASAF usually meets four times a year, it has met six times in the 2022/23 financial year (April 2022, July 2022, September 2022, December 2022, February 2023 and March 2023). The UKEB was represented at all meetings.
116The UKEB Chair and Technical Director presented the research paper 'Subsequent Measurement of Goodwill: a Hybrid Model' at the September 2022 ASAF meeting for consideration of the IASB and the other members of that group.
Working with IFASS
117The International Forum of Accounting Standard Setters (IFASS) is a group of national accounting standard setters from around the world. The forum provides a place for national accounting standards setters, and others interested in financial reporting, to discuss current issues in financial reporting.
118The group usually meets twice a year. This financial year it met in September 2022 and January 2023. The meetings were attended by the UKEB Chair and Technical Director.
119The IASB participates in these meetings on an equal footing with national standard setters. In addition, the IASB uses IFASS to conduct outreach, especially for queries lodged with the IFRS Interpretations Committee, to gather information on the practical relevance, prevalence, and current practice of potential agenda item requests.
Working with other National Standard-setters
120The UKEB engages with other national standard-setters (‘NSS') on various projects in order to learn from their work and to develop an understanding of issues and concerns in other jurisdictions and proposed approaches to their escalation or resolution.
NSS Sustainability Forum
121In February 2023, the UKEB set up a NSS Sustainability Forum to develop an understanding of connectivity issues between IFRS Accounting Standards and IFRS Sustainability Disclosure Standards, consider possible solutions that would address the stakeholder needs for connectivity between information presented in companies' sustainability reports and financial reports, and share them with ISSB and IASB as they develop high-quality international standards.
122Its membership is limited to national standard-setters, with a particular interest in, or responsibility for, the overlap between IFRS Accounting Standards and IFRS Sustainability Disclosure Standards.
Organisational Structure and Our People
UKEB Board
124The UKEB Board, is comprised of the Chair and 12 members. Collectively they bring together a range of relevant backgrounds and expertise.
125The interim Chair, appointed by the Secretary of State in September 2020 to lead the set-up of UKEB and appointment of the inaugural Board, was announced as UKEB's first permanent Chair as of 11 September 2022. The appointment followed a fair and open process, led by BEIS, and is for a three year period.
Our Structure
UKEB Advisory Groups
126During the year, the UKEB set up four standing advisory groups: Academic, Accounting Firms and Institutes, Investor, and Preparer. Ad hoc groups will be established for specific projects. Currently, there is an ad hoc group for Rate-regulated Activities.
127These groups are not decision-making bodies in their own right. They act as advisory, consultative groups which provide specialist knowledge and information as input into the Board's technical decision-making.
128The advisory groups are chaired by UKEB Board Members and members are appointed in their personal capacities.
129The members of the advisory groups are senior, high calibre individuals. Their appointment illustrates the importance of the UKEB to UK stakeholders and that the UKEB is engaging with the full range of UK stakeholders. Biographies for the members of each group are available on the UKEB website.
Academic Advisory Group (AAG)
130Members of the AAG include academics with expertise and experience in the use of accounting by individuals, organisations, or government; academics with an interest in accounting policy, governance and environmental issues, quantitative analysis, wider corporate reporting, and economics.
131The group currently has 10 members, including the Chair. Its inaugural meeting was held in September 2022.
Accounting Firms and Institutes Advisory Group (AFIAG)
132Members of the AFIAG have a close interest in the use and implementation of international accounting standards. They include individuals from large and medium-sized professional services firms in the UK, and from UK Accounting Institutes.
133The group currently has 12 members, including the Chair. Its inaugural meeting was held in July 2022 and two further meetings were held in November 2022 and March 2023.
Investor Advisory Group (IAG)
134Members of the IAG have practical experience in analysing and using financial reporting information. Members can include “buy-side” fund managers, institutional investors, and retail investors, as well as participants from “sell-side” investment banks and ratings agencies.
135The group currently has 8 members, including the Chair. Its inaugural meeting was held in October 2022 and a further meeting was held in February 2023.
Preparer Advisory Group (PAG)
136Members of the PAG have considerable practical experience of financial reporting, with knowledge and understanding of the financial reporting issues faced by IFRS reporters and include individuals from large accounting firms and publicly listed UK companies.
137The group currently has 11 members, including the Chair. Its inaugural meeting was held in July 2022 and two further meetings were held in October 2022 and March 2023.
Rate-regulated Activities Technical Advisory Group (RRA TAG)
138Members of the ad hoc RRA TAG include preparers working in rate-regulated industries, users of accounts with a particular interest in accounts of entities that undertake rate-regulated activities; and, individuals from professional services firms in the UK that provide services to entities with rate-regulated activities.
139The group currently has 10 members, including the Chair. Its inaugural meeting was held in March 2023.
UKEB Working Groups
140The UKEB has also set up working groups to access specialist technical knowledge and expertise on certain projects. These solely advise the Secretariat and the membership of these groups may change as the focus of the group's work evolves.
141Currently, the UKEB has working groups for Financial Instruments and Sustainability. The groups are chaired by senior members of the Secretariat.
Governance and Transparency
Regulatory Strategy and Workplan
142The UKEB consults annually on its Regulatory Strategy and technical work plan for the year ahead. The UKEB's draft 2023/24 Regulatory Strategy, was open for consultation from 16 December 2022 to 27 January 2023. The final strategy and workplan was published on 27 March 2023.
143The UKEB's expected technical workplan, incorporated within the Regulatory Strategy, includes a variety of upcoming adoption, influencing and research projects. The UKEB will focus on the areas of the IASB agenda that are of highest priority to UK stakeholders. Additionally, given the need to align our work programme with that of the IASB, some technical projects listed on 2022/23 workplan did not commence during the year or were rolled forward to accommodate delays in the IASB's workplan.
Public Board Meetings
144The Board's technical decision-making is carried out in a fully transparent manner via public Board meetings. Members of the public can choose to observe the discussions live or watch an online recording.
145The meetings are attended by Official Observers from the Department for Business and Trade ('DBT'), Bank of England, FRC, HMRC and FCA, all of whom have speaking rights.
146UKEB has a Board Meetings Transparency Policy which sets out the key principles the Board considers when deciding which matters it discusses in public Board meetings and which matters are discussed in private.
Published Board Papers
147Meeting agenda and Board papers on technical matters are published on the UKEB website in advance and a summary of decisions and minutes are published afterwards.
148The agenda and summary minutes of the UKEB's private Board meetings are also published on the UKEB website.
Footnotes
-
Following the changes announced on 7 February 2023, oversight of UKEB's discharge of its statutory functions has moved from BEIS to the Department for Business and Trade. ↩
-
The International Accounting Standards and European Public Limited Liability Company (Amendment etc.) (EU Exit) Regulations 2019 ↩
-
Taskforce for climate-related financial disclosures (TCFD) are required to be provided by all large entities within their Strategic Report ↩
-
Streamlined Energy and Carbon Reporting (SECR) disclosures are required by all large entities in either their Directors' Report (for companies) or in an Energy and Carbon Report (for LLPs) ↩