8 IASB General Update
25 June 2026 Agenda Paper 8 OFFICIAL - PUBLIC
Executive Summary
| Project Type |
|---|
| Various |
| Project Scope |
|---|
| Various |
| Purpose of the paper |
|---|
| This paper provides the Board with an update on projects the Secretariat is currently monitoring. As agreed with the Board, the Secretariat monitors projects being undertaken by the IASB. This is to inform the Board about the progress and decisions being made by the IASB on active projects. Discussion by the Board may also help inform interactions with international standard setter meetings, including the IASB's Accounting Standards Advisory Forum (ASAF), of which the UKEB is a member. |
| Summary of the Issue |
|---|
| Topics addressed in this paper include topics discussed by the IASB at its May 2026 meeting and topics to be discussed at the July 2026 ASAF meeting. |
Topics for discussion
- Financial Instruments with Characteristics of Equity
- Risk Mitigation Accounting
- Intangible Assets
- Presentation of Taxes or Other Charges that Are Not Tax Expense or Tax Income Applying IAS 12 Income Taxes (IFRS 18)
- Equity Method
- Business Combinations—Disclosure, Goodwill and Impairment
Topics for noting
- Statement of Cash Flows and Related Matters
- List of IASB projects
Decisions for the Board
Financial Instruments with Characteristics of Equity (Appendix A)
1Do Board Members have any feedback in relation to the brand new presentation proposals included in the ASAF paper?
2Do Board Members agree that the key message given to ASAF on the presentation proposals should be tentative support, subject to the need to consult stakeholders on the proposals?
3Do Board Members agree that the key message given to ASAF on these measurement proposals should be that they be dropped from the FICE project, and the existing cross reference to IFRS 9 retained?
Risk Mitigation Accounting (Appendix B)
1Do Board Members have any feedback in relation to the UKEB's key messages for the July 2026 ASAF meeting?
Intangible Assets (Appendix C)
1Considering the IASB's findings on user information needs and the UKEB's research findings so far, what is the Board's advice on the key messages to the IASB on the appropriate direction and prioritisation of their project?
Presentation of Taxes or Other Charges that Are Not Tax Expense or Tax Income Applying IAS 12 Income Taxes (IFRS 18) (Appendix D)
1Do Board Members have any comments on the IASB's decision to explore amending IFRS 18 to require or allow an entity to classify in the income taxes category of the statement of profit or loss non-income tax charges that meet the definition of “covered taxes" under the OECD's Pillar Two model rules?
Equity Method (Appendix E)
1Do Board Members have any views on the IASB's (tentative) decision at its May 2026 meeting on introducing an accounting policy choice for recognition of gains or losses on transactions with associates?
2Do Board Members agree that the proposed disclosures would provide useful information to users and mitigate the potential negative effect on comparability an accounting policy choice might have?
Business Combinations—Disclosures, Goodwill and Impairment (Appendix F)
1Do Board Members agree with the Secretariat that, on balance, the IASB's proposals will not sufficiently improve the information that users receive?
2Do Board Members agree that the IASB should proceed only with the changes proposed in the ED to simplify the impairment test in IAS 36?
Topics for noting
Do Board members have any questions or comments on the topics for noting?
| Recommendation |
|---|
| N/A |
Appendices
- Appendix A: Financial Instruments with Characteristics of Equity
- Appendix B: Risk Mitigation Accounting
- Appendix C: Intangible Assets
- Appendix D: Presentation of Taxes or Other Charges that Are Not Tax Expense or Tax Income Applying IAS 12 Income Taxes (IFRS 18)
- Appendix E: Equity Method
- Appendix F: Business Combinations—Disclosures, Goodwill and Impairment
- Appendix G: Statement of Cash Flows and Related Matters
- Appendix H: List of IASB projects
Appendix A: Financial Instruments with Characteristics of Equity
Executive Summary
| Research / Pipeline | Discussion Paper | Redeliberation | Exposure Draft | Redeliberation | Final Standard | Post Implementation Review | |
|---|---|---|---|---|---|---|---|
| IASB | |||||||
| UKEB | Research / Influencing | Research / Monitoring | Influencing | Influencing | Monitoring | Endorsement | Influencing |
UKEB Post Implementation Review
UKEB project page
UKEB Final Comment Letter on Exposure Draft (published 3 April 2024)
IASB Next Milestone: Final Amendments 2027
Purpose
A1The purpose of this paper is to ask for Board Members' views on the key messages the UKEB plans to raise at the July 2026 Accounting Standards Advisory Forum (ASAF) meeting. At the meeting IASB staff will discuss feedback to the proposals in the Exposure Draft Financial Instruments with Characteristics of Equity (ED) in respect of obligations to purchase an entity's own equity instruments, and possible next steps.
Background
A2In November 2023, the IASB issued the ED, which sought to clarify the classification requirements and principles of IAS 32 Financial Instruments: Presentation. The ED also included presentation and disclosure proposals in response to calls from users for “better information about the characteristics of financial liabilities and equity instruments that are not captured by classification alone, and about the amounts attributable to ordinary shareholders of an entity”1. The UKEB issued its Final Comment Letter (FCL) in response to the ED in April 2024.
Obligations to purchase an entity's own equity instruments
Current requirements
Paragraph 23 of IAS 32 sets out requirements for contracts containing an obligation for an entity to purchase its own equity instruments. Examples of such contracts include a forward contract to purchase the entity's own shares and a written put option that gives the holder the right to require the entity to purchase its own shares.
IAS 32 requires an entity to recognise a financial liability at the present value of the redemption amount. This amount is removed from equity and included in financial liabilities. The IASB proposes to clarify which component of equity this amount is removed from and how to measure the financial liability at the present value of the redemption amount.
Exposure Draft Proposals
The ED proposed clarifying:
- that the requirements in IAS 32 for contracts containing an obligation for an entity to purchase its own equity instruments also apply to contracts that will be settled by delivering a variable number of another class of the entity's own equity instruments;
- the treatment on initial recognition of the obligation to redeem own equity instruments where the entity does not yet have access to the rights and returns associated with ownership of those equity instruments;
- the approach for initial and subsequent measurement of the financial liability—measure the liability at the present value of the redemption amount and ignore the probability and estimated timing of the counterparty exercising that redemption right;
- that any gains or losses on remeasurement of the financial liability are recognised in profit or loss;
- the treatment on expiry of contracts containing an obligation to purchase own equity without delivery; and
- the requirement for gross presentation of written put options and forward purchase contracts on an entity's own equity instruments that are gross physically settled.
UKEB comment letter
The UKEB final comment letter (FCL) supported all these proposals apart from those relating to the initial and subsequent measurement of the financial liability.
The FCL raised concerns at introducing measurement requirements into a presentation standard, and highlighted concerns that the proposals could lead to a change in measurement for some common instruments and could lead to less relevant information for users. The FCL recommended retaining the existing cross reference to IFRS 9 in paragraph 23 of IAS 32, and to address any measurement concerns within the IASB's *Amortised Cost Measurement
- project.
July 2026 ASAF meeting
Obligations to purchase own equity instruments
A5At the July 2026 ASAF meeting, IASB staff will share details of the feedback received on the ED proposals relating to obligations to purchase own equity instruments and will seek members views on possible proposals to address this feedback2. The IASB has not held any detailed discussions on this topic, consequently the UKEB Secretariat have not been able to seek feedback from UKEB Advisory Groups prior to bringing this topic to the Board.
A6The UKEB Secretariat's preliminary analysis is set out below. This is primarily informed by outreach conducted on this topic in developing the UKEB response to the ED. In addition, the UKEB Financial Instruments Working Group (FIWG) will be asked for feedback prior to the ASAF meeting.
A7ASAF members will be asked the following questions:
| Questions for ASAF members |
|---|
| Presentation |
| 1. Would the alternative presentation approach address stakeholder concerns about the presentation of these obligations in the statement of financial position and provide useful information to users of financial statements? |
| 2. Would additional presentation in the attribution section in the statement of profit or loss address perceived double-counting concerns in the income statement and provide useful information to users of financial statements? |
| Measurement |
| 3. How do you suggest the IASB responds to the challenges identified in applying the measurement approach in the ED? |
UKEB Secretariat preliminary analysis
Presentation proposals
A8The IASB analysis in the ASAF paper identifies a number of areas of feedback relating to the ED presentation proposals. This feedback relates primarily to non-controlling interest (NCI) puts, and includes:
a) concerns about the recognition of an initial debit entry in equity and the recognition of gains and losses on the financial liability;
b) concerns about double counting, with recognition of a debit in equity and a financial liability, and the impact on banks' regulatory capital ratios; and
c) the counterintuitive effect in profit and loss for distributions to NCI.
A9The ASAF paper dismisses a number of alternative proposals suggested in feedback that would have altered existing IAS 32 requirements. Proposals included permitting net presentation of the liability and equity components of the NCI put, or recognising remeasurement gains and losses in equity. It notes these would be a fundamental change to IAS 32, and beyond the scope of the FICE project.
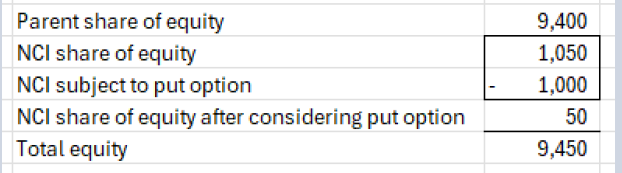
A10The ASAF paper proposes a brand new alternative presentation approach of presenting the debit in equity as a deduction to NCI. As far as UKEB Secretariat is aware the IASB has not discussed this new approach. It is recognised and presented as a separate component of NCI, but does not lead to derecognition of the NCI. Slide 25 of the IASB's ASAF presentation pack includes an illustrative example of this alternative:
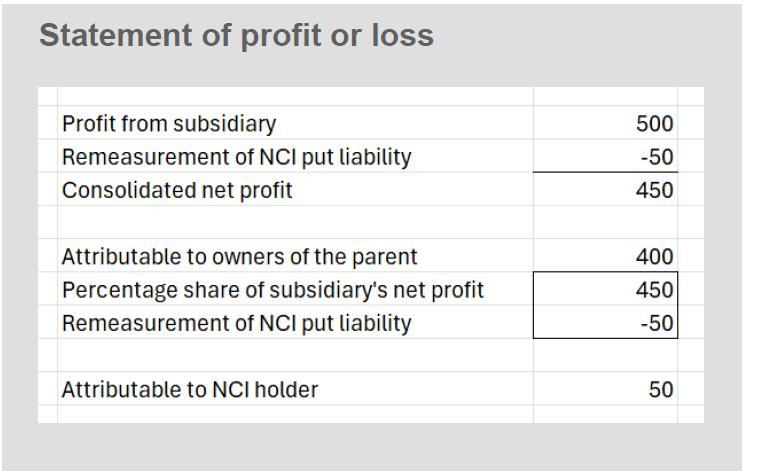
A11The ASAF paper also notes that the staff are considering whether to extend the alternative presentation approach to the attribution section of the statement of profit or loss. Slide 28 includes an illustrative example of this possible approach:
A12The UKEB Secretariat's preliminary assessment of these alternative presentation approaches is informed by the UKEB FCL position, which supported the ED presentation proposals in relation to obligations to purchase own equity instruments. We did not identify any significant feedback from UK stakeholders raising any of the concerns highlighted in the IASB's paper.
A13However, as the UKEB supported the ED presentation proposals, our tentative view is to support these alternative presentation proposals, to the extent that they allow the IASB to finalise the presentation proposals in this area, and as long as they do not have any unintended consequences. Our initial review has not identified any concerns, but we would need to test this with stakeholders.
UKEB Key messages: Presentation (ASAF questions one and two)
A14The UKEB supported the ED presentation proposals on this topic. We support the IASB's efforts to finalise these aspects of the amendments. We can see some merits in the proposed alternative presentation.
A15We have not had the opportunity to test the alternative presentation proposals with stakeholders. Our preliminary review has not identified any problems, but we would want to test these proposals in more detail with stakeholders.
| Question for the Board |
|---|
| 1. Do Board Members have any feedback in relation to the brand new presentation proposals included in the ASAF paper? |
Measurement Proposals
A16The IASB ASAF paper summarises a number of common themes of feedback relating to measurement proposals for obligations to purchase own equity in the ED. These include:
a) concerns at referencing the earliest possible settlement date when a later settlement date would lead to a larger settlement amount;
b) mixed views, with some supporting an IFRS 9 approach and others supporting the ED approach;
c) concerns the ED introduces a new measurement basis into IAS 32 which is inconsistent with IFRS 9; and
d) those who supported the ED approach, but sought further clarification on various aspects, such as discount rates, and EBITDA3 linked settlement amounts.
A17The ASAF paper says the IASB staff are exploring whether they could address some concerns by requiring measurement at an amount that is 'not less than the amount payable on demand, discounted from the date the amount could be required to be paid'. They consider this could permit measurement at a higher amount if there are multiple fixed settlement amounts at different dates.
A18The paper also indicates that measurement of variable amounts, for example those linked to EBITDA, would be based on circumstances at the reporting date.
A19However, the paper also notes that while these simplifications may address some of the concerns raised, it also highlights other challenges or complexities such as:
a) the discount rate to be used;
b) whether historic or forecast EBITDA should be used; and
c) the interaction of the 'not less than' instruction with a cap on a variable amount where that cap is not expected to be met.
A20Our preliminary assessment of these possible refinements to the ED proposals are that while they potentially seek to address one of the specific examples raised in the UKEB FCL, the refinements leave a number of questions unanswered.
A21The paper refers to the ED proposals resulting in a measurement that is already 'an IFRS 9 measurement'. However, the ED proposed deleting the cross reference to IFRS 9 in paragraph 23 of IAS 32.
A22It is not clear that the ASAF paper fully addresses the main concern raised in the UKEB FCL that the ED proposals introduce measurement requirements into IAS 32. The UKEB FCL noted that this 'goes beyond the objective of IAS 32'. It also highlighted:
a) concerns that the proposals would require significant additional application guidance to be clear and effective; and
b) the need to introduce scope exclusions from IFRS 9 for instruments within the scope of paragraph 23 of IAS 32.
A23The other challenges and complexities set out in page 33 of the ASAF paper illustrates some of the issues that would need to be addressed if these measurement refinements were to be introduced into IAS 32.
A24Our tentative view is that the proposed possible refinements do not address the main concerns raised in the FCL. The recommended message for ASAF thus remains that the proposed changes to the measurement provisions of paragraph 23 should be dropped and the cross reference to IFRS 9 retained. This tentative view is subject to wider stakeholder consultation. This was, however, a topic on which a number of UK stakeholders expressed concern during the original ED consultation.
UKEB Key messages: Measurement (ASAF question three)
A25We welcome the IASB's approach to seeking to provide solutions in relation to the feedback to the measurement proposals in the ED. The challenges and complexities identified in the paper indicate it would be very difficult to finalise these proposals on a timely basis.
A26We remain concerned that the proposals will cause confusion for stakeholders, and result in less useful information for users. We recommend the IASB drop the measurement proposals for these contracts, and retain the cross-reference to IFRS 9, enabling timely finalisation of the other aspects of this topic.
| Question for the Board |
|---|
| 3. Do Board Members agree that the key message given to ASAF on these measurement proposals should be that they be dropped from the FICE project, and the existing cross reference to IFRS 9 retained? |
Next steps
A27The IASB will continue to redeliberate the ED proposals during 2026, with final amendments expected in 2027.
Appendix B: Risk Mitigation Accounting
Project Stage
| Research / Pipeline | Discussion Paper | Redeliberation | Exposure Draft | Redeliberation | Final Standard | Post Implementation Review | |
|---|---|---|---|---|---|---|---|
| IASB | |||||||
| UKEB | Research / Influencing | Research / Monitoring | Influencing | Influencing | Monitoring | Endorsement | Influencing |
UKEB Post Implementation Review
UKEB project page
UKEB Draft Comment Letter on Exposure Draft (comment deadline 21 October 2026)
IASB Exposure Draft comment and fieldwork deadline: 30 November 2026
Objective
B1The objectives of this paper are to:
a) update Board Members on the stakeholder outreach activities conducted subsequent to the UKEB May 2026 meeting; and
b) seek Board Members' views on the key messages the UKEB plans to raise in the Risk Mitigation Accounting (RMA) session at the July 2026 IASB's Accounting Standards Advisory Forum (ASAF) meeting.
Background
B2On 3 December 2025, the IASB published the Exposure Draft (ED) IASB/ED/2025/1 Risk Mitigation Accounting—Proposed amendments to IFRS 9 and IFRS 7, with the comment period originally ending on 31 July 2026 and subsequently extended to 30 November 2026. The IASB is also conducting fieldwork on the proposals with final results by 30 November 2026.
B3Following the IASB's extension of their comment deadline, the UKEB has extended its public consultation deadline on its Draft Comment Letter (DCL) to 21 October 2026.
Stakeholder outreach activities
B4As agreed by the Board, the Secretariat is undertaking targeted stakeholder outreach activities during the UKEB's public consultation period to gather stakeholder feedback on the IASB's ED and the UKEB's DCL.
B5Subsequent to the UKEB May 2026 meeting, a second UKEB Financial Instruments Working Group (FIWG) RMA roundtable4 was held on 3 June 2026 with over 35 attendees. FIWG members as well as other interested stakeholders from a range of backgrounds (such as risk management and treasury) attended the roundtable and shared interim feedback on the UKEB's DCL and the IASB's ED. Also in attendance were some UKEB Members, an IASB Member and the relevant IASB project team.
B6In addition to the roundtable above, the Secretariat has also engaged separately with a hedge accounting software provider, a medium-sized building society, and an industry body for UK insurers. They are currently assessing the proposals in the IASB's ED.
B7The Secretariat will continue to engage with UK stakeholders during the DCL consultation period.
July 2026 ASAF meeting
IASB staff's objectives
B8The purpose of the July 2026 ASAF meeting is to:
a) Provide ASAF members with an update on the IASB's outreach activities to date and on common feedback themes.
b) Seek information from ASAF members on:
i. current levels of engagement on the Exposure Draft and intended fieldwork participation in their jurisdictions or regions, and identify areas where further guidance or clarification is needed;
ii. potential areas for education and outreach activities that the IASB should prioritise during the remaining consultation period; and iii. companies in their jurisdictions or regions that still apply IAS 39 *Financial Instruments: Recognition and Measurement
- hedge accounting requirements.
B9In particular, ASAF members will be asked the following questions:
| Questions for ASAF members |
|---|
| 1. What is the current level of engagement on the Exposure Draft in your jurisdiction or region, including intended participation in the fieldwork? |
| 2. In your view, are there any priority areas for education and outreach activities on which the IASB should focus on during the remaining consultation period? |
| 3. Apart from banks and insurance companies, are you aware of any companies in your jurisdiction or region that still apply IAS 39 hedge accounting requirements? Do you have any suggestions on how the IASB could reach out to them regarding the proposed withdrawal of IAS 39? |
UKEB's key messages
B10The Secretariat's suggested key messages to convey at the ASAF meeting are:
a) There is active engagement by some large UK banks and insurers on the ED. However, we are only aware of large UK banks participating in fieldwork at this stage.
b) The following areas of the proposals would benefit most from further clarification and education:
i. The intended application of RMA when the designated derivatives used exceed the net repricing risk exposure in certain repricing time bands.
ii. The intended application of RMA when a present value per basis point measure or non-linear derivatives are used for risk management purposes.
iii. The construction of benchmark derivatives when there is optionality in either the underlying portfolios or the designated derivatives, and on transition to RMA.
iv. The identification and definition of unexpected changes. Clarity over the interaction of such changes, especially temporary changes, with the proposed requirements on adjustments to benchmark derivatives and the risk mitigation adjustment excess would also be needed.
v. The assessment and measurement of risk mitigation adjustment excess.
c) Early stakeholder feedback indicates that most building societies reporting under UK-adopted IFRS apply the hedge accounting requirements in IAS 39. We have been conducting further outreach via continued engagement with the relevant industry bodies, the accounting firms, a hedge accounting software provider and one-to-one meetings with some building societies.
d) Based on limited desktop research conducted thus far, we are aware of only a small number of UK companies other than banks and building societies applying IAS 39 hedge accounting requirements. We plan to reach out to some of these companies.
e) The IASB should continue raising awareness on both the proposed new model and the proposed withdrawal of IAS 39 among entities that are not large banks or insurers.
| Question for the Board |
|---|
| 1. Do Board Members have any feedback in relation to the UKEB's key messages for the July 2026 ASAF meeting (see paragraph B10)? |
Next steps
B11The Secretariat will continue to engage with UK stakeholders during the DCL consultation period.
B12The Secretariat will present a technical paper based on updates from stakeholder feedback for discussion at the UKEB October 2026 meeting. A verbal update on any comment letters received will also be provided.
Footnotes

- v. The assessment and measurement of risk mitigation adjustment excess.
Question for the Board
- Do Board Members have any feedback in relation to the UKEB's key messages for the July 2026 ASAF meeting (see paragraph B10)?
Next steps
B11 The Secretariat will continue to engage with UK stakeholders during the DCL consultation period.
B12 The Secretariat will present a technical paper based on updates from stakeholder feedback for discussion at the UKEB October 2026 meeting. A verbal update on any comment letters received will also be provided.
Appendix C: Intangible Assets

Project Stage
| IASB | Research / Pipeline | Discussion Paper | Redeliberation | Exposure Draft | Redeliberation | Final Standard | Post Implementation Review |
|---|---|---|---|---|---|---|---|
| UKEB | Research / Influencing | Research / Monitoring | Influencing | Influencing | Monitoring | Endorsement | Influencing |
IASB Next Milestone: Decide Project Direction (H2 2026)
Objective
C1 This paper:
- summarises the IASB's research findings on users' information needs and the IASB's current thinking on the direction of its Intangible Assets project[^4]; and
- sets out the Secretariat's preliminary views on the direction of this project and seeks the Board's input in response to the IASB's request for advice, (to inform the July 6, 2026 ASAF meeting).
User feedback
C2 At its May 2026 meeting, the IASB discussed the information users seek about intangible assets, how they use it, where they currently obtain it, and the improvements they would like to see.
C3 The key findings from the IASB's research are as follows:
| Issue | Description |
|---|---|
| User information needs | Users mainly want to understand how intangible-related activities drive value creation. They focus on how these activities affect future cash flows, growth, margins and risk. |
| Users generally favour enhanced disclosure. Some concerns about recognition relate to use of judgement, auditability, earnings-management risk and comparability (e.g. if fair value is used for measuring internally generated intangible assets). | |
| Existing information included in financial statements in relation to intangibles only partly meet user needs. There is a consistent call for more disaggregated information, greater transparency on differences between spend on capex and opex (capitalisation versus expensing), improved comparability, and better linkage between financial statements and narrative reporting. In making these calls, investors are cognisant of practical constraints such as commercial sensitivity. | |
| A minority of users find current information sufficient. | |
| User use of financial information and responses to limitations | Investors typically use financial statements as a starting point for analysis and a sense-check (e.g. as a historical anchor or confirmation of assumptions about intangible-related inputs). Most users draw on multiple sources when analysing intangible activities. They supplement financial statements with narrative reporting (for example, management commentary or strategic reports), investor materials, industry data and expert insights. Users rely on qualitative insights and sector-specific metrics to assess growth, margins, cash-flow durability and risk. |
| In the absence of detailed information, past performance and management track record are often used as proxies for assessing how effectively intangible-related expenditure may translate into future returns. Where disclosures lack detail or comparability, users adjust reported figures, to reflect differences in accounting treatment (such as capitalised versus expensed amounts), or place greater emphasis on cash-based measures. | |
| Credit analysts focus on debt repayment and servicing capacity; express conservative preference for expensing, and do not 'give credit' to early-stage intangible spend. They requested enhanced disclosures (e.g. to obtain greater disaggregation/traceability, impairment sensitivity, valuation inputs and assumptions). More recognition could help unlock financing, although evidence in this respect is limited. |
C4 Annex 1 to this paper summarises the more specific challenges that users face when analysing information on intangibles, together with their corresponding suggestions for improvement.

IASB's current thinking on its intangibles project
C5 In May 2025, the IASB decided to progress its Intangible Assets project by grouping topics into workstreams. In May 2026, based on feedback from the user information needs workstream, the IASB expressed preliminary preferences on whether topics should remain on track or be reprioritised, with a focus on areas that could deliver the most useful information to users in a timely manner. The IASB plans to consider the views of its consultative groups when deciding on the project direction in Q4 2026
C6 The diagram below illustrates how the IASB intended to progress the various workstreams in May 2025. Following the May 2026 discussions, these priorities may change5. The Secretariat has highlighted in red the topics that may be prioritised based on Secretariat's interpretation of those discussions.
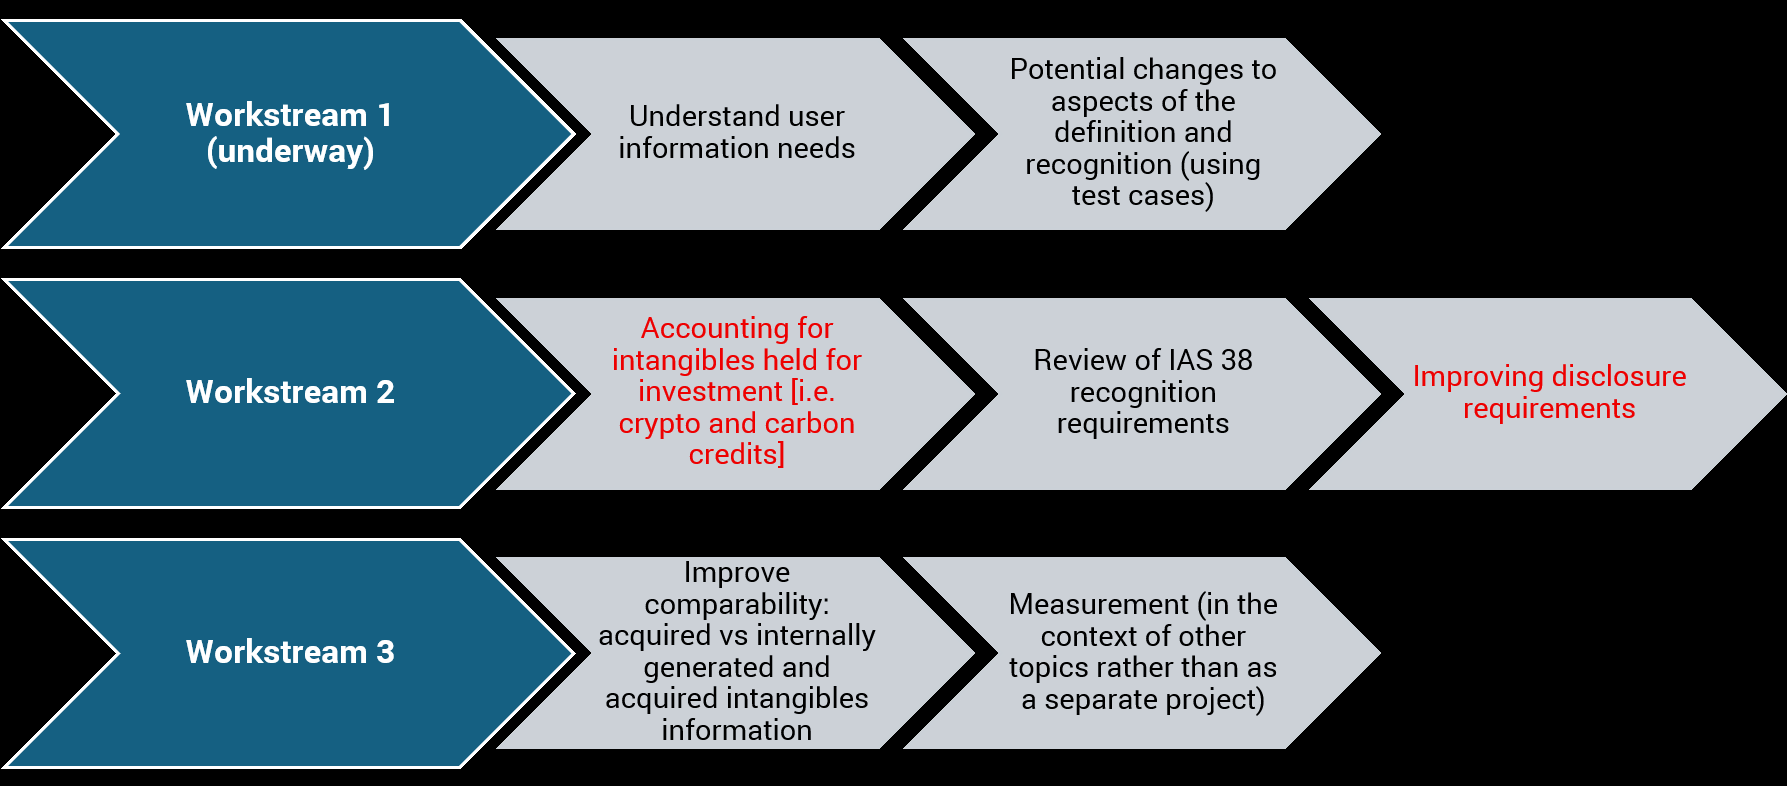
C7 The Board is asked for views on the direction and prioritisation of the IASB's Intangibles project, to help inform the UKEB input at the July 2026 ASAF discussion on this topic.
C8 The table on the next page summarises IASB members' preliminary views across the key workstreams (including any indications of potential reprioritisation) along with relevant indications from the UKEB's research.

| Topic | IASB preliminary views | Indications from UKEB research |
|---|---|---|
| 1 Foundational work | Seen as essential to provide evidence (user outreach, case studies) to inform later stages. No reprioritisation indicated | UKEB research conducted so far suggests that the prevalence of crypto assets and carbon credits is increasing. That research suggests that the requirements in IAS 38 may be insufficient or unsuitable for such assets as they differ from traditional intangible assets and, in some cases, are more akin to commodities. |
| 2(a) Intangibles held for investment6 | User feedback provided limited evidence on accounting for intangible assets held for investment. However, some IASB members consider crypto assets and carbon credits to be distinct from other intangible assets and sufficiently prevalent to warrant separate analysis. Accordingly, some members suggested addressing crypto assets and carbon credits in separate projects (outside the Intangibles project). | However, the research also shows limited support for fragmented, asset-specific solutions. Instead, stakeholders prefer a broad, principles-based approach, reflecting the business model, intended use or purpose of holding the asset. The research suggests that this could promote consistency across different types of intangibles, better support comparability of the resulting financial information, reduce complexity over time, and future-proof the requirements against emerging types of intangible assets. |
| 2(b) Review of IAS 38 recognition requirements | IASB's user feedback appears not to generally support recognition of internally generated intangible assets. | A comprehensive review of IAS 38 is supported; the need for clearer and more consistent principles remains essential. |
| Some IASB members continue to support a targeted 'fatal flaw' review | UKEB research and case study evidence so far indicate that disclosures cannot fully compensate for existing weaknesses in recognition and measurement. Without strengthening the current recognition |

| Topic | IASB preliminary views | Indications from UKEB research |
|---|---|---|
| of IAS 387, drawing on findings from the first workstream. | framework, e.g. by addressing core principles, additional disclosure requirements are unlikely to be able to reflect underlying economics and the entity's business model. Enhancing comparability and reducing complexity over time (a key user ask) is not feasible without clarity on those recognition principles. | |
| Other members questioned whether the scope of this review should be broader, to improve comparability across entities when applying recognition criteria, given concerns about inconsistency and lack of comparability in the application of existing requirements. | The IASB intends to consider the findings of UKEB research, which is based on testing case studies on research and development (R&D), training costs, carbon credits and data. These should highlight areas of tension and ambiguity in applying the existing requirements in IFRS and help the Board develop its recommendations on how best to reflect the underlying economics and business models and deliver the comparable information requested by investors. | |
| 2(c) Improving disclosures | User feedback tends to focus on enhanced disclosures to help them: | UKEB research shows strong demand from users for granular, decision-useful disclosures, suggesting that improving disclosures should be a priority. However, some stakeholders consider that without a robust underlying recognition and measurement framework, disclosure will at best provide disaggregated information about a particular financial year's worth of spend on intangibles (as defined by management). This is unlikely to address user need for consistent and comparable disclosures of spend on intangibles by for example, |
| 1. link spend-to-outcomes-especially separating 'maintenance' versus 'growth', | ||
| 2. link narrative to numbers-financial statements being hard to reconcile to the narrative | ||
| 3. compare entities-challenges comparing entities making different capitalisation versus expensing judgements, and |

| Topic | IASB preliminary views | Indications from UKEB research |
|---|---|---|
| 4. understand recognised intangible assets-users struggling to understand entities' capitalisation, valuation, amortisation, impairment and categorisation decisions. | disaggregation into opex and capex spend. | |
| Users are cognisant of the need to weigh commercial sensitivity and cost/benefit of those disclosures. | This is consistent with UKEB case study findings, which indicate that clearer principles for recognition and measurement could provide the stable foundation for consistent and comparable disclosures requested by investors. For example, differences in the accounting treatment of acquired and internally generated intangibles may limit the usefulness and comparability of disclosures. | |
| Accordingly, several IASB members emphasised that improvements to disclosures should not be delayed by more complex work on recognition and the work on disclosures should be re-prioritised to commence urgently. | ||
| 3(a) Improving comparability of information -organic vs acquisitive entities and usefulness of information about acquired intangibles recognised in a business combination | Some members noted that comparability concerns mainly arise from the difference in existing accounting for acquired and internally generated intangible assets, the former are permitted to be recognised and the latter are not. Some noted that the amortisation of intangibles can distort performance measures and reduce the usefulness of information. While IASB members highlighted several approaches: (a) improving disclosures, (b) increasing recognition of internally generated intangibles, or (c) reducing recognition of acquired intangibles, there was general support for (a) | Investors value comparable information. Current reporting requirements, particularly limited disaggregation and different accounting treatments for acquired versus internally developed intangibles, reduce comparability of current financial information for intangibles. Improved disclosures could help users make their own comparisons by providing greater comparability over years and across entities. |
| Some stakeholders have highlighted that disclosure on its own may lack the granularity and be constrained by materiality and reporting limitations. They consider that, comparability may need to be considered more holistically by developing a comprehensive principles-based approach. |

| Topic | IASB preliminary views | Indications from UKEB research |
|---|---|---|
| -focusing first on enhanced disclosures as a practical way to improve comparability. | ||
| 3(b) Improving measurement of intangible assets | Some members noted that the measurement requirements in IAS 38 may be outdated, with the current model-focused on amortised cost and limited use of revaluation-seen as having limited relevance in the contemporary business context. However, there was agreement that there is no need for a standalone measurement project and that measurement could be addressed in the context of other related areas.8 | UKEB research so far indicates that the measurement of intangible assets is challenging, particularly due to uncertainty about future economic benefits and difficulties in determining an appropriate unit of account. This becomes more complex for activities that are managed on a portfolio basis. While fair value measurement could be applied in some contexts, stakeholders are concerned that its broader use may be limited due to concerns about reliability and subjectivity. |
UKEB key messages
C9 We welcome the IASB drawing on the UKEB's case study work as part of its evidence base. These case studies provide practical insight into how IAS 38 is applied across a range of fact patterns (e.g. R&D, data, training, and carbon credits), highlighting both areas of consistent application and points of tension or ambiguity. They demonstrate the challenges in applying existing requirements to modern, intangible-driven business models, and provide a useful diagnostic for targeted standard-setting, including evaluating how alternative recognition and measurement approaches perform across different business models.
Principles-based review
C10 We acknowledge that certain asset classes (e.g. crypto-assets, carbon credits) are increasingly prevalent. However, the challenges they present largely reflect broader limitations in IAS 38 (e.g. unclear unit of account, limited business model-

based classification, and measurement uncertainty), rather than issues unique to those assets.
C11 Therefore, we would recommend maintaining the UKEB's support for a broad, principles-based review of the accounting for intangible assets, rather than fragmenting the project into separate workstreams for specific asset types. A holistic approach is more likely to:
- ensure internal consistency across different types of intangibles;
- avoid unintended consequences and boundary issues between standards; and
- future-proof the requirements against emerging forms of intangible assets.
C12 In our view, focusing on underlying economic characteristics (e.g. how assets generate value, are managed, and give rise to cash flows), rather than asset-specific solutions, will better support comparability and reduce complexity over time.
Accounting based on business model
C13 Consistent with feedback from our outreach and case study work, we observe strong support for an approach that reflects how intangible assets are used within an entity's business model. In particular:
- distinguishing between intangibles held for sale or trading, use in operations, and long-term investment appreciation is critical to understanding their economic role;
- similar expenditures (e.g. on software, data, or platform development) may have different economic substance depending on how they contribute to value creation; and
- current requirements do not always capture these distinctions clearly, which can obscure performance and reduce decision-usefulness.
C14 Therefore, encouraging the IASB to explore the business model concept for intangibles could help inform the broader standard setting questions about recognition, measurement, and presentation.
Disclosure underpinned by good accounting
C15 We agree with the IASB that improving disclosures is a priority and responds to clear user demand, particularly for greater disaggregation, linkage, and transparency. However, there is a risk that enhanced disclosures alone could result in entity-specific and management-defined information that lacks consistency and comparability across entities and over time. This would limit

users' ability to make consistent assessments across entities, undermining one of the primary objectives of financial reporting.
C16 In particular:
- weaknesses or inconsistencies in recognition (e.g. differences between acquired and internally generated intangibles) can limit the effectiveness of disclosures; and
- there is a risk that relying primarily on disclosures could increase complexity and obscure comparability if not anchored in consistent accounting outcomes.
Acquired vs internally generated asymmetry
C17 Another clear message from both the IASB's and UKEB's research is the need to explicitly address the asymmetry between acquired and internally generated intangible assets. This distinction is a primary driver of comparability concerns and may obscure an entity's underlying economic performance. Any reform to recognition principles should consider whether this distinction remains conceptually justified.
C18 In addition, it is clear from the research that measurement challenges, particularly uncertainty of future benefits and defining the unit of account, are integral to the broader issues in IAS 38. While we agree that a standalone measurement project may not be necessary, these challenges should be addressed as part of a holistic review to ensure that any revised model faithfully represents the underlying economics without introducing undue subjectivity.
C19 A singular focus on prioritising disclosures in response to user demand, can undermine the importance of sequencing. Early disclosure improvements should be designed with a clear pathway to, and consistency with, future recognition and measurement reforms. Without this, there is a risk of embedding disclosure requirements that are not aligned with eventual accounting outcomes, leading to rework, increased cost, user confusion and reduced credibility of reported information.
Question for the Board
- Considering the IASB's findings on user information needs and the UKEB's research findings so far, what is the Board's advice on the key messages to the IASB on the appropriate direction and prioritisation of their project?
Appendix D: Presentation of Taxes or Other Charges that Are Not Tax Expense or Tax Income Applying IAS 12 Income Taxes (IFRS 18)

UKEB Project Status
| Monitoring |
IASB Next Milestone
The IASB will decide whether to proceed with a potential amendment to IFRS 18.
Purpose
D1 The purpose of this paper is to provide an update on the IASB's deliberation at its May 2026 meeting of decisions made by the IFRS Interpretations Committee ('the Interpretations Committee' or 'the Committee') at its March 2026 meeting to finalise:
- the Agenda Decision Presentation of Taxes or Other Charges that Are Not Tax Expense or Tax Income Applying IAS 12 Income Taxes (IFRS 18); and
- updates to the Agenda Decision Presentation of Payments on Non-income Taxes (IAS 1 Presentation of Financial Statements and IAS 12) and the Agenda Decision Classification of Tonnage Taxes (IAS 12).
Background
D2 At its meeting in October 2025, the IASB asked the Interpretations Committee to consider a consistent application matter related to the application of IFRS 18 Presentation and Disclosure in Financial Statements. The matter concerns the presentation of taxes or other charges that are not income taxes within the scope of IAS 12 Income Taxes by an entity applying IFRS 18.

D3 The Board has previously considered this topic at its May 2026 meeting9. A summary of the issue is provided below.
| | IFRS 18 Presentation and Disclosure in Financial Statements | |:---|:---|:-------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------
- Do Board Members have any feedback in relation to the UKEB's key messages for the July 2026 ASAF meeting (see paragraph B10)?
Next steps
B11 The Secretariat will continue to engage with UK stakeholders during the DCL consultation period.
B12 The Secretariat will present a technical paper based on updates from stakeholder feedback for discussion at the UKEB October 2026 meeting. A verbal update on any comment letters received will also be provided.
Appendix C: Intangible Assets

Project Stage
| IASB | Research / Pipeline | Discussion Paper | Redeliberation | Exposure Draft | Redeliberation | Final Standard | Post Implementation Review | UKEB Post Implementation Review |
|---|---|---|---|---|---|---|---|---|
| UKEB | Research / Influencing | Research / Monitoring | Influencing | Influencing | Monitoring | Endorsement | Influencing |
IASB Next Milestone: Decide Project Direction (H2 2026)
Objective
C1 This paper:
- summarises the IASB's research findings on users' information needs and the IASB's current thinking on the direction of its Intangible Assets project[^4]; and
- sets out the Secretariat's preliminary views on the direction of this project and seeks the Board's input in response to the IASB's request for advice, (to inform the July 6, 2026 ASAF meeting).
User feedback
C2 At its May 2026 meeting, the IASB discussed the information users seek about intangible assets, how they use it, where they currently obtain it, and the improvements they would like to see.
C3 The key findings from the IASB's research are as follows:
| Issue | Description |
|---|---|
Appendix D: Presentation of Taxes or Other Charges that Are Not Tax Expense or Tax Income Applying IAS 12 Income Taxes (IFRS 18)

UKEB Project Status
| Monitoring |
IASB Next Milestone
The IASB will decide whether to proceed with a potential amendment to IFRS 18.
Purpose
D1 The purpose of this paper is to provide an update on the IASB's deliberation at its May 2026 meeting of decisions made by the IFRS Interpretations Committee ('the Interpretations Committee' or 'the Committee') at its March 2026 meeting to finalise:
- the Agenda Decision Presentation of Taxes or Other Charges that Are Not Tax Expense or Tax Income Applying IAS 12 Income Taxes (IFRS 18); and
- updates to the Agenda Decision Presentation of Payments on Non-income Taxes (IAS 1 Presentation of Financial Statements and IAS 12) and the Agenda Decision Classification of Tonnage Taxes (IAS 12).
Background
D2 At its meeting in October 2025, the IASB asked the Interpretations Committee to consider a consistent application matter related to the application of IFRS 18 Presentation and Disclosure in Financial Statements. The matter concerns the presentation of taxes or other charges that are not income taxes within the scope of IAS 12 Income Taxes by an entity applying IFRS 18.

D3 The Board has previously considered this topic at its May 2026 meeting9. A summary of the issue is provided below.
| Standard | IFRS 18 Presentation and Disclosure in Financial Statements |
|---|---|
| IASB | Research / Pipeline |
| **UKEB | Research / Influencing |
C1 This paper:
- summarises the IASB's research findings on users' information needs and the IASB's current thinking on the direction of its Intangible Assets project[^4]; and
- sets out the Secretariat's preliminary views on the direction of this project and seeks the Board's input in response to the IASB's request for advice, (to inform the July 6, 2026 ASAF meeting).
User feedback
C2 At its May 2026 meeting, the IASB discussed the information users seek about intangible assets, how they use it, where they currently obtain it, and the improvements they would like to see.
C3 The key findings from the IASB's research are as follows:
| Issue | Description | |:------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------- | | | UKEB Key Messages to convey to the ASAF meeting (July 2026) |
Research / Pipeline
UKEB Research / Influencing
IASB Next Milestone: Decide Project Direction (H2 2026)
Objective
C1 This paper:
- summarises the IASB's research findings on users' information needs and the IASB's current thinking on the direction of its Intangible Assets project[^4]; and
- sets out the Secretariat's preliminary views on the direction of this project and seeks the Board's input in response to the IASB's request for advice, (to inform the July 6, 2026 ASAF meeting).
User feedback
C2 At its May 2026 meeting, the IASB discussed the information users seek about intangible assets, how they use it, where they currently obtain it, and the improvements they would like to see.
C3 The key findings from the IASB's research are as follows:
| Issue | Description |
C1 This paper:
- summarises the IASB's research findings on users' information needs and the IASB's current thinking on the direction of its Intangible Assets project[^4]; and
- sets out the Secretariat's preliminary views on the direction of this project and seeks the Board's input in response to the IASB's request for advice, (to inform the July 6, 2026 ASAF meeting).
User feedback
C2 At its May 2026 meeting, the IASB discussed the information users seek about intangible assets, how they use it, where they currently obtain it, and the improvements they would like to see.
C3 The key findings from the IASB's research are as follows:
| Issue | Description | |:---|:---|:------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------- | Description | UKEB Key Messages to convey to the ASAF meeting (July 2026) | |:------------|:----------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------- | | | This summarises user feedback based on Agenda Papers 17A–17C presented at the May 2026 IASB meeting. This evidence spans over 100 pages of research and analysis and is drawn from IASB staff desktop research (Agenda Paper 17A), in-depth discussions with equity analysts (Agenda Paper 17B), and additional evidence including research on credit analysts and lenders and input from consultative groups—the Corporate Reporting Users' Forum UK (CRUF UK), the Capital Markets Advisory Committee (CMAC), the Accounting Standards Advisory Forum (ASAF) and the Emerging Economies Group (EEG). and EFRAG outreach (Agenda Paper 17C). | | 4 | The IASB is using the term 'intangible assets held for investment' to describe intangible assets other than those used in the production or supply of goods or services or held for sale in the ordinary course of business. |
| Description | UKEB Key Messages to convey to the ASAF meeting (July 2026) |
|---|---|
| Description | UKEB Key Messages to convey to the ASAF meeting (July 2026) |
| :------------ | :--------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------- |
| The UKEB notes these specific messages received on the topic of intangible assets via the ASAF meeting (July 2026), alongside other input already available to the IASB. | |
| Project | UKEB Key Messages to convey to the ASAF meeting (July 2026) |
| IAS 37 Provisions, Contingent Liabilities and Contingent Assets | The UKEB supports the IASB in its decision to update IAS 37 Provisions, Contingent Liabilities and Contingent Assets. However, the UKEB notes that IASB staff will provide an update on the project at the forthcoming ASAF meeting and expects to provide an update on the project at its July 2026 Board meeting. |
| The UKEB highlights the following messages from its outreach and analysis: | |
| 1. Onerous Contracts (Agenda Paper 8A) | |
| The UKEB supports the IASB in taking forward its work on onerous contracts. The UKEB agrees with the IASB’s tentative decision to propose amendments to IAS 37 to: | |
| 1. | clarify the meaning of unavoidable costs by adding that unavoidable costs are those costs that an entity could not avoid if it were to cancel the contract; and |
| 2. | clarify that when an entity applies the direct approach for determining unavoidable costs, it should include all direct costs of fulfilling the contract (ie incremental costs such as materials and labour and an allocation of costs directly related to contracts such as depreciation of equipment used to fulfil the contract). |
| The UKEB notes that these changes address stakeholder feedback, including from the UKEB, and improve the usefulness of the information provided to users by improving the consistency of application and the comparability of financial statements. | |
| The UKEB encourages the IASB to consider whether it should further clarify how entities determine the unavoidable costs of a contract for the purpose of identifying an onerous contract. The UKEB’s outreach found that stakeholders continue to have questions in this area. | |
| The UKEB supports the IASB in its decision to improve the disclosures about onerous contracts. The UKEB agrees with the IASB’s tentative decision to propose amendments to IAS 37 to require entities to disclose: | |
| 1. | the judgements made in determining which contracts are onerous; |
| 2. | how entities determine the unavoidable costs of contracts (eg: whether entities apply the direct approach or an alternative approach for determining unavoidable costs); and |
| 3. | information about the significant assumptions used in measuring the provision for onerous contracts (eg: specific growth rates and discount rates used). |
| The UKEB notes that these changes improve the usefulness of the information provided to users by providing more granular disclosures about the assumptions and judgements made in assessing and measuring onerous contracts. This will allow users to better understand how onerous contracts affect an entity’s financial statements and future cash flows. | |
| 2. Restructuring and Disposals (Agenda Paper 8B) | |
| The UKEB supports the IASB in its decision to improve the disclosures about restructurings. The UKEB agrees with the IASB’s tentative decision to propose amendments to IAS 37 to require entities to disclose: | |
| 1. | the judgements made in determining the existence of a constructive obligation; and |
| 2. | how restructurings are expected to affect future cash flows (eg: providing information about the stage of implementation of the restructuring projects). |
| The UKEB notes that these changes improve the usefulness of the information provided to users by providing more granular disclosures about the assumptions and judgements made in assessing and measuring restructurings. This will allow users to better understand how restructurings affect an entity’s financial statements and future cash flows. | |
| 3. Financial Guarantees (Agenda Paper 8C) | |
| The UKEB’s outreach found that users are looking for more information about the financial guarantees provided by an entity. The UKEB highlights that users suggested that the IASB could achieve this by requiring entities to disclose: | |
| 1. | more granular disclosures about the types of financial guarantees provided (eg: distinguishing between guarantees to related parties and third parties); |
| 2. | how financial guarantees are expected to affect future cash flows (eg: providing information about the stage of the financial guarantees and the probability of a payout); and |
| 3. | disclosures about specific metrics (eg: financial guarantees as a percentage of total liabilities). |
| The UKEB notes that the IASB staff will provide an update on the project at the forthcoming ASAF meeting and expects to provide an update on the project at its July 2026 Board meeting. | |
| 4. Regulatory Assets and Liabilities (Agenda Paper 8D) | |
| The UKEB supports the IASB in its decision to remove the accounting policy choice that permits entities to present regulatory assets and regulatory liabilities gross or net in the statement of financial position. This will improve the comparability of financial statements. | |
| The UKEB notes that the IASB staff will provide an update on the project at the forthcoming ASAF meeting and expects to provide an update on the project at its July 2026 Board meeting. | |
| 5. Measurement of Provisions (Agenda Paper 8E) | |
| The UKEB supports the IASB in its decision to provide further guidance on the measurement of provisions when there is a range of possible outcomes. The UKEB agrees with the IASB’s tentative decision to propose amendments to IAS 37 to clarify that when there is a range of possible outcomes and each point within the range is not equally likely, an entity would use the weighted average of all possible outcomes. | |
| The UKEB notes that these changes address stakeholder feedback, including from the UKEB, and improve the usefulness of the information provided to users by improving the consistency of application and the comparability of financial statements. | |
| The UKEB notes that the IASB staff will provide an update on the project at the forthcoming ASAF meeting and expects to provide an update on the project at its July 2026 Board meeting. | |
| 6. Changes in Provisions (Agenda Paper 8F) | |
| The UKEB supports the IASB in its decision to provide further guidance on changes in provisions. The UKEB agrees with the IASB’s tentative decision to propose amendments to IAS 37 to clarify that when a change in the provision results from a change in the discount rate or the estimate of the timing of future cash flows, the change in the provision would be presented as interest accretion (or unwinding) in profit or loss. | |
| The UKEB notes that these changes address stakeholder feedback, including from the UKEB, and improve the usefulness of the information provided to users by improving the consistency of application and the comparability of financial statements. | |
| The UKEB notes that the IASB staff will provide an update on the project at the forthcoming ASAF meeting and expects to provide an update on the project at its July 2026 Board meeting. | |
| 7. Liabilities from Claims (Agenda Paper 8G) | |
| The UKEB supports the IASB in its decision to provide further guidance on liabilities from claims. The UKEB agrees with the IASB’s tentative decision to propose amendments to IAS 37 to clarify that the best estimate of the outflow of economic benefits to settle a liability arising from a claim, would include: | |
| 1. | legal and other costs to defend the claim; and |
| 2. | the costs of any settlement or a transfer to a third party. |
| The UKEB notes that these changes address stakeholder feedback, including from the UKEB, and improve the usefulness of the information provided to users by improving the consistency of application and the comparability of financial statements. | |
| The UKEB notes that the IASB staff will provide an update on the project at the forthcoming ASAF meeting and expects to provide an update on the project at its July 2026 Board meeting. | |
| 8. Reimbursements (Agenda Paper 8H) | |
| The UKEB supports the IASB in its decision to provide further guidance on reimbursements. The UKEB agrees with the IASB’s tentative decision to propose amendments to IAS 37 to clarify that an entity would only recognise a reimbursement asset if it is virtually certain that the reimbursement will be received and that this assessment would be made at the same time and in the same way as for the underlying provision. | |
| The UKEB notes that these changes address stakeholder feedback, including from the UKEB, and improve the usefulness of the information provided to users by improving the consistency of application and the comparability of financial statements. | |
| The UKEB notes that the IASB staff will provide an update on the project at the forthcoming ASAF meeting and expects to provide an update on the project at its July 2026 Board meeting. | |
| 9. Expected Changes (Agenda Paper 8I) | |
| The UKEB supports the IASB in its decision to provide further guidance on expected changes when measuring provisions. The UKEB agrees with the IASB’s tentative decision to propose amendments to IAS 37 to clarify that future events that may affect the measurement of a provision (eg: future technological changes, future changes in law and future changes in prices) would be reflected in the measurement of the provision if they are expected to occur. | |
| The UKEB notes that these changes address stakeholder feedback, including from the UKEB, and improve the usefulness of the information provided to users by improving the consistency of application and the comparability of financial statements. | |
| The UKEB notes that the IASB staff will provide an update on the project at the forthcoming ASAF meeting and expects to provide an update on the project at its July 2026 Board meeting. | |
| 10. Transition (Agenda Paper 8J) | |
| The UKEB supports the IASB’s tentative decision to propose amendments to IAS 37 to require retrospective application (with some specific exemptions) of all amendments and to require entities to disclose the impact of applying the new requirements. | |
| The UKEB notes that these changes address stakeholder feedback, including from the UKEB, and improve the usefulness of the information provided to users by improving the consistency of application and the comparability of financial statements. | |
| The UKEB notes that the IASB staff will provide an update on the project at the forthcoming ASAF meeting and expects to provide an update on the project at its July 2026 Board meeting. | |
| 4 | The IASB is using the term 'intangible assets held for investment' to describe intangible assets other than those used in the production or supply of goods or services or held for sale in the ordinary course of business. |
Appendix D: Income Taxes (Pillar Two)
Next steps
D13At a future meeting, the IASB plans5 to explore an analysis of the detailed technical aspects of the potential amendments. This will include considering:
- whether and what elements of the definition of "covered taxes" to incorporate into IFRS 18;
- whether to incorporate the definition of covered taxes in IFRS 18 by:
- making a direct reference to the OECD definition of “covered tax"; or
- reproducing relevant elements of the definition and the related commentary in IFRS 18;
- whether the classification of non-income tax charges that meet the definition of covered taxes in the income taxes category should be required or permitted;
- whether to explicitly require disaggregation of non-income tax charges classified in the income taxes category from income taxes (or whether the principles of disaggregation in IFRS 18 are sufficient);
- whether to introduce additional disclosure requirements for non-income tax charges classified in the income taxes category; and
- whether and how to rename the income taxes category.
D14The UKEB Secretariat will continue to monitor the IASB's redeliberation and tentative decisions and update the Board.
| Question for the Board |
|---|
| 1. Do Board Members have any comments on the IASB's decision to explore amending IFRS 18 to require or allow an entity to classify in the income taxes category of the statement of profit or loss non-income tax charges that meet the definition of "covered taxes" under the OECD's Pillar Two model rules? |
Appendix E: Equity Method
Project Stage
| IASB | Research / Pipeline | Discussion Paper | Redeliberation | Exposure Draft | Redeliberation | Final Standard | Post Implementation Review |
|---|---|---|---|---|---|---|---|
| UKEB | Research / Influencing | Research / Influencing | Monitoring | Influencing | Monitoring | Endorsement | Influencing |
UKEB project page
UKEB Final Comment Letter (published 16 December 2024) IASB Next Milestone: Final Amendments (expected H1 2027)
Purpose
E1The purpose of this paper is to provide an update on the IASB's deliberation at its May 2026 meeting, on the proposals in the Exposure Draft (ED) 'Equity Method of Accounting IAS 28 Investments in Associates and Joint Ventures (revised 202x)' relating to:
- presentation of the investor's share of the associate's profit or loss and other comprehensive income; and
- transactions with associates6.
Background
E2In September 2024, the IASB published its ED, which aimed to:
- clarify and add to the requirements in IAS 28, to answer application questions about the equity method of accounting;
- reorder the requirements in a more logical and consistent way to help companies apply the Standard i.e. improve the understandability; and
- improve the disclosure requirements in IFRS 12 Disclosure of Interests in Other Entities and IAS 27 Separate Financial Statements to complement the proposed amendments to IAS 28.
E3The UKEB undertook a ‘light touch' approach in responding to the ED and is not aware of pervasive or material concerns for the UK arising from the proposals. Therefore, the UKEB supported the proposals in the ED, but did not comment on each specific proposal.
Status of IASB redeliberation
E4In May 2025, the IASB discussed feedback on the ED.
E5In September 2025, the IASB commenced its redeliberation of the ED proposals. The Board has received regular updates on IASB's decisions/tentative decisions7.
E6The IASB is expected to issue a revised Standard in H1 20278.
IASB May 2026 meeting
E7At its May 2026 meeting, the IASB continued its redeliberation of the ED proposals and:
- made tentative decisions on the recognition and separate presentation of the investor's share of the associate's profit or loss and other comprehensive income; and
- considered the feedback on the ED proposal that an investor would recognise gains and losses in full from transactions with associates, and decided on the way forward9.
Presentation of the investor's share of the associate's profit or loss and other comprehensive income
| Presentation of the investor's share of the associate's profit or loss and other comprehensive income |
|---|
| #### Current requirements |
| Paragraph 38 of IAS 28 requires that if an investor's share of losses equals or exceeds its interest in the associate, the investor discontinues recognising its share of further losses. |
| Paragraph 39 of IAS 28 requires that if the associate subsequently reports profits, the entity resumes recognising its share of those profits only after its share of the profits equals the share of losses not recognised. |
| IAS 28 does not include requirements on how an investor accounts for its share of the associate's profit or loss and its share of the associate's other comprehensive income, if both are losses that, in aggregate, equal or exceed its net investment in the associate. |
| #### Exposure Draft proposals |
| The ED proposed that an investor that has reduced its interest in an associate to nil would be required to: |
|
| #### UKEB Comment Letter |
| The UKEB Final Comment Letter generally supported the ED proposals but did not comment on each specific proposal. |
| #### IASB tentative decisions |
| At its May 2026 meeting, in considering the feedback on the ED, the IASB decided to: |
|
The IASB also considered an additional aspect i.e. whether the investor, on resuming the recognition of its share of profit after the investment has been reduced to nil, should recognise first its share of the associate's profit or loss or its share of the associate's other comprehensive income. The IASB decided not to add a question to the scope of the project.
UKEB Secretariat preliminary view
The IASB's tentative decision about the ED proposal in (a) above is consistent with the ED proposal.
The IASB tentatively decided to withdraw the ED proposal in (b) due to mixed feedback received in response to the ED. In particular, respondents to the ED expressed concern that the proposal introduces unnecessary complexity and could result in an investor presenting a profit in profit or loss before any unrecognised losses have been recovered.
Transactions with associates
E8In May 2026, the IASB met to discuss an analysis of feedback on the ED proposals that and investor would:
- recognise in full gains and losses from transactions with associates; and
- disclose gains or losses from 'downstream' transactions with its associates.
Background
E9There are polarised views on the ED proposal to recognise in full gains and losses from transactions with associates. Whilst most respondents who commented agreed with the ED proposal, some respondents (mostly from Japan and China) disagreed because, in their view:
- the proposed change to the requirements in paragraph 28 of IAS 28 is inconsistent with the project objective, which is to answer application questions without undertaking a fundamental review of the equity method;
- the requirements in paragraph 28 of IAS 28 are consistent with the view that the equity method is a one-line consolidation method; and
- the proposal might lead to earnings management/structuring opportunities.
E10To understand the background to the polarised views, the IASB undertook additional outreach and considered a summary of the feedback from the additional outreach in February 202612.
IASB tentative decisions
| Transactions with associates |
|---|
| #### Current requirements |
| Paragraph 28 of IAS 28 requires an investor to recognise gains or losses resulting from transactions with an associate only to the extent of the unrelated investors' interests in the associate13. That requirement applies to both ‘downstream' transactions (such as a sale or contribution of assets from an investor to an associate) and 'upstream' transactions (such as a sale of assets from an associate to an investor). |
| If an investor loses control of a subsidiary in a transaction with an associate, the requirement in IAS 28 to recognise only a portion of the gains or losses is inconsistent with the requirement in IFRS 10 Consolidated Financial Statements to recognise in full the gain or loss on losing control of a subsidiary. |
| #### Exposure Draft proposals |
| The ED proposed requiring an investor to: |
|
| #### UKEB Comment Letter |
| The UKEB Final Comment Letter generally supported the ED proposals but did not comment on each specific proposal. |
| #### IASB decisions: May 2026 |
| 1. Project scope |
| The IASB decided to retain within the scope of the project the application question on inconsistency between IAS 28 and IFRS 10. |
| 2. Introducing an accounting policy choice |
| The IASB staff explored several alternative ways forward14 and recommended that the IASB should permit an accounting policy choice. This would allow those who supported the ED proposal to choose full recognition of gains and losses on transactions with associates, while accommodating those who disagreed with the proposal. |
The IASB tentatively decided:
- to introduce an accounting policy choice that permits an investor to choose either full or restricted recognition of gains or losses on all transactions with associates, except for gains or losses on transfer of businesses, which would be recognised in full;
- to confirm its proposal in the ED to withdraw the amendments in Sale or Contribution of Assets between an Investor and its Associate or Joint Venture (2014); and
- to amend IFRS 10 to require an investor that chooses to restrict gains and losses on transactions with associates to also restrict gains and losses on the loss of a control of a subsidiary that is not a business.
3. Disclosures
The IASB tentatively decided that:
- if an investor chooses to recognise gains or losses in full, the investor discloses:
- the accounting policy for recognising gains or losses on transactions with associates; and
- gains or losses from 'downstream' transactions with its associates (as proposed in the ED); and
- if an investor chooses to restrict the recognition of gains or losses, the investor discloses:
- its accounting policy for recognising gains or losses on transactions with associates;
- a reconciliation of the opening balance to the closing balance of restricted gains or losses on transactions with associates;
- the amount of gains or losses restricted at the end of the period and where it is included in the statement of financial position; and
- the line items in the statement of comprehensive income where the restricted gains or losses have been recognised.
UKEB Secretariat preliminary view
The Secretariat notes feedback received by the IASB from some stakeholders that the ED proposal to recognise the full gains or losses resulting from all transactions with associates might lead to earnings management/structuring opportunities.
In the Secretariat's view, the introduction of an accounting policy choice, while impairing comparability, might address the concerns of some stakeholders on the ED proposal. The additional disclosures now proposed would provide useful information to users and mitigate the potential negative effect on comparability an accounting policy choice might have for users of the financial statements, by providing users with similar information regardless of the policy choice made.
IASB discussion
E11Many IASB members who commented on the feedback that the ED proposal might lead to earnings management/structuring opportunities disagreed with this argument. This is because any earnings management would indicate the investor has control and should therefore be consolidating, rather than equity accounting, the investee. One IASB member also noted that IAS 24 Related Party Disclosures requires specific disclosures of transactions with related parties, including associates. Such disclosures mitigate the risks of earnings management/ structuring opportunities.
E12One IASB member strongly disagreed with the accounting policy choice because:
- It is against the project objective to reduce diversity in practice.
- It will reduce comparability.
- The current requirement in IAS 28 on the restriction of gains or losses from transactions with associates has a conceptual basis. The accounting policy choice is not an improvement and thus will not lead to high quality financial reporting.
- The ED proposal is a practical solution that is less burdensome for preparers.
E13Other IASB members agreed that the ED proposal is conceptually 'superior' mainly because it would:
- provide useful information to users, for example, to help estimate future cash flows and analyse the associate's performance; and
- be simpler and less costly to apply for preparers.
E14However, these IASB members supported the accounting policy choice because:
- It is a pragmatic solution.
- The lack of comparability would be mitigated through the additional disclosures suggested by the staff.
- It responds to the mixed views i.e. it satisfies those stakeholders who supported the ED proposal and respond to the concerns of those who strongly disagreed with the ED proposals.
Next steps
E15The IASB will continue redeliberating the following topics:
- the scope of transactions to be disclosed for 'downstream' and 'upstream' transactions with an associate; and
- the possible introduction of an exemption from disclosing some or all of the information about gains or losses from transactions with associates, if the disclosure could be expected to seriously prejudice the investor.
E16The IASB will continue redeliberating the remaining ED proposals over the next few months.
E17The UKEB Secretariat will continue to monitor the IASB's redeliberation and tentative decisions and update the Board.
Appendix F: Business Combinations—Disclosures, Goodwill and Impairment
Project Stage
| IASB | Research / Pipeline | Discussion Paper | Redeliberation | Exposure Draft | Redeliberation | Final Standard | Post Implementation Review |
|---|---|---|---|---|---|---|---|
| UKEB | Research / Influencing | Research / Influencing | Monitoring | Influencing | Monitoring | Endorsement | Influencing |
UKEB project page
UKEB Final Comment Letter on Exposure Draft (published 19 July 2024) IASB Next Milestone: Decide Project Direction H2 2026
Purpose of this paper
F1This paper provides the Board with an update on the International Accounting Standards Board's (IASB's) redeliberation at its May 2026 meeting of the proposals in the Exposure Draft Business Combinations—Disclosures, Goodwill and Impairment (the ED)15.
Background
F2The IASB's objective for this project is to explore whether entities can, at a reasonable cost, provide users with more useful information about business combinations (by amending the requirements in IFRS 3 Business Combinations).
F3The resulting information should assist users to make better decisions, by helping them to understand and assess:
- the strategic rationale behind an acquisition;
- how the acquired business is performing; and
- whether the acquirer's management has been effective and efficient in using the entity's economic resources to acquire the business.
F4Within this project, the IASB aims to improve the effectiveness and reduce the cost and complexity of the impairment test in IAS 36 Impairment of Assets.
IASB meeting 20 May 2026
Acquisition date expected synergies and post-acquisition performance information
F5At its May 2026 meeting, the IASB discussed the suggested package of disclosures about the expected synergies from, and post-acquisition performance of, some business combinations.
F6The IASB tentatively decided, by the narrowest margin possible, that the benefits of the suggested package of performance information and expected synergy information would justify the costs associated with providing the information. Details of the decisions are set out in the table below:
| Changes to the ED proposed package of acquisition-date expected synergy information and subsequent performance information |
|---|
| #### Current requirements |
| Paragraph B64(e) of IFRS 3 requires an acquiring company to disclose, for each business combination that occurs during the reporting period, a qualitative description of the factors that make up the goodwill recognised (such as expected synergies from combining operations of the acquiree and the acquirer, intangible assets that do not qualify for separate recognition, or other factors). |
| There are currently no requirements for an acquirer to disclose separate post-acquisition performance in relation to an acquired business. |
| ED proposals |
|---|
| #### Subsequent performance of a business combination |
| To provide users with more useful information, the ED proposed to require an entity to provide disclosures about the performance of a business combination. In particular, the ED proposed to require an entity to disclose: |
|
| In the ED, the IASB responded to preparers' concerns about disclosing this information by proposing: |
|
| A 'strategic' business combination would be one for which failure to meet any one of an entity's acquisition-date key objectives would put the entity at serious risk of failing to achieve its overall business strategy. |
| The ED proposed that entities identify a 'strategic' business combination using a set of thresholds in IFRS 3 (see paragraphs BC56–BC73). The proposed thresholds are both quantitative (see paragraphs BC63–BC67) and qualitative (see paragraphs BC68–BC70). |
| #### Quantitative expected synergy information |
| The ED also proposed requirements to disclose quantitative information about expected synergies, including a description of expected synergies by category and, for each category of synergies: |
|
| An entity would be required to disclose expected synergy information for each material business combination and in aggregate for individually immaterial business combinations that are material collectively. |
| #### UKEB Comment Letter |
| The UKEB broadly supported the IASB's proposals to require disclosure of information about the performance of business combinations, based on the acquirer's acquisition-date KOTs, for only a subset of the most important business combinations. However, the UKEB considers that the proposed exhaustive list of quantitative and qualitative |
thresholds16, may not capture the most important acquisitions. Instead, the UKEB recommended a principle-based approach, including a rebuttable presumption, focusing on the importance of the acquisition to achieve the acquirer's overall business strategy (see paragraphs 6 and 8 of the UKEB Comment letter).
The UKEB highlighted concerns with the ‘operating profit' threshold due to volatility (see paragraphs A19–A20 of the UKEB Comment Letter).
The UKEB also suggested that the IASB should require disclosures for a series of business combinations that individually may not appear to be strategic but are part of a series of acquisitions which are collectively strategic (see UKEB Comment Letter paragraphs A11–A15).
IASB May 2026 meeting update
At its May 2026 meeting, the IASB tentatively decided that the benefits of the suggested package of performance information and expected synergy information (being a revised version of that included in the ED17, as set out below) would justify the costs of providing that information and could therefore proceed with the next steps.
The following diagram18 summarises the revised suggested package, indicating changes to the package proposed in the ED:

| Key | |
|---|---|
| ✔ Retain from Exposure Draft | S Only required for a Subset |
| X Remove from Exposure Draft | E Exemption can be applied |
| + Add since Exposure Draft |
| At acquisition | Subsequently |
|---|---|
| ✓ Key objectives for a subset SE | ✓ Actual performance S |
| ✓ Targets for a subset SE | + Only performance against currency unit targets |
| + How performance information is measured | |
| ✓ Expected synergies for all material E BCs | X Qualitative statement E |
| X Aggregated expected synergies for E individually immaterial BCs | |
| + Statements that targets / expected synergies are management's expectation |
| Subset for performance information: | Exemption |
|---|---|
| ✓ 10% of revenue | ✓ If disclosure seriously prejudices any of the acquisition's KOTs or |
| X 10% of operating profit | + If disclosure breaches legal / regulatory requirements. |
| X 10% of total assets | |
| X Qualitative thresholds |
Only a simple majority (seven of 13) of IASB members supported the suggested proposals.
IASB members who did not support the revised package of proposals, including all three investor members, expressed concerns that a key objective for the project (to improve information on the success of acquisitions) would not be met. Specific concerns raised include the following:
- There is a risk that the proposed thresholds are at such a level that they only rarely be met, meaning the required disclosures will rarely be made.
- The proposed focus on currency unit targets may lead to investors receiving incomplete information about acquisitions, as such targets may not be aligned with the entity's approach to the acquisition.
- There are challenges relating to the reporting of synergies, and questions around the usefulness of the proposed disclosures.
IASB members who supported the revised suggested package acknowledged there have been compromises made when revising the original ED proposals. However, they preferred to support a 'stepping stone' approach that they considered was moving the disclosure requirements in the right direction and which might provide a good basis on which to build future requirements to further improve information for users. On balance, those IASB members thought that some disclosure requirements for some important acquisitions were better than none.
DPOC June 2026 meeting update
At its June 2026 meeting, the Due Process Oversight Committee (DPOC) noted the need for a supermajority19 to approve a new or amended IFRS Accounting Standard and questioned how the IASB plans to finalise the project successfully.
The IASB Chair advised that the staff are considering how the concerns of IASB members that do not currently support the proposals can be addressed in a way that can be supported by the remaining IASB members.
UKEB Secretariat views
The Secretariat notes that only a simple majority of IASB members supported the suggested proposals and there is a need for a supermajority to approve a new or amended IFRS Accounting Standard. The UKEB Secretariat cannot currently see a path to the revised package being finalised for publication as an amendment to the Standard under the requirements in the IFRS Foundation's Due Process Handbook.
The UKEB Secretariat agrees with the IASB members who did not support the revised package of proposals, i.e. that the suggested disclosure requirements will likely not improve the information provided to users about the most important acquisitions.
The Secretariat also agrees that, on balance, the proposals will not sufficiently improve the information that users receive and suggests that the IASB proceeds only with the changes proposed in the ED to simplify the impairment test in IAS 36 Impairment of Assets20.
ASAF meeting July 2026
F7At the forthcoming meeting of the IASB's Accounting Standards Advisory Forum (ASAF), of which the UKEB is a member, the IASB staff will provide an update on the project status. No specific consultation questions are expected as part of this update. However, it will be beneficial to understand the views of the Board on the IASB's proposals ahead of any discussions at ASAF.
| Question for the Board |
|---|
| 1. Do Board Members agree with the Secretariat that, on balance, the IASB's proposals will not sufficiently improve the information that users receive? |
| 2. Do Board Members agree that the IASB should proceed only with the changes proposed in the ED to simplify the impairment test in IAS 36? |
Next Steps
F8At the May 2026 meeting, it was agreed the IASB will continue redeliberating the benefits of the suggested package of disclosures about performance of a business combination and expected synergies.
F9At a future meeting the IASB will finalise other aspects of the requirements such as:
- amendments to IFRS 19;
- the disclosure of performance and expected synergy information in interim financial reports; and
- transition.
F10The UKEB Secretariat will continue to monitor the IASB's redeliberation and tentative decisions and will provide the Board with updates accordingly.
F10The UKEB Secretariat will continue to monitor the IASB's redeliberation and tentative decisions and will provide the Board with updates accordingly.
Appendix G: Statement of Cash Flows and Related Matters
Project Stage
| IASB | UKEB | |
|---|---|---|
| Research / Pipeline | Research / Pipeline | Research / Influencing |
| Discussion Paper | Discussion Paper | Research / Influencing |
| Redeliberation | Redeliberation | Monitoring |
| Exposure Draft | Exposure Draft | Influencing |
| Redeliberation | Redeliberation | Monitoring |
| Final Standard | Final Standard | Endorsement |
| Post Implementation Review | Post Implementation Review | Influencing |
| UKEB Post Implementation Review | UKEB Post Implementation Review |
IASB Next Milestone: Exposure Draft (2027)
UKEB project page
Purpose
G1The purpose of this paper is to ask for Board Members' views on the key messages the UKEB plans to convey at the July 2026 Accounting Standards Advisory Forum (ASAF) meeting. At the meeting, the IASB technical staff will provide ASAF members with an overview of the IASB's initial research and activities to date relating to the statement of cash flows for financial institutions and will seek ASAF members' views on its approach for financial institutions, including:
- Whether the expected benefits of the tentative improvements to cash flow information generally, apply to financial institutions.
- Possible exemptions for financial institutions, from some or all of the requirements from presenting a statement of cash flows.
- Possible presentation or supplementary disclosure requirements specific for financial institutions that might enhance the usefulness of information about cash flows for such entities.
G2The IASB technical staff will also seek ASAF members' advice on any industry groups or other stakeholders to engage with during outreach on this topic.
G3Input received at the ASAF meeting will be used by the IASB staff to help plan future work for financial institutions and develop ideas for discussion with the IASB members at a future meeting.
Background
G4This paper provides the Board with an update1 on the status of the Statement of Cash Flows and Related Matters project, following the IASB's meeting in May 2026, at which the IASB discussed:
- Disaggregation of cash flow information; and
- Changes in liabilities arising from financing activities.
G5Last year, at its May 2025 meeting, the IASB decided that this project would address five topics:
- The transparency of information communicated about cash flow measures not specified in IFRS Accounting Standards.
- The consistent application of requirements for classification of cash flows i.e. operating, investing or financing.
- The disaggregation of cash flow information in the financial statements.
- The reporting of information about non-cash transactions in the financial statements.
- The consistent application of the definition of 'cash equivalents'.
G6The IASB decided to consider any additional changes to cash flow statement requirements for financial institutions only after concluding discussions on the above topics.
G7The project was moved to the IASB's standard setting work plan in January 2026.
G8The tentative decisions made by the IASB to date on this project can be found in Appendix A of Staff Agenda Paper 20 for the May 2026 IASB meeting 2.
May 2026 IASB meeting
Disaggregation of cash flow information
G9In September 2025, the IASB tentatively decided to improve the disaggregation of cash flow information by strengthening the link between the statement of cash flows and information presented or disclosed in other parts of the financial statements in accordance with IFRS Accounting Standards other than IAS 7 Statement of Cash Flows.
G10At its May 2026 meeting, the IASB was asked whether it agrees to:
- aggregating and disaggregating line items in the statement of cash flows;
- labelling and describing line items; and
- specifying that the information in a note might relate to more than one primary financial statement.
G11The IASB's tentative decisions made at the May 2026 meeting are set out below:
| Improving disaggregation of cash flow information by strengthening the link with other information |
|:------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------ to
* The entity must be registered in the UK or ROI
* Annual revenue must exceed £10 million
* The auditor must be struck through independent
For uppercase alphabetical lists:
- First criterion
- Second criterion with bold text
- Third criterion
``
(Note: Use HTML
-
Table of Contents Handling:
- Begin with first substantive content: Start your markdown output with the first real content section, omitting cover pages, title pages, and decorative elements
- When PDF has a Table of Contents page: Insert the placeholder
[TOC]on a new line where the original Contents page was located- The Contents heading and its list items become:
[TOC] - This single marker will be replaced with an auto-generated, linked table of contents
- Document flow: cover pages (omitted) →
[TOC]marker → main content
- The Contents heading and its list items become:
- When PDF has no Table of Contents: Begin directly with the first content section - do not insert
[TOC]
-
Document Structure:
- Use proper markdown heading levels (# ## ###) to preserve document hierarchy
- H1 (#): Never use - reserved for page title
- H2 (##): ONLY for major top-level sections (e.g., "1. Introduction", "2. Methodology", "Appendices")
- H3 (###): For subsections under H2 (e.g., "Background", "Purpose", "Assessment Process")
- H4 (####): For sub-subsections under H3
- CRITICAL: Once you open a numbered section (e.g., "## 3. Risk Assessment"), ALL subsections within that section MUST use H3 or deeper - NEVER promote them back to H2 until you reach the next numbered section (e.g., "## 4. Next Section")
- Heading hierarchy must be continuous - don't skip levels (e.g., don't go from H2 to H4 without an H3)
- Remove any running headers, footers, and page numbers
- Include ALL substantive content including legal disclaimers, copyright notices, and appendices
- Skip only purely decorative elements (page borders, background graphics, etc.)
- Use semantic structure rather than visual formatting
- Add blank lines before headings for readability
- For lists:
- Each list item MUST start on a new line
- Use
-for unordered lists, numbers for ordered lists (e.g.,1.,2.,3.) - Maintain proper indentation for nested lists
- If a list continues from a previous page/chunk, continue the numbering sequence
- Ensure there are blank lines before and after lists for proper rendering
- For alphabetical lists (a., b., c. or A., B., C.): Use HTML ordered lists with
typeandmarkdown="1"attributes:- Lowercase:
<ol markdown="1" type="a"><li markdown="1">First item</li><li markdown="1">Second item</li></ol> - Uppercase:
<ol markdown="1" type="A"><li markdown="1">First item</li><li markdown="1">Second item</li></ol> - CRITICAL: Always include
markdown="1"to ensure markdown formatting inside list items (bold, italic, strikethrough, links, etc.) is properly parsed
- Lowercase:
- For tables:
- CRITICAL: Wrap all tables in a container div for horizontal scrolling:
<div class="table-container" markdown="1">before the table and `
- CRITICAL: Wrap all tables in a container div for horizontal scrolling:
- Use proper markdown heading levels (# ## ###) to preserve document hierarchy
for lowercase orfor uppercase alphabetical lists. Always includemarkdown="1"` to ensure markdown formatting inside list items is parsed.)
Example 8 - Hyperlink Handling (CRITICAL):
CORRECT - Explicit Link:
Text in PDF: "Visit our website at www.example.com"
Markdown: Visit our website at [www.example.com](https://www.example.com)
CORRECT - Clickable Text:
Text in PDF: "Read the full report" (hyperlinked to https://example.com/report)
Markdown: [Read the full report](https://example.com/report)
CORRECT - No Link:
Text in PDF: "Guidance on Audit Matters" (bold text, no hyperlink)
Markdown: **Guidance on Audit Matters**
WRONG - Hallucinated Link (Don't do this):
Text in PDF: "Guidance on Audit Matters" (no hyperlink)
Markdown: [Guidance on Audit Matters](https://www.example.com/guidance-on-audit-matters) -> WRONG! Don't guess URLs.
Markdown: Guidance on Audit Matters -> WRONG! Don't make the text the URL.
CRITICAL - Never Repeat the Document's Own Title (But Keep Everything Else): - The document's title (as it appears on its cover/title page, or as the first prominent heading on page 1) is already displayed separately by the website. Omit ONLY the exact heading/text that duplicates this title - not even reworded or with different punctuation. - This applies even if the title doesn't appear on a visually distinct "cover page" - e.g. if it's simply the first bold/large line of text on page 1, above the real content. - Do NOT omit anything else that appears on the same page as the title. Metadata fields (e.g. "Project Type", "Project Scope", "Status", dates, reference numbers, author names, version numbers) and any other substantive text near the title MUST still be included in your output, even though they're physically close to (or below) the title on the page. If in doubt whether something is "part of the title" or genuine content, always include it - only the literal repeated title itself should ever be skipped. - Begin your output with the first genuine content (which may be that metadata, or the first real content heading, e.g. "Executive Summary"), never with a heading that just restates the document's own title.
WRONG (title duplicated): ``` # Project Initiation Plan - IFRS 18 Presentation and Disclosure in Financial Statements
## Executive Summary ... ```
WRONG (metadata incorrectly dropped along with the title):
## Executive Summary
...
(where the PDF's first page actually read:
"Project Initiation Plan - IFRS 18 ... / Project Type: Endorsement and
adoption / Project Scope: Significant" - only the first line is the
title; the Project Type/Scope fields must still appear in the output)
CORRECT: ``` Project Type: Endorsement and adoption Project Scope: Significant
## Executive Summary ... ```
Requirements:
after
        *   Each table row MUST be on its own line *   Use
|delimiters with proper spacing:| Column 1 | Column 2 |* Include header separator row:
|----------|----------|` * For tables, you MUST include a header row. If the original document provides no headers, create a header row with blank cells. * Do not merge rows or cells * If a table continues from a previous page/chunk, do not repeat the header * Ensure proper alignment using colons in separator row if needed * Example structure: ```
        | Header 1 | Header 2 |
        |----------|----------|
        | Data 1   | Data 2   |
        ```
-   **Heading Cleanup and Hierarchy Verification:**
    *   Delete any titles or headings that contain "(continued)"
    *   If a heading is exactly "ACME Corporation", convert it to a bold paragraph (`**ACME Corporation**`) instead of a heading.
    *   Delete any heading that is identical to the immediately preceding heading at the same level.
    *   **Before creating an H2 heading, verify:** Is this truly a major top-level section, or is it a subsection of the current numbered section? If it's a subsection (like "Assessment Period", "Reporting Requirements", "Summary of Requirements" within a numbered section), use H3 (###) instead.
    *   **Watch for PDF layout tricks:** Sometimes PDFs make subsection titles look prominent (bold, larger font), but they're still subsections. Look at the numbering and logical flow, not just visual appearance.
-   **Extraneous Elements:**
    *   Remove any purely decorative horizontal lines (e.g., `---`, `***`).
-
Content Preservation:
- Include legal disclaimers, copyright notices, and important notices
- Preserve all tables, even if they contain legal or administrative information
- Maintain all substantive text regardless of whether it appears "administrative"
- Only skip content that is purely decorative or redundant page elements
-
Content Formatting:
- Emphasis: Preserve bold and italic text using markdown syntax (
**bold**,*italic*) - Footnotes: Convert to markdown format using 1 syntax, with footnotes collected at end of document
- Hyperlinks:
- Convert ALL hyperlinks to markdown format
[text](url). - CRITICAL: Only include URLs that are explicitly present in the PDF (either visible in text or as a clickable link).
- NEVER invent URLs. If text looks like a title but has no link in the PDF, leave it as plain text.
- NEVER create links where the URL is just the text itself. (e.g.,
Titleis WRONG). - NEVER guess URLs based on the text content.
- Convert ALL hyperlinks to markdown format
- Amendment Documents (e.g. FRED, draft standards): Preserve editing marks:
- Strikethrough text →
~~deleted text~~ - Underlined insertions →
<ins>inserted text</ins> - (Regular underline for emphasis uses standard markdown)
- Strikethrough text →
- HTML Elements with Markdown Content: When using HTML block-level elements that contain markdown-formatted content (bold, italic, lists, etc.), always add
markdown="1"attribute to the opening tag. Examples:<blockquote markdown="1">Governments lie; bankers lie; even auditors sometimes lie: gold tells the truth.</blockquote>- `Chart showing quarterly results:
Revenue increased by 25% over the previous quarter.
- Emphasis: Preserve bold and italic text using markdown syntax (
*
The diagram illustrates the relationship between:

1.  **IFRS Standards** - International requirements
2.  **FRS 102** - UK GAAP for most entities
3.  **The Code** - UK Corporate Governance requirements
- **Blockquotes:** Do NOT wrap the entire blockquote content inbold-- only use bold for specific emphasized words/phrases that are bold in the original PDF. Blockquotes should use normal body text weight by default.
* **Correct:**
Companies should ensure that all requirements are met when presenting disclosures.
* **Correct with selective emphasis:**Companies should ensure that all requirements are met.
* **WRONG:**Companies should ensure that all requirements are met when presenting disclosures.`
-
Numbered Sections and Paragraphs for Web Linking:
- Identify numbered sections/paragraphs: Look for content with explicit numbering like "1.", "2.1", "3.a)", "Section 1", "Paragraph 5", etc.
- Handle numbered paragraphs and sections differently:
- For numbered paragraphs: Create self-linking anchor tags:
<a class="section__global-number" href="#paragraph-N" id="paragraph-N">N</a>Content goes here... - For numbered section headings: Use markdown headings with attr_list syntax to add IDs:
## Section 2.1 Overview {: #section-2-1 } - IMPORTANT: Always use markdown syntax (##, ###) for headings, NOT HTML tags. The markdown processor will automatically make all headings self-linking.
- For numbered paragraphs: Create self-linking anchor tags:
- Anchor ID formatting rules:
- Use lowercase for the prefix ("paragraph-" or "section-")
- Keep numbers and letters exactly as they appear
- For hierarchical numbering: Use dashes instead of dots for IDs (e.g.,
#section-2-1not#section-2.1) - For parenthetical numbering: Convert to dashes (e.g., "3.a)" becomes
#paragraph-3-aor#section-3-a) - For attr_list IDs, use the syntax
{: #id-name }with spaces inside the braces
- ID Uniqueness: All
idattributes MUST be unique within the document. If a number is repeated (e.g., paragraph 1 in multiple sections), create a unique ID by appending a letter or number (e.g.,#paragraph-1,#paragraph-1-a,#paragraph-1-b). - Examples of numbered content to mark:
- Numbered paragraphs: "1. The Panel is authorised..." →
<a class="section__global-number" href="#paragraph-1-1" id="paragraph-1-1">1</a>The Panel is authorised... - Numbered paragraphs: "2.1 Overview details" →
<a class="section__global-number" href="#paragraph-2-1" id="paragraph-2-1">2.1</a>Overview details - Section headings: "Section 2.1 Overview" →
## Section 2.1 Overview {: #section-2-1-overview }(Note: ID includes heading text to ensure uniqueness) - Section headings: "3.a) Requirements" →
### 3.a) Requirements {: #section-3-a-requirements } - Section headings without explicit "Section" word: "1. 2024/25 highlights" →
## 1. 2024/25 highlights {: #section-1-2024-25-highlights } - Regular headings (no numbers): "Financial Statements" →
## Financial Statements(gets auto-generated ID)
- Numbered paragraphs: "1. The Panel is authorised..." →
- Custom IDs only for numbered content: Add attr_list IDs
{: #section-N }only for headings with explicit numbering. Regular headings get auto-generated IDs from their text for TOC linking.
-
Image Handling:
- I'm providing an IMAGE REPORT below containing meaningful embedded images that were extracted and uploaded
- When you encounter an embedded image that corresponds to an entry in the IMAGE REPORT, replace it with:
 - For charts, diagrams, or illustrations that appear visual but are NOT in the IMAGE REPORT (likely drawn as vector graphics/text), wrap descriptions in semantic HTML: use
<div class="chart-description" markdown="1">for charts/graphs,<div class="diagram-description" markdown="1">for technical diagrams,<div class="illustration-description" markdown="1">for other visual elements - For purely decorative visual elements (borders, design patterns, logos used decoratively), skip them entirely
- Include any image captions or titles as part of the surrounding text context
-
Content Guidelines:
- Focus on capturing the semantic meaning of the document
- Preserve the logical flow and relationships between content
- Ensure all content is presented in a screen-reader friendly format
- Include all pages unless they contain only decorative elements
- Keep the output clean and well-structured without extraneous formatting
IMAGE REPORT: EXTRACTED IMAGES: - Page 2: Logo for UKEB, the UK Endorsement Board URL:
-
Page 3: Logo for UKEB, the UK Endorsement Board URL:
-
Page 7: Logo for UKEB, UK Endorsement Board URL:
-
Page 7: Financial table detailing equity composition, including parent share, NCI share, and the adjustment for NCI subject to a put option. URL:
-
Page 8: Financial statement showing profit or loss details, including consolidated net profit, profit from subsidiary, NCI put liability remeasurement, and profit attribution to parent owners and NCI holders. URL:
-
Page 18: Diagram outlining three workstreams. Workstream 1 focuses on user needs and definition/recognition changes. Workstream 2 addresses accounting for intangibles (crypto, carbon credits), IAS 38 review, and disclosure improvements. Workstream 3 covers comparability and measurement of intangibles. URL:
-
Page 22: Logo for UKEB, the UK Endorsement Board, featuring the acronym UKEB in teal with a stylized arrow, and the full name below. URL:
-
Page 42: Key defining document revision marks: check for retain, X for remove, plus for add, S in blue for subset requirement, and E in pink for exemption. URL:
-
Page 42: A structured breakdown of reporting requirements for business acquisitions, detailing criteria at acquisition (S, E) and subsequently (S), performance information subset thresholds (e.g., 10% revenue), and exemption conditions (E). URL:
Provide ONLY the markdown content.
Appendix F
F10The UKEB Secretariat will continue to monitor the IASB's redeliberation and tentative decisions and will provide the Board with updates accordingly.
Appendix G: Statement of Cash Flows and Related Matters
Project Stage
| IASB | UKEB | |
|---|---|---|
| Research / Pipeline | Research / Pipeline | Research / Influencing |
| Discussion Paper | Discussion Paper | Research / Influencing |
| Redeliberation | Redeliberation | Monitoring |
| Exposure Draft | Exposure Draft | Influencing |
| Redeliberation | Redeliberation | Monitoring |
| Final Standard | Final Standard | Endorsement |
| Post Implementation Review | Post Implementation Review | Influencing |
| UKEB Post Implementation Review | UKEB Post Implementation Review |
IASB Next Milestone: Exposure Draft (2027)
UKEB project page
Purpose
G1The purpose of this paper is to ask for Board Members' views on the key messages the UKEB plans to convey at the July 2026 Accounting Standards Advisory Forum (ASAF) meeting. At the meeting, the IASB technical staff will provide ASAF members with an overview of the IASB's initial research and activities to date relating to the statement of cash flows for financial institutions and will seek ASAF members' views on its approach for financial institutions, including:
- Whether the expected benefits of the tentative improvements to cash flow information generally, apply to financial institutions.
- Possible exemptions for financial institutions, from some or all of the requirements from presenting a statement of cash flows.
- Possible presentation or supplementary disclosure requirements specific for financial institutions that might enhance the usefulness of information about cash flows for such entities.
G2The IASB technical staff will also seek ASAF members' advice on any industry groups or other stakeholders to engage with during outreach on this topic.
G3Input received at the ASAF meeting will be used by the IASB staff to help plan future work for financial institutions and develop ideas for discussion with the IASB members at a future meeting.
Background
G4This paper provides the Board with an update1 on the status of the Statement of Cash Flows and Related Matters project, following the IASB's meeting in May 2026, at which the IASB discussed:
- Disaggregation of cash flow information; and
- Changes in liabilities arising from financing activities.
G5Last year, at its May 2025 meeting, the IASB decided that this project would address five topics:
- The transparency of information communicated about cash flow measures not specified in IFRS Accounting Standards.
- The consistent application of requirements for classification of cash flows i.e. operating, investing or financing.
- The disaggregation of cash flow information in the financial statements.
- The reporting of information about non-cash transactions in the financial statements.
- The consistent application of the definition of 'cash equivalents'.
G6The IASB decided to consider any additional changes to cash flow statement requirements for financial institutions only after concluding discussions on the above topics.
G7The project was moved to the IASB's standard setting work plan in January 2026.
G8The tentative decisions made by the IASB to date on this project can be found in Appendix A of Staff Agenda Paper 20 for the May 2026 IASB meeting 2.
May 2026 IASB meeting
Disaggregation of cash flow information
G9In September 2025, the IASB tentatively decided to improve the disaggregation of cash flow information by strengthening the link between the statement of cash flows and information presented or disclosed in other parts of the financial statements in accordance with IFRS Accounting Standards other than IAS 7 Statement of Cash Flows.
G10At its May 2026 meeting, the IASB was asked whether it agrees to:
- aggregating and disaggregating line items in the statement of cash flows;
- labelling and describing line items; and
- specifying that the information in a note might relate to more than one primary financial statement.
G11The IASB's tentative decisions made at the May 2026 meeting are set out below:
| Improving disaggregation of cash flow information by strengthening the link with other information |
|---|
Footnotes
-
Obligations to purchase own equity July 2026 ASAF paper. ↩↩↩
-
Earnings before interest, tax, depreciation and amortisation. Put options containing features of this nature typically define these in the contract, and would not be affected by changes arising from IFRS 18 Presentation and Disclosure in Financial Statements. ↩
-
A summary of the discussion at the roundtable will be uploaded within the next few weeks on the UKEB website. The relevant discussions have been incorporated into the Secretariat's preliminary view about UKEB key messages to convey at the ASAF meeting. ↩
-
Paragraph 30 of Staff paper 12D presented to the IASB at the May 2026 meeting. ↩
-
References to 'investor', 'associate' and 'significant influence' should be read as also referring to 'joint venturer', 'joint venture' and 'joint control' in relation to investments in joint ventures in consolidated financial statements. ↩
-
Refer to:
- ↩
-
For further details on IASB rationale for the ED proposal, stakeholder feedback, IASB's outreach with its consultative groups and UKEB advisory groups feedback, refer to UKEB Public Board Meeting – 26 February 2026, paragraphs D8 - D20 of Agenda Paper 9 IASB General Update (Appendix D). ↩↩
-
For example, if an investor has reduced its net investment to nil and its share of profit or loss is a loss of CU250 and its share of other comprehensive income is a profit of CU100, the investor recognises a loss of CU100 in profit or loss and a profit of CU100 in other comprehensive income. ↩
-
The IASB received mixed feedback on this proposal. Further, the IASB thinks that this aspect of the application question cannot be solved without a fundamental discussion about other comprehensive income. ↩
-
For overall messages from this additional outreach, refer to UKEB Public Board Meeting - 26 March 2026, paragraph C10 of Agenda Paper 8 IASB General Update (Appendix C). ↩
-
The IASB issued amendments to that requirement in 2014 (see Sale or Contribution of Assets between an Investor and its Associate or Joint Venture (Amendments to IFRS 10 and IAS 28)), but the effective date of those amendments has been deferred indefinitely. ↩
-
For the alternatives, see paragraph 23 of Agenda Paper 13D of May 2026 IASB meeting. ↩
-
A summary of the ED proposals, the IASB's redeliberation and tentative decisions to date can be found in Appendix A of the IASB Staff Agenda paper 18 for the May 2026 meeting. ↩
-
The closed threshold approach. ↩
-
The suggested package i.e. changes to the ED proposals, is set out in paragraphs 30-31 of IASB staff paper 18a for the May 2026 meeting. Appendix A of that paper summarises IASB staff views, and the IASB's tentative decisions prior to the May 2026 meeting, on whether to retain or change each aspect of the proposed package, based on the common and specific feedback. ↩
-
Replicated from paragraphs 31 of IASB staff paper 18a for the May 2026 meeting. ↩
-
A supermajority requires that eight members ballot or vote in favour of publishing a document if the board has 13 or fewer members, and nine members in favour if the board has 14 members. (IFRS Foundation Due Process Handbook, paragraph 3.16). ↩
-
Proposals in the ED include amendments to IAS 36 to clarify how to allocate goodwill to cash generating units, certain disclosure requirements relating to cash generating units containing goodwill and amendments to how an entity calculates an asset's value in use. ↩