Project Initiation Plan - Post-Implementation Review of IFRS 16 Leases
Purpose
1On 17 June 2025, the IASB published its Request for Information (RFI) for the Post-implementation Review (PIR) of IFRS 16 Leases1 with a comment deadline on 15 October 2025. This paper sets out the plan to influence the IASB in response to its RFI.
Background
2In January 2016, the IASB issued IFRS 16. The Standard was effective for annual periods beginning on or after 1 January 2019. Earlier application was permitted, as long as IFRS 15 Revenue from Contracts with Customers is also applied. In December 20232, the IASB decided to commence the PIR of IFRS 16.
3The UKEB has undertaken desk-based research and conducted some limited outreach activities on this topic with the UKEB Investor Advisory Group (IAG), the UKEB Preparer Advisory Group (PAG), the UKEB Accounting Firms and Institutes Advisory Group (AFIAG), and the UKEB Academic Advisory Group (AAG). This work has informed this Project Initiation Plan (PIP) and will be reflected in the Draft Comment Letter (DCL).
4During May 2025, the Secretariat also conducted limited and targeted initial outreach with UK IFRS reporters who are lessees through a survey to collect information on the ongoing costs and benefits of applying IFRS 16. There were 51 respondents and their feedback will be reflected in the DCL.
Project Plan
Proportionality assessment
Significance and size
IASB Project scope
5The IASB has established a high threshold for initiating amendments following a PIR. “The IASB uses the PIR process to assess whether the effects of applying new requirements on users of financial statements, preparers, auditors and regulators are as intended when the IASB developed those new requirements”3. This ensures that only significant issues or widespread concerns prompt additional action, thereby maintaining the integrity and stability of the standards.
UK context
6IFRS 16 is relevant to most UK IFRS reporters. However, analysing Reuters-Eikon data for the 2023 year-end of UK listed companies (excluding funds and trusts) revealed the following:
- The total value of lease liabilities across the UK listed market as a whole amounted to £167.4bn, representing 1.8% of total recognised liabilities. The industries with the highest value of lease liabilities are the Consumer (£70.3bn), Energy (£32.8bn), Industrials (£22.9bn) and Telecommunications (£19.0bn) industries. However, a relatively small number of companies with very large total liabilities (primarily financial institutions) but low lease liabilities significantly skew this ratio.
- When analysed by company, rather than the market as a whole, the ratio of lease liabilities to total liabilities for an average company is 13.5%.
Complexity
7Based on the list of questions within the RFI, which primarily focus on the costs and benefits of IFRS 16, the most complex issue relates to sale-and-leaseback transactions.
Expected timeline / urgency
8There are limited UKEB Board and advisory/working group meetings scheduled within the IASB's RFI consultation period. The consultation period also overlaps with interim reporting and summer holidays for a significant number of UK stakeholders. In anticipation of the deadlines, the UKEB Secretariat has performed desk-based research and some limited outreach activities. This included conducting a survey of UK IFRS reporters who are lessees, to collect information on the ongoing costs and benefits of applying IFRS 16.
Expected interest / sensitivity
9There has been interest in the project from a range of UKEB stakeholders, particularly preparers. This is reflected in the number of responses received to the UKEB preparer survey, and in discussions with UKEB advisory groups. There is no indication of any other significant wider UK concerns in relation to this project.
Feedback from desk-based research / initial outreach
10Desk-based research and feedback from initial outreach with stakeholders (UKEB advisory and working groups as well as the UKEB preparer survey) indicate that:
- For some companies implementing and applying IFRS 16 has been costly, with ongoing costs continuing to be high. Stakeholders have suggested mitigations including simplification of discount rate requirements and broadening low value asset exemptions could be considered.
- A number of companies report supplementary non-GAAP measures as a result of applying IFRS 16.
- Technical challenges include:
- The level of judgement required in applying IFRS 16 can affect comparability within the same industry, particularly in determining whether a contract contains a lease, the lease term, and the discount rate.
- Sale-and-leaseback transactions and the interaction with IFRS 15 Revenue from Contracts with Customers.
- Investors are getting the information they need under IFRS 16, which is an improvement on IAS 17 Leases.
Connectivity
11The potential overlaps between IASB Accounting Standards and ISSB Sustainability Disclosure Standards has been considered as part of the development of this PIP. There do not appear to be any significant connectivity implications for the project.
Recommended UKEB project scope
12Based on the proportionality assessment above, the PIP has been developed based on a 'Limited' project scope. The project will:
- Publish a DCL, which will be primarily based a high-level overview of the findings from desk-based research and feedback from initial outreach with stakeholders.
- Include an Invitation to Comment (ITC) accompanying the DCL.
- Allow for a 45-day consultation period on the DCL to mitigate the fact that this period overlaps with interim reporting and summer holidays for a significant number of UK stakeholders.
Project - key activities
| Key activities | Due Process Handbook |
|---|---|
| Board Education Session | 4.10b Optional |
| Creation of a Project Initiation Plan (this document) | 5.4-5.8 Mandatory |
| Desk-based research to support the proportionality assessment including: | 5.9 Optional |
|
|
| Publication of a Draft Comment Letter for public consultation | 5.13-5.17 Generally |
|
mandatory |
| Stakeholder outreach | 5.10-5.12 Mandatory |
|
|
|
|
| Final Comment Letter | 5.18 Mandatory |
| A final comment letter will be prepared for Board approval, submission to the IASB, and publication on the UKEB website. | |
| Project Closure | 5.19-5.26 Mandatory |
| A Feedback Statement and Due Process Compliance Statement will be prepared. Once approved by the Board these documents will be published on the UKEB website. |
Resources allocated
13To undertake the activities described in this project plan, a project team has been assigned consisting of a Project Director, with some oversight from a Senior Project Director. The required resources are allowed for in the 2025/26 UKEB plan and budget.
14In addition, some support from the economics team during the outreach to UK IFRS reporters was allocated.
Setting up an ad-hoc advisory body
15The UKEB will not require a separate ad-hoc advisory body for this project. Existing UKEB advisory groups have the necessary skills and expertise to support this project and have been consulted, as outlined in the project plan.
Project timeline
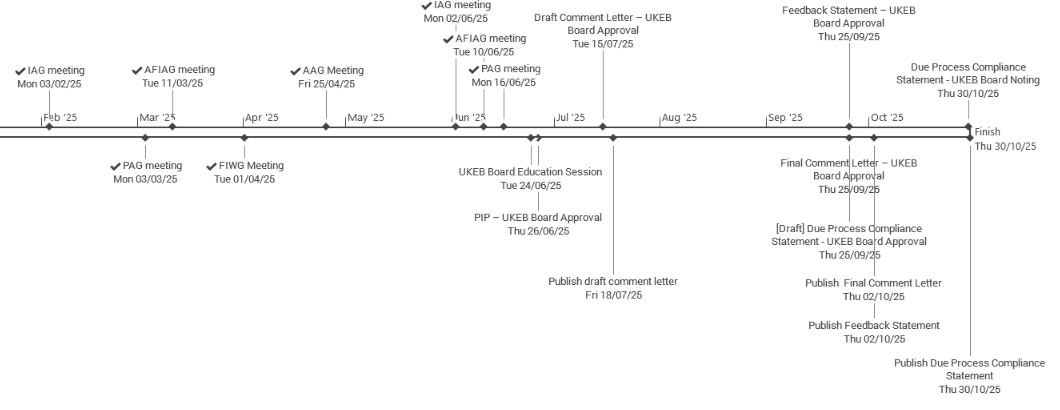
16The proposed high-level project timeline is shown below. This provides a best estimate based on information known at the time of writing. If necessary, a revised PIP will be presented to the Board, to reflect any major changes, as the project progresses.
| Date | Milestones |
|---|---|
| 24 June 2025 | Board Education Session |
| 26 June 2025 | Project Initiation Plan for Board Approval (this document) |
| 15 July 2025 | Draft Comment Letter for Board approval |
| Estimated DCL consultation period (45 days): 18 July 2025 – 1 September 2025* | |
| 25 September 2025 | Board review of Final Comment Letter, Feedback Statement, draft Due Process Compliance Statement |
| By 15 October 2025 | Final Comment Letter submitted to IASB. |
| 30 October 2025 | Due Process Compliance Statement for noting. |
* To be confirmed
Project Initiation Plan: Post-implementation Review of IFRS 16 Leases - Project timeline.
17The diagram below is a graphical view of the mandatory milestone activities described above. This provides a best estimate based on information known at this time. If necessary, a revised PIP will be presented to the Board, to reflect any major changes, as the project progresses