UKEB IFRS 17 Preparer Survey – summary of findings
UKEB September 2020
The views expressed in this presentation not necessarily those of the Endorsement Board, nor are they necessarily reflective of any official policy or position.
- 1. Overview
- 2. Level of Aggregation
- 3. Annual Cohorts
- 4. Risk Adjustment
- 5. Discount Rates
- 6. Presentation
- 7. Transition
- 8. Reinsurance
- 9. Interest accretion on CSM at locked in rate
- 10. Variable fee approach
- 11. With-Profits
- 12. Significance of benefits from IFRS 17
- 13. One-off IFRS 17 implementation costs
- 14. Impact on baseline reporting costs
- 15. Requirements causing ongoing cost increases
- 16. Anticipated significance of commercial impacts
- 17. Competitive impacts (outside UK)
- 18. Non-GAAP MPMs and post transition presentation
1. Overview
12 Groups 4 Individual Entities 10 Listed Companies
Illustration of 16 respondents, broken down into types of insurers.
9 Life Insurers 6 General Insurers 1 Composite Insurer
Implementation challenges:
- Interpretation uncertainty
- Data readiness
- Operational complexity
- Resource availability
- Endorsement uncertainty
Bar chart showing the expected month and year of completion of the implementation programme, with a peak in Jul - Dec 2022.
Majority of respondents are building and testing systems, with only one respondent at the parallel run stage.
* Representing approximately 67% of the total gross written premiums of IFRS reporters in the UK based on their latest set of accounts.
2. Level of Aggregation
81% of respondents will recognise significantly more groups of insurance contracts under IFRS 17 than under current GAAP
Horizontal bar chart showing the extent of support for IFRS 17's requirements regarding the division of portfolios into 'profitability buckets' (IFRS 17.16). 'Neither oppose nor support' has the highest bar, followed by 'Support', then 'Oppose', 'Strongly oppose', and 'Strongly support'.
Favorable comments:
- Supportive of objective to avoid offsetting profitable and onerous contracts
- Promotes a greater understanding of unearned profit upon recognising contracts
Unfavorable comments:
- The nature of the insurance business is the aggregation and sharing of risk so profitability expectations should be set at the portfolio level
- The requirement to divide a portfolio into the profitability buckets does not meet the cost benefit analysis
- Introduces significant cost and complexity
3. Annual Cohorts
"Insurance contracts are fundamentally managed together as a portfolio, as are the assets backing those liabilities. The annual cohort requirement undermines the fundamental business model of insurance."
Bar chart showing responses to the question "To what extent do you support/oppose the annual cohort requirement (IFRS 17.22)?". 'Neither oppose nor support' has the highest bar.
"Enhancing disclosure around profitability of each underwriting cohort enhances transparency"
"The requirement aligns with the underwriting year view of planning and is consistent with the insurance cycle.”
Only 3 of the 9 Life insurers oppose the requirement.
The need for annual cohorts is understood, but at the same time results in additional calculation complexity
4. Risk Adjustment
Pie chart showing estimation techniques entities expect to use for determining risk adjustment for non-financial risk (IFRS 17.B91-92).
Decision tree diagram asking "Does the entity plan to present separately the effect of discounting the risk adjustment or to include it all as part of insurance service result (IFRS 17.81)?". The outcome is 31% to "Include it all in insurance service result" and 69% to "Disaggregate and include part in insurance finance income or expenses".
The estimation technique is not expected to differ by portfolio
5. Discount Rates
| Preferred approaches by product | |
|---|---|
| Bottom up | Top down |
| Protection Business | Annuities |
| With-Profit | |
| General/P&C | |
| Health |
Policy objectives driving the choice of approach:
- Regulatory alignment
- Consistency with current practice
- Operational simplicity
- To minimise accounting volatility that doesn't reflect economics
- To aid explanation of performance
6. Presentation
19% of respondents plan to apply the OCI option.
Rationale:
- it aligns with their IFRS 9 policy (FVOCI) and enables asset and liability matching
- it will reduce volatility
Bar chart illustrating the treatment of accounting estimates in interim financial statements, comparing 'Restatement of interim estimates' (Year-to-date) with 'No restatement of interim estimates' (Period-to-period).
7. Transition
| Average application of transition approaches across respondents | ||
|---|---|---|
| General | Life | |
| Fully retrospective approach | 98% | 54% |
| Modified retrospective approach | 2% | 3% |
| Fair value approach | - | 43% |
Drivers behind policy choice:
- Availability of data and ease of calculation
- Operational complexity
- Alignment of business models within the group
8. Reinsurance
12 out of 16 Respondents were supportive of the requirements to recognise income in P&L on certain RI contracts to cover losses on onerous underlying insurance contracts.
Only one entity anticipates a critical impact on their financial statements from measuring RI contracts under the GMM, but related underlying contracts under PAA.
81% of respondents note that the accounting for intra-group reinsurance arrangements will be more complex or significantly more complex.
- Accounting mismatches will arise on consolidation because the contract will be accounted for differently by the issued entity and held entity
- VFA ineligibility creates accounting mismatches that are difficult to explain in the entity accounts
- Complexity is further increased because internal reinsurance relates to with-profits business
- Reinsurance of unit linked investment contracts is more challenging when accounted for under IFRS 9/IFRS 17 compared to IAS 39/IFRS 4
9. Interest accretion on CSM at locked in rate
83% of respondents agree or strongly agree that accreting interest on the CSM at the current rate would significantly reduce the operational burden.
Bar chart showing the extent of support for or opposition to the requirement to accrete interest on the Contractual Service Margin (CSM) in the General Measurement Model (GMM) at a locked-in rate (IFRS 17.44(b) and B72(b)).
Points noted in favor:
- Principles are clear
- Consistency across methodology
- CSM does not reflect a future cash flow
Points noted against:
- Creates an accounting mismatch (other components of the balance sheet are measured at current rates)
- Operationally complex to track and manage historic discount rates
- Undesirable volatility in financial statements
58% of respondents note that the difference from applying a locked-in vs current discount rate to the CSM is expected to be material.
10. Variable fee approach
Bar chart showing the extent of support for or opposition to the criteria for determining eligibility for the Variable Fee Approach (VFA) (IFRS 17.B101). 'Neither oppose nor support' has the highest bar.
* Of the 9 respondents who provided a response to this question
At what level does the entity expect to determine eligibility for the VFA?
Individual contract/group of contracts/other
40% respondents: Individual contract level
60% respondents: Other
- Operationally impractical to determine at an individual contract level
- Propose to determine eligibility for one representative contract in a group of homogenous contracts
11. With-Profits
The main themes from the responses:
- Accounting treatment will lead to accounting mismatches and unnecessary volatility in results.
- valuation of policies with guaranteed annuity options
- non-profit contracts in a with-profit fund
- Accounting treatment is not consistent with the economics of the businesses or funds:
- Inherited estates – allocation between policyholders and shareholders
- Significant additional disclosure will be needed to explain these products to investors
12. Significance of benefits from IFRS 17
Approximately a third of respondents anticipated some moderate benefits but most stated either negligible or no benefit. Common benefits were noted as consistency of accounting treatment, greater comparability and a better understanding of data.
'The increased disclosure requirements ... should also aid comparability and external confidence in strength of insurer's Balance Sheets.'
Pie chart titled "What benefits do you anticipate will be derived from the application of IFRS 17 compared with current accounting?", showing Negligible (44%), Moderate (31%), None or Not Applicable (24%), and Significant (1%).
'Greater consistency of accounting treatment across the Group resulting in streamlining of processes and use of Group tools'
'... uniformity of reporting for long-term business contracts across products & territories, and the resulting scope for operational simplification.'
'Greater comparability with other insurers, better understanding of data and internal Management Information'
'improving the understanding of the business and industry in anticipation that it will make the industry and company more attractive to investors.'
'Greater insight into financial performance through increased granularity of profitability information'
'We are struggling to envisage any benefits from the standard, which is frustrating as it is a lot of effort and cost to implement'
13. One-off IFRS 17 implementation costs
Aggregate implementation costs were £783m[^1] ranging from £3.5m to £191m[^2]. All but one insurer advised that implementation costs were 1% (or less) of Gross Written Premium (as the average calculated over the last 5 years).
Pie chart showing total expected one-off implementation costs by categories of spend: Technology (23%), Accounting and Reporting (20%), Actuarial (19%), Data Management (13%), External Audit (7%), External Hardware / Software (9%), and Other (9%).
Significant investment has been made in systems development, actuarial and reporting processes and the management of data.
[^1] One survey participant chose not to disclose their implementation costs. There cost was estimated by using a regression model based on their Gross Written Premium to determine an estimated implementation cost. [^2] Some survey participants submitted their costs inclusive of wider finance transformation costs i.e. in addition to directly attributable IFRS 17 implementation costs. Therefore, the total cost may be overstated to an extent.
14. Impact on baseline reporting costs
Most insurers have yet to quantify the impact on 'business as usual'. However, 64% anticipated that costs will increase while 36% saw no material change. This appeared to be due to the associated cost reductions from improvements to systems, process and data quality.
'In the absence of transformation we would expect run-rate costs to increase marginally as a result of increased requirements mostly notably in the actuarial function.'
Pie chart showing entities' expectation of total annual financial reporting costs to increase or decrease as a consequence of adopting IFRS 17, taking 2019 as a baseline. It shows 67% expect an Increase and 33% expect No material change.
'additional operational complexity of the standard will undoubtedly increase internal and external (e.g. audit) costs.'
'although we anticipate no material change, this is in the context of multiple other changes of a transformation nature impacting financial reporting processes in parallel.'
15. Requirements causing ongoing cost increases
| Requirement | Rationale | |
|---|---|---|
| 1 | Disclosures and granularity of reporting | Increased ongoing financial reporting costs from both an internal and external (e.g. audit) perspective. |
| 2 | Data, systems and processes | To achieve the working day timetable, the IFRS 17 solution requires additional data warehousing, processes changes and visualisation tools. In addition to third party licence fees the new process will require more scrutiny and validation of the results. |
| 3 | Eligibility testing | The requirement to assess eligibility for VFA at individual contract level is expected to be significant. |
| 4 | Actuarial models | Discounting and Risk Adjustment require additional actuarial models which need to be maintained going forward. |
| 5 | Locked-in discount rate | The requirement to use a locked-in discount rate for accreting interest and adjusting the CSM under the General Model will result in significant ongoing annual cost and complexity. |
Of those responding on behalf of a group, 45% expect subsidiaries to have to prepare individual entity accounts using policies other than IFRS 17. Of these, all expected that this would lead to both greater differences in accounting between subsidiary and group and increased annual financial reporting costs.
16. Anticipated significance of commercial impacts
Approximately three quarters of respondents believe commercial impacts will be either negligible or have not yet fully assessed them.
Moderate commercial Impacts
Reinsurance strategy
'Impact on IFRS metrics may influence level of reinsurance sought on some products. However, reinsurance strategy will be mostly influenced by regulatory capital impacts ...'
Rating agencies
'It is possible that rating agency models will change, e.g. to reflect changes in leverage arising from IFRS 17 and if they are going to benchmark insurers.'
Hedging strategy
'P&L volatility under IFRS 17 may require additional hedging to be put into place to mitigate the impact of mismatches, taking into account the impact on regulatory capital within the Group'
Pie chart titled "Commercial impacts anticipated compared with current accounting?", showing Negligible (45%), Not Assessed Yet (29%), Moderate (21%), and Significant (5%).
Significant commercial impacts
Mergers and acquisitions
'IFRS 17 will encourage diversified product portfolios and be a potential barrier to entry. This may impact mergers and acquisitions in the insurance industry.'
Product range and design
'As some products will be less attractive as a result, there will be changes to product range and design'
Buy in and Buy outs
'Deferred DB schemes will be less attractive as a product'
17. Competitive impacts (outside UK)
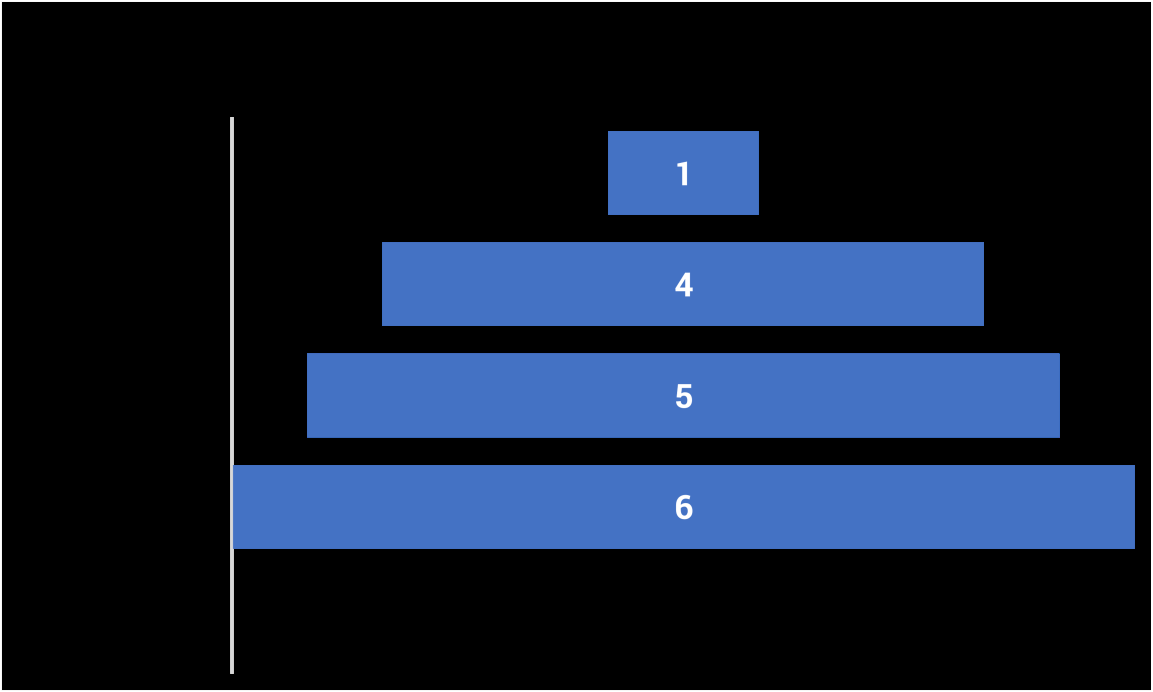
Most respondents perceive this as either negligible or have yet to fully assess the impact on their competitiveness. One participant noted a significant impact (but did not provide rationale) and four a 'moderate' impact - of these three viewed it as a disadvantage.
Moderate Impacts
'expect that more consistent global accounting policies would improve competitiveness. However, we note that IFRS 17 is not required in the US, Switzerland and Japan and it is uncertain how fully China will adopt'
'the standard will have little benefit on the comparability of insurers from outside IFRS reporting areas'
'Due to additional costs (resource, software license fees, and audit) from having to account under two fundamentally different GAAPs.'
Negligible Impacts
'We do not expect any impact on our competitiveness.'
'Competitiveness is likely to be dominated by regulatory constraints.'
'Greater transparency across other insurers based on other countries... Other insurers might not have applied IFRS 17, but there are similar measures out there e.g. US GAAP.'
18. Non-GAAP MPMs and post transition presentation
A third of responders anticipated more MPMs while another third anticipated no change. No responders anticipated fewer MPMs while a third remain undecided on the extent of the change.
MPMs under consideration
- Underlying IFRS operating profit - to explain the impact of accounting mismatches and short term fluctuations.
- Adjusted operating profit metric – may include a reconciliation to existing economic new business metrics.
- Present Value of New Business Premiums
- European Embedded Value (EEV) results
- Additional disclosures to explain sales volumes and to reconcile IFRS 17 measures to other information provided.
- Cost : Income Ratio
- Free surplus generation
- Net client flows
- Assets under Management and or Administration
- Measures on Solvency Position such as Solvency II coverage ratio, capital generation etc.
Pie chart titled "Does the entity expect to present fewer or more non-GAAP Management Performance Measures (MPMs) under IFRS 17 than it does under current accounting?". Shows No Change (38%), Undecided (31%), More (31%), and Fewer (0%).
Post Transition Presentation
'...we anticipate a greater focus on the value of new business value being generated in any year...'
'deferral of income and costs through the CSM will inevitably impact the cost : income ratio therefore an adjusted metric may be required.'
'anticipate having to remove additional accounting mismatches from the result to reflect the economics of the business.'
'We may change our emphasis towards regulatory metrics as they will more clearly reflect dividend capacity although this will depend on final interpretations.'
Most responders anticipate providing additional voluntary disclosure in the notes to enable reconciliation between financial statements and MPMs.
The views expressed in this pack are not necessarily those of the UK Endorsement Board, nor are they necessarily reflective of any official policy or position.
This publication forms part of the UK Endorsement Board's outreach activities in relation to the endorsement of IFRS 17 Insurance Contracts.
Should you be interested in being involved further with the endorsement process, please contact us at: [email protected]