7 Statement of Cashflows and Related Matters – Project Initiation Plan
28 November 2024 Agenda Paper 7
Executive Summary
| Project Type | Research |
|---|---|
| Project Scope | Moderate |
| Purpose of the paper |
The purpose of this paper is for the Board to:
- Consider a research project on the Statement of Cash Flows and Related Matters.
- Consider for approval a proposed Project Initiation Plan (PIP) for a project to research the Statement of Cash Flows and Related Matters.
- Gather preliminary Board member views on the question on this topic expected at the IASB's Accounting Standards Advisory Forum (ASAF) in December 2024.
Summary of the Issue
Project Initiation Plan – Appendix A
- The IASB decided to add a project on the Statement of Cash Flows and Related Matters to its research pipeline. The IASB staff plan to perform initial research to gather evidence of the nature and extent of the perceived deficiencies and the likely benefits of developing new financial reporting requirements for IAS 7 Statement of Cash Flows. This research is intended to provide evidence to support the IASB's decision on the scope of the project.
- In line with the UKEB's regulatory strategy (page 13) to support the IASB in ad hoc, country-specific research to provide effective, early influencing of projects, the Board is asked to consider adding a research project on the Statement of Cash Flows and Related Matters to its work plan. The UKEB can engage with preparers and investors to develop a more comprehensive understanding of what improvements they believe would be most beneficial and achievable.
- In anticipation of approval by the Board to add a project to its work plan, the attached PIP sets out a project plan aimed at developing an understanding of the UK perspectives on the statement of cash flows, including user and preparer views. This would then allow the Board to develop its own views on this topic for inclusion in a discussion paper.
ASAF Discussion
- At ASAF in December 2024, IASB staff will provide an update on their preliminary research, including financial statement analysis and stakeholder feedback.
- They will also seek ASAF members' views on the nature and pervasiveness of the perceived deficiencies in IAS 7 related to the topics reproduced in paragraph A7 below. The input from ASAF members will contribute to the IASB's decision on the scope of the project.
- The IASB staff presentation can be found here
Questions for the Board
Project Initiation Plan
- Does the Board support adding a research project on the Statement of Cash Flows and Related Matters to the UKEB Work Plan?
- Subject to any suggested amendments at the Board meeting, does the Board approve the PIP for this project for publication on the UKEB website?
ASAF Discussion
- Do Board Members have any preliminary views on the perceived deficiencies in IAS 7 identified by the IASB staff?
Recommendation
We recommend the Board support adding a research project examining the Statement of Cash Flows and Related Matters and that it approves the related PIP.
Appendix
Appendix A [Draft] Project Initiation Plan: Statement of Cash Flows and Related.
Appendix A: Project Initiation Plan Exposure Draft Statement of Cash Flows and Related Matters
Purpose
A1The UKEB delegated functions include responsibility for "participating in and contributing to the development of a single set of international accounting standards.” Undertaking pro-active thought leadership activities is key to the UKEB's ability to effectively deliver this statutory function.
A2The UKEB's Terms of Reference (ToR) further explain that with regard to thought leadership, the UKEB shall:
- Lead the UK debate on international accounting standards and reporting.
- Represent UK views in international fora with the aim of influencing debate.
- Engage with accounting and reporting and endorsement and adoption bodies in other jurisdictions, in order to improve influence and understand best practice.
- Proactively participate in the development of new global accounting standards, for example by undertaking research.
A3A project on the statement of cash flows and related matters, as described below, supports the UKEB meeting these responsibilities. It is also consistent with 2024-25 Regulatory Strategy as it supports the UKEB's “aim to influence the IASB early on in its standards development cycle, providing evidence-based recommendations and thought leadership on emerging issues from a UK perspective" (page 8).
Background
A4The IASB decided to add a project on the Statement of Cash Flows and Related Matters to its research pipeline following feedback on its Request for Information: Third Agenda Consultation.
A5Most respondents to the Request for Information recommended the addition of a potential project on cash flows to the IASB's workplan and many of them rated it as high priority. It is notable that most users of financial statements who recommended addition of this topic rated it as high priority.
A6The Board received an update on this project, including an overview of the IASB's research plan in an IASB General Update paper in October 2024.
A7The IASB staff have identified the following topics to explore in this project:
- changing the requirements for classifying cash flows into operating, investing and financing categories;
- specific disaggregation requirements for information about cash flows (for example, separating capital expenditures into maintenance and growth);
- changing the definition of cash and cash equivalents;
- requiring the use of the direct method;
- presentation or disclosure requirements for additional information about the non-cash effects of some transactions;
- presentation or disclosure requirements for information about commonly used cash flow measures (for example, free cash flow); and
- specific requirements for the statement of cash flows for financial institutions.
IASB plan for research to support a decision on project scope
A8The IASB staff plan to perform initial research to gather evidence of the nature and extent of the perceived deficiencies and the likely benefits of developing new financial reporting requirements for IAS 7 Statement of Cash Flows. This research is intended to provide evidence to support the IASB's decision on the scope of the project. The initial research will also address possible ways of improving the perceived deficiencies.
A9The IASB is considering a number of approaches it could take to the project. These include:
- A comprehensive review of IAS 7, which could lead to a new IFRS Accounting Standard.
- A phased project that could make targeted improvements to address some of the issues identified in the short-term, while undertaking a longer-term project to perform a comprehensive review of IAS 7.
- A limited project which would identify and address a few specific areas of concern.
A10Initial research findings are expected to be reported to the IASB in Q1 2025, when the IASB will be asked whether it has enough evidence to decide on the project scope at a subsequent meeting.
Opportunity for the UKEB
A11There is an opportunity for the UKEB to build on the work already done in the UK by the FRC (and others). While there has been research into the problems with the cash flow and possible solutions to these problems, to date direct evidence from preparers and users has been limited. The UKEB can utilise its previous stakeholder engagement experience to seek more comprehensive feedback from preparers and investors.
A12Subject to approval of a Project Initiation Plan, this project would aim to gather primary evidence on key stakeholder views. Specifically, the improvements investors and creditors want made to the statement of cash flows, and preparer views on these possible improvements. This would provide a foundation for the UKEB to propose potential solutions for the problems already identified by the IASB for this project.
A13Research would be grounded in previous work undertaken by the IASB, FRC and UKEB. It will focus primarily on exploring opportunities already identified for improvements to the statement of cash flows and related disclosures, using targeted stakeholder interviews, supported by Advisory Group discussions.
A14IFRS 18 Primary Financial Statements made limited amendments to IAS 7. The UKEB's IFRS 18 surveys sought views on these changes, and these findings, along with additional research will form part of this research.
A15The IASB's current timetable for completion of the research phase of their project means that the work would be more constrained than previous UKEB pro-active research projects. We would also stage the research so that the Board has opportunity to engage with the research more regularly, with a view to incorporating those views into the final published report.
Project Plan
Proportionality assessment
Significance and size
A16The IASB is currently in the research phase of the project, and no decision has yet been made on the IASB's project scope.
Entities affected by the proposals
A17The statement of cash flows is a primary financial statement that all entities are required to prepare. Any changes have the potential to affect all entities that prepare financial statements using IFRS Accounting Standards.
Complexity
A18The requirements of IAS 7 are quite limited. Generally, the statement of cash flows is not considered a complex area of accounting.
A19However, over the past 14 years, the Statement of Cash Flows has been consistently among the top 10 issues identified by the Corporate Reporting review (CRR) team as part of the review of financial statements. In the last four years it has been one of the top three issues every year, resulting in 46 restatements in company accounts.
Expected timeline / urgency
A20The IASB is expected to start making decisions about the scope of the project in 2025. To effectively participate in this discussion, publishing a research report during H1 2025 would be ideally timed to contribute to the IASB process. The September 2025 Accounting Standards Advisory Forum (ASAF) meeting will provide an opportunity to present a summary of the UKEB's research and views on the direction of the project.
Expected interest / sensitivity
A21As noted above, there was a significant response to IASB's Request for Information: Third Agenda Consultation, calling for a project addressing the statement of cash flows. Given the pervasive nature of the statement there will be significant interest in the project.
A22Early discussions with UK stakeholders have indicated significant interest in the project. There are also strong views on what should be prioritised and the extent to which change is feasible.
Feedback on the proposals from desk-based research / initial outreach
A23There has been significant interest in the UK in the statement of cash flows. As part of this proposed project the Secretariat plan to provide the Board with a comprehensive review of the relevant literature. One key element to that literature is work already done by the FRC.
FRC's Improving the Statement of Cash Flows Report - 2016
A24In 2016, the FRC published a discussion paper “Improving the Statement of Cash Flows" for public comment, which focused on the existing IAS 7 Statement of Cash Flows and was timed to feed into the IASB 's Primary Financial Statements project, from which IFRS 18 Presentation and Disclosure in Financial Statements resulted. This was followed in 2017 by a feedback statement of comments received from stakeholders.
A25The discussion paper made a number of recommendations, including:
- Notional cash flows should not be reported in any section of the statement of cash flows. However, transparent disclosure of non-cash transactions should be required.
- Operating activities should be positively defined or described (perhaps as including transactions with customers, employees and suppliers) rather than being a residual or default classification.
- Entities should be encouraged to disclose the extent to which expenditure on property, plant and equipment represents 'maintenance' or 'growth'.
- The statement of cash flows should report inflows and outflows of cash, rather than cash and cash equivalents.
- A reconciliation of profit and cash flow should be presented in all cases (including where a direct method statement of cash flows is presented). The reconciliation should be required to reconcile a sub-total in the statement of profit or loss that represents operating income (rather than, for example, net profit or loss) and reconcile that to cash flow from operating activities.
A26That discussion paper received 22 comment letters, 12 from the UK. Three letters were from preparers and four were from user groups. Some of the highlights from the feedback:
- A large majority of respondents agree that notional cash flows should not be reported in the statement of cash flows although there should be disclosure of non-cash transactions.
- A majority of respondents agree that operating activities be positively defined or described.
- There are split views as to whether the statement of cash flows should report flows of cash or of cash and cash equivalents.
Initial Engagement with UKEB Advisory Groups
A27Early discussions with UKEB Advisory Group (PAG, IAG, and AFIAG) have drawn a mixed response. While all AGs seem content that the key issues have been identified by the IASB, there is no clear consensus yet on how those issues could be best tackled. Focusing on the links between the statement of cash flows and the other primary financial statements, however, was a key theme.
A28There was clear support for the UKEB undertaking further research, in particular for exploring possible approaches to enhance the statement of cash flows. A number of members also expressed an interest in participating in that research.
Connectivity
A29A stakeholder who participated in the Investor Advisory Group indicated a growing interest in specifically identifying "green spending" as part of the Statement of Cash Flows. With increasing focus on disclosure of entities' climate-related risks it is not unreasonable to expect a greater focus on “green cashflows".
A30This is also consistent with expectations of the Bank of England and the Basel committee's Principles for the effective management and supervision of climate-related financial risks. Both of which call for greater measurement, disclosure and monitoring of climate risks, and the important role that accounting plays in this process.
A31The implications for connectivity will be assessed as part of the outreach on the project.
Recommended UKEB project scope
A32Based on the proportionality assessment above we recommend a “moderate scope" project and the approach described in this document reflects this.
A33The UKEB would undertake the following set of activities:
- December 2024: Background paper - This research paper will set the stage, examining the background of the project, relevant research and an examination of previous CRR findings. The paper would include discussion of the relevant recent changes made by IFRS 18. It would also analyse the last 10 years of concerns raised by CRR about cash flows as a specific example of some of the issues encountered by preparers.
- March 2025: Investor and Preparer Perspectives paper – This research paper will summarise user and preparer perspectives on how the Statement of Cash Flows could be improved including consideration of financial institutions. The intention is to conduct around 10 – 12 interviews with a diverse range of users and the same number of preparers of financial statements along with discussion with the IAG (early February) and PAG (early March).
- April 2025: UKEB discussion on its views on scope and approach for the IASB's cash flows project based on research undertaken.
- May 2025: UKEB Perspectives Discussion Paper (Draft) - This paper will outline the UKEB's recommendations for the scope and approach to the cash flow project. It will be accompanied by an invitation to comment and a 90-day comment period (June – August).
- September 2025: UKEB Perspectives Discussion Paper (Final) - UKEB final discussion paper.
A34There is no intention to undertake research collectively with other parties as part of this project.
Project - key activities
| Key activities | Due Process Handbook |
|---|---|
| Identification of issues for research (this document) | 7.15 Mandatory |
| Creation of a Project Initiation Plan (this document) | 7.16-7.21 Mandatory |
Desk-based research to support the proportionality assessment including:
|
7.22 Optional |
| Outreach activities: As described above the UKEB will gather views and opinions from UK stakeholders, particularly users and investors, to contribute to the development of this research. This will include one-to-one interviews and discussions with UKEB Advisory Groups. |
7.23 – 7.24 Optional |
Publication of a Background paper
|
7.25 Mandatory |
Publication of an Investor and Preparer Perspectives paper
|
7.25 Mandatory |
Publication of a Draft UKEB Perspectives Discussion Paper for public consultation
|
7.26-7.28 Mandatory |
| Final UKEB Perspectives Discussion Paper A Final Paper will be created for Board approval, and publication on the UKEB website. |
7.29 & 7.34 Mandatory |
| Project Closure A Feedback Statement and Due Process Compliance Statement will be prepared. Once approved by the Board these documents will be published on the UKEB website. |
7.30 -7.38 Mandatory |
Resources allocated
A35To undertake the activities described in this project plan a project team has been assigned consisting of two Project Directors working with the Project Director – Research Lead. The required resources are allowed for in the 2024/25 UKEB plan and budget.
Project timeline
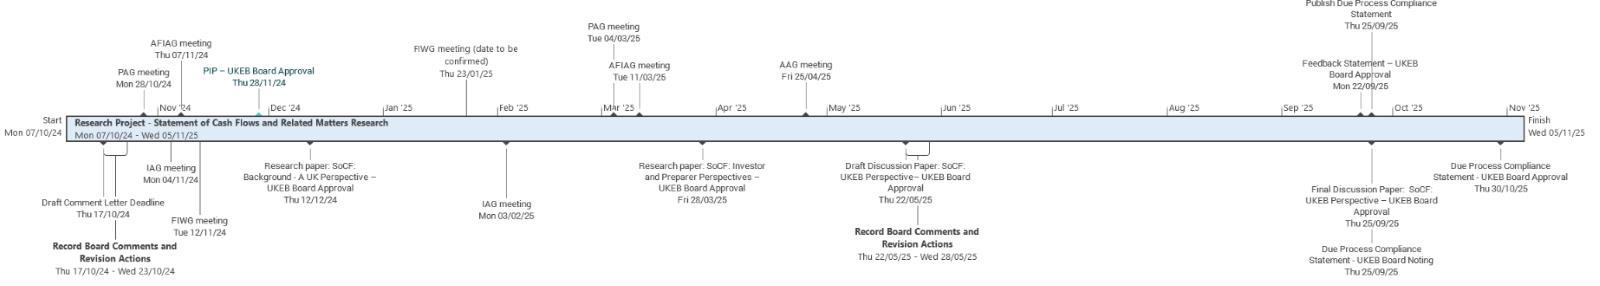
A36The proposed high-level project timeline is shown below. This provides a best estimate based on information known at this time. If necessary, a revised PIP will be presented to the Board, to reflect any major changes, as the project progresses.
| Date | Milestones |
|---|---|
| November 2024 | Project Initiation Plan for Board approval |
| December 2024 | Background paper |
| March 2025 | Investor and Preparer Perspectives paper |
| May 2025 | Draft UKEB Perspectives Discussion Paper for Board approval |
| Estimated draft paper consultation period (not less than 90 days): June– August 2025* | |
| September 2025 | Board review of Final UKEB Perspectives Discussion Paper, Feedback Statement, draft Due Process Compliance Statement |
| September 2025 | Final Comment Letter submitted to IASB (deadline xx month 202x) |
| October 2025 | Due Process Compliance Statement for noting. |
* To be confirmed
Project Initiation Plan: Statement of Cash Flows and Related Matters - Project timeline.
A37The diagram below is a graphical view of the mandatory milestone activities described above. This provides a best estimate based on information known at this time. If necessary, a revised PIP will be presented to the Board, to reflect any major changes, as the project progresses