7.0 Final Report Goodwill research
Project update: goodwill research
Executive Summary
Project Type: Research
Project Scope: Limited scope
Purpose of the paper
This paper presents the final draft of the UKEB's research paper on subsequent measurement of goodwill.
Decisions for the Board
The Board is asked whether:
- subject to the proposed changes set out in Appendix 2 and any comments at the Board meeting, it approves the draft research paper for publication; and
- it has any comments on the high-level promotional plan.
Summary of the Issue
The UKEB undertook a limited scope research project on the subsequent measurement of goodwill. The project's objective is to contribute UKEB thought leadership to the IASB's redeliberations on its Discussion Paper Business Combinations: Disclosures, Goodwill and Impairment and to contribute to the ongoing international debate on goodwill.
Subject to the Board's approval, it is scheduled for publication early during the week beginning 26 September 2022, with the aim that it will be presented later that week at the International Forum for Accounting Standard Setters and the IASB's Accounting Standards Advisory Forum.
The IASB is expected to vote on the subsequent measurement of goodwill in Q4 2022.
Recommendation
That subject to the proposed changes set out in Appendix 2 and any comments at the Board meeting, the Board approves the draft research paper for publication.
Appendices
Appendix 1 Draft research paper Appendix 2 Proposed changes to draft research paper
Background
1The UKEB's research project aims to explore the potential impact for UK stakeholders if the IASB's current impairment-only model for the subsequent measurement of goodwill were to change to a hybrid model. Under a hybrid model for the subsequent measurement of goodwill, impairment testing would be supported by an annual amortisation charge, with context provided by supporting disclosure. The UKEB Secretariat's 2021 response to the IASB's Discussion Paper Business Combinations: Disclosures, Goodwill and Impairment recommended exploring a hybrid model for the subsequent measurement of goodwill.
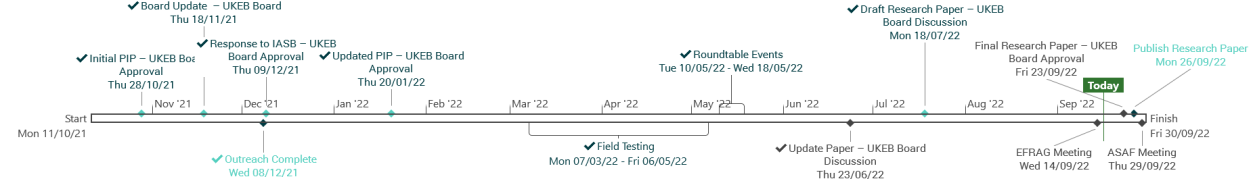
2The Board received a project update at its July 2022 meeting and approved an updated timeline.1 In line with the updated timeline, the draft research paper is brought to the September 2022 meeting for comment, and subject to those comments, approval for publication of the final research paper on 26 September 2022.
3The IASB will vote on the subsequent measurement of goodwill in Q4 2022.
4We were invited to present the draft goodwill research paper at the private EFRAG TEG-CFSS2 meeting on 14 September 2022. The paper was well-received and there was strong engagement during the session. The main comments were:
- The usefulness of the potential disclosures for investors could be given greater emphasis.
- Whilst it is not possible to conclude definitively that goodwill impairments under the current impairment-only model are insufficient, the data on the declining rate of goodwill impairments clearly demonstrates problems with the growth of goodwill.
- Some concerns about retrospective application of the hybrid model to legacy goodwill. The recommendation was that more clarity could be provided that the retrospective application of the hybrid model explored in the paper would not require write-off of all legacy goodwill at the transition date. In fact, it would require write-off of only the amount of goodwill that would have been amortised between the acquisition date and the effective date.
- It would be interesting to explore whether greater proportions of purchase prices have been allocated to goodwill since the introduction of the impairment-only model. If so, whether changes to the current requirements on recognition of intangibles on acquisition, allowing greater recognition of other intangibles, could help to address the problem of growth in goodwill.
- More clarity could be provided on the respective roles of amortisation and impairment testing under the hybrid model explored in the paper.
5We propose some minor changes to the draft research paper to take account of the feedback from the EFRAG TEG-CFSS meeting and to respond to feedback received from board members. The proposed changes are set out in Appendix 2. The draft of the research paper is at Appendix 1 and any changes approved by the Board at this meeting will be incorporated in that draft after the meeting.
Question for the Board
6Subject to the proposed changes in Appendix 2 and any comments at this meeting, does the Board approve the draft research paper for publication?
Proposed high-level promotional plan
7The UKEB has been invited to present the research on subsequent measurement of goodwill at the September 2022 IFASS and ASAF meetings being held during the week commencing 26 September 2022. We note the very limited turnaround time between the UKEB September board meeting on Friday 23 September and the start of the IFASS meeting on Tuesday 27 September 2022.
8The UKEB Secretariat will also promote the publication of the research paper via our usual channels, including:
- The UKEB website, subscriber alert, social media and podcast.
- In partnership with professional bodies and membership associations.
9We will consider whether there are suitable opportunities to ask Advisory Group members to promote the research paper.
Question for the Board
10Does the Board have any comments on the high-level promotional plan?
Next steps
11Subject to comments from the Board at this meeting, the paper will be finalised and published on the UKEB website on 26 September.
Timeline
September 2022
- Project update: goodwill research
- Background
- Proposed high-level promotional plan
- Next steps
- Executive Summary
- 1. Context
- 2 Description of a hybrid model
- 3. Potential implications of moving to a hybrid model
- Introduction
- Effect on financial reporting outcomes
- Feasibility of amortising goodwill under a hybrid model
- Approach to legacy goodwill at the transition date
- Examples of methods used by field test participants to estimate the useful life of goodwill and treatment of legacy goodwill
- Effect on financial stability
- Evidence sources
- Evidence
- Effect on compliance with debt covenants
- Effect on compliance with market regulations
- Effect on tax payments
- Effect on management compensation schemes
- Effect on audit, processes, systems and costs
- Sources of evidence
- Evidence
- Implications for audit, processes and systems
- Implications for costs
- 4 A hybrid model: potential benefits, concerns and solutions
- Anticipated benefits of the hybrid model explored in this paper
- Financial reporting benefits
- Other benefits
- Potential concerns and potential solutions
- Volume of disclosures
- Commercial sensitivity of disclosures
- Potential loss of disclosures required by IAS 36 Impairment of Assets
- Potential increase in number of reconciling items between IFRS totals and subtotals and management performance measures
- 5 Conclusions
- 6 Potential areas for further research
- Appendix A Shielding
- Appendix B Research method
- Appendix C Field test participants
- Appendix D Survey respondents
- Appendix E Outreach events and participants
- Appendix F Glossary
- Appendix G Analysis of age of goodwill
- Appendix 2: suggested amendments to draft Goodwill research report
- Appendix C: Profiles of entities that participated in field testing
- Appendix D: Glossary
- Appendix E: References
Executive Summary
Background
1The UK Endorsement Board (UKEB) is responsible for endorsement and adoption of international accounting standards (issued by the International Accounting Standards Board (IASB) in the form of International Financial Reporting Standards, or IFRS) for use in the United Kingdom (UK). The UKEB is therefore the UK's National Standard Setter for IFRS Accounting Standards.
2As a part of this role, the UKEB has a statutory function3 to participate in, and contribute to, the development of a single set of IFRS Accounting Standards. The UKEB's active research programme complements this statutory function and is aimed at providing evidence-based research that identifies key issues and potential solutions, to be addressed during the development of a standard.
Purpose of this research
3The research was undertaken by the UKEB to better understand the use and impact of the IFRS impairment-only model for subsequent measurement of goodwill by UK-listed companies and the potential implications of a transition to a hybrid model for the subsequent measurement of goodwill.
4Under the hybrid model outlined in this paper and tested in this research, goodwill would be subject to an annual amortisation charge, supplemented by impairment testing would take place only when there was an indicator of impairment.
5The research took place between October 2021 and July 2022.
Context and economic analysis
6Goodwill is a significant asset in the financial statements of a large proportion of the UK's FTSE 3504 companies. 65% (228 companies) of those companies included goodwill as an asset in their 2021 financial statements, with total goodwill of £397 billion, on average representing 18% of total assets and 63% of net assets. Given this prevalence, and the absolute and relative size of goodwill on company balance sheets, its subsequent measurement is an important issue from a UK perspective.
7Whilst the carrying amount of goodwill has increased between 2005 and 2021 by 78% (from £223 billion in 2005 to £397 billion in 2021), the rate of impairment has slowed. The mandatory application of the IFRS impairment-only model for the subsequent measurement of goodwill resulted in UK listed companies in the FTSE 350 charging £150 billion of goodwill impairments between 2005 and 2021, averaging 2.85% of the opening carrying amount of goodwill over that period. The average goodwill impairment of 2.85% of the opening carrying amount of goodwill implies a potential average write-off period of 35 years. The five-year rolling average implied write-off period for goodwill has also increased, from 20 years in 2009 to 51 years in 2021.
8To provide an indication of the age of the goodwill, the 2021 financial statements of seven FTSE 350 companies with high carrying amounts of goodwill were analysed. Undertaking this analysis was challenging as financial statement disclosures were generally insufficient to enable a complete analysis of the age of goodwill. A number of items, including some impairment expenses could not be allocated to years. The limitations of the disclosures made it difficult to draw overall conclusions in relation to the age of the goodwill carried in these companies' 2021 balance sheets, although it was determined that four companies included goodwill arising from pre-2010 acquisitions ranging from 20% to 53% of the 2021 carrying amount.
9Despite the mandatory use of the IFRS impairment-only model since 2005, the subsequent measurement of goodwill also remains the subject of ongoing international debate, with standard setters, preparers, investors and government all participating in that debate in recent years. This debate has highlighted that there is a range of strongly held views and that stakeholders believe there are advantages and disadvantages of both impairment-only and amortisation-based models.
A hybrid model
10The research explored and tested a hybrid model for the subsequent measurement of goodwill. This model would involve:
Goodwill being subject to an annual amortisation charge, supplemented by;
- Impairment testing, only when impairment is indicated; and
- Disclosures to enhance management accountability for acquisitions and the relevance of information for users.
11Amortisation would be based on management's estimate of the remaining useful economic life of goodwill.
12Impairment testing would be conducted only when there is an indication of impairment (indicator-only impairment testing), to reflect the extent to which the carrying amount of goodwill is no longer expected to be recovered. No change from the current IFRS methodology for impairment testing is assumed.
13Disclosures would focus on management's judgements and estimates about the useful life of goodwill and the make-up of the carrying amount of goodwill.
Research and findings
14Research was carried out in two main phases:
- October–December 2021: Exploration of how the useful life of goodwill is determined under UK GAAP and whether a transition to a hybrid model for the subsequent measurement of goodwill would be likely to have a significant impact on financial stability in the UK.
- January–July 2022: Exploration of the feasibility of transition to a hybrid model for subsequent measurement of goodwill for UK IFRS preparers.
15Evidence was collected from a preparer survey, a field test with preparers, and outreach with users, auditors and academics. In addition, a review of the application of UK GAAP provided evidence on how the useful life for goodwill is determined under that reporting regime.
Effect on financial reporting outcomes
16A majority of preparers and some users consider that a hybrid model would provide a more faithful representation of the consumption of economic benefits. They also considered that an annual amortisation charge would mitigate the risk of overstatement of individual goodwill balances.
17Most stakeholders agreed that improved disclosures on the age and make-up of goodwill balances would provide relevant information to users, helping them hold management to account for acquisitions.
Feasibility of amortising goodwill under a hybrid model
Feasibility of estimating a useful life for goodwill
18A majority of preparers considered it would either be easy, or challenging but possible, to estimate a useful life of goodwill for amortisation purposes. A minority of preparers considered it could be practically impossible to estimate a useful life for goodwill.
19Participants in the field test also agreed that the relevant and appropriate factors to be considered when estimating a useful life for goodwill include:
- Legal, regulatory and contractual provisions affecting the useful life of the acquired business.
- Expected timing of realisation of anticipated income and cost synergies.
- Expected useful life of benefits acquired which are not recognised separately from goodwill (e.g., synergies and value of the assembled workforce).
- Expected useful life of assets acquired and recognised under IFRS, such as customer lists and research and development projects recognised on acquisition.
- Period over which an acquired product is expected to be viable in a market.
- Nature of the acquired business.
20Auditors and academics generally concurred with the above factors for estimating a useful life for goodwill. Users generally found the disclosures relating to the factors to be useful.
21A review of the 2020 financial statements of the UK's 100 largest private companies provided information on how the useful life of goodwill is estimated under UK GAAP5. 48 of those companies use FRS 102 The Financial Reporting Standard Applicable in the UK and Republic of Ireland when preparing their financial statements, of which 34 companies reported goodwill. Of the companies reporting goodwill, half estimated a useful life for goodwill greater than 10 years, indicating that the useful life of goodwill can be estimated reliably in these cases. Only one entity estimated a useful life of goodwill greater than 20 years.6
Default periods for the useful life of goodwill
22A majority of preparers from the field test considered that including a maximum or minimum useful life for goodwill would partially negate the anticipated improved financial reporting outcomes of improved relevance and more faithful representation. These preparers preferred that estimates should be specific to each acquisition. A minority of preparers considered that a backstop would be helpful where management is unable to determine the useful life reliably.
Approach to legacy goodwill at the transition date
23A majority of preparers considered that retrospective application of a hybrid model would be easy to achieve. However, they also considered that practical expedients, such as default useful lives for legacy goodwill, would be necessary.
24Section 3 of this report includes examples of methods used by preparers to estimate the useful life of goodwill and the treatment of legacy goodwill.
Effect on financial stability
25The research covered the anticipated effect of a transition to a hybrid model for subsequent measurement of goodwill.
Compliance with debt covenants
26A preparer survey was used to establish whether a transition to a hybrid model for subsequent measurement of goodwill was likely to lead to breaches of debt covenants. Of the 15 respondents to this part of the survey, almost all had debt covenants that used IFRS measures. However, they did not identify an increased risk of failing to meet debt covenants if there were changes to the subsequent measurement of goodwill.
Compliance with market regulations
27Desk-based research and the preparer survey did not identify an increased risk of failing to meet market regulations if there were changes to the subsequent measurement of goodwill.
Tax payments
28Desk-based research found that UK companies' corporation tax liabilities are calculated at individual company level, whereas amortisation of goodwill arising on acquisitions of legal entities arises usually only in consolidated financial statements7. Consequently, it does not seem that there will be an impact on tax payments from a change to the subsequent measurement of goodwill.
Management compensation schemes
29A preparer survey asked whether a transition to a hybrid model for subsequent measurement of goodwill was likely to impact management compensation schemes. Some respondents considered that a change to a hybrid model for subsequent measurement of goodwill could affect management compensation schemes. However, remuneration committees typically discuss and agree any necessary adjustments to IFRS-based performance measures in management compensation schemes in the event of changes to IFRS. Consequently, the effect on management compensation schemes is unlikely to be unexpected by management.
Effect on audit, processes, systems and costs
30A majority of respondents from the survey considered that they would not anticipate significant operational changes if they were to transition to a hybrid model for the subsequent measurement of goodwill. However, a minority of respondents expected significant operational changes required for such a change. These respondents identified significant changes in the following areas: processes and procedures, audit, data, staff training, systems and technology.
31Almost half of preparers from the survey considered there would be a minor increase in costs, while a minority expected there would be a significant increase in costs. Over a third of preparers from the survey expected a reduction or minimal or no impact on cost.
Benefits, concerns and solutions
Anticipated benefits of a hybrid model explored in this paper
32The majority of field test participants considered that amortisation of goodwill would provide a more faithful representation of profitability and asset values by reflecting the consumption of economic benefits. Consequently, this would reduce the risk that:
- goodwill continues to be reported at cost in the statement of financial position when its benefits have already been consumed; and
- goodwill is overstated through shielding.
33Disclosure of goodwill by age and make-up, and of management's assumptions for the estimate of useful life of goodwill, would support investors in holding management to account for acquisitions.
Potential concerns
34Preparers raised concerns relating to the commercial sensitivity of some disclosures. This could be addressed by providing a commercial sensitivity exemption.
35Potential concerns raised about increased volume of disclosure could be addressed through limiting disclosures to a subset of acquisitions (proposals under consideration by the IASB at the time of writing).
36Overall, these concerns do not appear to outweigh the benefits arising from the hybrid model for subsequent measurement of goodwill explored in this paper.
Conclusions
37The evidence from UK listed companies' financial reporting points to the need for reconsideration of the current impairment-only model for subsequent measurement of goodwill under IFRS because:
- Despite nearly two decades of experience of implementing an impairment-only model under IFRS, the debate on subsequent measurement of goodwill continues.
- Goodwill for FTSE 350 entities represents approximately 18% of total assets and 63% of net assets for the 228 FTSE 350 companies reporting goodwill in 2021.
- Whilst the carrying amount of goodwill for the FTSE 350 has increased from £223 billion in 2005 to £397 billion in 2021, the rate of goodwill impairment has slowed.
- Under the current impairment-only model for goodwill, disclosure does not help investors in holding management to account for acquisitions, because it is extremely difficult to analyse the carrying amount of goodwill by age and acquisition.
38The UKEB research demonstrated that a transition to a hybrid model would be feasible as:
- The majority of preparers involved in the research believe it is possible to estimate a useful life for goodwill through consideration of a range of relevant factors and if sufficient application guidance is provided.
- A similar model works effectively under UK GAAP.
- Suitable transition arrangements could be provided for legacy goodwill.
- There do not appear to be significant adverse consequences for financial stability or for operations and costs from a transition to a hybrid model.
1. Context
1.1The UKEB researched the potential implications of a transition to an amortisation and impairment model for the subsequent measurement of goodwill. The research took place from October 2021 to July 2022. The research is intended to contribute to the ongoing debate about the most appropriate way to account for recognised goodwill.
1.2Goodwill is a significant asset in the financial statements of many UK companies, totalling £397 billion8 for FTSE 3509 entities in 2021 and representing on average 18% of total assets for those FTSE 350 entities reporting goodwill in 2021.
1.3This section provides background information on the prevalence and size of goodwill in the FTSE 350 and on the application of the current impairment-only model in the UK since 2005.
Prevalence and size of goodwill in the FTSE 350
1.4Goodwill is a significant asset in the financial statements of a large proportion of the UK's FTSE 350 companies. 65% of the FTSE 350 companies (228 companies) included goodwill as an asset in their 2021 financial statements. These 228 companies had a combined market capitalisation of £2.4 trillion, representing 86% of FTSE 350 total market capitalisation.
1.5Goodwill is significant, both in absolute terms and as a proportion of balance sheet value for the FTSE 350 companies that reported a goodwill asset for financial years ended in 2021. For those entities, goodwill totalled £397 billion and represented on average 18% of total assets and 63% of net assets.10
1.6UK listed companies were first required to produce financial statements in accordance with IFRS in 2005.11 Since then, the carrying amount of goodwill for the
The UKEB does not accept any liability to any party for any loss, damage or costs howsoever arising, whether directly or indirectly, whether in contract, tort or otherwise from any action or decision taken (or not taken) as a result of any person relying on or otherwise using this document or arising from any omission from it.
© 2022 All Rights Reserved
1.1The UKEB researched the potential implications of a transition to an amortisation and impairment model for the subsequent measurement of goodwill. The research took place from October 2021 to July 2022. The research is intended to contribute to the ongoing debate about the most appropriate way to account for recognised goodwill.
1.2Goodwill is a significant asset in the financial statements of many UK companies, totalling £397 billion for FTSE 35013 entities in 2021 and representing on average 18% of total assets for those FTSE 350 entities reporting goodwill in 2021.
1.3This section provides background information on the prevalence and size of goodwill in the FTSE 350 and on the application of the current impairment-only model in the UK since 2005.
Prevalence and size of goodwill in the FTSE 350
1.4Goodwill is a significant asset in the financial statements of a large proportion of the UK's FTSE 350 companies. 65% of the FTSE 350 companies (228 companies) included goodwill as an asset in their 2021 financial statements. These 228 companies had a combined market capitalisation of £2.4 trillion, representing 86% of FTSE 350 total market capitalisation.
1.5Goodwill is significant, both in absolute terms and as a proportion of balance sheet value for the FTSE 350 companies that reported a goodwill asset for financial years ended in 2021. For those entities, goodwill totalled £397 billion and represented on average 18% of total assets and 63% of net assets.14
1.6UK listed companies were first required to produce financial statements in accordance with IFRS in 2005.15 Since then, the carrying amount of goodwill for the FTSE 350 has increased by 78% from £223 billion to £397 billion.16 The carrying amount of goodwill has remained broadly constant as a proportion of total assets for those entities reporting goodwill during that period, at approximately 18%.
1.7There are mixed views on the level of merger and acquisition activity anticipated in the UK over the short and medium term17, with those predicting an economic slowdown expecting a reduction in deal rates. As a consequence, the rate of growth in goodwill may lag that of other assets. However, currently deal activity remains strong in some sectors with a high price-to-book ratio18, so that a significant proportion of deal price may in some cases be recognised as goodwill.19 Those sectors include telecommunications, pharmaceuticals and biosciences, media and software and are expected to be significant contributors to future UK economic growth. It seems unlikely, therefore, that the prevalence or absolute or relative size of goodwill will decline in the short or medium term.
1.8The subsequent measurement of goodwill is an important issue for UK stakeholders given its prevalence, its absolute and relative size compared to company total assets and net assets, and its potential continued growth.
Ongoing debate on subsequent measurement of goodwill
1.9The subsequent measurement of goodwill has long been a matter of debate. In recent decades, the debate has focused on the relative merits of two subsequent measurement models. These are the amortisation-based model and the impairment-only model.
1.10A comprehensive analysis of the arguments for and against each model is outside the scope of this paper. To provide context however, the main conceptual arguments for and against each model are set out in figure 1.
Figure 1
| Model | For | Against |
|---|---|---|
| Amortisation-based | Goodwill is a wasting asset whose benefits are consumed over time. | Estimating a useful life for goodwill is judgmental. |
| Amortisation reflects the underlying economics, i.e., the consumption of benefits. | A default useful life does not provide useful information to users. | |
| Impairment-only | Impairments provide relevant information on the subsequent performance of acquisitions. | The shielding effect20 increases the risk of overstatement of goodwill. |
| Impairment provides information that is potentially useful in holding management to account for acquisitions. | Management optimism increases the risk of overstatement of goodwill. | |
| Consequently, goodwill impairments are reported infrequently and when they are reported the information value is limited as the market has often already reflected the bad news. |
1.11The lack of consensus amongst the standard setting community on the most appropriate model for the subsequent measurement of goodwill has been evident over the past few decades. For example:
- The reporting requirements for subsequent measurement of goodwill under UK GAAP, US GAAP and IFRS have, at various stages, included amortisation-based and impairment-only models.
- The financial reporting regime for subsequent measurement of goodwill changed three times for listed companies in the UK between 1984 and 2005.
- US GAAP's current impairment-only model has required seven Accounting Standards Updates21 and the topic recently featured on the FASB's agenda22.
- Despite over 18 years of experience of an impairment-only model under IFRS, the ongoing international debate on subsequent measurement of goodwill does not appear to have abated. The topic currently features on the IASB's agenda.
Application of the impairment-only model in the UK (2005-2021)
Value and concentration of goodwill impairments
1.12On average each year over the seventeen-year period from 2005 to 2021, approximately 225 of FTSE 350 companies reported goodwill as an asset.
1.13Total goodwill impairments recognised by FTSE 350 companies over the seventeen-year period from 2005 to 2021 were approximately £150 billion. During that period, the average annual goodwill impairment expense for the FTSE 350 was £8.8 billion,23 with the highest goodwill impairment expense for any given year at £15.8 billion (in 2019), and the lowest at £1.2 billion (in 2006).
1.14On average from 2005 to 2021, goodwill impairments represent 2.85% of the opening carrying amount of goodwill for FTSE 350 companies. This implies that under the impairment-only model, at the average rate of goodwill impairment recognised by FTSE 350 companies over the last seventeen years, it would take an average of 35 years for goodwill to be written off.
1.15The implied write-off period for goodwill has generally increased over the seventeen years, as shown in figure 2.24 The upward trend is shown by the five-year rolling average implied write-off period which increases from 20 years in 2009 to 51 years in 2021.25 The reasons for the growth in the implied write-off period are unclear.
Figure 2 Five year rolling average implied write-off period of goodwill
Five year rolling average implied write-off period of goodwill. The chart shows the implied write-off period in years from 2008 to 2022, with values ranging from 20 years (2008, 2010) to 52 years (2018) and ending at 51 years (2022).
1.16Of the £150 billion total goodwill impairments recognised by FTSE 350 entities from 2005 to 2021:
- £120 billion, or 80% of goodwill impairments by value, was reported by 12 entities (5% of the 225 entities reporting goodwill as an asset).
- £30 billion, or 20% of goodwill impairments by value, was reported by 157 entities (70% of the 225 entities reporting goodwill as an asset).
- 56 entities (25% of the 225 entities reporting goodwill as an asset) reported no goodwill impairments.
1.17If impairments have not been charged on the grounds that subsequent expenditure maintains the value of goodwill, the consumption of benefit of the original goodwill asset arising on acquisition may not necessarily be reflected in the carrying amount of goodwill.
Frequency and concentration of goodwill impairments
1.18776 goodwill impairments were recognised by FTSE 350 entities between 2005 and 2021. Of the 225 companies reporting goodwill over the seventeen-year period:
- 40% (88 companies) reported 80% of goodwill impairments by number (621 impairments).
- 35% (81 companies) reported 20% of goodwill impairments by number (155 impairments.
- 25% (56 entities) reported no goodwill impairments.
Frequency and size of losses on disposal of businesses
1.19According to the UK Regulator26 it is not unusual for entities to report large losses on disposal of businesses. This may provide some evidence that goodwill may be being sheltered from impairment as it is part of a larger CGU.
Age profile of goodwill
1.20Because of changes to the financial reporting regime for subsequent measurement of goodwill for UK companies in recent decades, the 2021 carrying amount of goodwill could include amounts originally measured on different bases and dating back to before 2005. Any such amounts would have been at least 17 years old when reported in 2021.
1.21Figure 3 illustrates the changes in the financial reporting regime for subsequent measurement of goodwill for UK companies and these are explained further in the following paragraphs.
Figure 3
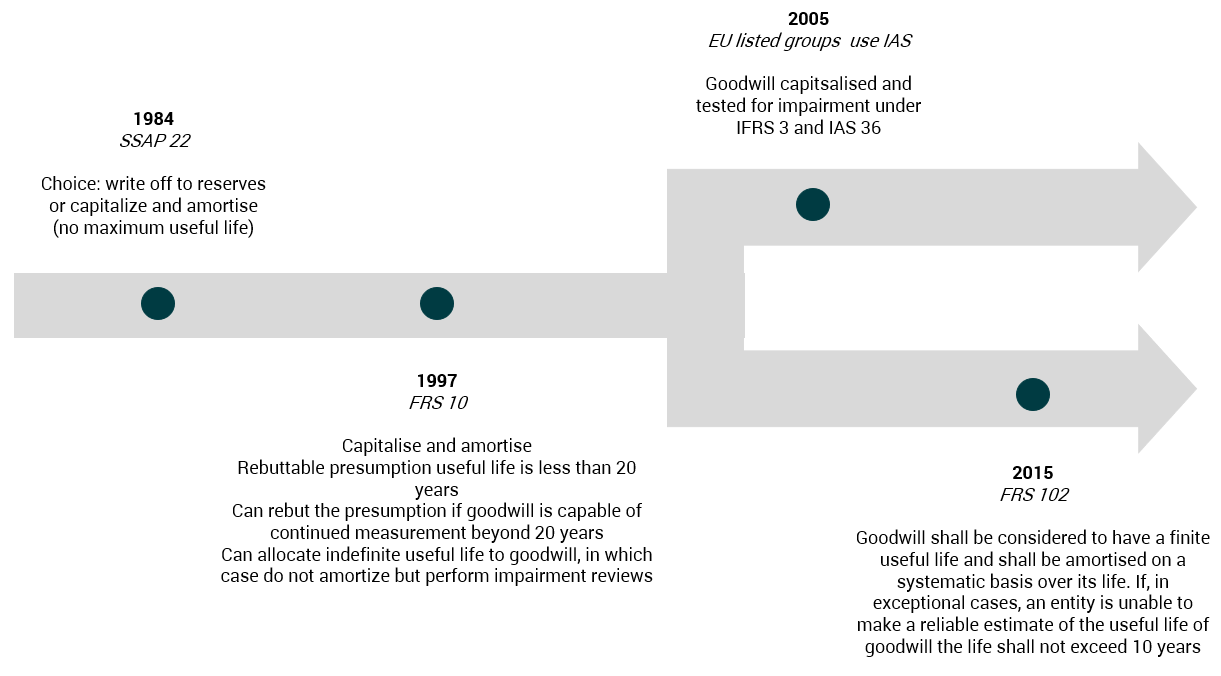
1.22On transition to IFRS for financial years starting on or after 1 January 2005, companies were given the choice between full retrospective application of IFRS 3 Business Combinations and IAS 36 Impairment of Assets, or an optional exemption to carry forward existing goodwill balances on a net basis where those balances had previously been amortised. Given the changes in UK financial reporting regimes for subsequent measurement of goodwill from 1985 to 2004, it is therefore possible that UK IFRS reporters' current goodwill balances include amounts:
- Capitalised and amortised under FRS 10 Goodwill and Intangible Assets27. Goodwill arising on acquisitions between 1998 and 2004 may have been partly or fully amortised before IFRS became mandatory for UK listed companies in 2005. The net carrying amount of partly amortised goodwill could be included in the 2021 carrying amount of goodwill.
- Capitalised and subject to an annual impairment review under FRS 10 between 1998 and 2004. FRS 10 permitted goodwill to be treated as an indefinite life asset, subject to an annual impairment review, so goodwill arising on acquisitions between 1998 and 2004 could be included in the 2021 carrying amount of goodwill at its gross cost on initial recognition or at a partially impaired amount.
- Capitalised and amortised under SSAP 22 Accounting for Goodwill28. SSAP 22 did not stipulate a maximum useful life for goodwill, so goodwill arising on acquisitions between 1985 and 1997 may have been partly or fully amortised when FRS 10 was introduced. Partly-amortised goodwill balances may then have been carried forward under FRS 10 until IFRS became mandatory for UK listed companies in 2005, and so could be included in the 2021 carrying amount of goodwill.
- Written off directly to equity reserves under SSAP 22 between 1985 and 1997. SSAP 22 permitted a choice of methods for accounting for goodwill and write off to equity reserves was used by many companies. On transition to FRS 10, companies had the option to leave goodwill as a write off to reserves until the relevant business was disposed of, or to capitalize it at cost less accumulated amortisation and impairments attributed to previous periods. If a company had elected to reinstate goodwill as an asset, amounts could be included in the 2021 carrying amount of goodwill.
1.23To obtain indicative information on the age of the carrying amount of goodwill in the 2021 financial statements of FTSE 350 companies, the UKEB analysed the individual financial statements of seven FTSE 350 companies for the period from 2005 to 2021. These companies were chosen because of the high carrying amount of goodwill in their financial statements.
1.24The method adopted was to allocate changes in the carrying amount of goodwill to the year of acquisition of the related goodwill to determine the age of the goodwill carried in the 2021 balance sheet.
1.25In undertaking this analysis the UKEB encountered significant challenges. Disclosures were generally insufficient to enable a complete analysis of the age of goodwill to be performed. The analysis therefore contains a number of items that could not be allocated to years, including some impairment expenses and movements relating to disposals and transfers to 'held for sale'.
1.26A particular limitation of the analysis relates to foreign exchange movements. Exchange movements arise from the subsequent accounting for subsidiaries acquired in a currency other than the functional currency of the group. All seven companies had exchange movements but disclosures were insufficient to enable allocation to specific acquisitions. In some cases the cumulative foreign exchange amounts were material to the 2021 carrying amount of goodwill (ranging from 1% to minus 71%).29
1.27The limitations of the analysis make it difficult to draw overall conclusions in relation to the age of the goodwill carried in these companies' 2021 balance sheets. However:
- For the four companies for which the unallocated items were smaller than 10% of the 2021 carrying amount, goodwill arising pre-2010 ranged from 20% to 53% of the 2021 carrying amount.
- For one company, 144% of the 2021 net carrying amount of goodwill appears to relate to 2004 and earlier. This is over 100% due to unallocated foreign exchange movements (minus 71%).
- By contrast, for three companies, 61%-86% of the 2021 net carrying amount of goodwill appears to relate to acquisitions in the period 2015-2019.
1.28The review was complex and time-consuming because current IFRS disclosure requirements do not require an analysis of the carrying amount of goodwill by age or by acquisition, or the acquisition to which impairments relate. There is therefore limited information to support users of financial statements in enhancing management accountability for an asset which represents a material proportion of total assets and net assets for the majority of FTSE 350 entities.
Responsiveness of goodwill impairments to economic conditions
1.29Figure 4 shows the total annual goodwill impairment charges for FTSE 350 companies from 2005 to 2021.
Figure 4
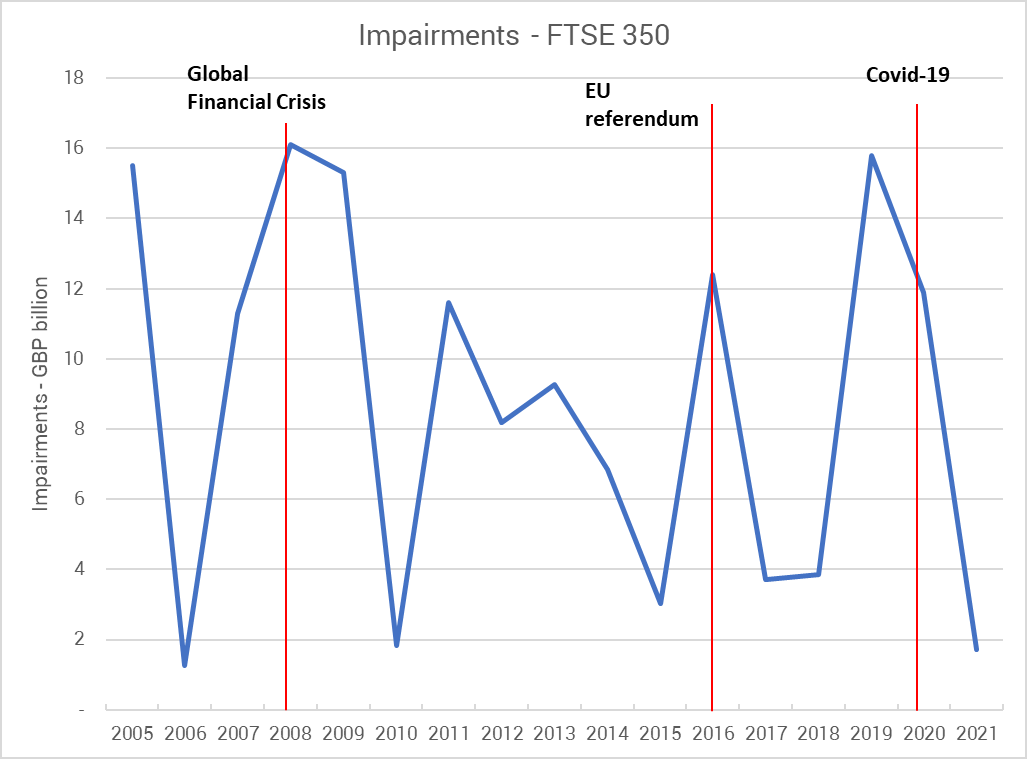
1.30Figure 4 indicates some correlation between increases in the value of total impairments and periods of significant economic uncertainty.
2008 global financial crisis
1.31In 2008, goodwill impairment charges for the FTSE 350 totalled £16.1 billion, the highest level during the seventeen-year period.
- The high absolute level of the total impairment was caused primarily by an increase in the value of impairments rather by an increase in the number of companies making impairments.
- Whilst total goodwill impairment charges in that year are higher than in most other years over the seventeen-year period, they represent only 7% of the opening carrying amount of goodwill.
- Further, the impairments charged in 2008 were not concentrated in a particular sector. Only one bank charged a goodwill impairment in 2008.
2016 EU Referendum
1.322016 saw the highest number of entities reporting goodwill impairments during the period. 76 companies reported goodwill impairments in 2016, compared to an annual average of 46 companies. Impairments totalled £12.4 billion (5% of opening goodwill) and no significant concentration by sector was observable.
2020 Covid-19 pandemic
1.33Goodwill impairments of £11.8 billion were charged by the FTSE 350 during 2020, compared to an average of £8.8 billion over the seventeen-year period. 64 companies reported goodwill impairments, compared to an average of 46 companies. There was an increased frequency of impairments in the travel and retail sectors during 2020 in comparison to other years in the period.
Other factors
1.34However, the high level of total impairments in 2005, 2009 and 2019 indicates that general economic conditions are only one factor driving impairments. Further, the total amount of goodwill impairments for the FTSE 350 in any one year can be sensitive to large individual impairments. For example, total goodwill impairment charges in 2009 were £15.3 billion, the fourth highest year during the seventeen-year period. While this might suggest a further response to the global financial crisis, £12.2 billion, or 80%, arose on a single impairment by an entity in the telecommunications sector, a sector not expected to be particularly sensitive to the global financial crisis.
1.35Total goodwill impairment charges were at their second highest in the seventeen years in 2019 at £15.8 billion, which might suggest a response to the UK's exit from the European Union or an early response to the COVID-19 pandemic, but £10.2 billion or 65% of the total 2019 goodwill impairment charge arose from two large impairments which do not appear to be directly related to the UK's exit from the European Union or to the COVID-19 pandemic.30
1.36Given this context, the impairment- only model does not appear to have consistently resulted in comparable, decision useful information. Alternative models merit further consideration and this research contributes to the ongoing debate by exploring the feasibility of a transition to a hybrid model.
2 Description of a hybrid model
A hybrid model
2.1This section describes the hybrid model used in the field test in this research. It was a prototype to explore the feasibility of a move to a hybrid model. More comprehensive development would be needed should a standard mandating a hybrid model be developed.
2.2Under the hybrid model used in the field test during this research:
Goodwill would be subject to an annual amortisation charge based on an estimate of its useful life determined by management; supplemented by
- Impairment testing only when impairment is indicated; and
- Disclosures to enhance management accountability for acquisitions and the relevance of information for users focusing on:
- management's judgements and estimates about the useful life of goodwill; and
- the make-up of the carrying amount of goodwill.
2.3Further details of the approach to amortisation, impairment and disclosures used in the field test of the hybrid model explored in this paper are set out below.
Amortisation
2.4In the field test, entities were required to amortise goodwill, based on management's estimate of its remaining useful economic life. Consequently, when relevant, amortisation included the identification of significant components of goodwill. Amortisation methods could be straight-line or other bases that reflected the pattern in which its service potential is consumed.
2.5The hybrid model applied in the field test did not set a minimum or maximum useful life of goodwill, nor did it include a rebuttable presumption31 regarding that useful life.32
2.6Entities participating in the field test identified relevant factors to consider when estimating the useful life of goodwill. Participants were provided with a list of potential factors to consider. The field test briefing pack specified that since the list was not intended to be comprehensive, factors to consider in estimating amortisation should not be limited to those included in it.
2.7The list included in the field test pack is set out below33:
- The nature of the acquired business.
- The expected useful life of identifiable assets acquired and recognised under IFRS.
- The expected useful life of benefits acquired which IFRS does not recognise separately from goodwill (e.g., assembled workforce, synergies).
- The expected timing of the realisation of anticipated income synergies.
- The expected timing of the realisation of anticipated cost synergies.
- Legal, regulatory or contractual provisions that may affect the useful life of the benefits expected from the acquisition.
- The anticipated effect of diversified business operations on future consolidated cash flows.
- The anticipated effect of acquiring an entity in a defensive acquisition.
- The period over which an acquired product is expected to be viable in a market.
- The amount of time it would have taken to develop in-house the technology, customer base or other value acquired through the business combination.
- The period over which the acquired entity, on a standalone basis, is expected to maintain higher future net cash flows than competitors.
- The price:earnings ratio implied by the purchase price.
Indicator-only impairment testing
2.8Under the hybrid model explored in the field test in this research, impairment testing only when there is an indication of impairment (indicator-only impairment testing) would be used to reflect the extent to which the carrying amount of goodwill is no longer expected to be recovered.
2.9Indicator-only impairment testing is mandated in IAS 36 Impairment of Assets for all non-financial assets apart from goodwill, intangible assets not yet available for use and indefinite-life intangible assets. Therefore, the existing requirements and methodology in IAS 36 could be leveraged for indicator-only impairment testing of goodwill. IAS 36 states that "an entity shall assess at the end of each reporting period whether there is any indication that an asset may be impaired. If any such indication exists, the entity shall estimate the recoverable amount of the asset.” The Standard provides further guidance on the external and internal sources of information ('indicators') an entity should consider when deciding whether an impairment test is needed.34
2.10The field test assumed that goodwill would be allocated to cash-generating units before indicators of impairment were considered. The field test assumed that the method for allocating goodwill to cash-generating units and testing the cash-generating unit for impairment would be the same as currently set out in IAS 36.35 The field test also assumed that where an impairment test of goodwill was performed, the same disclosures would be required as are currently required by IAS 36.36 In addition, the field test assumed that a full impairment test would be required if the aggregation of assets for identifying the cash-generating unit has changed since the previous estimate of the cash-generating unit's recoverable period.
Disclosures
2.11Current disclosure requirements do not require an analysis of the carrying amount of goodwill by acquisition or age. In addition to existing disclosure requirements for acquisitions in IFRS 3 paragraph B6437 and any disclosures that are currently under discussion by the IASB, the hybrid model field tested in this research required participants to disclose the following that would be specific to goodwill38:
- For each acquisition, or group of acquisitions with similar characteristics, management's estimate of the useful life of goodwill and the assumptions underpinning the estimate, including:
- Identification and explanation of the factors considered in estimating a useful life of goodwill and, where relevant, how a weighting was assigned to each factor;
- If goodwill was analysed into components, the value ascribed to each component and the factors considered and assumptions made in estimating a useful life for that component.
- An analysis of total goodwill in a single table, disclosing separately for each business combination39, or for groups of business combinations with similar characteristics:
- Gross goodwill.
- Acquisition date.
- Accumulated amortisation at the start of the most recent reporting period.
- Accumulated impairments at the start of the most recent reporting period.
- Impairments expensed during the most recent reporting period.
- Amortisation expensed in the most recent reporting period.
- Opening carrying amount at the start of the most recent reporting period.
- Closing carrying amount at the end of the most recent reporting period.
- Total amortisation charged during the financial period, the line(s) in the statement of profit or loss where it is included, and the amount included in each line.
Example disclosure
2.12The following example illustrates the types of disclosures that field test participants considered would be useful under the hybrid model explored in this paper.
| Subsidiaries | A | B | C | D | E | Total40 |
|---|---|---|---|---|---|---|
| Acquisition date | 2002 | 2006 | 2007 | 2019 | 2021 | |
| Gross carrying amount | £m | £m | £m | £m | £m | £m |
| At 1 January 2021 | 2,460 | 492 | 7,965 | 270 | 11,187 | |
| Additions | - | - | - | - | 14,196 | 14,196 |
| Disposals | - | - | - | - | - | - |
| Gross carrying amount | ||||||
| 31 December 2021 | 2,460 | 492 | 7,965 | 270 | 14,196 | 25,383 |
| Accumulated amortisation | ||||||
| At 1 January 2021 | 2,376 | 488 | 5,486 | 48 | 8,398 | |
| Amortisation charge for the year | 84 | 3 | 378 | 48 | 593 | 1,106 |
| Impairment charge | - | - | - | - | - | - |
| Accumulated amortisation | ||||||
| 31 December 2021 | 2,460 | 491 | 5,864 | 96 | 593 | 9,504 |
| Net carrying amount | - | 1 | 2,101 | 174 | 13,603 | 15,879 |
| 31 December 2021 | ||||||
| Net carrying amount | 84 | 4 | 2,479 | 222 | - | 2,789 |
| 31 December 2020 |
Extract - Entity A
When determining the consideration the group was willing to pay for the company being acquired, the group identified revenue and cost synergies it expected to achieve through the business combination. These included, but are not limited to, shared maintenance, operations and procurement.
Synergies arising upon the acquisition of subsidiaries are initially recognised at fair value at the date of acquisition and then amortised over the period that synergies were expected to be generated in the business case for the acquisition (x years).
Assembled workforce arising on the acquisition of a subsidiary is initially valued at fair value on the acquisition date and amortised over the period of expected staff turnover within that subsidiary (x years).
2.13The proposed hybrid model outlined above was tested as part of the UKEB's research work, aimed at understanding the potential implications of a transition to a hybrid model for subsequent measurement of goodwill. The results of that research work are set out in Section 3 ‘Potential implications of moving to a hybrid model'.
3. Potential implications of moving to a hybrid model
Introduction
3.1This section summarises the UKEB's research on the potential implications of a transition to a hybrid model for subsequent measurement of goodwill. The research was undertaken in two phases.
3.2Phase one took place from October 2021 to December 2021. Phase one explored how the useful life of goodwill is determined under UK GAAP and whether a transition to a hybrid model for subsequent measurement of goodwill would be likely to have a significant impact on financial stability in the UK. Phase one showed that a range of relevant factors is considered in estimating the useful life of goodwill under UK GAAP, and that a transition to a hybrid model for subsequent measurement of goodwill would be unlikely to have a significant impact on financial stability in the UK. Research methods used in phase one were a preparer survey, a review of the application of the UK GAAP hybrid model, and other desk-based research.
3.3Phase two took place from January 2022 to July 2022 and built on the conclusions from phase one. Phase two explored the feasibility of a transition to a hybrid model for subsequent measurement of goodwill for UK IFRS preparers, focusing on anticipated financial reporting outcomes, the feasibility of estimating a useful life of goodwill, options on transition, and anticipated effects on audit, processes, systems and costs. Research methods used in phase two were an analysis of FTSE 350 data and financial statements, and a field test completed with UK IFRS preparers, followed by roundtables and one-to-one meetings with users, auditors and academics at which the results of the field test were shared.
3.4The four areas addressed during the research and the methods used to gather evidence for each area were:
- Effect on financial reporting outcomes – including stakeholder views on accountability, faithful representation, relevance and comparability. The evidence was gathered through field-testing with preparers and meetings with auditors, academics and users of accounts.
- Feasibility of amortising goodwill under a hybrid model – including the feasibility of estimating a useful life of goodwill, the factors considered when estimating a useful life of goodwill, and approach to legacy goodwill. The impact of transition was also considered. Evidence was gathered through a review of the application of the hybrid model under UK GAAP, field-testing with preparers, and meetings with auditors, academics and users of accounts.
- Effect on financial stability – including the potential impact on loan covenants, compliance with market regulation, tax revenues and management compensation schemes. Evidence was gathered through a preparer survey and desk-based research.
- Effect on audit, processes, systems and costs – evidence was gathered through a preparer survey, field test and meetings with auditors.
3.5Further information on the research methodology is set out in Appendix B.
Effect on financial reporting outcomes
Evidence sources
3.6Evidence from field tests with preparers, roundtables with auditors and academics, and meetings with users of accounts supported the analysis of the expected effect on financial reporting outcomes of a potential transition to a hybrid model for subsequent measurement of goodwill.
Evidence
3.7The majority of preparers participating in the field test anticipated improved financial reporting outcomes from the application of a potential hybrid model for subsequent measurement of goodwill:
| Field test participants (preparers)35 | Hybrid model would better reflect underlying economics | Hybrid model would mitigate the shielding effect | Hybrid model would provide more relevant information for investors | Hybrid model would improve comparability |
|---|---|---|---|---|
| A | ✓ | ✓ | ✓ | |
| B | ✓ | ✓ | ✓ | ✓ |
| C | ✓ | ✓ | ✓ | ✓ |
| D | ✓ | ✓ | ✓ | ✓ |
| E | ? | ? | ? | ? |
| F | x | x | x | x |
| G | ✓ | x | x | |
| H | ✓ | x | ? | ? |
| I | ✓ | ? | ✓ | ✓ |
| Key: | ✓ = Yes | x = No | ? = Maybe |
3.8Preparers participating in the field test made the following observations highlighting the improved financial reporting outcomes they anticipated from a hybrid model:
"We believe the amortisation model better reflects the underlying economic value of goodwill. It would reflect consumption of goodwill through time as for any other asset with a finite useful life."
"We would support this approach, primarily based on perceived improved information for investors."
3.9However, one preparer participating in field-testing noted:
“We believe that the existing approach of impairing goodwill is superior, because the impairment approach results in better stewardship and holds management to account for their investment decisions."
3.10Investor and other user views were mixed. Some investors commented:
- Disclosures on the rationale underpinning management's estimate of useful life would be useful, and would help discussions with management about accountability for acquisitions.
- A disclosure table analysing goodwill by acquisition and date would help to improve management accountability for acquisitions because it would provide greater insight into the make-up and age of the carrying amount of goodwill. Users explained:
"The gross amount of goodwill is a useful number because it is part of the total amount paid for acquisitions, so we can hold management to account. If they were to allocate capital in the future as they have in the past, we can use the return on capital including gross goodwill as indicative of future returns.”
"Gross goodwill is really good. If you do have impairment, it's always nice to find out what was impaired.”
3.11These users also proposed that additional sub-totals showing how goodwill is allocated to segments would provide them with relevant information for forecasting purposes.
3.12Other users did not agree that an analysis of goodwill at an individual acquisition level would be useful. They observed that a consolidated entity-level view was necessary to assess management's stewardship, given it is not possible to invest in the acquisitions or in the CGUs or operating segments to which those acquisitions are allocated.
3.13Users also had differing views on whether a hybrid model would improve faithful representation by more accurately reflecting underlying economics. Some investors are sceptical about the relevance of information about the useful life of goodwill because in their view goodwill is an indefinite-life intangible asset. However, other users commented that an acquisition gives rise to both indefinite-life assets such as brands which should be recognised at fair value and tested for impairment (as per IFRS 3 / IAS 38 Intangible Assets), and short-lived assets such as synergies, which should be amortised. Those users confirmed that disclosures were most useful when management estimated a useful life for goodwill and, where possible, its components. In their view, such disclosures would enhance management accountability for acquisitions.
3.14One user commented:
It's useful for investors to know how management has determined the useful life of goodwill. The underlying assumptions used in determining the useful life can be very useful to investors as they give insights about the acquisition and why it was made. It would foster interesting debates with companies."
3.15Some users noted the importance of comparability with jurisdictions which do not mandate IFRS. However, other users noted that data-aggregators would remove amortisation charges to allow comparability with financial statements prepared in other jurisdictions, and concluded that this was not, therefore, a significant issue.
3.16A credit-rating agency commented that a hybrid model would not change the decision-usefulness of financial information, because their methodology excludes goodwill from credit-rating decisions.
Feasibility of amortising goodwill under a hybrid model
3.17Assessing the feasibility of a potential transition to a hybrid model for subsequent measurement of goodwill requires consideration of the following topics:
- Feasibility of estimating a useful life of goodwill.
- Default periods for the useful life of goodwill.
- Approach to legacy goodwill at the transition date.
3.18Each topic is examined further below.
Feasibility of estimating a useful life for goodwill
Evidence sources
3.19Evidence on the feasibility of estimating a useful life of goodwill was derived from the field test, roundtables with auditors and academics, meetings with users, and from a review of how the useful life of goodwill is determined under UK GAAP.
Field test evidence
3.20The field test questionnaire asked participants to identify whether it would be: (i) easy, (ii) challenging but possible, or (iii) practically impossible to estimate a useful life of goodwill.
3.21The majority 36 of field test participants (six of nine) considered it would either be easy, or challenging but possible, to estimate a useful life of goodwill for amortisation purposes.
3.22Those field test participants considered a range of relevant and specific factors to estimate the useful life of goodwill. The most frequently used were:
- Legal, regulatory and contractual provisions affecting the useful life of the acquired business.
- Expected timing of realisation of anticipated income synergies.
- Expected timing of realisation of anticipated cost synergies.
- Expected useful life of benefits acquired which are not recognised separately from goodwill (e.g., value of assembled workforce, synergies).
- Expected useful life of assets acquired and recognised under IFRS, such as customer lists and research and development projects recognised on acquisition of another entity.
- Period over which an acquired product is expected to be viable in a market.
- Nature of the acquired business.
3.23Field test participants commented:
'Determining the useful life of goodwill could be very subjective, but no less subjective than judgements involved under the impairment-only model.”
"The useful life would likely be a critical judgement37 which would need to be explained."
3.24Given the potential challenges of estimating a useful life of goodwill, several preparers participating in the field test and several auditors at the auditor roundtable noted that if the IASB were to introduce a hybrid model for subsequent measurement of goodwill, they would welcome application guidance including examples of factors to consider when determining the useful life of goodwill.
3.25A minority of field test participants (three of nine) identified that it would be practically impossible to estimate a useful life of goodwill. That minority fell into two categories:
- The first category (two participants) agreed conceptually that goodwill had a finite useful life but observed that it would be difficult to estimate that useful life without application guidance or established practice. However:
- These entities had estimated a useful life of goodwill in their 2004 financial statements prior to the introduction of IFRS38; and
- Entities in the same sector reporting under UK GAAP currently estimate a useful life of goodwill.
- The second category (one participant) held the view that goodwill is not a wasting asset, because:
- Synergies comprise a considerable proportion of the value of the goodwill, and in their view, synergies have an indefinite useful life.
- Although the benefits of the original goodwill may have been consumed, expenditure on the acquired business will have replaced it.39
3.27The field test asked participants to apply the following approach when estimating the useful life of goodwill, where relevant and feasible:
- Identify the main components of goodwill arising on each business combination.
- Value those components of goodwill.
- Estimate a useful life for each of those components.
- Use the estimated lives of the components of goodwill in calculating the amortisation charge for goodwill on each business combination.
3.28Two out of nine field test participants chose to apply this approach. For these participants, the total carrying amount of goodwill was made up of goodwill arising on a relatively small number of individually material acquisitions.
3.29One of the remaining participants identified the main components of goodwill arising on each business combination and disclosed them but did not separately value them or estimate their useful lives. The carrying amount of goodwill for this participant was also made up of goodwill arising on a relatively small number of individually material acquisitions.
3.30The remaining six participants did not consider that it was feasible or useful to identify the components of goodwill. They considered that, if goodwill were to be amortised, its useful life should be estimated assuming it is a single asset arising on each acquisition, rather than by identifying the separate components of goodwill arising on each acquisition. Those six participants represented a range of sectors including banking, media, industrial goods and services, insurance and personal care. Typically, their goodwill balances were made up of goodwill arising on large numbers of individually immaterial acquisitions. Their rationale for not identifying separate components of goodwill included:
- Goodwill is already a residual.
- Valuing components would be arbitrary and subjective.
- The cost would outweigh the benefits.
- Negotiating ability would not be captured.
Evidence from roundtables
3.31At the roundtables, there was general consensus that the factors considered by field test participants when estimating a useful life for goodwill appeared relevant and appropriate. A participant at the auditor roundtable also observed:
"The factors are consistent with what I discuss with clients that report under UK GAAP.40 A good number of preparers generally can determine a useful life and are comfortable with their assessment."
3.32Participants at both the auditor and academic roundtables concurred that estimation of the useful life of goodwill should not require separate identification and valuation of components such as synergies and value of an assembled workforce, as it may not be necessary in every case. At the academic roundtable, a participant noted that:
"Some of the approaches taken here seem to suggest that estimating the useful life of goodwill is an incredibly difficult exercise. I don't think that's true. Companies already do a lot of high-level work including estimates before making an acquisition.”
3.33An auditor observed that:
"The feedback we've received is that acquisitive entities don't think of the purchase price as a building-block concept, they look at it from an overall perspective."
User outreach evidence
3.34Some users considered that insight into the components of goodwill by acquisition has the potential to enhance management accountability for those acquisitions and would provide relevant information. However, some other users believed that valuing those components separately is over-sophisticated and subjective.
UK GAAP review evidence
3.35The UK GAAP requirements for subsequent measurement of goodwill are set out in FRS 102 The Financial Reporting Standard Applicable in the UK and Republic of Ireland (FRS 102).
3.36FRS 102 paragraph 19.23 states that “After initial recognition, the acquirer shall measure goodwill acquired in a business combination at cost less accumulated amortisation and accumulated impairment losses. Goodwill shall be considered to have a finite useful life and shall be amortised on a systematic basis over its life. If, in exceptional cases, an entity is unable to make a reliable estimate of the useful life of goodwill, the life shall not exceed 10 years.” Consequently, 10 years is a backstop, not a default.
3.37To understand how the useful life of goodwill is estimated under FRS 102, the research project included:
- Review of a sample of UK GAAP financial statements to understand individual application.
- Structured interviews with audit firms to understand the audit perspective.
- Outreach to the regulator responsible for reviewing compliance with UK GAAP41 to understand general application.
Review of UK GAAP financial statements
3.38Review of the financial statements of the UK's 100 largest private companies showed that 48 of those companies report under FRS 102. Of those 48 companies, 34 reported goodwill in their most recent financial statements.42
3.39Analysis of goodwill and related disclosures in the annual financial statements of those 34 UK private companies showed that:
- The private company goodwill balances in the sample are comparable in size to those reported at the smaller end of the listed market. The highest carrying amount of goodwill in the sample of private companies was £628 million and the average was £48 million. By comparison, the average carrying amount of goodwill for AIM entities in 2021 was £11.3 million. For the FTSE 350 in 2021, the average carrying amount of goodwill for those 228 entities reporting goodwill was £1.7 billion. However, 82% of carrying amount of goodwill for the FTSE 350 in 2021 was concentrated in 20% of the number of entities reporting goodwill. For the remaining 80%, or 183 entities that reported goodwill, the average carrying amount of goodwill was £380 million.
- The 34 companies in the sample took different approaches to estimating and disclosing the useful life of goodwill, as shown in the analysis below:
| Approach to estimating the useful life of goodwill | Number of companies | |:---------------------------------------------------------------|:--------------------| | Use the same estimate for all acquisitions | 16 | | Estimate separately for each acquisition and disclose: | | | • Range of estimates of useful lives used | 10 | | • Estimate of useful life for each acquisition | 4 | | Not disclosed | 4 | | Total number of companies | 34 |
- The sixteen companies that estimated the same useful life of goodwill for all acquisitions, estimated the useful life of goodwill as shown in the analysis below:
| Useful life of goodwill | Number of companies | |:------------------------|:--------------------| | 20 years | 5 | | 10 years | 9 | | 5 years | 2 | | Total number of companies | 16 |
- The ten companies that estimated a range of acquisition-specific useful lives of goodwill disclosed the following ranges:
| Range of estimates of useful lives of goodwill disclosed | Number of companies | |:---------------------------------------------------------|:--------------------| | Between 5 and 20 years | 5 | | Between 10 and 20 years | 2 | | Up to 20 years | 2 | | Between 4 and 20 years | 1 | | Total number of companies | 10 |
- The 4 companies that disclosed the useful life of goodwill for each acquisition disclosed the following estimates of useful life: 1 year, 7 years, 19 years, and 50 years. These companies each had only one acquisition resulting in goodwill.
- Where the useful life was determined for individual acquisitions, disclosures indicated that a range of relevant factors was considered in that determination. These included:
- strength of brand;
- products and services provided;
- competition and expected future performance;
- expected use of acquired assets43; and
- any legal, regulatory or contractual provisions that may limit the useful life.
- The useful life was typically longer for the food retail, luxury goods and motor services sectors. The useful life was also typically longer when acquisitions had delivered technological capability or online presence. By contrast, entities in the construction, retail, leisure and hospitality sectors estimated shorter useful lives for goodwill. Whilst not conclusive, this evidence suggests that factors specific to the sector and type of business are considered when determining the useful life of goodwill.
- Seventeen companies in the sample determined a useful life of goodwill that exceeded ten years for at least some of their acquisitions, as shown in the analysis below. UK GAAP requires entities that cannot estimate useful life reliably should amortise goodwill over a maximum of ten years, and so this evidence suggests that, despite the judgement involved in estimating the useful life of goodwill, management can reliably estimate the useful life of goodwill.
| Estimate of useful life of goodwill | Number of companies | |:-------------------------------------------------------------------------|:--------------------| | Useful life estimate is 10 years or less for all acquisitions, or is not disclosed | 17 | | Useful life estimate exceeds 10 years for at least some acquisitions | 17 | | Total number of companies | 34 |
Structured interviews with auditors of UK GAAP financial statements
3.40Research included structured interviews with auditors of UK GAAP reporters to ascertain the types of audit evidence they seek on management's estimate of the useful life of goodwill, and how that evidence is challenged.
3.41Auditors gain sufficient and appropriate audit evidence on the useful life of goodwill by applying ISA 540 Auditing Accounting Estimates and Related Disclosures44.
3.42Audit firms highlighted that the 2019 revision of ISA 540 led to increased use of expert input from business valuation specialists to provide audit evidence and audit challenge on the useful life of goodwill.
Outreach to the UK GAAP regulator
3.43Discussions with the regulator responsible for reviewing compliance with IFRS and UK GAAP (the FRC) indicated that it does not generally need to raise issues on estimating the useful life of goodwill under FRS 102. In contrast, a significant number of issues are raised with IFRS reporters on the application of the impairment-only model.
Default periods for the useful life of goodwill
Evidence sources
3.44Evidence from the field test, roundtables and meetings with users was used to explore the advantages and disadvantages of default periods and minimum and maximum useful lives for goodwill.
Evidence
3.45The field test asked participants for views on whether standards should set a requirement for minimum or maximum useful lives for goodwill.
3.46Field test participants observed that setting a maximum or minimum useful life for goodwill would partially negate the anticipated improved financial reporting outcomes of improved relevance and more faithful representation. The view was encapsulated by one participant who commented:
"The estimate of each useful life should be specific to each acquisition, there should not be a blanket approach.”
3.47However, there was some support from preparers for a model where, if management is unable to determine the useful life of goodwill reliably, there is a cap on the period over which goodwill is amortised. Such caps are sometimes referred to as backstops. UK GAAP currently includes a backstop of a ten-year maximum period over which goodwill can be amortised if management is unable to determine its useful life reliably.
3.48Some stakeholders asked whether having no maximum useful life would introduce the possibility of indefinite useful life; whereas other stakeholders observed that a model which allowed indefinite useful life would not be a faithful representation of those elements of goodwill whose benefits run off over time.
Approach to legacy goodwill at the transition date
Evidence sources
3.49The field test, roundtables with auditors and academics, and meetings with users were used to gather evidence on the best approach to recognised goodwill at the transition date in the event of a transition to a hybrid model for subsequent measurement of goodwill.
Evidence
3.50Field test participants' responses to the field test questions on legacy goodwill are summarised in the table below:
| Preparers45 | How easy would it be to analyse legacy goodwill by business combination? | Does legacy goodwill consist of many individually immaterial balances? | Is legacy goodwill material as a % of net assets?46 | Would amortisation of legacy goodwill be likely to have a material impact on profit after tax?47 | If there were a transition to a hybrid model, would prospective or retrospective application be preferable? | Should there be a choice of prospective or retrospective application? |
|---|---|---|---|---|---|---|
| A | Easy | N | Y | Y | Retrospective | No |
| B | Easy | Y | Y | Y | Retrospective | No |
| C | Easy | N | N | N | Retrospective | No |
| D | Easy | N | N | N | Retrospective | Yes |
| E | Easy | N | N | N | Choice | Yes |
| F | Easy | N | Y | Y | Retrospective | No |
| G | Easy | N | Y | Y | Retrospective | No |
| H | Challenging but possible | Y | Y | Y | Prospective (practicability) | Yes |
| I | Easy | Y | Y | Y | No response | No response |
3.51Almost all (8 out of 9) field test participants stated that it was easy to identify the dates and business combinations to which legacy goodwill related. One stated that this exercise would be challenging but possible, due to the considerable number of business combinations which made up the legacy goodwill balance.
3.52Field test participants were asked whether, in the event of transition to a hybrid model, they thought prospective or retrospective application of the hybrid model would be preferable.48
3.53The majority view was that retrospective application was preferable. Participants noted that:
- prospective application would not necessarily provide a faithful representation, because the benefits of legacy goodwill may already have been consumed; and
- retrospective application would allow for improved comparability between entities from the effective date forward.
3.54The majority did not agree with a free choice between retrospective and prospective application. Participants felt that mandating retrospective application would lead to greater comparability.
3.55However, most participants noted that practical expedients would be necessary for retrospective application because:
- The information required to determine a useful life of goodwill may not be available for historic acquisitions, due to systems and data retention policies at the time of the acquisition and employee turnover since the acquisition.
- Management may have limited ability to determine the useful life of goodwill without hindsight, that is, using only the information which would have been available at the date of the acquisition.
3.56The most frequently recommended practical expedient for retrospective application was a default amortisation period for legacy goodwill.
3.57One participant also supported the practical expedient of adjusting opening reserves for the earliest period presented at transition.
3.58Two participants recommended that if retrospective application were used, the adjustment should be made to opening reserves of the current reporting period, and full restatement of comparatives should not be required, because in their view the cost of full restatement of comparatives would outweigh the benefit.
3.59Auditors noted that in cases where legacy goodwill was not fully amortised at the date of transition, it should be possible to estimate remaining useful life, rendering practical expedients unnecessary.
3.60The materiality of legacy goodwill did not appear to influence field test participants' views on the anticipated financial reporting outcomes of a potential transition to a hybrid model for subsequent measurement of goodwill. Despite potentially material impacts on reported net assets and reported profit, the majority of field test participants anticipated improved financial reporting outcomes arising from a transition to a hybrid model.
3.61Field test participants with immaterial legacy goodwill were more likely to recommend that a choice of retrospective or prospective application should be permitted if there were a transition to a hybrid model. It is possible that the immateriality of legacy goodwill for these participants led them to conclude that more choice in the treatment of legacy goodwill would be acceptable, because, where legacy goodwill is immaterial, different treatments have less impact on comparability.
3.62Some users expressed concern about the time and resource that would be needed to restate previous years' figures in forecasting models if retrospective application were required.
Examples of methods used by field test participants to estimate the useful life of goodwill and treatment of legacy goodwill
3.63This section provides four examples based on the field test to show how participants estimated the useful life of goodwill and treated legacy goodwill.
3.64Entity A49 used the following approach to determine the useful life of goodwill on a recent acquisition and to calculate the amortisation charge:
- Applied a valuation model approved by its board and used by advisers that assisted during a recent material acquisition.
- Used the valuation model to identify components of goodwill and to value them. The components identified were the assembled workforce, anticipated cost synergies and anticipated margin uplift. The value of goodwill was allocated to these components in the following proportions: assembled workforce – 63%; cost synergies – 3%; margin uplift – 34%.
- Estimated a useful life of the assembled workforce based on expected remaining service and knowledge transfer.
- Estimated a useful life of anticipated cost synergies based on the expected realisation period for those synergies.
- Determined a useful life for anticipated margin uplift based on expected period of access to a specific market.
- Performed a weighted average calculation to arrive at an annual amortisation charge.
- Fully amortised in year one the excess of goodwill over the combined valuation of specific components of goodwill.
- Used the practical expedient of amortising legacy goodwill over the same period as that arrived at in the methodology outlined in a) to f) above.
3.65Entity B used the following insights and approach to estimate the useful life of goodwill on recent acquisitions:
- Identified that the main components of goodwill were synergies, value of the assembled workforce and access to a network.
- Used the valuation undertaken at acquisition to value the assembled workforce and synergies. The remaining portion of goodwill was deemed to be the value of access to a network.
- The estimate of the useful life of the assembled workforce was based on employee churn data.
- Synergies were amortised over the same time period used for cash flow forecasts in the business case for the acquisition.
Entity B example disclosure (extract)
When determining the consideration the group was willing to pay for the company being acquired, the group identified revenue and cost synergies it expected to achieve through the business combination. These included, but are not limited to, shared maintenance, operations and procurement.
Synergies arising upon the acquisition of subsidiaries are initially recognised at fair value at the date of acquisition and then amortised over the period that synergies were expected to be generated in the business case for the acquisition (x years).
Assembled workforce arising on the acquisition of a subsidiary is initially valued at fair value on the acquisition date and amortised over the period of expected staff turnover within that subsidiary (x years).
3.66Entity C used a valuation model which determines the period of time over which returns are expected to exceed the cost of capital. Entity C used this period as the useful life of goodwill and amortised goodwill on a straight-line basis.
Entity C example disclosure (extract)
Goodwill of £xxm was recognised, which is attributable to the anticipated increase in revenues arising from a strengthened market position and greater critical mass, and the anticipated future operating cost synergies arising from the elimination of duplicated back office and support functions.
For the period ended 31 December 2021, the amount of amortisation of goodwill charged is £xxm. This is included in the 'operating expenses before credit impairment write-backs / losses, provisions and changes' line in the statement of profit or loss.
3.67Users told us that Entity C's example disclosure was helpful because it identified where amortisation of goodwill was charged in the statement of profit or loss, so that it could easily be adjusted for cash flow forecasting.
3.68Entity D's illustrative disclosures under the hybrid model provided insight into the strategic rationale for each material acquisition. The factors that entity D considered in estimating the useful life of goodwill included access to new markets, value of assembled workforce, cost synergies and expected useful life of underlying assets acquired. Entity D recommended that where the useful life of goodwill cannot be determined with certainty, its useful life should not exceed 10 years. Entity D concluded that the useful life of the identified factors could not be determined with certainty and amortised goodwill over 10 years.
Entity D example disclosure (extract)
The acquisition was a long-term strategic investment expected to create value for the ABC group through revenue growth.
The following have been considered in the assessment of useful life of goodwill:
- The expected benefit of the strengthened customer proposition that owning the DEF group brings.
- The assembled workforce and its existing customer relationships which will generate income going forwards.
3.69The investor webinar poll on the example disclosures in the illustrative examples above returned these results:
| Entity B | Entity C | Entity D | |
|---|---|---|---|
| Very useful | 30% | 27% | 22% |
| Partly useful | 60% | 64% | 44% |
| Not useful at all | 10% | 9% | 33% |
| Total | 100% | 100% | 100% |
3.70Entity D's example disclosure was seen as less useful than Entity B's and Entity's C's example disclosures were seen as only partly useful, perhaps because it did not include management's assumptions about the estimated useful life of goodwill.
Effect on financial stability
3.71The research covered the anticipated effect of a transition to a hybrid model for subsequent measurement of goodwill on compliance with debt covenants, compliance with market regulations, tax payments and management compensation schemes.
Evidence sources
3.72The research assessed the effect on financial stability of a transition to a hybrid model for subsequent measurement of goodwill through the field test, preparer survey and desk-based research.
Evidence
Effect on compliance with debt covenants
3.73The preparer survey included questions on debt covenants. The objective of these questions was to establish whether a transition to a hybrid model for subsequent measurement of goodwill was likely to lead to breaches of such covenants.
3.7415 out of the 23 respondents to the preparer survey for UK IFRS preparers completed the debt covenants section. Others declined to complete that section because they deemed the information requested commercially sensitive. Respondents who completed the covenants section of the survey had a combined market capitalisation of £290 billion, representing 11% of FTSE 350 market capitalisation as at 31 December 2021. Their combined goodwill totals £49 billion, representing 13% of FTSE 350 combined goodwill as at 31 December 2021.50
3.75Of the respondents to the debt covenants section, 87% (13 respondents) affirmed that those covenants use IFRS-based measures.
3.76Of these 13 respondents:
- eight stated that the IFRS-based measures in covenants include goodwill and are taken directly from the financial statements;
- one stated that the IFRS-based measures in covenants are derived from the financial statements but adjusted to exclude goodwill; and
- four stated that covenants used both types of IFRS-based measure.
3.77The survey asked whether IFRS-based measures in covenants were based on frozen GAAP.51 Of the respondents to the covenants section, 47% (seven respondents) stated that IFRS-based measures in covenants were based on frozen GAAP. Another 47% (seven respondents) stated that IFRS-based measures in covenants were not based on frozen GAAP. 6% (one respondent) did not answer this question.
3.78The survey further asked whether covenants allow for re-negotiation when there are changes to financial reporting standards. 80% (12 respondents) of the respondents to the covenants section of the survey stated that covenants do not allow for renegotiation when there are changes to financial reporting standards. However, in follow-up discussions those respondents identified that, in practice, debt covenants which did not use frozen GAAP would be likely to be renegotiated in the event of changes to IFRS.
3.7920% (three respondents) stated that covenants allow for renegotiation when there are changes to financial reporting standards.
3.80Some respondents noted that ability to comply with debt covenants could be affected by changes to credit ratings resulting from a transition to a hybrid model for subsequent measurement of goodwill. However, during this research project, credit ratings agencies highlighted that goodwill is typically excluded from their rating methodologies, so it seems that changes in the subsequent measurement of goodwill are unlikely to lead to changes in credit ratings.
3.81Respondents from the insurance sector noted that loan covenants are typically based on their Solvency II position rather than on IFRS-based measures.
3.82There were no other discernible trends by sector, size of entity, reported goodwill or number of acquisitions in the responses to the survey questions on debt covenants.
Effect on compliance with market regulations
3.83Desk-based research and the preparer survey did not identify an increased risk of failing to meet market regulations if there were changes to the subsequent measurement of goodwill.
3.84UK Listing Rules require additional disclosure where the gross assets, capital or profits of an acquiree exceed certain thresholds relative to the gross assets, capital or profits of the acquiror. Tests are performed to establish whether the additional disclosures are necessary52. These tests are based on asset, capital and profit values at the date the test is required.
3.85Application of a hybrid model for subsequent measurement of goodwill may lead to increased disclosure on future acquisitions under the Listing Rules. If accumulated amortisation and goodwill impairment charges under a hybrid model exceed goodwill impairments charged under the current impairment-only model, then gross assets, capital and profits of the acquiror will be lower under a hybrid model, and, if gross assets, capital and profits of the acquiree are unchanged, the gross assets, capital or profits of an acquiree are more likely to exceed a percentage threshold of gross assets, capital or profits of the acquiror.
3.86Retrospective adjustments do not affect the test. Therefore, retrospective application of potential changes to the subsequent measurement of goodwill would not increase the risk of compliance failure.
Effect on tax payments
3.87Transitioning to a hybrid model for the subsequent measurement of goodwill under IFRS would not generally directly impact tax payable by UK IFRS reporters and their UK-based subsidiaries.
3.88This is because for UK companies, corporation tax liabilities are calculated at individual company level, whereas amortisation of goodwill arising on acquisitions of legal entities arises only in consolidated financial statements. Even in those less frequent cases when goodwill arises in individual company financial statements due to trade and assets acquisitions, amortisation of goodwill may still not have an impact on tax payable because accounting amortisation of goodwill is generally not deductible for corporation tax purposes. However, the position is complex in relation to some legacy goodwill, depending on when it arose, and for non-UK based subsidiaries different tax regimes may apply.
Effect on management compensation schemes
3.89Some survey respondents highlighted that changes to the subsequent measurement of goodwill could impact management compensation schemes.53
3.90Through follow up discussion with survey respondents, research identified that remuneration committees will typically discuss and agree any necessary adjustments to IFRS-based performance measures in management compensation schemes in the event of changes to IFRS Accounting Standards. Given lead-times for the implementation of new IFRS Accounting Standards, the effect on management compensation schemes is unlikely to be significant or unexpected by management.
Effect on audit, processes, systems and costs
Sources of evidence
3.91Evidence on audit, processes, systems and costs is gathered from the preparer survey, field test and auditor roundtable.
Evidence
Implications for audit, processes and systems
3.92The majority (71% / 16 responses) of preparer survey respondents said that they would not anticipate significant operational changes if there were a transition to a hybrid model for the subsequent measurement of goodwill. One respondent commented:
"We have systems and processes in place already for other tangible and intangible assets that are accounted for at cost less accumulated depreciation and accumulated impairment losses. Should a hybrid approach be introduced, goodwill can be embedded into the existing reporting environment to allow amortisation going forward.”
3.93These respondents identified that they would expect some change in the following operational areas if a potential transition to a hybrid model were to go ahead: processes and procedures, audit, staff training and investor relations. One respondent commented:
"There would be a need to train/educate investors and users of our financial reports on the change in our reporting, given the non-cash nature of the charge."
3.94The remaining respondents (39% /seven responses) said that they anticipated significant operational changes if there were a transition to a hybrid model. These respondents identified that significant changes would be needed to the following areas: processes and procedures, audit, data, staff training, systems and technology. One field test participant commented,
"To get the judgements involved in estimating the useful life of goodwill through SOX level reviews, we would anticipate having to provide a significant amount of information."
3.95Another field test participant commented:
"We think auditors would want to do full impairment testing anyway. It is therefore unlikely that there would be a saving on the audit of goodwill impairment. Management and the audit committee also wouldn't want to look at an indicator-only approach for impairment.”
3.96Respondents anticipating significant operational changes if there were a transition to a hybrid model did not report higher goodwill or higher numbers of acquisitions in the last five years.
Implications for costs
3.97When asked about the anticipated cost impact of a potential transition to a hybrid model, 39% of survey respondents anticipated either a substantial reduction, a minor reduction, or minimal or no impact on costs. The respondent who anticipated a substantial reduction in costs cited ongoing cost reductions in processes and procedures as the underlying reason. At the auditor roundtable, one participant commented:
"You'd have less costs on impairment testing as you'd only look at it if there was a trigger."
3.9848% of respondents anticipated a minor increase in costs and 13% of respondents anticipated a significant increase in costs. Approximately one third of the respondents anticipating a minor increase in costs attributed this to one-off implementation costs rather than ongoing costs.
3.99The 13% of survey respondents anticipating a significant increase in on-going costs cited audit, staff training and additional expert resource as underlying reasons. Two thirds of these respondents anticipated increases in implementation costs and ongoing costs. The implementation costs related to developing a model for estimating the useful life of goodwill and a methodology for revising it for future acquisitions. One participant at the auditor roundtable observed:
"Smaller AIM companies have smaller teams and won't be able to determine the valuations of different components of goodwill themselves. Where they opt to seek assistance from experts or firms, it generally isn't cheap."
3.100Respondents anticipating cost increases did not report higher numbers of acquisitions in the last five years or higher goodwill.
3.101One field test participant commented that additional one-off costs could arise for training, development of consolidation systems and ongoing costs for resource. In particular, resource would be needed to monitor goodwill at the level of individual acquisitions where it is currently allocated to CGUs. However, the participant also observed that:
"If you have a lead time, you can future proof and do things right.”
3.102From the UKEB's research described above it appears a transition to a hybrid model for subsequent measurement of goodwill is feasible and is unlikely to lead to a significant adverse impact on financial stability or costs for UK companies. Therefore, this section explores the potential concerns and potential solutions with the hybrid model for subsequent measurement of goodwill that may need to be considered.
4 A hybrid model: potential benefits, concerns and solutions
4.1This section explores the potential benefits, concerns and solutions observed by stakeholders during the UKEB research project.
Anticipated benefits of the hybrid model explored in this paper
Financial reporting benefits
4.2As noted by the majority of field test participants, amortisation of goodwill would provide a more faithful representation of profitability and asset values by reflecting the consumption of economic benefits. Consequently, the risk that goodwill continues to be reported at cost in the statement of financial position when its benefits have already been consumed would be reduced.
4.3The risk of overstatement of goodwill through shielding would also be reduced. Subject to usual materiality constraints, a hybrid model would require management tracking of goodwill by acquisition. This would require consideration of the consumption of benefit of goodwill at the level of each material acquisition, thereby ensuring that amortisation is charged over the period where its benefits are consumed and reducing the risk of shielding whilst also enhancing accountability.
4.4Comparability between entities that grow organically and those that grow through acquisition would improve, because amortisation requires the cost of growing the entity to be charged to the statement of profit or loss in the same way that the cost of organic growth is charged to the statement of profit or loss, albeit in different accounting periods.
4.5The analysis of the carrying amount of goodwill by material acquisition or by groups of similar acquisitions would provide insight into the age and make-up of the constituent parts of goodwill. Investors would see which acquisitions make up the carrying amount of goodwill, when those acquisitions took place, and management's assumptions about the useful life of goodwill for those acquisitions. Users have noted that this insight could help to enhance management accountability for acquisitions.
4.6Disclosures of management's assumptions used to determine the useful life of goodwill would provide relevant information to investors. This information would provide insight into expected future profits and help investors to engage with management on the subsequent performance of acquisitions.
4.7Disclosures on the presentation and amount of the amortisation expense would allow investors to easily identify that expense54 and, where relevant, to adjust for amortisation expenses in models and metrics, for example in cash-flow forecast models and return on invested capital metrics.
4.8Indicator-only impairment testing would continue to provide relevant information where the carrying amount of goodwill is no longer expected to be recovered.
Other benefits
4.9There is potential for cost savings from moving from full annual impairment testing to indicator-only impairment testing. These are likely to arise from savings on resources currently deployed in impairment testing and associated audit fees.
Potential concerns and potential solutions
Volume of disclosures
4.10The hybrid model explored in this paper could lead to a substantial increase in volume of disclosures for entities with large numbers of acquisitions. However:
- Assuming usual materiality constraints are applied55, the hybrid model explored in this paper would not necessarily result in a large volume of disclosures. For example, disclosures on individually immaterial acquisitions could be aggregated.
- During meetings with investors undertaken as part of this research project, users anticipated that the disclosures proposed in the hybrid model explored in this paper would be useful.56 Some investors also commented that a large volume of disclosures is not problematic provided that those disclosures address users' needs.
- Developments in digital reporting may mean that users are able to extract the information they need more easily, and that increased volumes of disclosures are therefore less of an issue than they may have been before those developments in digital reporting.
- IASB's Discussion Paper: Disclosures, Goodwill and Impairment proposed additional disclosures to support management accountability for acquisitions. The feedback to the Discussion Paper identified a potential increase in volume of disclosures as a potential concern with its proposals. The IASB is currently considering a potential solution which would require disclosures only for a subset of acquisitions.57 If that solution is carried forward in the final amendment to the standard, it would be feasible to deploy it to address any potential concerns arising from a high volume of disclosures under the hybrid model discussed in this paper.
Commercial sensitivity of disclosures
4.11Concerns regarding commercial sensitivity of some disclosures arose during this research. A commercial sensitivity exemption could be a potential solution, as is permitted elsewhere in IFRS. A similar exemption on grounds of commercial sensitivity in IAS 37 Provisions, Contingent Liabilities and Contingent Assets paragraph 92 permits an entity not to disclose information if doing so may prejudice seriously the entity's position in a legal dispute. However, the IASB's research58 shows that the exemption was mentioned only in approximately 110 entities in 2021, with the source database containing over 37,000 entities globally.
Potential loss of disclosures required by IAS 36 Impairment of Assets
4.12In some cases, IAS 36 Impairment of Assets requires disclosure of key assumptions used in impairment testing goodwill.59 These disclosures are required for each cash-generating unit when the amount of goodwill allocated to that cash-generating unit is significant in comparison with the entity's total carrying amount of goodwill. These disclosures include growth rates, discount rates, forecast periods and the extent to which assumptions reflect past experience or external information.
4.13In meetings with investors forming part of this research project, some investors stated that these disclosures are useful for forecasting purposes in the cases where they are provided. Those investors initially thought that the hybrid model explored in this paper could lead to less frequent updates of the assumptions in these disclosures, because currently IFRS requires full impairment testing of goodwill annually, whereas under the hybrid model explored in this paper, goodwill would be tested for impairment only when there is an indicator of impairment.
4.14However, it is unlikely that the assumptions in these disclosures would be updated significantly less frequently under the hybrid model explored in this paper than they are currently. This is because IAS 36 currently exempts an entity from updating the assumptions to be used in goodwill impairment testing where (i) there has not been a change in the assets and liabilities making up the cash-generating unit, (ii) the most recent recoverable amount exceeded carrying amount by a substantial margin, and (iii) the likelihood of a current determination of recoverable amount being below carrying amount is remote. Since these criteria apply in many cases, the key assumptions in the disclosures are usually only updated infrequently under the current model.
4.15Under the hybrid model explored in this paper, the approach to impairment testing remains the same as under IFRS now, but on an indicator-only basis. As a result, the current disclosure requirements will continue to apply, to the extent they are applicable. Consequently, the UKEB does not consider that the disclosures would be updated any less frequently under the hybrid model, because where the IAS 36 exemption does not apply, an impairment test would be required under the hybrid model just as it would be under the current requirements.
Potential increase in number of reconciling items between IFRS totals and subtotals and management performance measures
4.16One field test participant noted that requiring amortisation of goodwill would be likely to lead to an increase in the number of reconciling items between IFRS totals and subtotals and management performance measures (MPMs). In their view, such an increase would reduce the relevance of IFRS totals and subtotals.
4.17During the course of this research, a review of a sample of fifty annual reports showed that in almost all cases there is already an adjustment to IFRS totals or subtotals for amortisation of intangibles to arrive at an MPM. In most cases, amortisation of goodwill under a hybrid model is expected to be included in the existing adjustment for amortisation thus rendering additional adjustments for amortisation of goodwill unnecessary.
5 Conclusions
5.1The UKEB considers that the current impairment-only model for subsequent measurement of goodwill under IFRS needs reconsideration because:
- Despite nearly two decades of experience of implementing an impairment-only model under IFRS, the debate on subsequent measurement of goodwill continues. The problems with the impairment-only model are widely acknowledged and include a lack of faithful representation of those elements of goodwill whose benefits are consumed over time, shielding, and insufficient disclosure to hold management to account for acquisitions.
- The subsequent measurement of goodwill is an important issue from a UK perspective, since goodwill totals £397 billion for FTSE 350 entities in 2021 and represents approximately 18% of total assets and 63% of net assets for those 228 FTSE 350 companies reporting goodwill in 2021.
- On average, goodwill impairments for the FTSE 350 represent 2.85% of the opening carrying amount of goodwill over the seventeen-year period from 2005 to 2021, implying an average write-off period of 35 years. Whilst the carrying amount of goodwill has increased for the FTSE 350 from £223 billion in 2005 to £397 billion in 2021, the rate of goodwill impairment has slowed. The five-year rolling average implied write-off period for goodwill has increased from 20 years in 200960 to 51 years in 2021. By contrast, under the UK GAAP hybrid model, the UKEB's review of disclosures on goodwill amortisation periods for the largest private companies showed that only one estimated a useful life of goodwill greater than 20 years.
- There is some correlation between the annual value of total goodwill impairments recognised by the FTSE 350 and periods of economic uncertainty in the UK since 2005, with total goodwill impairment expense peaking at £16.1billion in 2008 during the global financial crisis for example. However, no firm conclusions can be drawn on the responsiveness of the model to economic conditions. Trends are prone to distortions arising from some very large single impairments, with 80% of total goodwill impairments by value charged by only twelve entities between 2005-2021.
- Under the current impairment-only model for goodwill, disclosure does not support investors in holding management to account for acquisitions, because it is extremely difficult to analyse the carrying amount of goodwill by age and acquisition.61
5.2Benefits of moving to the hybrid model explored in this paper include:
- Faithful representation of those elements of goodwill whose benefits are consumed over time. It would prevent the build-up of goodwill on the balance sheet when that goodwill no longer satisfies the definition of an asset. It would support the ongoing relevance of the statement of financial position.
- Disclosure of an analysis of goodwill by age and composition, and of management's assumptions in estimating the useful life of goodwill, providing investors with information relevant to their resource allocation decisions and support investors in holding management to account for acquisitions.
- Risk of shielding being mitigated.
5.3Stakeholders highlighted potential concerns about increased volume of disclosure and commercial sensitivity. However, these concerns could be addressed through limiting disclosures to a subset of acquisitions (proposals under consideration by the IASB at the time of writing) or by providing a commercial sensitivity exemption.
5.4The UKEB research demonstrated that a transition to a hybrid model would be feasible as:
- The majority of preparers involved in our outreach believe it is possible to estimate a useful life for goodwill through consideration of a range of relevant factors and if sufficient application guidance is provided.
- A similar model works effectively under UK GAAP.
- Suitable transition arrangements could be provided for legacy goodwill.
- There do not appear to be significant adverse consequences for financial stability or for changing processes, operations and costs.
6 Potential areas for further research
6.1During the research project, two further potential areas for future research were identified.
- Research into the effectiveness of the impairment-only model by:
- An analysis of trends in goodwill impairments against expectations of goodwill impairment derived from indicators of impairment, such as financial performance indicators, e.g., declining margins, net liabilities, and market capitalisation below book value. Trends in the light of rising costs and supply chain issues in 2022 may be particularly interesting to explore.
- Further analysis of carrying amounts of goodwill by acquisition date for UK IFRS reporters, to further understand the age profile of goodwill and its implications.
- Research into the prevalence and materiality of trade and assets deals, to understand the impact of amortisation of goodwill arising in separate company financial statements on distributable profits, dividend payments and financial stability.
Appendix A Shielding
IAS 36 requirements
A1IAS 36 Impairment of Assets states that any asset which is not capable of generating cash flows independently from other assets should be tested for impairment as part of a cash-generating unit (CGU) or group of CGUs.
A2Goodwill is cited in the standard as an example of an asset which cannot generate cash flows independently from other assets.
A3Such assets are allocated to a CGU or group of CGUs. A CGU is the lowest level group of assets which generates cash flows independently. Each CGU or groups of CGUs to which goodwill is allocated must represent the lowest level within the entity at which goodwill is monitored by management and cannot be larger than an operating segment.
A4To determine whether goodwill is impaired, the CGU (group of CGUs) recoverable amount is measured, typically by computing the present value of the forecast future cash flows of the CGU (group of CGUs). Where the carrying amount of the CGU (group of CGUs) exceeds its recoverable amount, those assets are impaired. Consequently, an impairment expense is recognised to reduce carrying amount to recoverable amount.
A5The impairment expense is typically presented in profit or loss and is allocated to the assets in the CGU in the following order, reducing their carrying amount:
- Goodwill
- Other assets in the CGU, pro-rated on their carrying amounts.
A6However, no individual asset can be impaired to a carrying amount that is below the higher of its recoverable amount and zero. When this limit is reached for an asset that forms part of a CGU, the otherwise unallocated impairment is allocated pro rata to the other assets of the CGU.
The shielding problem
A7The lack of granularity and other deficiencies in the allocation of goodwill to CGUs (group of CGUs) create a problem known as the shielding of goodwill.
Shielding arises where goodwill recognised in the accounting for a particular business combination is, inconsistently with economics, protected from impairment. Shielding is commonly results from headroom in the acquirer's pre-combination assets that form part of the CGU (group of CGUs) and headroom created by the future cash flows of unrelated assets in the CGU (group of CGUs). For example, an entity may have a CGU (group of CGUs) for a broad category of products, such as health products or magazines. All goodwill on all acquisitions in
IAS 36 requirements
A1IAS 36 Impairment of Assets states that any asset which is not capable of generating cash flows independently from other assets should be tested for impairment as part of a cash-generating unit (CGU) or group of CGUs.
A2Goodwill is cited in the standard as an example of an asset which cannot generate cash flows independently from other assets.
A3Such assets are allocated to a CGU or group of CGUs. A CGU is the lowest level group of assets which generates cash flows independently. Each CGU or groups of CGUs to which goodwill is allocated must represent the lowest level within the entity at which goodwill is monitored by management and cannot be larger than an operating segment.
A4To determine whether goodwill is impaired, the CGU (group of CGUs) recoverable amount is measured, typically by computing the present value of the forecast future cash flows of the CGU (group of CGUs). Where the carrying amount of the CGU (group of CGUs) exceeds its recoverable amount, those assets are impaired. Consequently, an impairment expense is recognised to reduce carrying amount to recoverable amount.
A5The impairment expense is typically presented in profit or loss and is allocated to the assets in the CGU in the following order, reducing their carrying amount:
- Goodwill
- Other assets in the CGU, pro-rated on their carrying amounts.
A6However, no individual asset can be impaired to a carrying amount that is below the higher of its recoverable amount and zero. When this limit is reached for an asset that forms part of a CGU, the otherwise unallocated impairment is allocated pro rata to the other assets of the CGU.
The shielding problem
A7The lack of granularity and other deficiencies in the allocation of goodwill to CGUs (group of CGUs) create a problem known as the shielding of goodwill.
Shielding arises where goodwill recognised in the accounting for a particular business combination is, inconsistently with economics, protected from impairment. Shielding is commonly results from headroom in the acquirer's pre-combination assets that form part of the CGU (group of CGUs) and headroom created by the future cash flows of unrelated assets in the CGU (group of CGUs). For example, an entity may have a CGU (group of CGUs) for a broad category of products, such as health products or magazines. All goodwill on all acquisitions in the broad category is allocated to the health products CGU or magazines CGU. None of the goodwill will be impaired provided the present value of future cash flows for the health products CGU (group of CGUs) or magazines CGU (group of CGUs) exceeds the carrying amount of the total assets in the CGU (group of CGUs). Goodwill on unsuccessful acquisitions could be allocated to the CGU (group of CGUs) but under the current impairment-only model would be shielded from impairment by the cash flows generated by other assets in the CGU (group of CGUs).
A8An entity may have a CGU (group of CGUs) which includes successful business lines developed organically rather than through acquisition. These successful organically developed business lines could shield goodwill arising on acquisitions from impairment.
A9Such shielding could continue indefinitely under the impairment-only model.
Appendix B Research method
Scope
B1The research addressed the following areas:
- Effect on financial reporting outcomes if there were to be a transition to a hybrid model for subsequent measurement of goodwill. In particular, stakeholder views on accountability, faithful representation, relevance and comparability were sought.
- Feasibility of a transition to a hybrid model for subsequent measurement of goodwill. This area examined the feasibility of estimating a useful life of goodwill, the factors considered when estimating a useful life of goodwill, and how to deal with legacy goodwill. The materiality of transitional impacts was also analysed. 62
- Potential impact on financial stability. This area considered the potential impact of a transition to a hybrid model on loan covenants, compliance with market and other regulatory rules, tax revenues and management compensation schemes.
- Potential impact on audit, processes, systems and costs.
Phases
B2Research took place between October 2021 and July 2022. Research consisted of two phases. Each phase is summarised below.
B3Phase one took place from October 2021 to December 2021. Phase one explored how the useful life of goodwill is determined under UK GAAP and whether a transition to a hybrid model for subsequent measurement of goodwill would be likely to have a significant impact on financial stability in the UK. Phase one showed that a range of relevant factors is considered in estimating the useful life of goodwill under UK GAAP, and that a transition to a hybrid model for subsequent measurement of goodwill would be unlikely to have a significant impact on financial stability in the UK. Research methods used in phase one were a preparer survey, a review of the application of the UK GAAP hybrid model, and other desk-based research. Further detail on each method is provided below.
B4Phase two took place from January 2022 to July 2022 and built on the conclusions from phase one. Phase two explored the feasibility of a transition to a hybrid model for subsequent measurement of goodwill for UK IFRS preparers, focusing on anticipated financial reporting outcomes, the feasibility of estimating a useful life of goodwill, options on transition, and anticipated effects on audit, processes, systems and costs. Research methods used in phase 2 were analysis of FTSE 350 data and financial statements, and a field test completed with UK IFRS preparers, followed by meetings with users, auditors and academics at which the results of the field test were shared. Further detail on each method is provided below.
Methods
Phase 1
Preparer survey
B5To obtain an understanding of UK stakeholders' views on the implications of a potential transition to a hybrid model for the subsequent measurement of goodwill, the UKEB conducted a survey of UK IFRS reporters.
B6The survey was open from 15 November to 26 November 2021 and was publicly promoted to UK IFRS preparers.
B723 UK IFRS preparers completed the survey, representing 17% of the FTSE 350 by market capitalisation.63 The survey participants covered a range of sectors including fast-moving consumer goods, banking, energy, utilities, construction, technology, retail, pharmaceutical, medical technology, insurance, airlines, B2B, and manufacturing. The total carrying amount of goodwill of respondents represented 17% of total goodwill of the FTSE 350. 22 of the 23 respondents had made acquisitions in the last five years.
Review of the application of the UK GAAP hybrid model for subsequent measurement of goodwill
B8To assess the feasibility of estimating the useful life of goodwill under a hybrid model, the UKEB reviewed the application of the UK GAAP hybrid model for subsequent measurement of goodwill.
B9The review consisted of:
- Review of the financial statements of the UK's 100 largest private companies to ascertain how the useful life of goodwill is estimated under UK GAAP.
- Structured interviews with auditors of UK GAAP entities to understand how the estimate of useful life of goodwill under UK GAAP is audited.
- Outreach to the UK GAAP regulator to ascertain whether particular issues arise with any frequency in regard to estimation of the useful life of goodwill under UK GAAP.
Desk-based research
B10The UKEB used desk-based research, including review of relevant legislation, regulation, and academic and industry papers, to understand the relevant accounting and economic issues relating to goodwill.
Conclusions from phase 1
B11The UKEB published the results of phase 1 of its research and shared those results with the IASB. The high-level conclusions from phase 1 were:
- It is possible to estimate a useful life of goodwill, and relevant factors are identified and considered by entities when making this estimation.
- It is unlikely that a transition to a hybrid model for the subsequent measurement of goodwill would have a significant adverse impact on financial stability in the UK.
Phase 2
Field test
B12Building on the conclusions from phase 1 of the research, the survey results and evidence from desk-based research were used to develop a field test questionnaire.
B13The field test was publicly promoted from February – March 2022.
B14Nine UK entities preparing financial statements under IFRS participated in field-testing.64 The entities were from the following sectors: financials, consumer discretionary, utilities, industrial, and consumer staples. Of the nine entities, seven are FTSE 100 listed, one is FTSE 250 listed, and one is AIM listed.
B15Field-test participants were asked to complete a questionnaire on transitional arrangements to a hybrid model and to prepare example financial statement extracts and disclosures under the hybrid model.
B16Four entities completed the questionnaire and example financial statement extracts and disclosures. Five entities completed the questionnaire only.
Outreach to auditors, academics and users of financial statements
B17Summarised field test questionnaire responses and anonymised financial statement extracts and disclosures were shared with auditors, academics and users of financial statements for comment.
B18An analysis of outreach by stakeholder group is provided in Appendix E.
Financial statement and FTSE 350 data analysis
B19To provide context for the research, the UKEB undertook financial statement and FTSE 350 data analysis to investigate the application of the impairment-only model for listed companies in the UK from 2005 to 2021.
B20Data relating to the carrying amount of goodwill, accumulated amortisation and impairment, and goodwill impairment charges for the FTSE 350 from 2005 to 2021 was extracted from Reuters Eikon and analysed by UKEB staff. As part of this work, a number of simplifying assumptions needed to be made. UKEB staff tested a sample of the data extracted from Reuters Eikon for reliability by agreeing it to annual reports. The data was deemed to be sufficiently reliable for the purposes of this research.
Appendix C Field test participants
| Organisation | FTSE Industry | FTSE Supersector | Listing medium |
|---|---|---|---|
| Entity A | Utilities | Utilities | LSE |
| Entity B | Consumer Discretionary | Travel and leisure | LSE |
| Entity C | Financials | Banks | LSE |
| Entity D | Financials | Financial services | LSE |
| Entity E | Financials | Insurance | LSE |
| Entity F | Financials | Insurance | LSE |
| Entity G | Industrials | Industrial goods and services | AIM |
| Entity H | Consumer Staples | Personal care, Drug and Grocery stores | LSE |
| Entity I | Consumer Discretionary | Media | LSE |
Market capitalisation of field test participants represented 10% of FTSE 350 market capitalisation and 0.02% of AIM market capitalisation.
Goodwill as a percentage of net assets averaged 36% for field test participants. Goodwill as a percentage of net assets ranged between 2% and 96% for field test participants.
Appendix D Survey respondents
| Sector | Number of respondents | Percentage of respondents |
|---|---|---|
| Communications | 2 | 9% |
| Consumer discretionary | 1 | 4% |
| Consumer staples | 2 | 9% |
| Energy | 3 | 13% |
| Financials | 6 | 26% |
| Health care | 2 | 9% |
| Industrials | 4 | 17% |
| IT | 1 | 4% |
| Materials | 1 | 4% |
| Utilities | 1 | 4% |
| Total respondents | 23 | 100% |
Appendix E Outreach events and participants
| Preparers | Auditors | Users | Academics | Total | |
|---|---|---|---|---|---|
| Survey | 23 | - | - | - | 23 |
| Meetings | - | 6 | 6 | - | 12 |
| Field test | 9 | - | - | - | 9 |
| Roundtables | - | 14 | 10 | 5 | 29 |
| Webinar | - | - | 17 | - | 17 |
| Total | 32 | 20 | 33 | 5 | 90 |
Appendix F Glossary
| Term | Description |
|---|---|
| AIM | Alternative Investment Market. The London Stock Exchange's market for small and medium size growth companies. |
| Amortisation | The systematic allocation of the depreciable amount of an intangible asset over its useful life. (IAS 38, paragraph 8.) |
| Backstop model | A model where, if management is unable to estimate the useful life of goodwill reliably, there is a cap on the period over which goodwill is amortised. |
| FRC | Financial Reporting Council |
| Frozen GAAP | GAAP effective at the time of the transaction. |
| FTSE 100 | A share index of the 100 largest companies traded on the London Stock Exchange (LSE). |
| FTSE 350 | A share index of the 350 largest companies traded on the London Stock Exchange (LSE). The FTSE 350 index is made up of the constituents of the FTSE 100 and FTSE 250 index. |
| Goodwill | An asset representing the future economic benefits arising from other assets acquired in a business combination that are not individually identified and separately recognised. (IFRS 3, Appendix A.) |
| Headroom | The excess of the recoverable amount of a cash-generating unit (or group of units) over the carrying amount of that unit. |
| Hybrid model | A method of accounting for goodwill after its initial recognition in which both an annual amortisation charge and an impairment test are applied. |
| IASB | International Accounting Standards Board |
| IFRS | International Financial Reporting Standard |
| IAS 36 | International Accounting Standard 36 Impairment of Assets |
| IAS 38 | International Accounting Standard 38 Intangible Assets |
| IFRS 3 | International Financial Reporting Standard 3 Business Combinations |
| Impairment | The amount by which the carrying amount of an asset exceeds its recoverable amount. (IAS 38, paragraph 8.) |
| Indicator-only impairment testing | Indicator-only impairment testing requires entities conduct an impairment test when there is an indicator of impairment, rather than at a regular time interval. Indicator-only impairment testing is currently used for all assets except for goodwill and indefinite-life intangible assets. IAS 36 paragraph 12 identifies the external and internal sources of information ('indicators') an entity should consider when deciding whether a full impairment test is needed. |
| Legacy goodwill | Goodwill arising from business acquisitions undertaken before adopting a hybrid model of accounting for goodwill. |
| LSE | London Stock Exchange |
| M&A | Mergers and Acquisitions |
| Management Performance Measures (MPMs) | Quantifiable measures that assess management's performance during the reporting period. |
| Outreach | Activities conducted with various groups and organisations, to gather information and insights. |
| Shielding effect | Shielding arises where goodwill recognised in the accounting for a particular business combination is, inconsistently with economics, protected from impairment. |
| Solvency II | Solvency II sets out regulatory requirements for insurance firms and groups, covering financial resources, governance and accountability, risk assessment and management, supervision, reporting and public disclosure. https://www.bankofengland.co.uk/prudential-regulation/key-initiatives/solvency-ii |
| Synergy | The value of the benefit arising from two or more companies operating together as opposed to operating separately. |
| Trade and asset transaction | A transaction involving the sale and purchase of some or all of an entity's assets and liabilities, without there being a change in the shareholding. |
| Useful life | The period over which an asset is expected to be available for use by an entity or the number of production or similar units expected to be obtained from the asset by an entity |
| UKEB | UK Endorsement Board |
| UK GAAP | United Kingdom Generally Accepted Accounting Practice |
| Unincorporated business | A business that does not possess a separate legal identity from its owners |
| Underlying items | Non-identifiable items that form part of an easily identifiable item |
| US FASB | United States Financial Accounting Standards Board. |
| Wasting asset | An asset whose useful life is limited |
Appendix G Analysis of age of goodwill
G1To analyse the age of the carrying amount of goodwill in the 2021 financial statements, the UKEB analysed the individual financial statements of seven FTSE 350 companies for the period from 2005 to 2021. The companies were selected because their combined carrying amount of goodwill represented a significant proportion of total FTSE 350 carrying amount of goodwill.
G2The notes relating to goodwill were analysed to determine if the explanations given enabled any changes in the carrying amount of goodwill to be assigned to the year(s) of the related acquisition.
Limitations in the analysis
G3The reconciliation of gross carrying amount of goodwill and the reconciliation of accumulated amortisation and impairment included several items in addition to acquisitions and impairments that needed to be checked. For example, exchange movements, transfer of assets held for resale, disposals and other. The most significant of these items are described below.
G4Impairment charges: The analysis was hampered by the fact that acquisitions are usually described by referring to the company acquired and impairments are described in the same terms. The impairment charge does not usually refer to the date of the acquisition, so further work was necessary to find the date of the acquisition to which the impairment charge relates.
G5Some companies describe the impairment charge in terms of the cash-generating unit to which it belongs and do not give the name of the acquisition or the year in which it took place.
G6Exchange movements: Exchange movements occur where an acquisition is not in the functional currency of the company.65 From the available information it is not possible to allocate the exchange rate movements to specific acquisitions.
G7Other items in the reconciliations: For example, transfer of assets held for resale. These items were usually explained in a similar way to impairment charges, by referring to the company about to be sold and did not usually refer to when the company was acquired.
How the data was grouped
G8The aim of the analysis was to analyse the net carrying amount of goodwill in the 2021 financial statements by age band, as shown in the table below:
| Age of goodwill | |
|---|---|
| 2004 and before | X% |
| 2005-2009 | X% |
| 2010-2014 | X% |
| 2015-2019 | X% |
| 2020-2021 | X% |
| 2021 Net carrying amount of goodwill | 100% |
G9However, this analysis was not possible given the limitations in the data, so the analysis was extracted as follows:
| Age of goodwill | |
|---|---|
| 2004 and before | X% |
| 2005-2009 | X% |
| 2010-2014 | X% |
| 2015-2019 | X% |
| 2020-2021 | X% |
| Impairment charge | X% |
| Transfer to held for sale | X% |
| Disposals | X% |
| Exchange movements 2005-2021 | X% |
| Other | X% |
| 2021 Net carrying amount of goodwill | 100% |
G10Impairment charge: For large value impairment charges further work was undertaken, by looking at earlier financial statements, to see whether the acquisition date of the company that had been subject to an impairment charge could be found and, if so, it was then allocated to the relevant year of acquisition. Smaller impairment charges were not analysed in this way due to time constraints, the remaining amount of unallocated impairment charges are shown as a separate item.
G11Other items in the reconciliations: For large values, these amounts were analysed, in a similar way to that for large value impairment charges to determine if the acquisition date could be found, and if so, it was then allocated to the relevant year of acquisition.
G12Exchange movements: Exchange movements were unable to be allocated to specific acquisitions, so the total amount of the movement for 2005-2021 is shown as a separate item.
What was found
G13The analysis shows that:
- 3 companies had 61%–86% of the 2021 net carrying amount of goodwill from acquisitions relating to 2015-2019. One company had 144% of the 2021 net carrying amount of goodwill from acquisitions relating to 2004 and before, although that company also has -71% relating to exchange movements. 2 companies also had 49%–54% of the 2021 net carrying amount of goodwill from acquisitions relating to 2004 and before.
- All 7 companies had exchange movements. These varied from less than 1% of the 2021 net carrying amount of goodwill to -71% of the 2021 net carrying amount of goodwill.
- 6 companies had unallocated impairment charges varying from less than 1% of the 2021 net carrying amount of goodwill to -19% of the 2021 net carrying amount of goodwill.
- All 7 companies had some unallocated items. For example, one company had -9% of the 2021 net carrying amount of goodwill relating to transfer of goodwill to held for sale and disposals.
| Company | A (£m) | A (%) | B (£m) | B (%) | C (£m) | C (%) | D (£m) | D (%) | E (£m) | E (%) | F (€m) | F (%) | G (£m) | G (%) |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 2004 and before | 7,607 | 18% | 5,927 | 54% | 304 | 3% | 7,235 | 144% | 2,377 | 16% | 9,883 | 49% | 257 | 3% |
| 2005-2009 | 1,850 | 4% | 4,418 | 40% | 2,712 | 26% | 1,436 | 29% | 598 | 4% | 817 | 4% | 1,855 | 24% |
| 2010-2014 | 133 | 0% | 660 | 6% | 1,264 | 12% | 16 | 0% | 57 | 0% | 2,192 | 11% | 1,765 | 23% |
| 2015-2019 | 34,522 | 80% | 33 | 0% | 6,402 | 61% | 0% | 12,786 | 86% | 5,623 | 28% | 2,024 | 27% | |
| 2020-2021 | 36 | 0% | 1,082 | 10% | 124 | 1% | 0% | 1,793 | 12% | 3,148 | 15% | 376 | 5% | |
| Impairment charge | 982 | -2% | -2,042 | -19% | 22 | 0% | 0% | 1,336 | -9% | 161 | -1% | 622 | -8% | |
| Transfer to held for sale | 0% | -1,014 | -9% | -739 | -7% | 0% | 0% | -1,099 | -5% | 0% | ||||
| Disposals | 21 | 0% | 0% | 0% | 0% | 0% | -660 | -3% | ||||||
| Exchange movements 2005-2021 | 77 | 0% | 1,852 | 17% | 611 | 6% | -3,594 | -71% | -256 | -2% | 204 | 1% | 1,948 | 26% |
| Other | 28 | 0% | 6 | 0% | -104 | -1% | -60 | -1% | -1,099 | -7% | 383 | 2% | 9 | 0% |
| Net carrying amount of goodwill | 43,194 | 100% | 10,910 | 100% | 10,552 | 100% | 5,033 | 100% | 14,920 | 100% | 20,330 | 100% | 7,612 | 100% |
UK Endorsement Board 1 Victoria Street
| London | SW1H 0ET | United Kingdom Web: www.endorsement-board.uk
UK Endorsement Board
Appendix 2: suggested amendments to draft Goodwill research report
The following table includes suggested amendments to the draft goodwill research report (See Appendix 1) to address comments by Board members and during other outreach with some stakeholders. Subsequent to the Board meeting, staff intend to insert the proposed text in the final report, prior to finalisation.
| Change no | Goodwill paper paragraph reference | Rationale for proposed change | Current text | Proposed text |
|---|---|---|---|---|
| 1 | 4 | Provide brief rationale for different elements of hybrid model. | Under the hybrid model outlined in this paper and tested in this research, goodwill would be subject to an annual amortisation charge, supplemented by impairment testing which would take place only when there had been an indicator of impairment. | Under the hybrid model outlined in this paper and tested in this research, goodwill would be subject to an annual amortisation charge, supplemented by impairment testing which would take place only when there had been an indicator of impairment. The annual amortisation charge would reflect the expected pattern of consumption of economic benefit. Indicator-only impairment testing would be used to reflect the extent to which the carrying amount of goodwill is no longer expected to be recovered. |
| 2 | 7 | Add clarity | The mandatory application of the IFRS impairment-only model for the subsequent measurement of goodwill resulted in UK listed companies in the FTSE 350 charging £150 billion of goodwill impairments between 2005 and 2021, averaging 2.85% of the opening carrying amount of goodwill over that period. | The mandatory application of the IFRS impairment-only model for the subsequent measurement of goodwill resulted in UK listed companies in the FTSE 350 charging £150 billion of goodwill impairments between 2005 and 2021, averaging 2.85% per annum of the opening carrying amount of goodwill over that period. |
| Change no | Goodwill paper paragraph reference | Rationale for proposed change | Current text | Proposed text ---
Appendix C: Profiles of entities that participated in field testing
Appendix C provides profiles of those entities which participated in field-testing.
Appendix D: Glossary
Acquisition date
The date on which the acquirer obtains control of the acquiree.
Amortisation
The systematic allocation of the depreciable amount of an intangible asset over its useful life.
Business combination
A transaction or other event in which an acquirer obtains control of one or more businesses. Transactions sometimes referred to as 'true mergers' or 'mergers of equals' are also business combinations in this IFRS.
Carrying amount
The amount at which an asset or liability is recognised in the statement of financial position.
Cash-generating unit (CGU)
The smallest identifiable group of assets that generates cash inflows that are largely independent of the cash inflows from other assets or groups of assets.
Depreciable amount
The cost of an asset, or other amount substituted for cost, less its residual value.
Depreciation
The systematic allocation of the depreciable amount of an asset over its useful life.
Equity method
A method of accounting whereby the investment is initially recognised at cost and adjusted thereafter for the post-acquisition change in the investor's share of the investee's net assets. The investor's profit or loss includes its share of the investee's profit or loss and the investor's other comprehensive income includes its share of the investee's other comprehensive income.
Fair value
The price that would be received to sell an asset or paid to transfer a liability in an orderly transaction between market participants at the measurement date.
Goodwill
An asset representing the future economic benefits arising from other assets acquired in a business combination that are not individually identified and separately recognised.
Impairment loss
The amount by which the carrying amount of an asset or a cash-generating unit exceeds its recoverable amount.
Intangible asset
An identifiable non-monetary asset without physical substance.
Recoverable amount
The higher of an asset’s or cash-generating unit’s fair value less costs of disposal and its value in use.
Residual value
The estimated amount that an entity would currently obtain from disposal of the asset, after deducting the estimated costs of disposal, if the asset were already of the age and in the condition expected at the end of its useful life.
Useful life
- the period over which an asset is expected to be available for use by an entity; or
- the number of production or similar units expected to be obtained from the asset by an entity.
Appendix E: References
- IASB Discussion Paper DP/2020/2 Business Combinations—Disclosures, Goodwill and Impairment 2020
- IASB Discussion Paper DP/2012/1 A Review of the Conceptual Framework for Financial Reporting 2012
- IASB Staff Paper Post-implementation Review—IFRS 3 Business Combinations 2015
- IASB Staff Paper Feedback Statement for the PIR of IFRS 3 Business Combinations 2016
- IPSASB Consultation Paper Measurement of Goodwill 2020
- IPSASB Research Paper Measurement of Goodwill 2021
- IASC Staff Paper Intangible Assets: A Discussion Paper 1998
- FASB Staff Paper Goodwill and Other Intangible Assets: A Revisit to Purchase Business Combinations 2019
- FASB Staff Paper Goodwill and Other Intangible Assets 2020
- PwC Goodwill impairment in the FTSE 350 – the annual review 2021
- FCA Policy Statement PS19/20 Quarterly reporting—feedback on CP19/18 and final rules 2019
- FRC Staff Paper Academic Panel: Literature Review on Goodwill and Impairment 2021
Footnotes
-
The timeline was updated because stakeholder engagement throughout the project had been more extensive than was originally anticipated. ↩
-
UKEB is an observer on EFRAG's Consultative Forum of Standard Setters (CFSS). ↩
-
The UK's statutory requirements for adoption of international accounting standards are set out in The International Accounting Standards and European Public Limited-Liability Company (Amendment etc.) (EU Exit) Regulations 2019 no. 685 (the Regulations, or SI 2019/685). ↩
-
The Financial Times-Stock Exchange 350 share index is a weighted index of the top 350 companies by free float market capitalisation on the London Stock Exchange. The FTSE 350 includes the FTSE 100 and the FTSE 250 indices. ↩
-
Under FRS 102, goodwill is considered to have a finite useful life and shall be amortised on a systematic basis over its life. If, in exceptional cases, an entity is unable to make a reliable estimate of the useful life of goodwill, the life shall not exceed 10 years. Consequently, a maximum amortisation period of 10 years is a backstop, not a default. ↩
-
Note that FRS 102 does not require separate recognition of intangibles on acquisition. Therefore, the factors considered in estimating the useful life of goodwill are likely to include greater consideration of the expected useful life of intangibles such as brands, etc. ↩
-
Goodwill may arise in individual company financial statements due to trade and assets acquisitions. Even in these cases, however, amortisation of goodwill may still not have an impact on tax payable because accounting amortisation of goodwill is generally not deductible for corporation tax purposes. ↩
-
Unless otherwise stated, the data referred to in this section is taken from Reuters Eikon. Appendix B discusses the reliability of the data. ↩
-
The Financial Times-Stock Exchange 350 share index is a weighted index of the top 350 companies by free float market capitalisation on the London Stock Exchange. The FTSE 350 includes the FTSE 100 and the FTSE 250 indices. ↩
-
Patloch-Kofler, M. and Roider, D. (2020), 'Impairment-Only Oder Amortization? – Eine Glaubensfrage Im Lichte Des IASB-Discussion Paper', RWZ, (9/2020), a 2020 study of STOXX Europe 600 goodwill reporters found that goodwill represented on average 12.8% of total assets and 35.0% of net assets for those entities in 2019. The study also found that goodwill had not varied significantly as a proportion of total assets or net assets for those entities in the period covered by the study (2010 to 2019). The findings from the study show the significance of goodwill for STOXX Europe 600 reporters. Comparison of the study's findings to the UKEB analysis shows that goodwill is even more significant as a proportion of total assets and net assets for the FTSE 350 than for the STOXX Europe 600. ↩
-
Prior to the adoption of IFRS, UK listed companies measured goodwill in accordance with an amortisation and impairment model included in UK GAAP FRS 10 Goodwill and Intangible Assets. ↩
-
Unless otherwise stated, the data referred to in this section is taken from Reuters Eikon. Appendix B discusses the reliability of the data. ↩
-
The Financial Times-Stock Exchange 350 share index is a weighted index of the top 350 companies by free float market capitalisation on the London Stock Exchange. The FTSE 350 includes the FTSE 100 and the FTSE 250 indices. ↩
-
Patloch-Kofler, M. and Roider, D. (2020), 'Impairment-Only Oder Amortization? - Eine Glaubensfrage Im Lichte Des IASB-Discussion Paper', RWZ, (9/2020), a 2020 study of STOXX Europe 600 goodwill reporters found that goodwill represented on average 12.8% of total assets and 35.0% of net assets for those entities in 2019. The study also found that goodwill had not varied significantly as a proportion of total assets or net assets for those entities in the period covered by the study (2010 to 2019). The findings from the study show the significance of goodwill for STOXX Europe 600 reporters. Comparison of the study's findings to the UKEB analysis shows that goodwill is even more significant as a proportion of total assets and net assets for the FTSE 350 than for the STOXX Europe 600. ↩
-
Prior to the adoption of IFRS, UK listed companies measured goodwill in accordance with an amortisation and impairment model included in UK GAAP FRS 10 Goodwill and Intangible Assets. ↩
-
In line with expectations, increases in the value of gross goodwill between 2005 and 2021 correlate with the value of mergers and acquisitions activity by FTSE 350 entities over the same period. ↩
-
Lexis Nexis Market Tracker Trend Report: Trends in UK Public M&A Deals in H1 2022 ↩
-
The ratio of market capitalisation to net assets. ↩
-
The high price-to-book ratio arises because much of the perceived value of those entities is represented by items not recognised as assets under IFRS, such as intellectual capital, anticipated future growth and potential synergies. ↩
-
Appendix A explains the shielding effect. ↩
-
The US FASB communicates changes to accounting standards via Accountings Standards Updates (ASUS). ↩
-
On 15 June 2022, FASB decided to remove the project on subsequent measurement of goodwill from its technical agenda. Prior to its decision to remove the project from its technical agenda, the FASB had made tentative decisions to reintroduce amortisation, to set a rebuttable presumption for the maximum amortisation period, and to require straight-line amortisation. ↩
-
The highest and lowest annual goodwill impairment charges for the FTSE 350 are provided to illustrate the range of annual goodwill impairment charges for the FTSE 350 from 2005 to 2021. The average goodwill impairment charge for the FTSE 350 from 2005 to 2021 is provided as a basis of comparison to identify relatively high or low annual impairment charges. ↩
-
The implied goodwill write-off period for the FTSE 350 for each year from 2005 to 2021 was calculated by dividing the total opening carrying amount of goodwill for the FTSE 350 by the total goodwill impairment expense for the year for the FTSE 350. ↩
-
The five-year rolling average implied write-off period for goodwill was calculated by dividing a five-year rolling average carrying amount of goodwill by a five-year rolling average of annual goodwill impairment expense. The five-year rolling average was used because the annual measure was prone to distortion in years when the total value of goodwill impairments was relatively low. For example, in 2006 when goodwill impairments totalled £1.2 billion the implied useful life of goodwill was 163 years and in 2010 when goodwill impairments totalled £1.8 billion the implied useful life of goodwill was 151 years. ↩
-
The Financial Reporting Council. ↩
-
FRS 10 was effective for accounting periods ending on or after 23 December 1998 and until 31 December 2004. ↩
-
SSAP 22 was effective for accounting periods beginning on or after 1 January 1985 until 1997. ↩
-
The full analysis is presented in Appendix 8. ↩
-
One impairment was due to softening consumer demand for branded health-care products. The other impairment was due to lower long-term economic growth assumptions for an acquisition with a global footprint. ↩
-
A rebuttable presumption is a presumption that is taken to be true unless proved otherwise. Previous UK financial reporting regimes for goodwill have included rebuttable presumptions about its useful life. For example, FRS 10 included a rebuttable presumption that the useful life of goodwill was 20 years or less. ↩
-
Although the hybrid model explored in this paper would not set a minimum or maximum useful life of goodwill or a rebuttable presumption regarding that useful life, the UKEB acknowledges that the absence of those guard-rails may be more challenging for jurisdictions without experience of estimating the useful life of goodwill under domestic GAAP. ↩
-
Whilst previous financial reporting regimes for subsequent measurement of goodwill have identified factors to consider in the estimation of useful life, the list of factors above is more comprehensive than those previously identified. For example, FRS 10 paragraph 20 identified the following factors as relevant to an estimation of the useful life of goodwill: 1. The nature of the business 2. The stability of the industry in which the acquired business operates 3. Typical lifespans of the products to which the goodwill attaches 4. The extent to which the acquisition overcomes market entry barriers that will continue to exist 5. The expected future impact of competition on the business. ↩
-
IAS 36 Impairment of Assets paragraph 12 identifies the indications that an entity shall consider when assessing whether there is any indication that an asset may be impaired. These indications include, for example, significant changes with an adverse effect on the entity in the technological, market, economic or legal environment in which the entity operates, and evidence from internal reporting that indicates that the economic performance of an asset is, or will be, worse than expected. IAS 36 paragraph 13 states that the list in paragraph 12 is not exhaustive and that an entity may identify other indications that an asset may be impaired. ↩
-
Preparer data has been anonymised. Preparer profiles are shown in Appendix C. Preparers represented 5 of the 10 sectors in the FTSE 350 with the highest carrying amount of goodwill. ↩↩
-
Nine participants took part in the field test. Six considered that it would be easy, or challenging but possible, to estimate a useful life for goodwill. Three considered that it would be practically impossible to estimate a useful life for goodwill. ↩↩
-
IAS 1 Presentation of Financial Statements paragraph 125 states that "An entity shall disclose information about the assumptions it makes about the future, and other major sources of estimation uncertainty at the end of the reporting period, that have a significant risk of resulting in a material adjustment to the carrying amounts of assets and liabilities within the next financial year." ↩↩
-
Disclosure in one entity's 2004 financial statements stated, "Useful economic lives have been determined in respect of each acquisition to match the period over which the value of the underlying businesses will exceed the value of their identifiable net assets." ↩↩
-
Although this view is rebuttable from a technical perspective, a rebuttal is not provided here because the purpose of this section is to set out the research findings. ↩↩
-
See section 1 for an overview of UK GAAP requirements for subsequent measurement of goodwill. ↩↩
-
The Financial Reporting Council (FRC). ↩
-
Analysis was conducted in 2021 using 2020 financial statements. ↩
-
Unlike IFRS, UK GAAP does not require separate recognition of intangibles on acquisition. Therefore, the factors considered in estimating the useful life of goodwill under UK GAAP are likely to include greater consideration of the expected useful life of intangibles such as customer lists. ↩
-
ISA 540 was revised for accounting periods beginning on or after 15 December 2019 to provide more extensive guidance on the audit of accounting estimates. ↩
-
Field test participants' profiles are shown in Appendix C. ↩
-
Field test participants' own assessment, checked for reasonableness in UKEB analysis. ↩
-
Field test participants' own assessment, checked for reasonableness in UKEB analysis. ↩
-
If applied prospectively, the hybrid model would be applied to legacy goodwill from the effective date forwards. If applied retrospectively, the hybrid model would be applied from the date of the business combination. ↩
-
Entity A did not provide illustrative disclosures as part of their field test response. ↩
-
Source: UKEB calculations based on Eikon data ↩
-
Frozen GAAP is the GAAP prevailing at the date of the transaction. ↩
-
For example, Listing Rules Class tests for transactions Listing Rules 13.5.33b; Disclosure Guidance and Transparency Rules Related Party tests. ↩
-
Some management compensation schemes include measures which would be affected by the introduction of a hybrid model for subsequent measurement of goodwill explored in this paper. Other schemes, may be based on measures such as EBITDA which would not be affected by changes to the subsequent measurement of goodwill. ↩
-
The disclosure of total amortisation and the lines in the statement of profit or loss where it is presented is currently under discussion by the IASB as part of its General Presentation and Disclosures project. ↩
-
Paragraph 2.11 notes that additional disclosures under the hybrid model explored in this paper would be subject to existing materiality constraints. ↩
-
Section 3 describes the benefits which the investors participating in this research anticipated from the hybrid model explored in this paper. ↩
-
The IASB has explored a subset based on a quantitative threshold, a subset based on a qualitative threshold, and a subset based on a factor or indicator-based threshold ↩
-
Slide 21 of ASAF Agenda Paper 1 "Goodwill and Impairment", July 2022 ASAF meeting: https://www.ifrs.org/content/dam/ifrs/meetings/2022/july/asaf/ap1-goodwill-and-impairment.pdf ↩
-
IAS 36 paragraphs 134 and 135 set out the required disclosures. ↩
-
The impairment-only model for subsequent measurement of goodwill became effective for UK listed companies on 1 January 2005. The first five-year rolling average is therefore provided for 2009. ↩
-
IASB's Disclosures, Goodwill and Impairment project aims to improve management accountability for acquisitions. Proposals to improve management accountability for acquisitions currently under discussion by IASB include improved disclosures on the rationale for acquisitions and disclosures on the subsequent performance of acquisitions. The advantages, disadvantages and feasibility of these proposals are currently under debate. ↩
-
Appendix C provides profiles of those entities which participated in field-testing. ↩
-
The market capitalisation of survey respondents represented 17% of FTSE 350 market capitalisation as at 30 November 2021. ↩
-
Appendix C sets out field test participants' profiles. ↩
-
IAS 21 The Effects of Changes in Foreign Exchange Rates requires that, foreign currency assets and liabilities, including goodwill, are translated at the rates of exchange ruling at the balance sheet date. ↩
-
These entities included those which participated in the field-testing. ↩
-
The market capitalisation of survey respondents represented 17% of FTSE 350 market capitalisation as at 30 November 2021. ↩