3.0 Draft Due Process Handbook – Review of Comments Received
Executive Summary
| Project Type | UKEB Set-up |
|---|---|
| Project Scope | N/A |
Purpose of the paper
This paper provides the Board with a summary of the main matters identified by respondents on the draft Due Process Handbook (the “Handbook").
Summary of the Issue
The Handbook was issued for comment on 21 February 2022 and was open for comment until 6 June 2022.
The appendices to this paper include a summary of the main matters identified by respondents on the Handbook (Agenda paper 3 Appendix 1). We are asking the Board for its comments which will help us develop a revised version of the Handbook that we will bring for discussion at a future meeting;
On the other non-substantive matters identified by respondents on the Handbook (Agenda paper 3 Appendix 2) we are also asking for comments, if any.
A copy of the draft Handbook that was published for public comment can be found here.
Decisions for the Board
We are not asking the Board to make any decisions at this meeting. Board members are only asked for their comments on the main matters identified in Appendix 1 and comments on the non-substantive matters in Appendix 2.
Recommendation:
Board members consider the proposed approach and provide comment on proposed actions indicated.
Appendices
- Appendix 1 Comments summary—Main (substantive) matters identified
- Appendix 2 Other non-substantive matters
Introduction
1 The (draft) Due Process Handbook (the “Handbook”) was issued for public consultation on 21 February 2022 and was open for comment (for 105 days) until 6 June 2022.
2 The Board received six comment letters[^1], from the following UK stakeholders:
- Two respondents are accounting firms;
- Two respondents are accountancy bodies;
- One respondent is an individual; and
- One respondent is a preparer from the insurance sector.
3 Additional comments were also received from the UK oversight body. These comments were similar in nature to the other respondents' comments and consequently have been addressed.
4 Respondents were generally supportive of the processes described in the Handbook. They thought that the processes described provide an adequate framework for the UKEB's due process activities. However, respondents raised several detailed comments and suggestions on the content of the Handbook.
Structure of the papers
5 Agenda paper 3.1 summarises the main (substantive) matters identified by respondents. We are asking the Board for its comments on our preliminary assessment and planned drafting amendments.
6 Agenda Paper 3.2 provides a table with a high-level summary of other non-substantive matters identified by respondents and our planned actions. We are not asking specific questions to the Board but we welcome any feedback on those matters.
Next steps and timeline
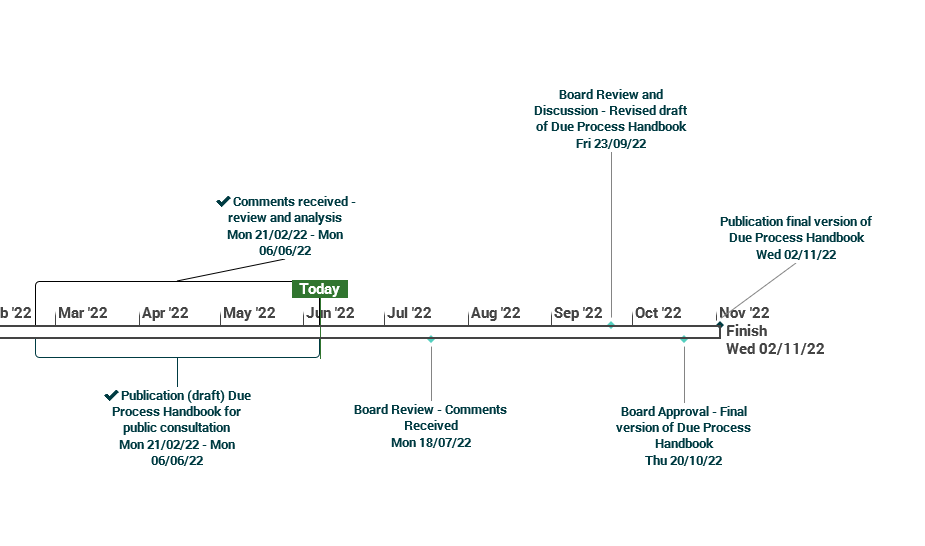
7 Subject to the comments we received at this meeting and any amendments/additions required by the Board, we plan to bring for Board review and discussion a revised draft of the Handbook at the September 2022 meeting.
8 We set out our planned next steps in a table and diagram in the next pages.
Timeline
| Date | At a public Board meeting: |
|---|---|
| 18 July 2022 | Feedback summary—Main matters identified discussion (This meeting) |
| 23 September 2022 | Board review and discussion of final version of Due Process Handbook |
| 20 October 2022 | Board approval of final version of Due Process Handbook |
| 2 November 2022 | Publication of final Due Process Handbook |
[Draft] Due Process Handbook— Upcoming Tasks
High Level Plan
Appendix 1: Comments summary—Main (substantive) matters identified
Purpose
1 This paper summarises the main (substantive) matters identified by respondents in relation to some of the sections in the (draft) Due Process Handbook (the “Handbook”) (see table below).
2 For each of the main matters identified we describe the issue and provide a preliminary assessment. We also ask the Board for its initial thoughts on the feedback received.
| Issue(s) in this paper | Areas identified in the Handbook where respondents raised substantive matters | Paragraphs in this paper |
|---|---|---|
| 1A–1B | Voting process for adoption decisions | 3–14 |
| 2A–2D | UKEB workplan—priorities, review and discussion | 15–26 |
| 3 | Milestones that should be mandatory | 27–30 |
| 4 | Considering whether to “pursue” a non-mandatory milestone should not be “optional" | 31–35 |
| 5 | Instances where consultation periods can be shortened | 36–43 |
| 6 | Circumstances for carrying out “minimum outreach activities" for endorsement projects | 44–48 |
| 7A–7C | DECA content | 49–62 |
| 8 | Timeframes for completing endorsement activities | 63–64 |
| 9A–9E | Activities for meeting the objectives of thought leadership and the research programme | 65–81 |
| 10A–10C | Requirements for carrying out post-implementation reviews | 82–99 |
| 11A–11B | Supporting the work of the IFRS Interpretations Committee | 100–106 |
| 12 | Quorum requirements for advisory groups and frequency of meetings | 107–108 |
| 13A–13D | Other issues not addressed in the Handbook | 109–121 |
Issue 1—Voting process for adoption decisions
3 Paragraphs 4.2–4.5 of the Handbook describe the voting process requirements for adopting an international accounting standard (hereafter “Standard”)[^1a]. These paragraphs reproduce the requirements in Section 5 of the UKEB's Terms of Reference. The Board's voting process requires an agreement of a two-thirds majority of the members of the Board. Paragraphs 4.4–4.5 describe the process that should be followed when this majority is not reached, including the possibility that the Board may decide not to adopt a Standard in full[^2]; these paragraphs are reproduced below:
4.4 Where the vote to adopt a standard or amendment or interpretation does not reach the required majority, the UKEB Chair may, after consultation with external parties including BEIS, choose to ask the Board to return to the vote. This may include asking the Board to vote on part of the standard, amendment or interpretation if it appears that this will have the required support. A subsequent decision to adopt the part standard or part amendment to a standard or part interpretation must be made by at least two-thirds of the Members (ToR, paragraph 5.4).
4.5 Where a vote by the Board to adopt a standard, amendment, or interpretation, in whole or in part, did not reach the required majority and, in the opinion of the UKEB Chair, there is no prospect of such majority being reached, the UKEB Chair must provide a written explanation of circumstances to the Secretary of State within 10 working days of the failure to adopt. The Secretary of State may require further evidence. The Chair must inform members of the Board of any recommendations by the Secretary of State (ToR, paragraph 5.5).
Matters raised
4 Some respondents raised the following concerns:
- The UKEB's ability not to adopt a Standard in full (Issue 1A)
- Additional procedures are needed: (Issue 1B):
- in deciding whether to adopt a Standard (i.e. in full or in part); and
- after a decision is made to not adopt a Standard (i.e. in full or in part).
Issue 1A: The UKEB's ability not to adopt a Standard in full
Matters raised
5 In respect of the UKEB's ability not to adopt a Standard in full (paragraph 4.4 of the Handbook):
- One respondent expressed some concerns as this would raise questions about the quality and effectiveness of the UKEB's influencing activities and undermine the position of UK companies.
- One respondent suggested creating additional steps to ensure that Standards are always endorsed in full. For example, carrying out a public consultation to discuss the contentious aspects of the Standard or amendment to build consensus amongst Board members.
- One respondent agreed with the UKEB's ability to carve-out or amend a Standard but were of the view that the Handbook should state explicitly that this is not a desired outcome.
Staff view
6 We disagree that the Handbook should state that Standards are always endorsed in full, as this would not be consistent with the purpose of the UKEB to ensure that international accounting standards meet the endorsement criteria before being considered for adoption.
7 We agree that the Board could consider emphasising that non-endorsement (in full or on a partial basis) is not a desired outcome, as we understand that the Board has expressed this desire during its discussions. However, the Handbook sets out the process the Board undertakes in assessing the appropriateness of international accounting standards for use in the UK, not the views on that process.
Issue 1A. Question for the Board
| a) | Does the Board agree that the Handbook does not require any further comment on the non-endorsement of international accounting standards and that it will rarely, if ever, be the desired outcome? |
Issue 1B: Additional procedures are needed (i) in deciding whether to adopt a Standard in full and (ii) after a decision is made to not adopt a Standard
Matters raised
(i) In deciding whether to adopt a Standard (i.e. in full or in part)
8 One respondent noticed a perceived inconsistency between paragraph 4.4 and paragraph 6.43(b) of the Handbook. While paragraph 4.4 permits the Chair to return to the vote when a two-thirds majority has not been obtained, paragraph 6.43(b) permits a restart of the adoption process. This respondent suggests that this process be clarified. These paragraphs are reproduced below (emphasis added):
4.4 Where the vote to adopt a standard or amendment or interpretation does not reach the required majority, the UKEB Chair may, after consultation with external parties including BEIS, choose to ask the Board to return to the vote. This may include asking the Board to vote on part of the standard, amendment or interpretation if it appears that this will have the required support. A subsequent decision to adopt the part standard or part amendment to a standard or part interpretation must be made by at least two-thirds of the Members (ToR, paragraph 5.4).
6.43(b) Decisions on the endorsement and adoption of a standard or amendment are made at public Board meetings and follow the requirements of the UKEB's Terms of Reference as follows:
- Quorum attendance—a minimum of sixty percent of the appointed members are required to attend a meeting of the Board (ToR, paragraph 5.1)
- Decision-making—an affirmative written vote of at least two-thirds of all of the appointed Board members (ToR, paragraph 5.2), is required for the decision to be passed. Each member of the Board has one vote. A situation where the two-thirds majority cannot be obtained may restart the endorsement and adoption process (ToR, paragraph 5.4).
9 In addition, respondents asked:
- What determines the Board's decision not to adopt a Standard?
- Does a vote on full adoption take place before a vote on non-adoption?
- Does a vote on non-adoption need to be formalised by circulation outside the Board meeting?
- Is the vote on non-adoption undertaken only by those Board members present at the meeting? Or by all Board members?
(ii) After a decision is made to not adopt a Standard (i.e. in full or in part)
10 Respondents asked:
- How are any recommendations by the Secretary of State[^3] communicated to the Board and how should they be acted upon?
- Would a subsequent vote to adopt a standard in full be allowed after the original adoption vote was for part-adoption or adoption with modifications to scope? If this is not allowed, is the UKEB required to give an indication that it will never adopt a Standard?
- Would a feedback statement (or any other relevant explanatory due process document) be required to clarify or explain a decision not to adopt?
11 One respondent observed that paragraph 6.45 of the Handbook should be amended to require the recording in minutes of the Board's reasons for not supporting the endorsement and adoption of a new or amended standard. This paragraph is reproduced below (emphasis added):
6.45 Where a Board member does not support the endorsement and adoption of a new or amended standard, that is reflected in their vote. If they wish, the reason for this view may be recorded in the minutes.
Staff view
12 We do not agree that there is an inconsistency between paragraphs 4.4 and 6.43(b) of the Handbook (as explained in paragraph 8). We do not consider that any changes need to be made to the Handbook although we suggest clarifying the position by further addition of cross-references as follows:
- in paragraph 6.43(a) to paragraph 4.1 (Quorum of attendance and decision making); and
- in paragraph 6.43(b) to paragraphs 4.2–4.5 (Voting process for endorsement decisions).
13 Addressing the respondents' concerns in paragraphs 9–10 of this paper would involve developing additional procedures that are not currently part of the requirements in section 5 of the Terms of Reference. The Terms of Reference are set by the Secretary of State for BEIS. Therefore, we would like to get the Board's view on asking the Secretary of State to undertake a clarification and/or extension of the Terms of Reference so that further procedures be developed to address respondents' concerns. We consider that these procedures do not need to be developed at this time as it is not expected to be a regular occurrence. Due process procedures should be developed when necessary.
14 We disagree with the respondent's suggestion in paragraph 11. Board members are only required to vote in favour or against the adoption of a Standard and are not required to provide their rationale for not adopting a Standard. Consequently, we do not think that paragraph 6.45 should be amended.
Issue 1B. Questions for the Board
| a) | Does the Board agree not to change paragraphs 4.4 and 6.43(b) and to include references to some of the paragraphs in Section 4 of the Handbook, as we suggested in paragraph 12? |
| b) | Does the Board think we should ask BEIS to undertake a clarification and/or extension of the Terms of Reference so that further procedures be developed to address respondents' concerns, in paragraphs 9–10)? |
| c) | Do you agree that paragraph 6.45 of the Handbook should not be amended to require the recording in minutes of the Board's reasons for voting against the endorsement and adoption of a new or amended standard for the reasons provided in paragraph 14? |
Issue 2—UKEB Workplan—priorities, review and discussion
Matters raised
15 Some respondents suggested that in relation to the UKEB workplan:
- UK-specific issues should be prioritised and be clearly identified (Issue 2A)
- Endorsement projects should always be top priority (Issue 2B)
- Additional factors should be considered in prioritising technical projects (Issue 2C)
- Regular consultations on the UKEB workplan should be undertaken (Issue 2D)
16 We address these issues separately in the paragraphs below.
Issue 2A: UK-specific issues should be prioritised and be clearly identified
Matters raised
17 A couple of respondents observed that although the UKEB's workplan is intended to be aligned with the IASB's work plan[^4], the latter might not necessarily include UK-specific issues. They suggested the UKEB to be proactive in identifying UK-specific issues; to add any of those issues identified to the work plan; and to bring those UK-specific issues to the IASB's attention during the influencing phase of the project.
Staff view
18 We observe that the Handbook already includes requirements that are consistent with the respondents' suggestions. For instance:
- Paragraph 4.36 includes a requirement to prioritise individual projects that are important to UK stakeholders and that impact UK entities.
- Regarding how UK-specific issues could be identified:
- Paragraph 7.2 (section on “Leading the UK debate”) includes a requirement to engage and collaborate with UK stakeholders to identify key areas of concern.
- Paragraph 7.15 (section on “Identification of issues for Research") requires the identification of proposals for research through the interaction with advisory groups or derived from outreach activities or from comment letters by UK stakeholders.
- Paragraph 4.31(b) states that (emphasis added) “other technical issues derived from the UKEB's own thought leadership and research programme” are also part of the UKEB's workplan.
Issue 2A. Questions for the Board
| a) | Do you agree that UK-specific issues are already prioritised sufficiently in the Handbook? |
Issue 2B: Endorsement projects should always be top priority
Matters raised
19 Paragraph 4.31 states that the UKEB's technical plan includes (emphasis added):
4.31
- Influencing projects that include technical issues identified by the IASB and technical issues identified by the IFRS Interpretations Committee that give rise to:
- draft IFRIC Interpretations; and
- proposals for minor or narrow-scope amendments to international accounting standards;
- Other technical issues derived from the UKEB's own thought leadership and research programme
- Adoption projects.
20 One respondent stated that while research, thought leadership and influencing projects are an important part of the UKEB's work, ensuring that the endorsement process is completed on a timely basis should be the top priority.
Staff view
21 We agree that endorsement projects are a priority. The current order of the sub-paragraphs reflects the order in which a standard is developed, finalised and then considered for endorsement and adoption and we recommend that this is explained in the Handbook. We do not recommend that the order shown in paragraph 4.31(c) needs to be changed although we could explain why it is in that order.
Issue 2B. Question for the Board
| a) | Do you agree that we should explain the order of the list of projects in the Handbook as noted in paragraph 21? |
Issue 2C: Additional factors should be considered in prioritising technical projects
Matters raised
22 Paragraph 4.36 of the Handbook states that in prioritising individual projects and allocating resources to them, the Board considers various factors, including (emphasis added):
4.36
- the importance of the issue to UK stakeholders (e.g. users, preparers, academics, accounting firms, accounting bodies and regulators, and others interested in financial reporting);
- the effect an issue has or is expected to have on UK entities using UK-adopted international accounting standards, including both the number of entities affected and the size of the effect;
- interactions with other current or proposed projects on the work plan;
- the urgency of the issue; and
- the availability of staff resources.
23 A couple of respondents suggested the following additional factors for prioritising technical projects:
- "the need to align with the IASB effective date of a new or amended standard"; and
- "the size of the entities affected”, so that an issue that significantly affects a small number of very large entities can be also prioritised.
Staff view
24 We consider that the first suggestion is covered by (d) urgency of the issue and the second suggestion is covered by (b). We do not recommend changing paragraph 4.36 of the Handbook.
Issue 2C. Question for the Board
| a) | Do you agree that the suggestions for additional factors mentioned in paragraph 23 are already included in paragraph 4.36 of the Handbook? |
Issue 2D: Regular consultations on the UKEB workplan should be undertaken
Matters raised
25 A respondent suggested that the Board undertakes regular consultations on its workplan with UK stakeholders and explains the reasons why topics have/have not been added to the plan.
Staff view
26 We consult on our workplan as part of the Regulatory Strategy consultation which will occur every year. The 2022/23 Regulatory Strategy consultation was published in January 2022 and closed on 1 March 2022. We consider that as the consultation on the workplan is within the Regulatory Strategy, that it does not need to be included in the Handbook.
Issue 2D. Question for the Board
| a) | Do you agree that the Handbook does not need to deal with consultations on the Board's workplan as it is included in the Regulatory Strategy consultation? |
Issue 3—Milestones that should be mandatory
Matters raised
27 Some respondents observed that the following milestones should be “mandatory" to support a more robust due process:
Influencing activities (paragraph 5.1)
- A draft comment letter (DCL). One respondent observed that without a DCL constituents would find it difficult to understand the direction of travel and may result in the accumulation of stakeholder concerns that could only be raised at a later stage in the endorsement process, reducing the UKEB's ability to influence the IASB's decision making process in a timely manner. Another respondent suggested that publishing a DCL should not be mandatory for a tentative agenda decision but that this should be the only exception in the Handbook.
- Outreach activities. One respondent thought that a certain amount of consultation with stakeholders should always be undertaken (even if this is holding informal meetings or interviews with interested parties or liaising with IASB staff members). Another respondent recommended including an explicit rebuttable presumption that some degree of outreach is expected in an influencing project.
- Feedback statement. One respondent thought that a feedback statement should be made mandatory if the UKEB issued a DCL.
Research programme (paragraph 7.12)
- Identification of issues for research. One respondent thought this milestone should be mandatory (this respondent did not provide specific reasons for this suggestion).
- Outreach activities. One respondent thought that as research projects are influenced by stakeholder engagement, there is merit in considering these activities as mandatory.
- Feedback statement. One respondent thought that a feedback statement should be made mandatory if the UKEB issued a public consultation document.
First phase of a UKEB post-implementation review (paragraph 8.13)
- Initial consultation. One respondent thought this milestone should be mandatory given that the "Publication of a Request for Information” (in paragraph 8.13(d)) is a mandatory milestone[^6].
Staff view
28 In practice most projects publish a DCL. The milestone is not “mandatory” because there are some instances where it is not possible due to the urgency of an issue and the existence of reduced comment periods (which are set out by the IASB). This was the case of the project on "Covid-19-Related Rent Concessions beyond 30 June 2021". The IASB issued the Exposure Draft for this project on 11 February 2021 and comments closed on 25 February 2021. The Secretariat did not have time to publish a DCL, however, it emailed many stakeholders (preparers/accounting firms/users) asking them to provide views on specific questions and to submit comments to the Secretariat via email. The Secretariat also held meetings with stakeholders to discuss the Exposure Draft. Based on the feedback received the Secretariat created a final comment letter which was later approved by the Board. In future, consultation with advisory groups may further supplement this activity. Consequently, we think that:
- A DCL should not be a “mandatory” milestone.
- A feedback statement in paragraph 5.1(f) should be "mandatory” if a DCL is published.
29 Whilst we agree that a certain amount of consultation with stakeholders is a requirement in Regulation 8 of SI 2019/685[^7], not all outreach activities can be made “mandatory” as they should be proportionate to the significance, complexity and/or size of the project, or to its expected timeline (as mentioned in paragraphs 5.13 and 7.14 of the Handbook). Hence, not all types of outreach activities (these activities are described in paragraph 5.15 of the Handbook) can be listed as “mandatory”. For example, not all projects will receive input from ad-hoc advisory groups or undertake fieldwork because it is a narrow-scope amendment; or not all of the research outputs listed in paragraph 7.11(d)–(e) (i.e. bulletins or quantitative studies) would require outreach activities as they are written to contribute to discussions on specific issues.
30 We:
- agree that “the identification of issues for research” should be mandatory for the research programme in paragraph 7.12(a).
- agree that the feedback statement in paragraph 7.12(f) should be mandatory for research documents that invite stakeholder comments.
- disagree that the “initial consultation” milestone for a UKEB post-implementation review should be mandatory in paragraph 8.13 as implementation problems may be identified only through desk-based research and may not require consultation activities in every instance.
Issue 3. Question for the Board
| a) | Do you agree with our view that a DCL and outreach activities should not be mandatory milestones? Do you agree that a feedback statement should be mandatory if a DCL is published? (refer to paragraphs 28–29) |
| b) | Do you agree that the “identification of issues for research" should be mandatory for the research programme in paragraph 7.12(a)? Do you agree that a feedback statement in paragraph 7.12(f) should be mandatory for research documents that invite stakeholder comments? (refer to paragraph 30(a)–(b))? |
| c) | Do you agree that “initial consultation” for a UKEB post-implementation review should not be mandatory in paragraph 8.13 (refer to paragraph 30(c)? |
Issue 4—Considering whether to “pursue” a non-mandatory milestone should not be “optional”
Matters raised
31 Paragraph 1.3 of the Handbook states that the required due process steps in the Handbook (emphasis added):
1.3
- specify the mandatory milestones to be achieved and other milestones (not labelled as 'mandatory') that may also be considered, as appropriate, to achieve an overall approach to the project that is proportionate to the significance and complexity (i.e. nature or scope) of the project (i.e. relevant standard or amendment), size of the issue and the expected timeline.(...)
- identify other activities that can be undertaken to achieve the milestones set out in this Handbook. These activities should be proportionate to the issue(s) being addressed (...)
32 One respondent observed that in paragraph 1.3:
- considering whether to pursue a non-mandatory milestone should not be optional and the Board should explain why an optional milestone will not be pursued.
- the mention to ‘nature or scope' suggests significance but not complexity.
33 This respondent suggests rewording paragraph 1.3(a) and making similar amendments in related paragraphs (for example, paragraphs 5.2 and 6.11) as follows:
Suggested rewording by the respondent (new text is underlined and deleted text is struck-through):
1.3(a)
- specify the mandatory milestones to be achieved and other milestones (not labelled as 'mandatory') that may also be
pursuedconsidered, as appropriate, to achieve an overall approach to the project that is proportionate to the significance, urgency and complexity (i.e. nature or scope) of the project (i.e. relevant standard or amendment), based on a combined assessment of the nature, scope, impact, size and contentiousness of the issue, and the expected timeline (...)
Staff view
34 Regarding the proposed edits in:
- Paragraph 1.3, we disagree that the word “considered” should be replaced by "pursued" in paragraph 1.3 as the latter implies that a non-mandatory milestone has to be achieved (similar to a mandatory milestone) and this would create confusion.
- Paragraphs 5.2 and 6.11, we disagree that milestones not labelled as 'mandatory' will be always considered. Optional milestones will be considered, as appropriate, to achieve an overall approach to the project that is proportionate. Therefore, we do not propose further changes to these paragraphs.
- Paragraph 1.3, we agree with the proposed edits to explain the application of a proportionate approach (i.e. that is proportionate to the significance, urgency and complexity of the project, based on a combined assessment of the nature, scope, impact, size and contentiousness of the issue, and the expected timeline) as we think they improve the wording of this paragraph. We also agree with the cross-references to this paragraph in paragraphs 5.2 and 6.11.
35 We disagree that the Handbook should require an explanation of why an optional milestone was not undertaken. As mentioned above, the Secretariat will consider non-mandatory milestones as appropriate, to achieve an overall approach to the project that is proportionate. There may be instances where the reason why a non-mandatory milestone is not undertaken is explained, for example, to mention that an optional education session was not held[^8].
Issue 4. Questions for the Board
| a) | Do you agree with our recommendation in paragraph 35 not to replace “considered” with "pursued" and to include the improved wording to explain the application of the proportionate approach? |
| b) | Do you agree with our recommendation in paragraph 34(b) not to change paragraphs 5.2 and 6.11 of the Handbook? |
| c) | Do you agree with the proposed edits to paragraph 1.3 to explain the application of a proportionate approach (refer to paragraph 34(c))? |
Issue 5—Instances where consultation periods can be shortened
36 Paragraphs 5.22(a)–(b) of the Handbook consider the possibility that the consultation period for a DCL could be shortened to a period of less than 30 days.
5.22
- Where amendments to international accounting standards are minor and meet the IASB's criteria for annual improvements or for narrow-scope amendments; and
- Where there is limited time to consult (e.g. for an urgent narrow-scope amendment issued by the IASB where it shortens the consultation period for an exposure draft from its usual 120 days).
37 A consultation period for a DECA can also be shortened in similar circumstances to a period of not less than 14 days in accordance with paragraph 6.31[^9].
6.31 The UKEB may decide to issue a DECA with a consultation period of not less than 14 days when any of the situations described in paragraph 6.21 (a)–(b) are present.
6.21
- Where amendments to international accounting standards are minor and meet the criteria for annual improvements or for narrow-scope amendments; and
- Where there is limited time to consult e.g. for an urgent narrow-scope amendment issued by the IASB where it shortens the period between publication date and effective date of the amendment and the amendment is urgently required to be adopted by entities.
Matters raised
38 Respondents raised concerns on:
- the situations for shortening comment periods for a DCL and for a DECA.
- the length of the consultation period for a DCL and for a DECA.
Length of the shorter consultation period for a DCL and for a DECA
39 Most respondents agreed that only urgent matters (and limited to consult) should qualify for a shorter consultation period but that this should not be allowed for amendments that meet the criteria for annual improvements or for narrow-scope amendments (as these can have a far bigger impact than initially identified).
40 One respondent suggested the removal of the instances for shortening comment periods and instead recommended the Board to develop guiding principles that would allow the Board to make an assessment on a case-by-case basis.
Situations for shortening consultation periods
41 Most respondents disagreed with the length of the shortened comment periods for a DCL (less than 30 days) and for a DECA (not less than 14 days) as they thought that both comment periods were too short to be meaningful. These respondents suggested that the minimum comment period for a DCL and for a DECA should be not less than 30 days. Two respondents thought that this period could be reduced only in exceptional circumstances, for example in the event of a true emergency and/or when there are critical and/or time sensitive emerging issues that need addressing urgently.
Staff view
42 We agree that consultation periods for amendments to Standards should only be shortened when the new or amended Standard is urgent. Therefore, we propose:
- For a DCL (Section 5): Deleting paragraph 5.22(a) (that states that the comment period of a DCL can be shortened for minor or for narrow-scope amendments).
- For a DECA (Section 6): In paragraph 6.21 (and updating paragraph 6.31):
- Deleting paragraph 6.21(a) which permits a shorter comment period for minor amendments.
- indicating that the consultation period for a DECA could be shortened only when the situation described in paragraph 6.21(b) is present (i.e. when there is limited time to consult, e.g. the new or amended Standard is urgent).
- For a research document (Section 7): Amend paragraphs 7.28 to state that only when a research document is on a topic that is related or linked to an urgent project the Board may set a shorter consultation period.
- For a Request for Information (Section 8): Amend paragraph 8.24 to state that only when a Request for Information is on a topic that is related or linked to an urgent project the Board may set a shorter consultation period.
Issue 5. Questions for the Board
| a) | Do you agree with our recommendations in paragraphs 42(a)–(d) to shorten consultation periods in urgent situations? |
| b) | Do you agree with our recommendation in paragraph 43 to continue allowing a shorter consultation period for a DCL of less than 30 days and for a DECA a period of not less than 14 days? |
Issue 6—Circumstances for carrying out “minimum outreach activities" for endorsement projects
44 Paragraphs 6.21(a)–(b) describe the situations in which the UKEB carries out minimum outreach activities for endorsement activities (as discussed in Issue 5 these situations are the same for shortening the comment period for a DECA). This is:
6.21
- Where amendments to international accounting standards are minor and meet the criteria for annual improvements or for narrow-scope amendments; and
- Where there is limited time to consult e.g. for an urgent narrow-scope amendment issued by the IASB where it shortens the period between publication date and effective date of the amendment and the amendment is urgently required to be adopted by entities.
Matters raised
45 Respondents agreed with the circumstances mentioned in paragraph 6.21 for carrying out minimum outreach activities for endorsement projects. One respondent thought that the amount of outreach undertaken should also be determined by how successful the UKEB has been at the influencing stage. For example, a limited amount of outreach may be appropriate if extensive stakeholder consultation was undertaken (while the Standard was being developed) and if the issues raised had been shared with the IASB and acted upon.
46 Another respondent recommended that paragraph 6.21 includes an explicit rebuttable presumption that outreach beyond the minimum level is to be undertaken as part of an endorsement process.
Staff view
47 We disagree that “the extent of stakeholder consultation during the development of a new or amended Standard” should be added as a new circumstance for determining minimum outreach activities for endorsement activities. The endorsement and adoption phase of a project has a different objective and different criteria that need to be addressed.
48 We think that adding an explicit rebuttable presumption that outreach beyond the minimum level is to be undertaken as part of an endorsement process is not necessary because paragraph 6.23 requires the Secretariat to highlight in the Project Initiation Plan "the amount of outreach undertaken, together with the rationale”.
Issue 6. Questions for the Board
| a) | Do you agree with our recommendation in paragraph 47 that "the extent of stakeholder consultation during the development of a new or amended Standard" does not need to be added as a new circumstance for determining minimum outreach activities for endorsement activities? |
| b) | Do you agree with our view in paragraph 48 that adding an explicit rebuttable presumption that outreach beyond the minimum level is to be undertaken as part of an endorsement process is not necessary? |
Issue 7—DECA content
49 Paragraph 6.27 of the Handbook states that the main sections of the DECA are as follows (we are reproducing an extract of this paragraph):
6.27
- Introduction: legislative framework and approach to the assessment:
- (...)
- Rationale for the new or amended international accounting standard, i.e. summary background, context and objectives and main accounting requirements;
- Technical criteria assessment:
- (...)
- Whether use of the new or amended standard is likely to be conducive to the long term public good in the UK (SI 2019/685 Regulation 7(1)(b)), including: (...)
Matters raised
50 Some respondents raised the following comments:
- The content of the DECA should be focused on UK-specific issues (Issue 7A)
- The technical accounting criteria in the DECA should be aligned with the IASB's 2018 Conceptual Framework (Issue 7B)
- The assessment on long-term public good should be expanded to include the impact of non-endorsement (Issue 7C)
51 We address these issues separately in paragraphs below.
Issue 7A: The content of the DECA should be focused on UK-specific issues
Matters raised
52 One respondent thought that a DECA should not be a document that re-deliberates and re-debates specific issues that have already been considered by the IASB and that instead, it focuses on UK-specific issues that were not adequately addressed by the IASB.
53 This respondent also observed that the lengthy IFRS 17 DECA is not taken as a template going forward.
Staff view
54 We disagree with the respondent's suggestion to focus the DECA on UK-specific issues only as the content of the DECA is derived from the requirements in the UKEB's statutory instrument SI 2019/685.
55 The IFRS 17 DECA was mainly focused on UK-specific issues –the only exception being the assessment of annual cohorts which was additionally considered due to the implications to the UK's long-term public good assessment. Nevertheless, the length of the DECA will not always be the same and will vary depending on the nature, scope or complexity of the new (or amended) Standard. Consequently, we do not think that any further action is needed in this respect.
Issue 7A. Question for the Board
| a) | Do you agree with our conclusion in paragraph 54 that the focus of the DECA should not change? |
Issue 7B: The technical accounting criteria in the DECA should be aligned with the IASB's 2018 Conceptual Framework
Matters raised
56 One respondent recommends the alignment of the technical criteria for endorsement and adoption (in paragraph 6.27(c)(i) of the Handbook) with the qualitative characteristics in the revised Conceptual Framework issued by the IASB in March 2018. This is because:
- the UKEB's technical criteria give equal weight to the qualitative characteristics of financial information (i.e. understandability, relevance, reliability and comparability); whereas,
- the IASB's revised 2018 Conceptual Framework establishes a distinction between fundamental characteristics (relevance and faithful representation) and enhancing qualitative characteristics (comparability, verifiability, timeliness, and understandability).
57 We reproduce an extract of paragraph 6.27(c)(i) below:
6.27
- Technical criteria assessment:
- whether the standard meets the criteria of relevance, reliability, comparability and understandability required of the financial information needed for making economic decisions and assessing the stewardship of management (...)
Staff view
58 We disagree with the respondent's suggestion. The descriptions in the DECA are based on the qualitative characteristics that are part of the criteria for endorsement and adoption of IFRS in the EU's IAS Regulation (1606/2002), and, subsequently, were on-shored in SI 2019/685. Consequently, those characteristics cannot be aligned with the 2018 Conceptual Framework. We observe that the same respondent addressed this same point in its response to the IFRS 17 DECA[^11]. The IFRS 17 Feedback Statement[^12] observed that:
"The technical accounting criteria assessment was completed in accordance with the criteria set out in SI 2019/685, which is separate from the IASB's Conceptual Framework and does not require or indicate a weighting between criteria. On this basis no amendment was made in the final ECA for this point"
59 Based on the above, we do not recommend the Board take any further action in this respect.
Issue 7B. Question for the Board
| a) | Do you agree with our conclusion in paragraphs 58–59 that the technical accounting criteria used for endorsement and adoption should not be changed? |
Issue 7C: The assessment on long-term public good should be expanded to include the impact of non-endorsement
Matters raised
60 Paragraphs 6.27(d) of the Handbook explains that the assessment of whether use of the new or amended standard is likely to be conducive to the long term public good (LTPG) includes an assessment of:
6.27(d)
- whether the use of the standard is likely to improve the quality of financial reporting;
- the costs and benefits that are likely to result from the use of the standard; and
- whether the use of the standard is likely to have an adverse effect on the economy of the UK, including on economic growth
61 Two respondents were of the view that the LTPG assessment in paragraph 6.7(d) should additionally include consideration of the impact of non-endorsement (in full or in part).
Staff view
62 The impact of non-endorsement in full is already considered since, if a standard or amendment is not adopted in full, this is automatically the impact. The Terms of Reference of the UKEB set out that it is after a vote to adopt a standard or amendment or interpretation does not reach the required majority, the Chair may decide to ask the Board to vote on part of the standard or amendment. Consequently, the partial adoption question would only arise after adoption in full has been considered. We do not consider that this needs to be incorporated into the Handbook.
Issue 7C. Question for the Board
| a) | Do the Board agree that no changes to the Handbook are necessary on this point as explained in paragraph 62? |
Issue 8—Timeframes for completing endorsement activities
Matters raised
63 A few respondents observed that the Handbook does not mention detailed timeframes for completing endorsement and adoption projects. They think that including such timeframes is important because it would provide certainty to UK markets and would allow UK companies to prepare for the implementation of a new or amended Standard.
Staff view
64 The Handbook does not currently require the UKEB to complete the endorsement or adoption of a Standard under a certain timeframe. However, paragraph 6.15(a) (Section 6: “Project initiation Plan”) requires the Secretariat to provide a description of the proposed timeline, which we think should be sufficient. Therefore, we do not propose adding any further requirements in this respect.
Issue 8. Question for the Board
| a) | Do you agree with our recommendation in paragraph 64 not to add any requirements in the Handbook on timeframes for completing endorsement activities? |
Issue 9—Activities for meeting the objectives of thought leadership and the research programme
Matters raised
65 Some respondents suggested that the following issues should be clarified in Section 7 of the Handbook:
- Timing and frequency of engagement with UK stakeholders (Issue 9A)
- Developing the UKEB’s “own views” when 'leading the UK debate' is misleading (Issue 9B)
- Who represents the UKEB on IASB's consultative groups (Issue 9C)
- How the UKEB engages with bodies in other jurisdictions (Issue 9D)
- Why the research programme has a “problem-solving orientation” (Issue 9E)
66 We address these issues separately in paragraphs below.
Issue 9A: Timing and frequency of engagement with UK stakeholders
Matters raised
67 Paragraphs 7.2 and 7.3 in the Handbook explain how the UKEB carries out the objectives to "lead the UK debate on international accounting standards” and to "proactively participate in the development of global accounting standards”. One respondent observed that those paragraphs give no indication on the timing and frequency of the UKEB's engagement with UK stakeholders. This respondent thinks that this additional information would help manage stakeholder expectations as to the frequency and method of engagement.
68 Another respondent observed that smaller entities (i.e. entities that are not listed) sometimes do not have the resources to engage with the IASB directly, and therefore the UKEB should develop a process to engage with these stakeholders directly.
Staff view
69 The level of engagement with UK stakeholders will be project-specific and will depend on the nature, scope or complexity of the project. One of the requirements in the Project Initiation Plan (paragraph 7.18(b) of the Handbook) is to provide “a description of milestones and planned activities that will be undertaken to achieve those milestones...”. Therefore, this plan will give stakeholders an indication on the timing and frequency of the UKEB's engagement with UK stakeholders, including about its engagement with UK stakeholders that do not engage with the IASB directly. Additionally, we are setting-up advisory groups which will also provide regular input to the Board. Consequently, we do not recommend the Board take any further action in this respect.
Issue 9A. Question for the Board
| a) | Do you agree with our conclusion in paragraph 69 that the Project Initiation Plan provides stakeholders an indication on the timing and frequency of the UKEB's engagement with UK stakeholders and that no further action is needed? |
Issue 9B: Developing the UKEB’s “own views” when 'leading the UK debate' is misleading
Matters raised
70 Paragraph 7.2(a) of the Handbook states that the UKEB leads the UK debate on international accounting standards and reporting by (emphasis added):
7.2(a)
- actively engaging and collaborating with UK stakeholders on areas that concern UK stakeholders during the process of developing its own views, with the aim of building robust and evidence-based recommendations.
- (...)
71 One respondent observed that the meaning of “its own views” in paragraph 7.2(a) is ambiguous and potentially misleading as it implies that the UKEB will be interpreting Standards.
Staff view
72 We do not agree with the respondent. We consider that the phrase "during the process of developing its own views” is an intrinsic part of our thought leadership guiding principle and does not relate to interpreting standards.
Issue 9B. Question for the Board
| a) | Does the Board agree with our recommendation in paragraph 72 not to change the wording in the Handbook? |
Issue 9C: Who represents the UKEB on IASB's consultative groups
Matters raised
73 Paragraph 7.4(b) states that the UKEB directly influences the IASB Board and maintains a global presence on the international financial stage by (emphasis added):
7.4(b)
- maintaining effective relationships, communication and presence with the IASB and other national standard-setters subject to available UKEB resources.
- (...)
74 One respondent suggested that the UKEB should provide information about UK representatives attending IASB's consultative groups on the UKEB website for additional transparency.
Staff view
75 We agree with the respondent's suggestion to publish information about UKEB representatives to the IASB's consultative groups on the UKEB website, for example, the Chair is a member of ASAF. As to other UK people being a member of an IASB consultative group, we may publish such information if it is not contrary to the GDPR rules relating to the publication of personal information.
Issue 9C. Question for the Board
| a) | Do you agree with our view in paragraph 75 that information relating to UKEB representatives to the IASB's consultative groups should be on the UKEB website (unless it is contrary to the GDPR rules relating to the publication of personal information)? |
Issue 9D: How the UKEB engages with bodies in other jurisdictions
Matters raised
76 Paragraphs 7.5–7.6 of the Handbook in the Section "Engaging with other bodies in other jurisdictions" explain the interaction that the UKEB will have with bodies in other jurisdictions. These paragraphs are reproduced below:
7.5 Regular contact between the UKEB and the FRC as well as with other national standard-setters in other jurisdictions can help increase the understanding, awareness and support for UK views, thereby, allowing the UKEB to lead on the accounting debate.
7.6 The UKEB and other national standard-setters can interact in a range of ways including developing joint thought leadership and research documents, regular and ad-hoc emails, conferences and roundtables, blogs, articles, regional forums or telephone exchanges
77 One respondent observed that paragraphs 7.5–7.6 do not explain how the UKEB will engage with other bodies in other jurisdictions and suggests that those paragraphs be restructured to explain what the UKEB will be committed to do. This respondent suggested that this section should be preceded by the opening sentence “The UKEB engages with bodies in other jurisdictions by...".
Staff view
78 We disagree with the respondent's suggestion. We are unable to state how the UKEB will engage with bodies in other jurisdictions as the type of engagement will differ depending on the type of projects the UKEB is dealing with and the standard-setter we are engaging with. Therefore, we do not propose any changes to the wording in paragraphs 7.5–7.6 of the Handbook.
Issue 9D. Question for the Board
| a) | Do you agree with our recommendation in paragraph 78 not to change the wording in paragraphs 7.5–7.6 of the Handbook? |
Issue 9E: Why the research programme has a “problem-solving orientation”
Matters raised
79 Paragraph 7.7 of the Handbook explains that the objective of the research programme is as follows (emphasis added):
7.7 Research is generally directed to identify specific issues associated with projects that are on the UKEB's technical agenda. As such, research may be expected to have a problem-solving orientation by collecting evidence on the nature and extent of the perceived shortcomings of, and assessing potential ways, to improve or to remedy a deficiency in international accounting standards.
80 One respondent observed that while a 'problem-solving orientation' is to be encouraged, the UKEB must be careful not to inadvertently publish interpretation guidance or advice about issues where Standards are deficient or unclear.
Staff view
81 We consider that a problem-solving orientation for research does not lead to the UKEB issuing technical advice and/or interpretations of the Standards. We consider that no changes are required to the wording of paragraph 7.7.
Issue 9E. Question for the Board
| a) | Does the Board agree with our proposal not to change paragraph 7.7 as discussed in paragraph 81? |
Issue 10—Requirements for carrying out post-implementation reviews
Matters raised
82 A few respondents suggested that the following issues should be clarified in Section 8 ("Post-Implementation reviews") of the Handbook:
- Additional activities carried out during post-implementation reviews (Issue 10A)
- Process for carrying out subsequent reviews (Issue 10B)
- Clarifications around what constitutes a 'significant change in practice' (Issue 10C)
83 We address these issues separately in paragraphs below.
Issue 10A: Additional activities carried out during post-implementation reviews
Matters raised
84 One respondent agrees that it is appropriate for the UKEB to provide its input on an IASB's post-implementation review as required by paragraph 8.2 of the Handbook. This paragraph is reproduced below (emphasis added).
8.2 The UKEB's work on influencing the development of international accounting standards includes monitoring and responding to IASB post-implementation reviews of international accounting standards.
85 However, influencing an IASB's PIR to meet the IASB's objective for a PIR (i.e. assessing the effect of new requirements) is not the same as the objective of a UKEB PIR which is to focus on the impact of the adoption of a standard (see paragraph 8.6(a) of the Handbook reproduced below). Therefore, this respondent recommends that the UKEB's report setting out its conclusions of the (IASB's) post-implementation review (required by paragraph 8.5[^13] of the Handbook) be reinforced to include the evidence gathered by the UKEB. This evidence could be derived from its own outreach activities as well as its own findings and recommendations.
8.6 Paragraph 3 in Regulation 11 in SI 2019/385 contains a requirement to:
- 'carry out a review of the impact of the adoption of the standard' where the standard is likely to lead to a 'significant change in accounting practice'; and
- publish a report setting out the conclusions of the review no later than 5 years after the date on which the standard takes effect (being the first day of the first financial year in respect of which it must be used)'.
86 Another respondent observes that “testing the continuing relevance" of a Standard (as referred to in paragraph 8.10 of the Handbook) is not in line with the objective of a UKEB post-implementation review. Paragraph 8.10 is reproduced below (emphasis added).
8.10 When the IASB decides not to undertake a post-implementation review on a new international accounting standard and it is a significant change in accounting practice, the UKEB must perform its own post-implementation review of the standard to test its continuing relevance in line with the requirements in Regulation 11 in SI 2019/685. This should be completed no later than 5 years after the date on which the international accounting standard takes effect, in accordance with paragraph (3)(b) of this Regulation".
Staff view
87 For Standards that the UKEB did not adopt directly and that were adopted by the European Union before the Transition Period (31 December 2020) (e.g. PIRs on IFRS 9, IFRS 15 or IFRS 16), the UKEB will carry out its own influencing activities[^14] in accordance with paragraphs 8.2–8.5 of the Handbook). We expect that these activities will cover some of the aspects highlighted by the respondent (e.g. outreach activities). The UKEB is also required by paragraph 8.5 of the Handbook to explain in a separate report how the UKEB feedback was addressed by the IASB. Therefore, we do not think it is necessary to amend paragraphs 8.2–8.5.
88 For Standards that the UKEB adopted after the end of Transition Period (e.g. IFRS 17), or that the UKEB will adopt, it will apply the requirements in paragraph 8.6 of the Handbook (i.e. carry out a review of the impact of the adoption of the standard and publish a report setting out the conclusions of the review). We expect that this report will include the aspects highlighted by the respondent (i.e. evidence gathered, UKEB's own findings, recommendations and conclusions). Therefore, we do not think it is necessary to amend paragraph 8.6.
89 We agree that testing the continuing relevance of a new Standard is not an objective of a UKEB post-implementation review and consequently paragraph 8.10 should be amended to remove this objective.
Issue 10A. Questions for the Board
| a) | Does the Board agree with our conclusions in paragraphs 87–89 that no further changes are needed to the requirements in paragraphs 8.5–8.6 of the Handbook? |
| b) | Does the Board agree that paragraph 8.10 of the Handbook should be amended to remove the reference that the objective of a UKEB post-implementation review is to test the continuing relevance of a new Standard, as we recommend in paragraph 89? |
Issue 10B: Process for carrying out subsequent reviews
Matters raised
90 One respondent thinks that the Handbook should set out due process steps for deciding whether the subsequent review required in paragraph 8.7(a) of the Handbook is necessary. This paragraph is reproduced below (emphasis added):
8.7 Paragraph 4 in Regulation 11 in SI 2019/685 contains a requirement to:
- carry out subsequent reviews from time to time; and
- publish a report setting out the conclusions of any review conducted.
Staff view
91 We do not envisage situations where we will have to carry out subsequent reviews, so we are not recommending additional procedures in this respect.
Issue 10B. Question for the Board
| a) | Does the Board agree with our conclusion in paragraph 91 that no further guidance is needed in paragraph 8.7 of the Handbook? |
Issue 10C: Clarifications around what constitutes a “significant change in practice”
92 Paragraph 8.6(a) in the Handbook contains a requirement (in line with paragraph 3 in Regulation 11 in SI 2019/385) to (emphasis added):
8.6(a)
- carry out a review of the 'impact of the adoption of the standard' where the standard is likely to lead to a 'significant change in accounting practice'.
93 Paragraph 8.8 of the Handbook describes a “significant change in practice” as follows (emphasis added):
8.8 A 'significant change in accounting practice' usually occurs when a new accounting standard is issued by the IASB. A new standard meets a 'significant change in accounting practice' as it will usually have a widespread effect on many entities or a material effect on a few entities.
94 Respondents provided the following comments on paragraph 8.8:
- include, for example, IFRIC interpretations and major amendments to Standards that are considered 'significant'[^15]. Narrow-scope amendments and annual improvements are unlikely to be considered 'significant' and as such they should be exempted from the PIR requirements.
- The phrase “widespread effect on many entities or a material effect on a few entities” appears to be a presumption rather than a test that is applied to each adoption.
- The Handbook should set out the steps that the UKEB should follow to determine whether the potential impact of an amendment is considered 'widespread' enough to be considered 'significant' to UK companies. The UKEB should also explain how it reached a conclusion that a new or amended standard is 'significant' and include this explanation in the DECA.
- The adoption process should include a vote by the Board as to whether the adoption is a 'significant change in accounting practice'.
Staff view
95 We disagree that the definition of a 'significant change in accounting practice' could be broadened to include “IFRIC Interpretations” as we cannot envisage an Interpretation being a significant change in accounting practice due to its nature, i.e. being an interpretation of existing requirements.
96 We think that a “new standard” will always represent a 'significant change in accounting practice'. We agree that a major amendment could be considered 'significant'. However, whether a major amendment will always be a 'significant change in accounting practice' would ultimately be a matter of judgement and this should be indicated in the Handbook.
97 We do not agree that the meaning of a 'significant change in practice" or the term "widespread" should be further clarified in paragraph 8.8. We only suggest a few edits as follows: (new text is underlined and deleted text is struck-through):
8.8 A 'significant change in accounting practice' usually occurs when a new accounting standard is issued by the IASB. A new standard meets a 'significant change in accounting practice' when it has
as it will usually havea widespread effect on many entities or a material effect on a few entities.
98 We suggest adding the following paragraph below paragraph 8.8 of the Handbook to state that:
The Board may conclude that a major amendment constitutes a 'significant change in accounting practice'. If the Board reaches this conclusion, the UKEB will carry out a review of the impact of the adoption of the major amendment by following the requirements in paragraph 8.6 of this Handbook.
99 We disagree that the adoption process should include a vote by the Board as to whether the adoption is a 'significant change in accounting practice' because it is implicit that for new standards or for major amendments to standards, where the UKEB has indicated that it considers the new standard or major amendment to be a significant change in accounting practice, then the UKEB will carry out a PIR.
Issue 10C. Questions for the Board
| a) | Does the Board agree with our conclusion in paragraph 95 that an IFRIC Interpretation cannot be a "significant change in accounting practice" due to its own nature but that a major amendment can be a 'significant' change? |
| b) | Do you agree with our observation in paragraph 96 that concluding whether a major amendment is or not considered 'significant' would ultimately be a matter of judgement by the Board and that this should be indicated in the Handbook? |
| c) | Do you agree with our conclusion in paragraph 97 that the meaning of 'significant change in practice" or the term "widespread" should not be further clarified and that instead paragraph 8.8 could be amended by stating that: “...A new standard meets a 'significant change in accounting practice' when it has a widespread effect on many entities or a material effect on a few entities” |
| d) | Do you agree with our proposed addition to paragraph 8.8 (refer to paragraph 98) if the Board concludes that a major amendment constitutes a 'significant change in accounting practice'? |
| e) | Do you agree with our recommendation in paragraph 99 that the adoption process should not include a vote by the Board as to whether the adoption is a 'significant change in accounting practice'? |
Issue 11—Supporting the work of the IFRS Interpretations Committee
Matters raised
100 Some respondents suggested that in relation to Section 10 (“Supporting the work of the IFRS Interpretations Committee”), the Board should:
- Create a mechanism for altering IASB interpretations or agenda decisions derived from partially adopted Standards (Issue 11A)
- Publish an assessment of whether the Board will respond to a tentative agenda decision (Issue 11B)
101 We address these issues separately in paragraphs below.
Issue 11A: Create a mechanism for altering IASB interpretations or agenda decisions derived from partially adopted Standards
Matters raised
102 One respondent observed that the Board should create a mechanism for altering IASB interpretations or agenda decisions where these rely on Standards that have been partially adopted (i.e. carved out).
Staff view
103 We disagree with this view as we do not think that the UKEB will be developing due process requirements for “carved-out” situations.
Issue 11A. Question for the Board
| a) | Do you agree with our conclusion in paragraph 103 that due process requirements should not be developed for "carved-out" situations? |
Issue 11B: Publish an assessment of whether the Board will respond to a tentative agenda decision
Matters raised
104 One respondent suggested the publication of the UKEB's assessment of tentative agenda decision issued by the IFRS Interpretations Committee and whether or not the UKEB will issue a response.
Staff view
105 The Secretariat regularly briefs the Board about the matters under consideration by IFRIC and where appropriate, the Secretariat issues recommendations if further action should be taken.
106 The technical update now included as part of the Secretariat's report on “monitoring” projects (see our discussion for Issue 13C in paragraphs 118–119 of this paper) is discussed publicly and addresses the respondent's concerns. Therefore, we do not recommend the Board take any further action in this respect.
Issue 11B. Question for the Board
| a) | Do you agree that the discussion of the matters under consideration by IFRIC should be made at a public meeting and included in the Secretariat's report on "monitoring projects"? |
Issue 12—Quorum requirements for advisory groups and frequency of meetings
Matters raised
107 One respondent observed that paragraphs 9.15–9.21 of the Handbook should include quorum requirements for each advisory group and an indication of how frequently these groups should meet.
Staff view
108 We observe that the Terms of Reference for each advisory group will set out the requirements for the quorum and for the frequency of advisory group meetings. Therefore, we do not recommend the Board take any further action in this respect.
Issue 12. Question for the Board
| a) | Do you agree that the Handbook should not include requirements for a quorum and the frequency of meetings for each advisory group as those requirements will be set out in the Terms of Reference specific to each advisory group (as we observed in paragraph 108)? |
Issue 13—Other issues not addressed in the Handbook
Matters raised
109 Some respondents suggested the Board to:
- Undertake a review of the quality and effectiveness of the UKEB's activities and "lessons learned" (Issue 13A)
- Add steps for the UKEB's work on sustainability standards (Issue 13B)
- Cover the "monitoring” stage of influencing projects (Issue 13C)
- Create a process for receiving complaints (Issue 13D)
110 We address these issues separately in paragraphs below.
Issue 13A: Undertake a review of the quality and effectiveness of the UKEB's activities and "lessons learned"
Matters raised
111 Many respondents observed that the Handbook should include a new requirement to undertake a review of the quality and effectiveness of the UKEB's influencing and endorsement activities. This review could assess for example:
- Whether the UKEB has been successful in assessing the UK public good when making its endorsement decisions (for example, if the benefits and costs materialised as expected);
- Whether there are “lessons to be learned” from projects and other engagements; and
- How the UKEB could improve its processes in the future.
112 One respondent observed that such a review could be undertaken by an independent third party or by an ad hoc advisory group.
Staff view
113 We observe that the respondents' suggestion has been raised before[^16], and we think it is a valuable suggestion. We think that the proposed review might be more adequately addressed as part of the Board's effectiveness review[^17], the FRC oversight, and by the UKEB's continuous improvement efforts.
114 Consequently, we do not consider that the Handbook needs to be amended for this point.
Issue 13A. Question for the Board
| a) | Do you agree with our conclusion in paragraph 113 that the proposed review might be more adequately addressed as part of the Board's effectiveness review, and by the UKEB's continuous improvement efforts? |
Issue 13B: Add steps for the UKEB's work on sustainability standards
Matters raised
115 One respondent suggested that further processes should be added to the Handbook if the UKEB's remit extends to the work of the International Sustainability Standards Board (ISSB) on sustainability-related disclosure standards.
Staff view
116 We observe that the UK government has not yet consulted on which entity will be responsible for the endorsement and adoption of the standards issued by the ISSB. We advise that the appropriate moment to consider whether changes to the UKEB Handbook are necessary for this purpose when the UK Government finalises its approach to the adoption of ISSB standards. Any such amendments to the Handbook will be subject to formal public consultation.
Issue 13B. Question for the Board
| a) | Does the Board agree with our observation in paragraph 116 that if the endorsement and adoption of the standards issued by the ISSB is delegated to the UKEB the Handbook would have to be amended? |
Issue 13C: Cover the “monitoring” stage of influencing projects
Matters raised
117 One respondent suggests that the Handbook should include the “monitoring” stage of influencing projects as the UKEB and suggests that this is covered in Section 5 ("Influencing process”) of the Handbook.
Staff view
118 We disagree with the respondent that the “monitoring” stage of influencing projects should be covered in the Handbook.
119 The Secretariat provides regular updates to the Board about matters under consideration by the IFRIC (see paragraphs 105–106 of this paper), and by the IASB[^18]. Therefore, we do not recommend the Board take any further action in this respect.
Issue 13C. Question for the Board
| a) | Does the Board agree with our recommendation in paragraph 119 not to include separate guidance in the Handbook on “Monitoring projects"? |
Issue 13D: Create a process for receiving complaints
Matters raised
120 Two respondents recommended the creation of a process for complaints. This is for example if stakeholders think that the UKEB is acting unfairly, has breached its due process, or has not complied with a legal requirement; or, if the stakeholder wishes to appeal a UKEB adoption decision.
Staff view
121 We observe that the UKEB already has a Complaints policy which can be accessed on the UKEB's website. It has two stages: an internal review and an external review. It should be highlighted that this complaints process is not a vehicle through which a stakeholder can try to overturn or change the Board's technical decisions (see for example section 2 in the Complaints Policy[^19]).
Issue 13D. Question for the Board
| a) | Does the Board agree with our observation in paragraph 121 that a suitable complaints policy already exists and that no further action is necessary in this regard? |
Appendix 2: Other non-substantive matters
Purpose
1 This paper provides a table with a high-level summary of other non-substantive matters[^1-appendix-2] identified by respondents and our planned actions. We are not asking specific questions to the Board but we welcome any feedback on these matters.
| Area in the Handbook | Ref[^2-appendix-2] | Comments | Planned action |
|---|---|---|---|
| 1 Handbook objective | 1.1 | Expand the Handbook's objective in paragraph 1.1 Replace "assessing the appropriateness of" with "carrying out its statutory functions in respect of the adoption of" to better reflect the UKEB's role. | Agree. We will revise the objective of the Handbook. |
| 2 Education sessions | 4.10 (b) | Education sessions should not be a "UK Endorsement Board meeting" within the meaning of the ToR. | No further action. Education sessions are held in private meetings. |
| 3 Minutes for private meetings | 4.16 | Redact minutes to allow the content be made public. | No further action. Minutes from private meetings are published on the website. |
| 4 UKEB Secretariat papers | 4.19 | Add "stakeholder outreach" as another activity that the Secretariat will carry out to provide enough information for members of the Board. | Agree. |
| 5 Identification of stakeholders | 4.24 | The Handbook does not explain how the UKEB will identify stakeholders or how it will get input from them. Consider adopting the government's consultation principles here: https://www.gov.uk/government/publications/consultation-principles-guidance | No further action. Paragraph 1.3 states that the UKEB will perform the required due process steps using a 'proportionate' approach. In addition, paragraph 5.15 already describes the main types of outreach activities. The UKEB's obligation to consult is in accordance with Regulation 8 of the Statutory Instrument and in the Guiding Principles in the UKEB's Terms of Reference. We do not consider it necessary to add further principles. |
| 6 Situations in which the UKEB may consult | 4.26 | The UKEB might consult in circumstances other than the ones described in paragraph 4.26. | Agree. We will indicate that the list in paragraph 4.26 is not exhaustive. |
| 7 Governance activities—Keeping stakeholders informed | 4.27/4.28 | The UKEB is committed to keeping its stakeholders informed about its activities (per par. 4.27). All information and documents listed in paragraph 4.28 of the Handbook should be made available to stakeholders | Agree but we will amend paragraph 4.28(d) to indicate that we will provide links to IASB's or IFRIC's consultation documents open for comment but only for those that are part of the UKEB's workplan. |
| 8 Workplan should include new standards or major amendments and add UK-specific issues | 4.31 (a) | The UKEB's technical work plan as listed in this paragraph does not include influencing IASB projects that give rise to new standards or major amendments. | Agree the wording is unclear. We will include a reference to projects that could give rise to new standards or major amendments. |
| 9 Workplan: The assumption that similar issues exist in the UK needs testing with advisory groups | 4.32 | The assumption in paragraph 4.32 "...where a technical issue is significant enough to be added to the IASB's technical work plan, similar issues exist in the UK" should be tested with an advisory group in the first instance. | No further action. Testing with an advisory group will not always be necessary. |
| 10 Workplan discussion | 4.34 | Discussion of the work plan should not be at a private meeting. | No further action. Work plan discussions involve decisions on resource allocations that are currently not discussed in public. Each Project Initiation Plan has details of the timing of milestones and other planned activities that give transparency to each project. |
| 11 Workplan: explain why a project has been suspended or terminated | 4.35 | Add due process steps when a project is suspended or terminated. | No further action is needed as the steps would depend on the stage of the project we are at. |
| 12 Proportionate approach | 4.36 | Observation that in some cases minor changes or interpretations could turn out to be controversial or have much wider impact. | Noted. But we do not propose any further action. |
| 13 Influencing activities—Section 5 | 5 | Some respondents recommended that for completeness purposes all processes in other Sections of the Handbook that involve an "influencing activities" should be cross-referenced in Section 5 ("Influencing process"). | Agree. |
| 14 Proportionate approach—minor amendments | 5.3(b) | This paragraph refers that the influencing of minor amendments may be limited to an "issues paper" which is not clear what type of paper this is. | Agree. We will clarify instead, that this would involve emailing key stakeholders directly or including a request for feedback on the project's webpage._We will also add these activities to the list of outreach activities in paragraph 5.15. |
| 15 Influencing activities—PIP for AIPs and NSAS | 5.8 | It is not obvious why the Board would not also approve these Project Initiation Plans for projects that meet the criteria for annual improvements and narrow-scope amendments. | Agree. This paragraph should be changed as the Board has been approving this type of PIPs. |
| 16 Influencing activities – Include EFRAG | 5.11 | Does the reference to national standard-setters include EFRAG? | Agree. We will add a reference to "regional organisations" whenever we refer to national standard-setters. |
| 17 List of types of outreach activities | 5.15(e) | Bullet e)– the commissioning of external economic studies (i.e. data gathering and analysis conducted by external consultants to assess aspects of the economic impact of a standard on the UK. This does not appear to be an example of outreach | Disagree. This is an example of outreach as an economic study may help us to understand the issue as it relates to the UK environment. |
| 18 Influencing activities—Approval of final comment letter | 5.23 | It is not clear who approves the final comment letter. | Agree. We will mention in paragraph 5.23 that final comment letters are approved at a UKEB public meeting |
| 19 Influencing activities—Amend Feedback Statement content | 5.27/6.37 | The Feedback statement should not repeat information already included in the consultation document. | Disagree. The Feedback Statement is a stand-alone document so background information is useful to provide some context. |
| 20 Influencing activities—Feedback Statement publication | 5.29/6.39 | The feedback statement should be published before or at the same time as the final comment letter, except in very exceptional circumstances. | No further action as we cannot think of any exceptional circumstances where the feedback statement may not be published. |
| 21 Endorsement activities—Documents that are endorsed: include interpretations | 6.1, 6.9 | Paragraphs 6.1 and 6.9 should include interpretations, given that paragraph 10.6 refers to "international accounting standards and interpretations". | Footnote 2 in the Handbook indicates that the reference to international accounting standards includes Interpretations. We will amend paragraph 10.6 to include only international accounting standards. |
| 22 Endorsement activities—DECA approval | 6.24, 6.29 | It is not clear if the DECA needs approval from the Board. | Agree in principle. We think that it is implied in paragraph 6.28. However, we suggest making it explicitly in paragraph 6.29. |
| 23 Endorsement activities—Adoption statement | 6.41 | The Adoption Statement should confirm how many votes were cast and whether there was agreement (as shown on the Adoption Statement of IFRS 17) | Agree that paragraph 6.41 should require this information as this information is already in the Adoption Statement. |
| 24 Thought leadership—TL projects should be aligned with IASB's workplan | 7.1 | Thought leadership and research projects should be closely aligned to the IASB's workplan to ensure that this work informs an endorsement decision at some point. There could be other projects not directly linked to the IASB's workplan that may highlight UK specific issues. | Noted but no further action needed. |
| 25 Representing UK views (Thought Leadership)—Include engaging stakeholders on their views | 7.4 | Include "engaging stakeholders on their views" as an additional activity. | Agree. |
| 26 Research programme—DPCS | 7.12/7.31 | Unclear why a feedback statement and/or a DPCS are only applicable when stakeholder comments have been requested. | This is because some of the outputs of the research programme (e.g. bulletins) would not necessarily follow all the milestones in paragraph 7.12. |
| 27 Research programme—explain how research issues will be identified | 7.15 | Paragraph 7.15 does not explain how research proposals will be identified or received. Research projects should only be undertaken if there is a reasonable expectation of adding to existing knowledge and avoid duplicating work (from other standard-setters). | Comments noted but no further action is needed as paragraph 7.15 (second sentence) explains how proposals for research may be identified. |
| 28 PIR—Introduction | 8.1 | When mentioning that "a PIR assesses the effect of a new international accounting standard".... Should a link be inserted to legislative requirement? Or make clear that this is talking about the IASB's process | This paragraph refers to the IASB's PIR requirements, so it should be moved under the "Influencing IASB PIRs" heading. |
| 29 PIR—UKEB PIR (Second phase PIR) | 8.12/8.26 | The milestones for the second phase are outreach activities and project closure. - If the second stage is intended to collect views, wouldn't that mean that for PIRs outreach was mandatory? -And issuing a request for information is mandatory as part of the first phase. Or is this intended to be outreach other than the request for information? | Disagree—outreach activities are not mandatory consistent with other sections in the Handbook. Issuing a Request for Information is mandatory. |
| 30 PIR—UKEB PIR (PIP) | 8.14 | Not clear if the objective of the PIP to assess the need to undertake a PIR should be for all major changes (not just reviewed by the IASB) or if the assessment takes place before a PIP is prepared. | The objective of the PIP should be more closely aligned to paragraph 3 in Regulation 11 of SI 2019/685 as set out in paragraph 8.6—as that's the objective of the UKEB doing a PIR where the IASB isn't doing one. For the IASB PIR, the PIP objective is the same as for influencing as set out in paragraph 8.4. The above will be clarified in the Handbook. |
| 31 PIR—Comments on how the requirements in regulation 11 are met | 8.15 | The requirement in Regulation 9—"to publish a final decision on adopting a new or amended international accounting standard" would mean that a Standard cannot be unadopted. This makes a post-implementation review of limited purpose, other than seeking to influence the IASB. | Noted and no further action is needed. The UKEB is required to undertake post-implementation reviews in accordance with Regulation 11. |
| 32 Advisory groups—Composition: include users and preparers | 9.4 | Regulation 8 requires the UKEB to consult with users and preparers. Therefore, the UKEB should seek advice from those types of stakeholders. | Noted. During outreach activities the UKEB consults with users and preparers and no further action needed. The UKEB is in the process of creating advisory groups that will include groups of users and preparers. |
| 33 Advisory groups—summary of output should be made public | 9.16 and 9.18 | Advisory groups papers should provide as a minimum, a summary of what has been discussed at those meetings and be available publicly. | Noted but no further action needed. Paragraph 9.18 already notes that "the Secretariat will report a summary of the output from the group to the Board at a public meeting". Also as mentioned in paragraph 9.1 |
| 34 Supporting work of IFRS IC—TAD | 10.11 | Paragraph 9.16 does not explain how the views from advisory groups will be fed into the UKEB's influencing and endorsement activities and shared with the Board on a timely basis. | consulting with advisory groups is part of the targeted consultation efforts that the UKEB undertakes. |
| 35 Supporting the work of the IFRS IC—Responding to tentative agenda decisions | 10.13 | Milestones (for influencing activities) are not mandatory for tentative agenda decisions. The latter suggests that a PIP and a DPCS will not be mandatory. But Section 11 suggests a DPCS is required It is not obvious how the UKEB decides its recommendation to the Interpretations Committee. Is it a Board decision, or can it be delegated? | The milestones for tentative agenda decisions are not mandatory. Paragraph 11.1 does not indicate that a DPCS is required for tentative agenda decisions. We will revise this paragraph to avoid confusion. We will clarify that it is a Board decision. |
| 36 Due Process Compliance Statement (DPCS)—Explain process when due process steps have not been complied with | 11 | Section 11 is written on the assumption that all |