7.0 Draft Report Subsequent Measurement of Goodwill A Hybrid Model
Project Type: Research Project Scope: Limited scope
Purpose of the paper This paper presents the draft research paper on subsequent measurement of goodwill and a high-level promotional plan for its planned publication in September 2022.
Summary of the Issue The UKEB decided to undertake a limited scope research project on the subsequent measurement of goodwill. The project's objective is to contribute UKEB thought leadership to the IASB's redeliberations on its Discussion Paper Business Combinations: Disclosures, Goodwill and Impairment and to contribute to the ongoing international debate on goodwill. The IASB is expected to vote on the subsequent measurement of goodwill in Q4 2022.
Appendix 1 sets out an initial draft of the report collating the research carried out, including the proposed hybrid model, analysis of the potential implications of transition to a hybrid model for subsequent measurement of goodwill, and potential problems and solutions with the suggested model. Board members are asked to consider the analysis and provide any initial reactions or comments. We intend to incorporate these in the final report to be presented to the Board at its September meeting.
The paper also presents a high-level plan for promotion of the research report. A more detailed plan will be presented at the September meeting.
Decisions for the Board The Board is asked:
- For comments on the draft research report; and
- For comments on the high-level promotional plan.
Recommendation Board members are asked to consider the analysis and provide any initial reactions or comments on the draft report (Appendix 1) and the proposed promotional plan.
Appendices Appendix 1 Draft research paper
Background
1The UKEB's research project aims to explore the potential impact for UK stakeholders if the IASB's current impairment-only model for the subsequent measurement of goodwill were to change to a hybrid model. Under a hybrid model for the subsequent measurement of goodwill, impairment testing would be supported by an annual amortisation charge, with context provided by supporting disclosure. The UKEB Secretariat's 2021 response to the IASB's Discussion Paper Business Combinations: Disclosures, Goodwill and Impairment recommended exploring a hybrid model for the subsequent measurement of goodwill.
2The Board received a project update at its June 2022 meeting and approved an updated timeline.1 In line with the updated timeline, the draft research paper is brought to the July 2022 meeting for comment and the final research paper will be brought to the September 2022 meeting for approval to publish.
3The IASB is expected to vote on the subsequent measurement of goodwill in Q4 2022.
Draft Report
4The draft report is included at Appendix 1 to this paper. It currently includes the following sections
| Section | Heading |
|---|---|
| 1 | Significance of goodwill |
| 2 | Proposed hybrid model |
| 3 | Potential implications of a transition to a hybrid model: • Financial reporting outcomes • Feasibility • Financial stability • Audit, process, systems and cost |
| 4 | Potential problems with the proposed model and solutions |
| 5 | Conclusions |
| 6 | Potential areas for further research |
| Appendices |
5As explained at the Board's June 2022 meeting, we are conducting further outreach with users in order to obtain views on the potential for the hybrid model to improve financial reporting outcomes, specifically on whether the proposed disclosures would support management accountability for acquisitions. The draft research paper will be updated on completion of this work.
6The current conclusions are that:
- The hybrid model for subsequent measurement of goodwill merits exploration, as there is some evidence that the impairment-only model may not be working effectively.
- Field-test results indicate that a hybrid model would improve financial reporting outcomes.
- Field-test results indicate that a transition to a hybrid model would be feasible.
- Survey results and field-test results indicate that a transition to a hybrid model would be unlikely to have a significant adverse impact on financial stability.
- Survey results and field-test results indicate that the overall impact on audit, process, systems and cost of a transition to a hybrid model is not expected to be significant.
7We intend to update the following sections during July and August before the paper is finalised:
| Section | Heading | Planned Updates |
|---|---|---|
| Executive summary | Draft once other sections complete | |
| 1 | Significance of goodwill | Complete economic analysis |
| 2 | Proposed hybrid model | Final review |
| 3 | Potential implications of a transition to a hybrid model: • Financial reporting outcomes • Feasibility • Financial stability • Audit, process, systems and cost |
Include user and roundtable feedback Determine overall conclusions including user feedback |
| 4 | Potential problems of the proposed model and solutions | Develop discussion |
| 5 | Conclusions | Update for user feedback |
| 6 | Potential areas for further research | Final review |
| Appendices | Final review |
8A final report will be presented at the September Board meeting, with the intention of publication soon after.
Proposed high-level promotional plan
9At the June 2022 Board meeting, Board members asked us to consider how best to publicise the final issuance of the report. As part of that we intend to take the following high-level actions:
- We plan to share the research on subsequent measurement of goodwill with the IASB, EFRAG and other National Standard Setters. As part of that we are exploring the possibility of sharing suitable highlights at the September 2022 World Standard Setters and ASAF meetings.
- We also plan to promote the publication of the research paper via our usual channels. These include:
- Social media, UKEB website and subscriber alert
- In partnership with professional bodies and membership associations. For example, ICAEW's July 2022 edition of By All Accounts featured an article on the UKEB goodwill research project.
- As the UKEB Advisory Groups are set up, we will consider whether there are suitable opportunities to ask Advisory Group members to promote the research paper.
10We intend to bring a more developed plan for promotion to the September 2022 Board meeting.
Next steps
11The timeline for this project is set out below. We note the very limited turnaround time between the UKEB September board meeting on Friday 23 September and the start of the World Standard Setters meeting on Monday 26 September.
Timeline
12The project timeline is shown below.
| PIP approved for initial research in response to request from IASB | October 2021 |
| Initial research completed | October – November 2021 |
| Initial research presented to the Board | December 2021 |
| Initial research published and shared with IASB | December 2021 |
| PIP approved for further research into potential transitional arrangements for a potential transition to a hybrid model for subsequent measurement of goodwill | January 2022 |
| Initial user outreach | January 2022 |
| Field-testing | February – May 2022 |
| Desk-based research and economic analysis | February – May 2022 |
| Roundtables | May 2022 |
| Update to the Board | May 2022 |
| Update to the Board and approval of revised PIP | June 2022 |
| Draft research paper to the Board | July 2022 |
| Further user outreach | July 2022 |
| Paper finalisation | July – August 2022 |
| Updated paper to the Board | September 2022 |
| Publication of paper | September 2022 |
13The Board is asked:
- For comments on the draft research report; and
- For comments on the high-level promotional plan.
The UKEB does not accept any liability to any party for any loss, damage or costs howsoever arising, whether directly or indirectly, whether in contract, tort or otherwise from any action or decision taken (or not taken) as a result of any person relying on or otherwise using this document or arising from any omission from it.
© 2022 All Rights Reserved
The UK Accounting Standards Endorsement Board is an unincorporated association. Office: 1 Victoria Street, London, SW1H 0ET
- Background
- Draft Report
- Proposed high-level promotional plan
- Next steps
- Timeline
- Executive Summary
- 1. Significance of goodwill
- 2 Proposed hybrid model
- 3 Potential implications of transition to Hybrid Model
- Introduction
- Summary of key findings
- Impact on financial reporting outcomes
- Feasibility of transition
- Evidence from review of application of UK GAAP requirement to amortise goodwill
- Outreach to auditors
- Outreach to the UK GAAP regulator
- Legacy goodwill
- Outreach to auditors
- Outreach to the UK GAAP regulator
- Legacy goodwill
- Preference for retrospective or prospective application if there were to be a transition to a hybrid model for subsequent measurement of goodwill
- Materiality of legacy goodwill for UK-based IFRS reporters
- Conclusions
- Impact on financial stability
- Management compensation schemes
- Tax implications
- Market regulations
- Impact on audit, processes, systems and costs
- Operational implications
- Cost implications
- 4 Potential problems with the hybrid model and suggested solutions
- 5 Conclusions
- 6 Potential areas for further research
- Appendix 1 Shielding
- Appendix 2 History of UK financial reporting requirements for goodwill
- Appendix 2 History of UK financial reporting requirements for goodwill
- Appendix 3 Research Method
- Appendix 4 Field-test participant profiles
- Appendix 5 Survey Respondents
- Appendix 6 Outreach Events and Participants
- Appendix 7 Glossary
Executive Summary
[To be completed]
1. Significance of goodwill
Introduction
1.1The UKEB undertook research into the potential implications of a transition to an impairment and amortisation model for the subsequent measurement of goodwill.
1.2There are two primary reasons for the work:
- goodwill is a significant and growing asset in UK company accounts; and
- there is continued debate over the most appropriate way to account for goodwill.
1.3The following paragraphs provide further background information on these factors.
Significance of goodwill for UK IFRS reporters
1.4The subsequent measurement of goodwill affects the financial statements of a high proportion of UK IFRS reporters. 224 FTSE 350 companies reported goodwill in 2021. The market capitalisation of these 224 entities was £2.15 trillion, representing approximately 86% of FTSE 350 total market capitalisation.
1.5Goodwill is a significant balance for UK IFRS reporters, totalling £397bn for those FTSE 350 entities reporting goodwill for financial years ending in 2021. Goodwill represents on average 23% of total assets for those entities.
1.6Since 2005, when UK listed companies first produced financial statements in accordance with IFRS, the carrying value of goodwill for the FTSE 350 has increased by 75%.2 This overall growth in goodwill for the FTSE 350 from 2005 to 2021 reflects the value of mergers and acquisitions (M&A) deals in the FTSE 350 during that period.
1.7Goodwill is expected to increase for IFRS reporters in the UK in the short and medium term given the expected increase in M&A activity, in particular in sectors with a high price-to-book ratio3. Those sectors are expected to be significant contributors to future UK economic growth and include telecommunications, media, pharmaceuticals and biosciences, and software. The high price-to-book ratio arises because much of the perceived value of those entities is represented by items not recognised as assets under IFRS, such as intellectual capital, anticipated future growth and potential synergies. Therefore, a significant proportion of purchase price is recognised as goodwill.
1.8The subsequent measurement of goodwill is an important issue for UK stakeholders given its prevalence, its current absolute and relative size, and its anticipated future growth.
Goodwill and market capitalisation
1.9We compared the carrying value of goodwill with market capitalisation for the FTSE 350 from 2004 to 2021 in order to identify whether declines in market capitalisation arising from significant economic uncertainty led to impairments of goodwill.
1.10Despite the significant declines in market capitalisation experienced by the FTSE 350 during the 2007-2008 global financial crisis and during the Covid-19 pandemic in 2020, the carrying amount of goodwill increased.
Figure 1: Goodwill vs market capitalisation – FTSE 350
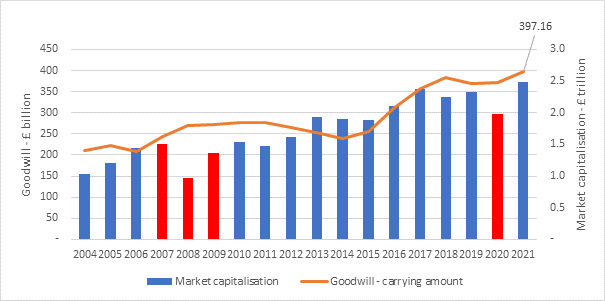
Source: Reuters-Eikon. Business cycle contractions (2007-2008 financial crisis and Covid-19) are emphasised in red based on the dates identified by the National Bureau of Economic Research: https://www.nber.org/research/business-cycle-dating.
1.11Given that the growth in goodwill during periods of market contraction could be explained by high value impairments being offset by even higher value M&A activity, we performed further detailed analysis to gain insight into the value and frequency of impairments during 2020 and 2021.
1.12Although impairments were charged during the Covid-19 global pandemic, the value and number of those impairments was perhaps lower than might have been expected during a period of significant global economic uncertainty. For the FTSE 350, annual reports for financial years ending in 2020 reported goodwill impairments of £11.9bn (3% of the carrying value of closing goodwill) and in 2021 £1.7bn (0.4% of the carrying value of closing goodwill).
1.13Further analysis shows that the sectors hardest hit by the Covid-19 global pandemic during 2020 and suffering the largest drops in market capitalisation4 did not necessarily report impairments of goodwill.
1.14The table below lists the ten FTSE 350 sectors with the largest carrying value of goodwill in 2020 and, for each of those sectors, shows the change in market capitalisation and the impairment of goodwill as a % of goodwill carrying value in 2020.
| Industry | Goodwill carrying value (£ billion) |
2020 market value change |
2020 impairment as a % of goodwill carrying value |
|---|---|---|---|
| Tobacco | 55.86 | -10.41% | 0.09% |
| Telecommunications Service Providers | 39.38 | -34.06% | 8.18% |
| Travel and Leisure | 28.47 | -12.38% | 3.32% |
| Personal Care, Drug and Grocery Stores | 27.59 | 9.82% | 0.22% |
| Oil, Gas and Coal | 24.71 | -59.18% | 0.00% |
| Media | 23.83 | -18.23% | 11.08% |
| Pharmaceuticals and Biotechnology | 19.98 | 1.85% | 0.00% |
| Banks | 18.43 | -48.14% | 0.97% |
| Industrial Support Services | 16.97 | 4.85% | 2.42% |
| Aerospace and Defense | 16.29 | -36.53% | 0.05% |
1.15Only two sectors recognised significant impairments and most sectors, including those with the largest declines in market capitalisation, did not.
1.16We also considered whether impairments might have been recognised in 2021, once the impact of the pandemic had been more fully determined. Figure 3 shows a scatterplot analysis of 2020 changes in market capitalisation against 2021 impairments. Each dot represents change in market value and impairment for a given sector. Again, most sectors experiencing falls in market value did not impair goodwill.
Figure 2: 2020 market value change vs 2021 impairments
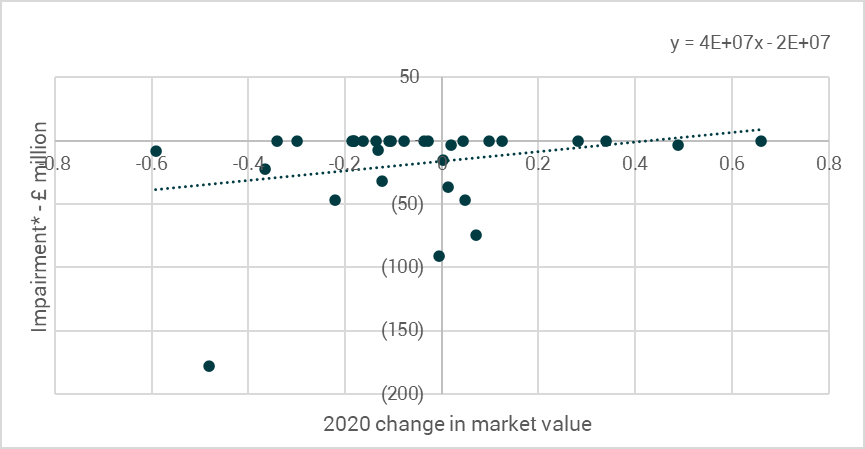
1.17At a minimum, the data indicates that it is worth investigating whether the impairment-only model is sufficiently responsive to economy wide and entity specific economic developments.
Continued debate on the subsequent measurement of goodwill
1.18The subsequent measurement of goodwill has long been a matter of debate. In recent decades, the debate has focused on the relative merits of two main models for the subsequent measurement of goodwill. These two models are the amortisation model and the impairment model.
1.19A comprehensive analysis of the arguments for and against each model is outside the scope of this paper. To provide context, however, the main conceptual arguments for and against each model are:
| For | Against | |
|---|---|---|
| Amortisation | Goodwill is a wasting asset whose benefits are consumed over time. | Estimating a useful life for goodwill is judgemental and arbitrary. |
| Amortisation reflects the underlying economics i.e., the consumption of benefits. | A default useful life does not provide useful information to users. | |
| Impairment | Provides relevant information on the subsequent performance of acquisitions. | The shielding effect5 increases the risk of overstatement of goodwill |
| Holds management to account for acquisitions. | Management optimism increases the risk of overstatement of goodwill | |
| Impairments are reported infrequently and when they are reported the information value is limited as the market has often already reflected the bad news |
1.20The difficulty in finding the best solution for the subsequent measurement of goodwill is evidenced by the following:
- The range of different reporting requirements for subsequent measurement of goodwill under IFRS, US GAAP and UK GAAP in recent decades. These have, at various stages, included amortisation only, amortisation and impairment, and impairment only models for the subsequent measurement of goodwill. For example, the financial reporting regime for subsequent measurement of goodwill changed three times for listed companies in the UK between 1984 and 2005.6
- The US FASB's current impairment-only model has led to 7 Accounting Standards Updates (ASUS).
- In spite of over 18 years of experience of an impairment-only model under IFRS, the ongoing international debate on subsequent measurement of goodwill does not appear to have abated. The topic recently featured on the FASB's agenda and currently features on the IASB's agenda.
1.21In March 2020, after 16 years of the impairment-only model, the IASB reopened the debate on the subsequent measurement of goodwill under IFRS when it published its Discussion Paper Business Combinations: Disclosures, Goodwill and
| For | Against | |
|---|---|---|
| Amortisation | Goodwill is a wasting asset whose benefits are consumed over time. Amortisation reflects the underlying economics i.e., the consumption of benefits. | Estimating a useful life for goodwill is judgemental and arbitrary. A default useful life does not provide useful information to users. |
| Impairment | Provides relevant information on the subsequent performance of acquisitions. Holds management to account for acquisitions. | The shielding effect5 increases the risk of overstatement of goodwill Management optimism increases the risk of overstatement of goodwill Impairments are reported infrequently and when they are reported the information value is limited as the market has often already reflected the bad news |
1.20The difficulty in finding the best solution for the subsequent measurement of goodwill is evidenced by the following:
- The range of different reporting requirements for subsequent measurement of goodwill under IFRS, US GAAP and UK GAAP in recent decades. These have, at various stages, included amortisation only, amortisation and impairment, and impairment only models for the subsequent measurement of goodwill. For example, the financial reporting regime for subsequent measurement of goodwill changed three times for listed companies in the UK between 1984 and 2005.6
- The US FASB's current impairment-only model has led to 7 Accounting Standards Updates (ASUS).
- In spite of over 18 years of experience of an impairment-only model under IFRS, the ongoing international debate on subsequent measurement of goodwill does not appear to have abated. The topic recently featured on the FASB's agenda7 and currently features on the IASB's agenda.
1.21In March 2020, after 16 years of the impairment-only model, the IASB reopened the debate on the subsequent measurement of goodwill under IFRS when it published its Discussion Paper Business Combinations: Disclosures, Goodwill and Impairment. The IASB's preliminary view expressed in the Discussion Paper was that the impairment-only model should be retained because there was no compelling evidence that a change was needed. However, the IASB asked stakeholders to share new information to help the Board's decision making.
1.22There were 193 responses to the IASB's Discussion Paper. 47% advocated the reintroduction of amortisation, either on its own or as part of a hybrid model.8 35% of respondents recommended retaining the impairment-only model. The remaining 18% of respondents did not conclude or recommended alternative treatments.9
1.23The main reasons cited by respondents in support of an amortisation or hybrid model were:
- Improved management accountability for business combinations through disclosures on assumptions underpinning the estimated useful life of goodwill.
- Faithful representation of those elements of goodwill whose benefits are consumed over time.
- Reduced risk of overstatement of goodwill in comparison to the impairment-only model, where the shielding effect increases the risk of such overstatement.
- Reduced risk of financial shock through delayed impairment in comparison to the impairment-only model.
- Improved comparability between entities growing by business combination and those growing organically, because in both cases the cost of growth would be charged to the statement of profit or loss, albeit that that timing of expense recognition would still be different because internally generated goodwill is expensed when incurred.
- Significant increases in the carrying value of goodwill since the introduction of the impairment-only model.
- The impairment-only model requires an annual impairment test on goodwill which could be decades old and relate to acquisitions which have long since been fully integrated. Such impairment tests may be costly for shareholders but provide little relevant information for users.
1.24This paper contributes the UK perspective to the ongoing international debate by sharing insights from our research, which analysed the potential impact of a transition to a hybrid model for the subsequent measurement of goodwill under IFRS. Information on the research methodology is set out in Appendix 3.
2 Proposed hybrid model
The hybrid model
2.1Under the proposed hybrid model:
- Goodwill would be subject to an annual amortisation charge based on an estimate of its useful life determined by management, supplemented by
- indicator-only impairment testing, and
- disclosures on management's assumptions about the useful life of goodwill to enhance management accountability for acquisitions and the relevance of information for investors.
2.2The detailed proposals and their anticipated benefits are set out below.
Amortisation and impairment
2.3Entities would be required to amortise goodwill over management's estimate of its remaining useful economic life. To support the provision of relevant information to users of financial statements, there would not be a rebuttable presumption or a maximum useful life of goodwill. However, application guidance on factors to consider in estimating the useful life of goodwill would be provided. This would include consideration of the components of goodwill, for example, synergies and value of the assembled workforce.
2.4Indicator-only impairment testing would be used to reflect the extent to which the carrying amount of goodwill is no longer expected to be recovered. Apart from requiring indicator-only impairment testing rather than an annual impairment test, the methodology for impairment testing would be the same as that currently set out in IAS 36 Impairment of Assets.
Disclosures
2.5Subject to usual materiality constraints, entities would be required to disclose:
- For each acquisition, or group of acquisitions with similar characteristics, management's estimate of the useful life of goodwill and the assumptions underpinning the estimate, including:
- identification and explanation of the factors considered in estimating a useful life of goodwill and how a weighting was assigned to each factor.
- if goodwill was analysed into components, the value ascribed to each component and the factors considered and assumptions made in estimating a useful life for that component.
- An analysis of total goodwill in a single table, disclosing separately for each business combination, or for groups of business combinations with similar characteristics:
- Gross goodwill.
- Acquisition date.
- Accumulated amortisation at the start of the most recent reporting period.
- Accumulated impairments at the start of the most recent reporting period.
- Impairments charged during the most recent reporting period.
- Amortisation charge for the most recent reporting period.
- Opening carrying value at the start of the most recent reporting period.
- Closing carrying value at the end of the most recent reporting period.
- Total amortisation charged during the financial period, the line(s) in the statement of profit or loss where it is included, and the amount included in each line.
Anticipated benefits of the hybrid model
2.6The main anticipated benefit of the proposed requirement to amortise goodwill over its useful life as estimated by management is improved relevance of financial information through faithful representation of the consumption of economic benefits. Section 3 below includes stakeholder feedback on anticipated benefits of a transition to a hybrid model.
2.7Impairment testing would continue to provide relevant information where the carrying amount of goodwill is no longer expected to be recovered.
2.8The proposed disclosures would provide insight into:
- The rationale for the business combination.
- Management's assumptions about the service potential of goodwill.
- The age and make-up of goodwill.
2.9These insights would help investors to engage with management on the subsequent performance of acquisitions and therefore increase management accountability for those acquisitions.
2.10Disclosures on the presentation and amount of the amortisation charge would allow investors to easily identify that charge.10 This would allow investors to adjust for amortisation charges in models and metrics, for example in cash-flow forecast models and return on invested capital metrics.
2.11The potential implications of a transition to a hybrid model for the subsequent measurement of goodwill under IFRS are analysed in Section 3. Potential problems arising from the UKEB's proposed hybrid model together with potential mitigations and solutions are discussed in Section 4 below.
3 Potential implications of transition to Hybrid Model
Introduction
3.1This section analyses the results of our research into the potential implications of a transition to a hybrid model for subsequent measurement of goodwill. Our research methodology is set out in Appendix 3. The four areas within the scope of the project and how we tested them are as follows:
- Effect on financial reporting outcomes – in particular, we present stakeholder views on accountability, faithful representation, relevance and comparability. We tested this through field-testing with preparers and through outreach with auditors, academics and users.
- Feasibility – including the feasibility of estimating a useful life of goodwill, the factors considered when estimating a useful life of goodwill, and how to deal with legacy goodwill. The materiality of transitional impacts was also considered. We tested this through field-testing with preparers and through outreach with auditors, academics and users.
- Impact on financial stability – including the potential impact on loan covenants, tax revenues, compliance with market and other regulatory rules, and management compensation schemes. We tested this through a survey to preparers and desk-based research.
- Audit, processes, systems and costs – potential impact on audit, processes, systems and costs. We tested this through a survey to preparers, field-testing, and outreach to auditors.
Summary of key findings
[To complete once user outreach complete]
Impact on financial reporting outcomes
3.2The following paragraphs analyse submissions from field-test participants.
3.3Nine UK entities preparing financial statements under IFRS participated in field-testing. The entities were from the following sectors: financials, consumer discretionary, utilities, industrial, and consumer staples. Of the nine entities, seven are FTSE 100 listed, one is FTSE 250 listed, and one is AIM listed.
3.4The field-test submissions consisted of financial statement extracts, sample disclosures and completed questionnaires.
3.5The majority of field-test participants anticipate improved financial reporting outcomes from a potential transition to a hybrid model for subsequent measurement of goodwill.
3.6Field-test participants anticipated the following financial reporting outcomes from the application of the UKEB's proposed hybrid model:
| Preparers11 | Hybrid model would better reflect underlying economics | Hybrid model would mitigate the shielding effect | Hybrid model would provide more relevant information for investors | Hybrid model would improve comparability |
|---|---|---|---|---|
| A | ✓ | ✓ | ||
| B | ✓ | ✓ | ✓ | ✓ |
| C | ✓ | ✓ | ✓ | ✓ |
| D | ✓ | ✓ | ✓ | ✓ |
| E | ? | ? | ? | ? |
| F | X | X | ✓ | X |
| G | ✓ | X | ✓ | X |
| H | ✓ | X | ? | |
| I | ? | ✓ | ? | ✓ |
Key: ✓ = Yes X = No ? = Maybe
3.7Preparers made the following observations in support of the proposed hybrid model:
"We believe the amortisation model better reflects the underlying economic value of goodwill. It would reflect consumption of goodwill through time as for any other asset with a finite useful life."
"The estimate of each useful life should be specific to each acquisition, there should not be a blanket approach."
"The useful life would likely be a critical judgement which would need to be explained."
"We would support this approach, primarily based on perceived improved information for investors.” "This would allow for more consistent reporting of goodwill in line with other intangibles.” “We believe that the existing approach of impairing goodwill is superior, because the impairment approach results in better stewardship and holds management to account for their investment decisions." “Determining the useful life of goodwill could be very subjective, but no less subjective than judgements involved under the impairment-only model.” 3.8Field test participants and other stakeholders identified the following financial reporting outcomes from the application of a hybrid model:
3.9Amortisation of goodwill would provide a more faithful representation of profitability and asset values by reflecting the consumption of economic benefits.
- Disclosures on management's assumptions used to determine the useful life of goodwill would provide relevant information to investors. This information would help investors to engage with management on the subsequent performance of acquisitions.
- Comparability between those entities growing organically and those growing by acquisition would improve, as the cost of growing the entity would be charged to the statement of profit or loss in both cases.
- Charging amortisation through the statement of profit or loss gives a better indication of future sustainable profits than the impairment-only model, because it captures the full cost of generating current profits.
- Goodwill would no longer be shielded through allocation to large cash-generating units or groups of cash-generating units. Subject to usual materiality constraints, the useful life of goodwill arising on each acquisition would be determined. This would reduce the risk of overstatement of goodwill. It would also improve consistency with the financial reporting treatment of other types of asset, which are separately measured for impairment rather than measured for impairment in a cash-generating unit together with other assets.
[To insert when complete – results of outreach to users of accounts NB to date users have told us that; * The proposed disclosure analysing goodwill by acquisition and date would help to improve management accountability for acquisitions. They also noted that sub-totals in the table showing how goodwill is allocated to segments would be helpful. * The proposed roll-forward of acquisitions would also help management accountability for acquisitions * However, users have observed that they do not see goodwill as a wasting asset, but more like other indefinite-life intangible assets, and so would be sceptical about the useful life of goodwill]
Feasibility of transition
Feasibility of estimating the useful life of goodwill
3.10The field-test questionnaire asked participants to identify whether it would be: (i) easy, (ii) challenging but possible, or (iii) practically impossible to estimate a useful life of goodwill.
3.11The majority of field-test participants considered it would either be easy, or challenging but possible, to estimate a useful life of goodwill for amortisation purposes.
3.12The remaining respondents (three) who identified that it would be practically impossible to estimate a useful life of goodwill fell into two categories:
- The first category agreed conceptually that goodwill had a finite useful life but observed that it would be difficult to estimate that useful life without application guidance or established practice. We note, however, that:
- These entities had estimated a useful life of goodwill in their 2004 financial statements prior to the introduction of IFRS, and
- Entities in the same sector reporting under UK GAAP currently estimate a useful life of goodwill.
- The second category held the view that goodwill is not a wasting asset, because:
although the benefits of the original goodwill may have been consumed, expenditure on the acquired business will have replaced it. We do not support this argument because:
- There is no established conceptual basis in IFRS for subsequent measurement of an asset measured at original historic cost where the original benefit has been consumed but replaced through other expenditure.
- This approach effectively capitalises internally generated goodwill and capitalising internally generated goodwill is not permitted under IFRS.
- Synergies comprise a significant proportion of the value of the goodwill, and in their view synergies have an indefinite useful life.
- Legal, regulatory and contractual provisions affecting the useful life of the acquired business.
- Expected timing of realisation of anticipated income synergies.
- Expected timing of the realisation of cost synergies.
- Expected useful life of benefits acquired which are not recognised separately from goodwill (e.g., value of assembled workforce, synergies).
- Expected useful life of assets acquired and recognised under IFRS.
- Period over which an acquired product is expected to be viable in a market.
- Nature of the acquired business.
3.14Field test participants and auditors noted that if the IASB were to introduce a hybrid model for subsequent measurement of goodwill, they would welcome application guidance including examples of factors to consider when determining the useful life of goodwill.
[To insert when complete – results of outreach to users of accounts NB users to date have told us that they do not see goodwill as a wasting asset so they are sceptical about the informational benefit of an estimated useful life]
Components of goodwill
3.15The field test asked participants to analyse the carrying value of goodwill in their latest financial statements by business combination, subject to usual materiality constraints.
3.16The field-test further asked participants to apply the following approach when estimating the useful life of goodwill, if they considered the approach relevant and feasible:
- Identify the main components of goodwill arising on each business combination. Examples of those components are cost and revenue synergies, and value of assembled workforce.
- Value those components of goodwill.
- Estimate a useful life for each of those components.
- Use the estimated lives of the components of goodwill in calculating the amortisation charge for goodwill on each business combination.
3.17Two out of nine field test participants applied this approach (see paragraphs 3.21 and 3.22).
3.18Of the remaining seven participants, one identified the main components of goodwill arising on each business combination and disclosed them but did not separately value them or estimate their useful lives (see Entity C in section below on methods used by field-test participants to estimate the useful life of goodwill).
3.19The remaining six participants did not consider that it was practicable or desirable to identify the components of goodwill arising on a business combination. Their rationale was that:
- Goodwill is a single item.
- Goodwill is already a residual.
- Valuing components would be very arbitrary and subjective.
- The cost would outweigh the benefits.
- Negotiating ability would not be captured.
[To insert when complete – results of outreach to users of accounts NB users to date have told us that it is helpful to understand what the components of goodwill are but that valuing them separately is over-sophisticated]
Views on setting a maximum and a minimum useful life for goodwill
3.20Field test participants observed that setting a maximum or a minimum useful life for goodwill would partially negate the anticipated improved financial reporting outcomes of improved relevance and more faithful representation.
3.21However, there was support for a 'backstop' model where, if management is unable to determine the useful life of goodwill reliably, there is a cap on the period over which goodwill is amortised.
[To insert when complete – results of outreach to users of accounts]
Examples of methods used by field-test participants to estimate the useful life of goodwill and treatment of legacy goodwill
3.22Entity A used the following approach to determine the useful life of goodwill on a recent acquisition and to calculate the amortisation charge:
- Applied a valuation model approved by its board and used by advisers that assisted during a recent material acquisition.
- Used the valuation model to identify components of goodwill and to value them. The components identified were the assembled workforce, anticipated cost synergies and anticipated margin uplift. The value of goodwill was allocated to these components in the following proportions: assembled workforce – 63%; cost synergies – 3%; margin uplift – 34%.
- Estimated a useful life of the assembled workforce based on expected remaining service and knowledge transfer.
- Estimated a useful life of anticipated cost synergies based on the expected realisation period for those synergies.
- Determined a useful life for anticipated margin uplift based on expected period of access to a specific market.
- Performed a weighted average calculation to arrive at an annual amortisation charge.
- Fully amortised in year one the excess of goodwill over the combined valuation of specific components of goodwill.
- Used the practical expedient of amortising legacy goodwill over the same period as that arrived at in the methodology outlined in a) to g) above.
3.23Entity B used the following insights and approach to estimate the useful life of goodwill on recent acquisitions:
- Identified that the main components of goodwill were synergies, value of the assembled workforce and access to a network.
- Used the valuation undertaken at acquisition to value the assembled workforce and synergies. The remaining portion of goodwill was deemed to be the value of access to a network.
- The estimate of the useful life of the assembled workforce was based on employee churn data.
- Synergies were amortised over the same time period used for cash flow forecasts in the business case for the acquisition.
Entity B example disclosure
In determining the consideration the group is willing to pay for the company being acquired the group identifies revenue and cost synergies which it expects to achieve through the business combination, which include, but are not limited to, shared maintenance, operations and procurement.
Synergies arising upon the acquisition of subsidiaries are initially recognised at fair value at the date of acquisition and then amortised over the period that synergies were expected to be generated in the business case for the acquisition (x years).
Assembled workforce arising on the acquisition of a subsidiary is initially valued at fair value on the acquisition date and amortised over the period of expected staff turnover within that subsidiary (x years).
3.24Entity C used a valuation model which determines the period of time over which returns are expected to exceed the cost of capital. Entity C used this period of time as the useful life of goodwill and amortised goodwill on a straight-line basis.
Entity C example disclosure
Goodwill of £xxm was recognised, which is attributable to the anticipated increase in revenues arising from a strengthened market position and greater critical mass, and the anticipated future operating cost synergies arising from the elimination of duplicated back office and support functions.
For the period ended 31 December 2021, the amount of amortisation of goodwill charged is £xxm. This is included in the 'operating expenses before credit impairment write-backs / losses, provisions and changes' line in the statement of profit or loss.
3.25Entity D's illustrative disclosures under the hybrid model provided insight into the strategic rationale for each material acquisition. These factors included access to new markets, value of assembled workforce, cost synergies and expected useful life of underlying assets acquired. Entity D recommended that where the useful life of goodwill cannot be determined with certainty, its useful life should not exceed 10 years. Entity D concluded that the useful life of the identified factors could not be determined with certainty and amortised goodwill over 10 years.
Example D example disclosure
The acquisition was a long-term strategic investment expected to create value for the ABC group through revenue growth.
The following have been considered in the assessment of useful life of goodwill:
- The expected benefit of the strengthened customer proposition that owning the DEF group brings.
- The assembled workforce and its existing customer relationships which will generate income going forwards.
[To insert when complete – results of outreach to users of accounts]
Evidence from review of application of UK GAAP requirement to amortise goodwill
3.26The UK GAAP requirements for subsequent measurement of goodwill are specified in The Financial Reporting Standard Applicable in the UK and Republic of Ireland (FRS 102).
3.27FRS 102 states that ‘After initial recognition, the acquirer shall measure goodwill acquired in a business combination at cost less accumulated amortisation and accumulated impairment losses. Goodwill shall be considered to have a finite useful life, and shall be amortised on a systematic basis over its life. If, in exceptional cases, an entity is unable to make a reliable estimate of the useful life of goodwill, the life shall not exceed 10 years.'
3.28To understand how the useful life of goodwill is estimated under FRS 102, we:
- Reviewed a sample of UK GAAP financial statements to understand individual application.
- Conducted structured interviews with audit firms to understand the audit perspective.
- Conducted outreach to the UK GAAP regulator12 to understand general application.
Review of UK GAAP financial statements
3.29Analysis of the financial statements of the UK's 100 largest private companies showed that 48 of those companies report under FRS 102. Of those 48 companies, 34 included goodwill in their most recent financial statements.
3.30Analysis of goodwill and related disclosures in those 34 annual reports showed:
- The highest reported goodwill was £628m and the average was £48m. By comparison, the average goodwill reported by FTSE 350 and AIM entities in 2020 was £366m. Therefore, the larger private company goodwill balances are comparable in size to those reported at the smaller end of the listed market.
- There were varying approaches to estimating the useful life of goodwill:
- Some companies amortised goodwill on the same straight-line basis for all acquisitions. Goodwill was amortised over 10 years (9 companies), 20 years (5 companies) and 5 years (2 companies).
- Some companies determined a useful life of goodwill that exceeded ten years for at least some of their acquisitions. Given the UK GAAP requirement to amortise goodwill over less than ten years if an entity cannot estimate its useful life reliably, this evidence suggests that, although estimating the useful life of goodwill includes an element of judgement, in half of the cases reviewed, management can reliably estimate the useful life of goodwill.
- Disclosures indicated that in some cases specific circumstances and factors had been considered in the estimation of the useful life of goodwill:
- 10 companies estimated different useful lives of goodwill for different acquisitions and disclosed the range of those useful lives, but did not disclose the useful life of goodwill on each acquisition. The ranges disclosed were: 4 – 20 years (1 company), 5 – 20 years (5 companies), 10 - 20 years (2 companies), and up to 20 years (2 companies).
- 4 companies disclosed the useful life of goodwill for each business combination. The useful lives disclosed were 1 year, 7 years, 19 years, and 50 years. This implies that specific factors are, in at least some cases, considered in the determination of the useful life of goodwill.
- Where the useful life was determined for individual acquisitions, disclosures indicated that a range of relevant factors was considered in that determination. These included:
- strength of brand;
- products and services provided;
- competition and expected future performance;
- expected use of acquired assets13; and
- any legal, regulatory, or contractual provisions that may limit the useful life.
- The useful life was typically longer for the food retail and motor services sectors, while the entities in the construction, retail, leisure and hospitality sectors had shorter useful lives. The useful life was typically longer in the luxury goods sector and where acquisitions had delivered technological capability or online presence. Whilst not conclusive, this evidence suggests that factors specific to the sector and type of business are considered when determining the useful life of goodwill.
Outreach to auditors
3.31We conducted structured interviews with auditors of FRS 102 reporters to ascertain the types of audit evidence they seek on management's estimate of the useful life of goodwill, and how that evidence is challenged.
3.32Auditors gain sufficient and appropriate audit evidence on the useful life of goodwill by applying ISA 540 Auditing Accounting Estimates and Related Disclosures, which was revised for accounting periods beginning on or after 15 December 2019 to provide more extensive guidance on the audit of accounting estimates.
3.33Audit firms highlighted to us that since the revision of the ISA and consequent increased audit challenge in this area, there has been increased use of expert input from business valuation specialists as audit evidence on the useful life of goodwill.
Outreach to the UK GAAP regulator
3.34Discussions with the UK GAAP regulator (the FRC) indicated that it does not generally need to consider issues on how to estimate the useful life of goodwill under FRS 102. It appears, therefore, that the application of FRS 102 on goodwill is not generally problematic.
Legacy goodwill
3.35Field test participants views on legacy goodwill are summarised in the table below:
- The useful life was typically longer for the food retail and motor services sectors, while the entities in the construction, retail, leisure and hospitality sectors had shorter useful lives. The useful life was typically longer in the luxury goods sector and where acquisitions had delivered technological capability or online presence. Whilst not conclusive, this evidence suggests that factors specific to the sector and type of business are considered when determining the useful life of goodwill.
Outreach to auditors
3.31 We conducted structured interviews with auditors of FRS 102 reporters to ascertain the types of audit evidence they seek on management's estimate of the useful life of goodwill, and how that evidence is challenged.
3.32 Auditors gain sufficient and appropriate audit evidence on the useful life of goodwill by applying ISA 540 Auditing Accounting Estimates and Related Disclosures, which was revised for accounting periods beginning on or after 15 December 2019 to provide more extensive guidance on the audit of accounting estimates.
3.33 Audit firms highlighted to us that since the revision of the ISA and consequent increased audit challenge in this area, there has been increased use of expert input from business valuation specialists as audit evidence on the useful life of goodwill.
Outreach to the UK GAAP regulator
3.34 Discussions with the UK GAAP regulator (the FRC) indicated that it does not generally need to consider issues on how to estimate the useful life of goodwill under FRS 102. It appears, therefore, that the application of FRS 102 on goodwill is not generally problematic.
Legacy goodwill
3.35 Field test participants views on legacy goodwill are summarised in the table below:
| Preparers13 | How easy would it be to analyse legacy goodwill by business combination? | Does legacy goodwill consist of a large number of individually immaterial balances? | Is legacy goodwill material as a % of net assets?14 | Would amortisation of legacy goodwill be likely to have a material impact on profit after tax?15 | If there were a transition to a hybrid model, would prospective or retrospective application be preferable? | Should there be a choice of prospective or retrospective application? |
|---|---|---|---|---|---|---|
| A | Easy | N | Y | Y | Retrospective | No |
| B | Easy | Y | Y | Y | Retrospective | No |
| C | Easy | N | N | N | Retrospective | No |
| D | Easy | N | N | N | Retrospective | Yes |
| E | Easy | N | N | N | Choice | Yes |
| F | Easy | N | Y | Y | Retrospective | No |
| G | Easy | N | Y | Y | Retrospective | No |
| H | Challenging but possible | Y | Y | Y | Prospective (practicability) | Yes |
| I | Easy | Y | Y | Y | No response | No response |
3.36 Almost all (8 out of 9) field-test participants stated that it was easy to identify the dates and business combinations to which legacy goodwill related. One entity stated that this exercise would be challenging but possible, due to the large number of business combinations which made up its legacy goodwill balance.
Preference for retrospective or prospective application if there were to be a transition to a hybrid model for subsequent measurement of goodwill
3.37 If applied prospectively, the hybrid model would be applied to legacy goodwill from the effective date forwards. If applied retrospectively, the hybrid model would be applied from the date of the business combination.
3.38 Field-test participants were asked whether, in the event of transition to a hybrid model, they thought prospective or retrospective application of the hybrid model would be preferable.
3.39 The majority view was that retrospective application was preferable. Participants noted that:
- prospective application would not necessarily provide a faithful representation, because the benefits of legacy goodwill may already have been consumed; and
- retrospective application would allow for improved comparability between entities from the effective date forward.16
3.40 The majority view was also that there should not be a choice between retrospective and prospective application. Participants felt that mandating retrospective application would lead to greater comparability than allowing a choice between retrospective and prospective application.
3.41 However, most participants noted that practical expedients would be necessary for retrospective application, because:
- The information required to determine a useful life of goodwill may not be available for historic acquisitions, due to systems and data retention policies at the time of the acquisition and employee turnover since the acquisition.
- Management may have limited ability to determine the useful life of goodwill without hindsight i.e., using only the information which would have been available at the date of the acquisition.
3.42 The most frequently recommended practical expedient for retrospective application was a default amortisation period for legacy goodwill.
3.43 One participant also supported the practical expedient of a write-off to reserves in the period when the business combination took place.
3.44 Two field-test participants recommended that if retrospective application were used, the adjustment should be made to opening reserves of the current reporting period, and full restatement of comparatives should not be required.
[To insert when complete – results of outreach to users of accounts]
Materiality of legacy goodwill for UK-based IFRS reporters
3.45 The materiality of legacy goodwill does not appear to influence field-test participants' views on the anticipated financial reporting outcomes of a potential transition to a hybrid model for subsequent measurement of goodwill. Despite potentially material impacts on reported net assets and reported profit, the majority of field-test participants anticipated improved financial reporting outcomes if there were to be a transition to a hybrid model.
3.46 Field-test participants with immaterial legacy goodwill were more likely to recommend that a choice of retrospective or prospective application should be permitted if there were a transition to a hybrid model. It is possible that the immateriality of legacy goodwill for these participants led them to conclude that more choice in the treatment of legacy goodwill would be acceptable, because where legacy goodwill is immaterial there is a lesser impact of different treatments on comparability.
Conclusions
3.47 Potential changes to the subsequent measurement of goodwill are likely to have material impacts for IFRS reporters in the UK, if adjustment of existing balances is required on transition to the new requirements.
3.48 Whilst the field test indicates that it is possible to estimate the useful life of goodwill, the appetite for a backstop or guard rails suggests that protections against arbitrary lives are needed if amortisation is to be introduced. Application Guidance would need to be robust to avoid too much variation in practice and consideration would need to be given to the extent to which such guidance would of necessity become detailed and rules-based, and the extent to which it would be principle-based.
3.49 If there were a transition to a hybrid model, retrospective application should be required for legacy goodwill balances, since this would be the most faithful representation of benefits already consumed. Practical expedients should also be permitted.
3.50 However, even if changes to the subsequent accounting for goodwill lead to material impacts on transition, we do not support deferral of those changes because if the growth trend in goodwill continues at the current pace17, transitional impacts will only increase in future.
Impact on financial stability
Covenants
3.51 Our public survey18 included questions on financial loan covenants. The objective of these questions was to establish whether potential changes to the subsequent measurement of goodwill could lead to breaches of such covenants.
3.52 15 out of the 23 respondents to our public survey for UK IFRS preparers completed the covenants section. Others declined to complete that section because they deemed the information requested as confidential. Respondents who completed the covenants section of the survey have a combined market capitalisation of £290bn, representing 11% of FTSE 350 market capitalisation. Their combined goodwill totals £49bn, representing 13% of FTSE 350 combined goodwill.19
3.53 Of the respondents to the covenants section, 87% (13 respondents) affirmed that covenants use IFRS-based measures.
3.54 Of these 13 respondents:
- eight stated that the IFRS-based measures in covenants include goodwill and are taken directly from the financial statements;
- one stated that the IFRS-based measures in covenants are derived from the financial statements but adjusted to exclude goodwill; and
- four stated that covenants used both types of IFRS-based measure.
3.55 We asked whether IFRS-based measures in covenants were based on frozen GAAP. Of the respondents to the covenants section, 47% (seven respondents) stated that IFRS-based measures in covenants were based on frozen GAAP.20 Another 47% (seven respondents) stated that IFRS-based measures in covenants were not based on frozen GAAP. 6% (one respondent) did not answer this question.
3.56 We further asked whether covenants allow for re-negotiation when there are changes to financial reporting standards. 80% (12 respondents) of the respondents to the covenants section of our survey stated that covenants do not allow for renegotiation when there are changes to financial reporting standards. 20% (three respondents) stated that covenants allow for re-negotiation when there are changes to financial reporting standards.
3.57 Based on our survey results, potential changes to the subsequent measurement of goodwill are associated with an increased risk of breach of covenants. The impact cannot be quantified without further information on current headroom and more comprehensive data on specific covenant terms. However, follow-up discussion with respondents identified that in practice, covenants which did not use frozen GAAP would be likely to be renegotiated in the event of changes to IFRS.
3.58 Some respondents noted that changes to credit ratings may impact loan covenants. We were informed that ratings agencies typically exclude goodwill in their rating methodologies, we do not anticipate that this would typically impact loan covenants.
3.59 Several respondents from the insurance sector noted that loan covenants are typically based on their Solvency II position rather than on IFRS-based measures. There were no other discernible trends by sector, size of entity, reported goodwill or number of acquisitions in the responses to our survey questions on covenants.
Management compensation schemes
3.60 Some survey respondents highlighted that potential changes to the subsequent measurement of goodwill could impact management compensation schemes. Through follow up discussion with survey respondents, we identified that remuneration committees will typically discuss and agree on any necessary adjustments to IFRS-based performance measures in management compensation schemes if there are changes to IFRS Standards. Given lead-times for the implementation of new IFRS Accounting Standards, there is sufficient time for adjustments to be made. We do not foresee significant impact on management compensation schemes arising from potential changes to the subsequent measurement of goodwill.
Tax implications
3.61 Transitioning to a hybrid model for the subsequent measurement of goodwill under IFRS would generally not directly impact tax payable by UK IFRS reporters and their UK-based subsidiaries.
3.62 This is because for UK companies accounting amortisation of goodwill is generally not deductible for corporation tax purposes. However, the position is complex in relation to some legacy goodwill, depending on when it arose, and for non-UK based subsidiaries, different tax regimes may of course apply.
Market regulations
3.63 Our outreach and desk-based research have not identified an increased risk of failing to meet market regulations if there were changes to the subsequent measurement of goodwill.
3.64 Where market regulations include tests of gross assets, capital and profits to determine whether additional disclosure is required21 these tests are applied to asset and profit values at the time the test is required. Therefore, retrospective application of potential changes to the subsequent measurement of goodwill would not increase the risk of compliance failure. Prospective application may lead to increased disclosures relating to acquisitions in future.
3.65 Several respondents to our public survey for IFRS preparers from the insurance sector noted that changes to the subsequent measurement of goodwill would not impact Solvency II compliance, since goodwill is already excluded from Solvency II ratios.
Impact on audit, processes, systems and costs
3.66 In our survey to IFRS preparers we asked about the impact of a potential transition to a hybrid model for subsequent measurement of goodwill on processes, systems and costs. The findings from the survey are summarised below.
Operational implications
3.67 The majority (71% / 16 responses) of responding organisations said that they would not anticipate significant operational changes if there were a transition to a hybrid model for the subsequent measurement of goodwill. One field-test participant commented,
“We have systems and processes in place already for other tangible and intangible assets that are accounted for at cost less accumulated depreciation and accumulated impairment losses. Should a hybrid approach be introduced, goodwill can be embedded into the existing reporting environment to allow amortisation going forward.”
3.68 These respondents identified that they would expect some change in the following operational areas if the potential transition to a hybrid model were to go ahead: (i) processes and procedures, (ii) audit, (iii) staff training and (iv) investor relations. One respondent commented that,
"There would also be a need to train/educate investors and users of our financial reports on the change in our reporting, given the non-cash nature of the charge."
3.69 The remaining respondents (39% /seven responses) said that they anticipated significant operational changes if there were a transition to a hybrid model. These respondents identified that significant changes would be needed to the following areas: processes and procedures, audit, data, staff training and systems and technology. One field-test participant commented,
“To get the judgements involved in estimating the useful life of goodwill through SOX level reviews, we would anticipate having to provide a significant amount of information.”
3.70 Respondents anticipating significant operational changes if there were a transition to a hybrid model did not report higher numbers of acquisitions in the last five years or higher goodwill.
3.71 One field-test participant commented:
"We think auditors would want to do full impairment test anyway. It is therefore unlikely that there would be a saving on the audit of goodwill impairment. Management and the audit committee also wouldn't want to look at an indicator-only approach for impairment."
Cost implications
3.72 When asked about the anticipated cost impact of a potential transition to a hybrid model, 39% of survey respondents anticipated either a substantial reduction, a minor reduction, or minimal or no impact on costs. The respondent who anticipated a substantial reduction in costs cited ongoing cost reductions in processes and procedures as the underlying reason.
3.73 48% of respondents anticipated a minor increase in costs and 13% of respondents anticipated a significant increase in costs. Approximately one third of the respondents anticipating a minor increase in costs attributed this to one-off implementation costs rather than ongoing costs.
3.74 Of the 13% of survey respondents anticipating a significant increase in on-going costs cited audit, staff training and additional expert resource as underlying reasons. Two thirds of these respondents anticipated increases in implementation costs and ongoing costs. The implementation costs related to developing a model for estimating useful life of goodwill and a methodology for revising it for future acquisitions.
3.75 Respondents anticipating cost increases did not report higher numbers of acquisitions in the last five years or higher goodwill.
3.76 One field-test participant commented that additional costs could arise for training, development of consolidation systems, and ongoing resource. However, the participant also observed that “If you have a lead time, you can future proof and do things right."
4 Potential problems with the hybrid model and suggested solutions
4.1 The table below summarises potential problems and solutions with the proposed hybrid model:
| Potential problem | Mitigants and potential solutions |
|---|---|
| Volume of disclosure | The proposed disclosures are subject to usual materiality constraints. |
| The proposal to allow acquisitions with similar characteristics to be grouped together balances volume with relevance. For example, in the roll-forward, acquisitions could be grouped by CGU or operating segment. | |
| A further potential solution is to no longer require disclosure once goodwill is fully amortised. | |
| Commercial sensitivity of proposed disclosures | Allow an exemption on grounds of commercial sensitivity, on similar lines to the IAS 37 paragraph 92 exemption. |
| Recent research by IASB indicated that such an exemption is rarely used in practice. | |
| Loss of relevant information under indicator-only impairment testing – IAS 36 paragraph 134 disclosures on discount rates and terminal value assumptions are often used by analysts for forecasting purposes, although that is not the purpose of the IAS 36 disclosure | We reviewed 50 annual reports and noted that only 12 included these disclosures so the impact of the loss of disclosures would not be universal. |
| Explore requiring disclosure of growth rates and discount rates for each segment under IFRS 8. | |
| Some field-test participants told us that they expected to complete a full impairment test even if a hybrid model were introduced, for three main reasons: | |
|
|
| Growth in MPMs, indicating that IFRS information may be less relevant | Our review of 50 annual reports identified that most entities already use an MPM which adjusts IFRS figures for amortisation of intangibles. Examples of such MPMs are EBITDA, Adjusted EBITDA, and underlying EBITDA. |
| While it is possible that amortisation of goodwill would feature as an additional reconciling item between the MPM and the nearest IFRS subtotal it, is unlikely that additional MPMs would result from the introduction of a hybrid model. | |
| Gaming | Consider prohibition of extension to the estimate of useful life of goodwill. |
| Difficulties in reliable valuation of components of goodwill in order to calculate an amortisation charge | Current research on intangibles by UKEB and IASB may provide further insight and consistency. |
5 Conclusions
5.1 The current impairment-only model for subsequent measurement of goodwill under IFRS needs reconsideration because:
- Goodwill features in the financial statements of a high proportion of UK IFRS reporters and represents a significant proportion of net assets. Based on trend analysis from 2005 – 2021, if the impairment-only model remains, the carrying value of goodwill will continue to increase.
- Significant proportions of balance sheet value will increasingly be represented by goodwill balances relating to acquisitions dating back many years.22 In many cases, the acquisitions will have long since been fully integrated and the benefits represented by the goodwill will have been consumed. Balance sheets may become dominated by goodwill whose relevance reduces over time and which may not meet the conceptual framework definition of an asset and therefore fail to provide a faithful representation.
- The impairment-only model requires an annual test of such aged goodwill balances even where the acquisition has long since been successfully integrated and synergies have been realised. The annual test is potentially costly but may not provide useful information.
- High-level economic analysis shows that periods of significant economic uncertainty are not necessarily reflected in impairments.
- In spite of nearly two decades of experience of implementing an impairment only model under IFRS the debate has not been settled and almost half of IASB's own stakeholders are concerned with the status quo and the outcomes for company balance sheets
5.2 A hybrid model should be further explored as a potential solution to problems with current and previous regimes for subsequent measurement of goodwill because:
- A hybrid model would provide a faithful representation of those elements of goodwill whose benefits are consumed over time. It would prevent the build-up of goodwill on the balance sheet when that goodwill may no longer meet the conceptual framework definition of an asset. It would support the ongoing relevance of the statement of financial position.
- Unlike previous models for the subsequent measurement of goodwill including amortisation, the hybrid model would not include a default useful life or a rebuttable presumption about useful life. Disclosures of management's assumptions underpinning the estimate of useful life would provide investors with relevant information and support accountability.
5.3 A transition to a hybrid model would be feasible because:
- The majority of preparers believe it is possible to estimate a useful life for goodwill through consideration of a range of relevant factors and if sufficient application guidance were provided.
- A similar model works effectively under UK GAAP.
- Suitable transition arrangements could be applied to legacy goodwill.
- Adverse consequences for financial stability or for process, operations and cost are not anticipated as a result of a transition.
6 Potential areas for further research
6.1 During our research we identified two further potential areas for future research. These are outlined in the following paragraphs.
- Research into the effectiveness of the impairment only model by:
- An analysis of trends in impairments against expectations of impairment derived from indicators of impairment, such as rising interest rates and financial performance indicators.
- An analysis of carrying values of goodwill by acquisition date for UK IFRS reporters, to test the hypothesis that the impairment-only model results in a build-up of goodwill and does not provide relevant information about that goodwill because of the length of time elapsed since the acquisition date.
- Research into the prevalence and materiality of trade and assets deals, to understand the impact of amortisation of goodwill arising in separate company financial statements on distributable profits, dividend payments and financial stability.
Appendix 1 Shielding
IAS 36 requirements
IAS 36 states that any asset which is not capable of generating cash flows independently from other assets should be tested for impairment as part of a cash generating unit (CGU) or group of CGUs.
Goodwill is cited in the standard as an example of an asset which cannot generate cash flows independently from other assets.
Such assets are allocated to a CGU or group of CGUs. A CGU is the lowest level group of assets which generates cash flows independently. CGUs are defined by management and cannot be larger than an operating segment.
To determine whether goodwill is impaired, the present value of future cash flows of the CGU is forecast and compared to the carrying value of assets in the CGU. Where the present value of future cash flows exceeds the carrying value of assets in the CGU, those assets are not impaired. Where the present value of future cash flows is less than the carrying value of assets in the CGU, the CGU is impaired.
The impairment is calculated as the difference between the present value of future cash flows of the CGU and the carrying value of assets in the CGU.
The impairment is charged to the statement of profit or loss and is allocated to the assets in the CGU in the following order, reducing their carrying value
- Goodwill
- Other assets in the CGU, pro-rated on their carrying values,
- No individual asset can be reduced to a carrying value below its recoverable amount through the allocation of an impairment charge
(Note: Assets which are capable of generating cash flows independently are tested for impairment and, if necessary, impaired before the impairment test is conducted on the CGU).
The shielding problem
The allocation of goodwill to CGUs creates a problem known as the shielding of goodwill.
Shielding arises where goodwill is protected from impairment by the future cash flows of assets in the CGU/ group of CGUs. For example, an entity may have a CGU for a broad category of products, such as health products or magazines. All goodwill on all acquisitions in the broad category is allocated to the health products CGU or magazines CGU. None of the goodwill will be impaired provided the present value of future cash flows for the health products CGU or magazines CGU exceeds the carrying amount of the total assets in the CGU. In reality goodwill on unsuccessful acquisitions could be allocated to the CGU but under the current impairment only model would be shielded from impairment by the cash flows of other goodwill and other assets in the CGU.
This could continue indefinitely under the impairment-only model.
Appendix 2 History of UK financial reporting requirements for goodwill
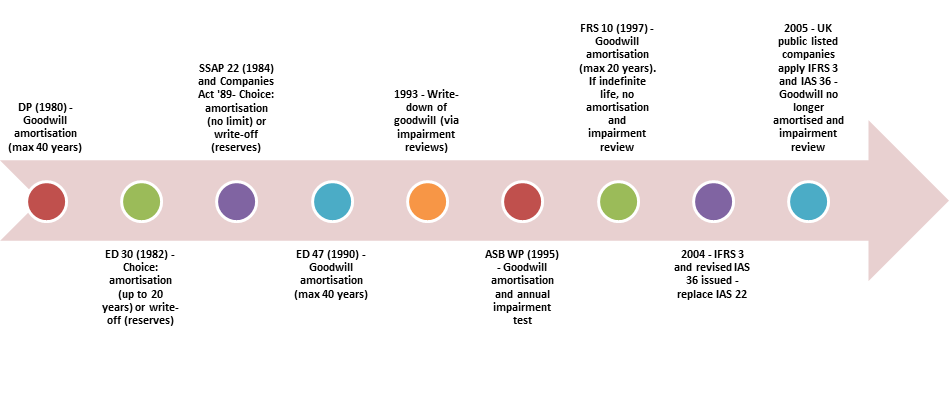
Appendix 2 History of UK financial reporting requirements for goodwill
Appendix 3 Research Method
Project approach
Our research project used desk-based research, a survey of IFRS preparers in the UK, a field-test with IFRS preparers in the UK, and outreach to users, auditors and academics to explore the potential impacts of a transition to a hybrid model for subsequent measurement of goodwill.
Research took place between November 2021 and July 2022.
Project scope
The research addressed the following areas:
- Effect on financial reporting outcomes if there were to be a transition to a hybrid model for subsequent measurement of goodwill. In particular, stakeholder views on accountability, faithful representation, relevance and comparability were sought.
- Feasibility of a transition to a hybrid model for subsequent measurement of goodwill. This area examined the feasibility of estimating a useful life of goodwill, the factors considered when estimating a useful life of goodwill, and how to deal with legacy goodwill. The materiality of transitional impacts was also analysed.
- Potential impact on financial stability. This area considered the potential impact of a transition to a hybrid model on loan covenants, tax revenues, distributable profits and dividend payments, compliance with market and other regulatory rules, and management compensation schemes.
- Potential impact on audit, processes, systems and costs.
Methodology
We used a variety of methodologies, including desk-based research, surveys and field-testing during the course of this research.
Desk-based research
We used desk-based research, including review of academic and industry papers, to understand the relevant accounting and economic issues relating to goodwill.
Survey
To obtain an understanding of UK stakeholders' views on the implications of a potential transition to a hybrid model for the subsequent measurement of goodwill, we conducted a survey of UK IFRS reporters. The survey was publicly promoted to UK IFRS preparers. 23 UK IFRS preparers completed the survey, representing 17% of the FTSE 350 by market capitalisation. The survey participants covered a range of sectors including: fast-moving consumer goods, banking, energy, utilities, construction, technology, retail, pharmaceutical, medical technology, insurance, airlines, B2B, and manufacturing. The total carrying value of goodwill of respondents represented 17% of total goodwill of the FTSE 350. 22 of the 23 respondents had made acquisitions in the last five years.
The results of our preparer survey indicated that preparers did not anticipate negative impacts on financial stability, significant operational changes or cost increases in the event of a transition to a hybrid model for the subsequent measurement of goodwill.
Review of UK GAAP application of subsequent measurement of goodwill
We conducted further desk-based research and outreach to assess the feasibility of determining a useful life for goodwill under the hybrid model, by reference to how companies using UK GAAP determined the useful life of goodwill. Our work indicated that a range of relevant and specific factors is considered by UK GAAP preparers in determining a useful life of goodwill and that these are audited.
Field-test
We used the survey results and evidence from desk-based research and outreach in developing field-test questions, aimed at ascertaining the feasibility of and appetite for a hybrid model. The field-test was publicly promoted. Nine UK entities preparing financial statements under IFRS participated in field-testing. The entities were from the following sectors: financials, consumer discretionary, utilities, industrial, and consumer staples. Of the nine entities, seven are FTSE 100 listed, one is FTSE 250 listed, and one is AIM listed.
Field-test participants were asked to complete a questionnaire on transitional arrangements to a hybrid model and to prepare financial statement extracts and disclosures under the hybrid model. Summarised questionnaire responses and anonymised financial statement extracts and disclosures were shared with users of financial statements for comment.
Economic analysis
To provide context for our rationale for undertaking the project, we undertook economic analysis to investigate outcomes from the current impairment-only model.
To gather evidence on the effectiveness of the impairment-only model as part of our project rationale, we explored whether there is a correlation between market contractions and impairments. Specifically, we compared trends in the carrying value of goodwill to trends in market capitalisation for the FTSE 350 for the period 2005 to 2021.
We undertook this analysis because a decline in market capitalisation is likely to reflect a period of significant economic uncertainty and may therefore represent an indicator of impairment of goodwill. Further, public data on market capitalisation is readily available.
We analysed the FTSE 350 by sector to ascertain which sectors had the highest carrying value of goodwill and which sectors had experienced the greatest declines in market capitalisation in 2020-2021. We undertook this analysis in order to direct our more detailed analysis to those sectors with the highest carrying values of goodwill and in which impairments might have been most likely.
We then analysed the composition of the overall net increase in goodwill between 2019 – 2021 to ascertain whether the decline in market capitalisation due to the pandemic had resulted in significant impairments that had been offset by a high value of new goodwill arising from acquisitions.
However, during our attempted analysis a data quality issue arose. It was unclear whether the source data recorded separately and consistently reductions in the carrying value of goodwill due to impairments, forex, and disposals. We were unable to reconcile opening goodwill to closing goodwill for 2019 – 2020 and for 2020 - 2021 using the results of our analysis and therefore we concluded that the figure for impairments derived from that analysis may not be reliable.
[For this reason, analysis is ongoing]
Appendix 4 Field-test participant profiles
| Organisation | FTSE Industry | FTSE Supersector | Listing medium |
|---|---|---|---|
| Entity A | Utilities | Utilities | LSE |
| Entity B | Consumer Discretionary | Travel and leisure | LSE |
| Entity C | Financials | Banks | LSE |
| Entity D | Financials | Financial services | LSE |
| Entity E | Financials | Insurance | LSE |
| Entity F | Financials | Insurance | LSE |
| Entity G | Industrials | Industrial goods and services | AIM |
| Entity H | Consumer Staples | Personal care, Drug and Grocery stores | LSE |
| Entity I | Consumer Discretionary | Media | LSE |
Market capitalisation of field-test participants represented 10% of FTSE 350 market capitalisation and 0.02% of AIM market capitalisation.
Goodwill as a percentage of net assets averaged 36% for field test participants. Goodwill as a percentage of net assets ranged between 2% and 96% for field-test participants.
Appendix 5 Survey Respondents
| Organisation | Sector |
|---|---|
| Centrica Plc | Utilities |
| Genus Plc | Healthcare |
| London Finance & Investment Group Plc | Financial services |
| Marks & Spencer | Consumer discretionary |
| National Grid plc | Utilities |
| Smith & Nephew Plc | Healthcare |
| Standard Chartered | Financial services |
| Trackwise Designs Plc | Technology |
| Zurich | Financial services |
The remaining 14 survey respondents asked to remain anonymous.
Analysis of survey responses by sector
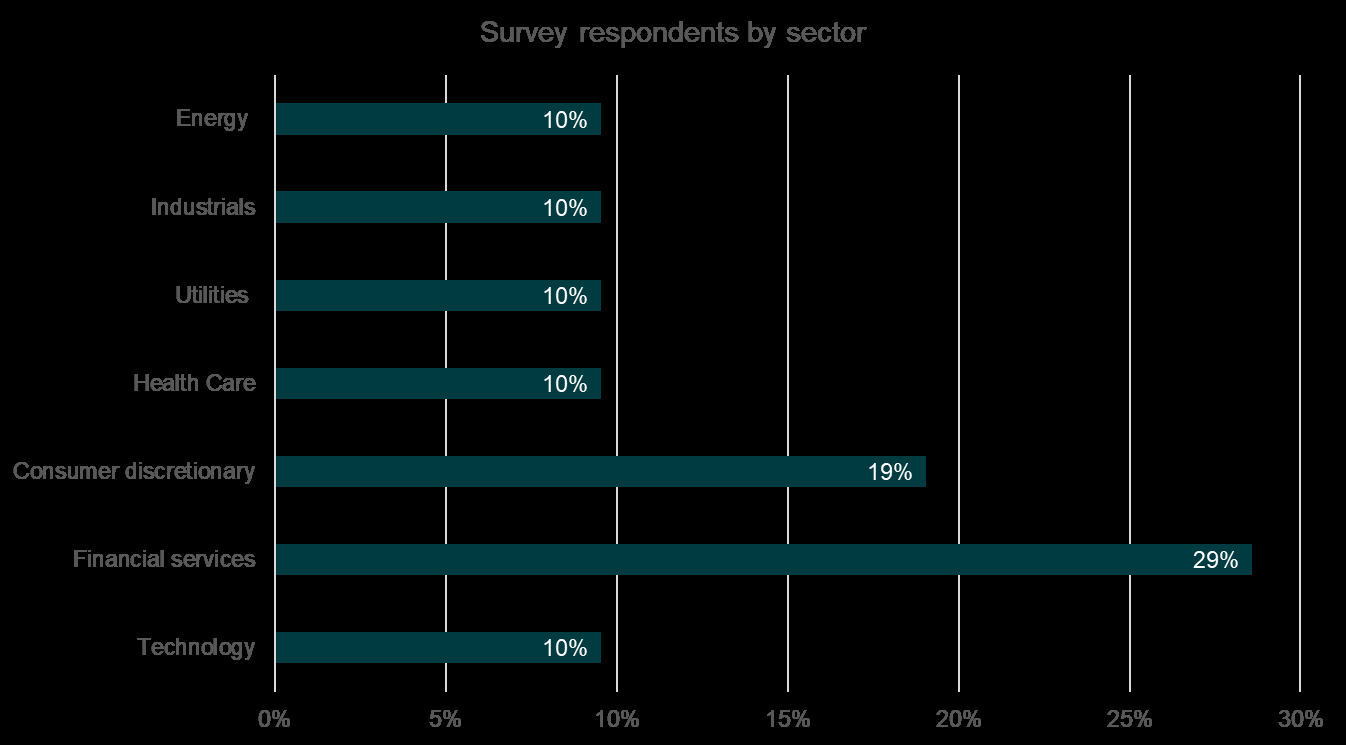
Appendix 6 Outreach Events and Participants
[to be updated once user outreach complete]
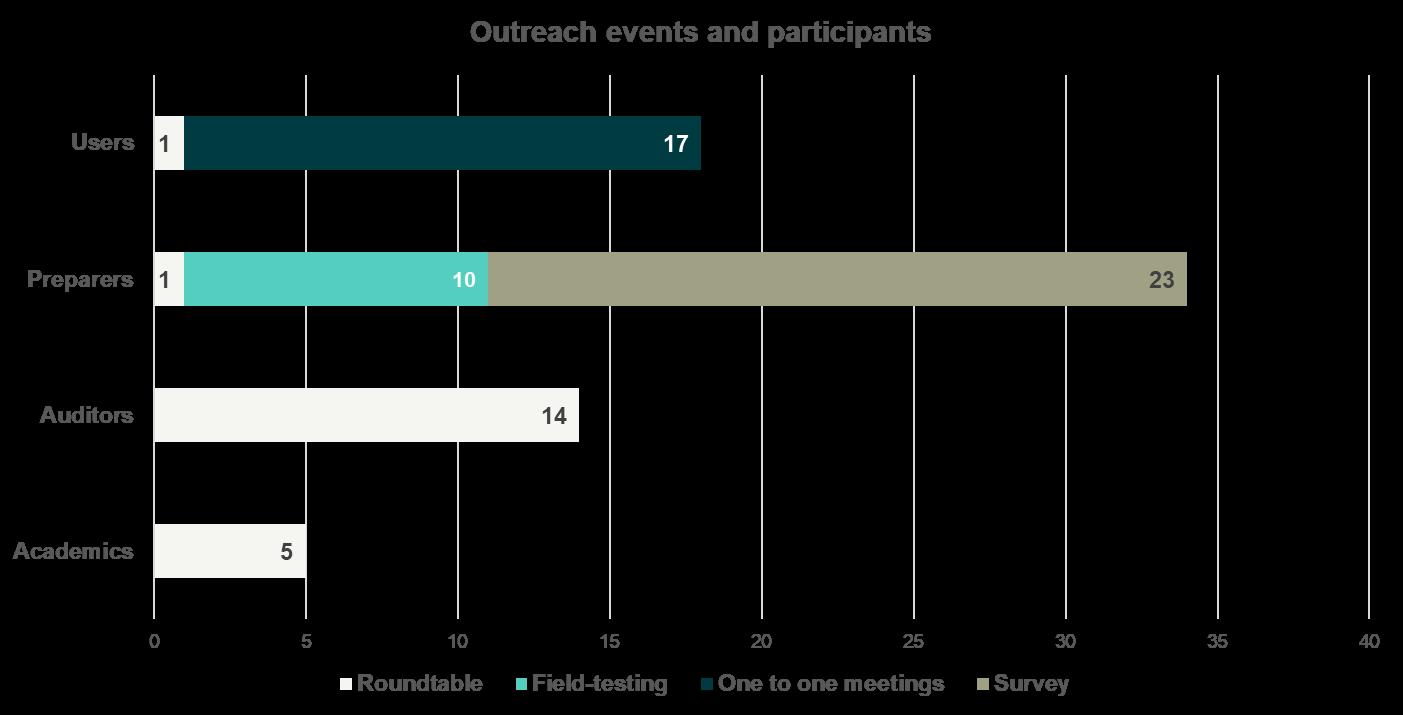
Appendix 7 Glossary
| Term | Description |
|---|---|
| AIM | Alternative Investment Market. A sub-market of the London Stock Exchange that is not a 'regulated market' |
| Amortisation | The systematic allocation of the depreciable amount of an intangible assets over its useful life |
| Backstop model | A model where, if management is unable to determine the useful life of goodwill reliably, there is a cap on the period over which goodwill is amortised |
| FASB | Financial Accounting Standards Board |
| Frozen GAAP | GAAP standards effective at the time of the transaction |
| FTSE 350 | A share index of the 350 companies listed on the London Stock Exchange with the highest market capitalisation |
| Goodwill | An asset representing the future economic benefits arising from other assets acquired in a business combination that are not individually identified and separately recognised |
| Headroom | The excess of the recoverable amount of a cash-generating unit) or group of units) over the carrying amount of that unit |
| Hybrid model | Impairment testing supported by an annual amortisation charge |
| IASB | International Accounting Standards Board |
| IFRS | International Financial Reporting Standard |
| IAS 36 | International Accounting Standard 36 Impairment of Assets |
| Impairment | Is the amount by which the carrying amount of an asset exceeds its recoverable amount |
| Legacy goodwill | Goodwill arising from business acquisitions undertaken in the past |
| M&A | Mergers and Acquisitions |
| Management Performance Measures (MPMs) | Quantifiable measures that assess management's performance during the reporting period |
| Outreach | Activities conducted with various groups and organisations, to gather information and insights on the goodwill measurement |
| Physical risk | Risks resulting from climate change that can be event-driven (acute) or from longer-term shifts (chronic) in climate patterns. These risks may carry financial implications for entities of supply-chain disruption. Entities' financial performance may also be affected by changes in water availability, sourcing and quality; and extreme temperature changes affecting entities' premises, operations, supply chain, transportation needs and employee safety |
| Preparer survey | The online survey of UK IFRS preparers conducted by the UKEB in November 2020 |
| Shielding effect | The resulting effect when goodwill is allocated to a cash-generating unit that contains unrecognised internally generated goodwill or other unrecognised internally generated intangible assets |
| Solvency II | A Directive in EU law that codified and harmonised EU insurance regulation. It governs the amount of capital that EU insurance companies must hold to reduce the risk of insolvency |
| Trade and asset transactions | A transaction involving the sale and purchase of some or all of an entity's assets and liabilities, without there being a change in the shareholding |
| Transitional risk | A risk arising on the transition to a lower-carbon economy |
| Useful life | The period over which an asset is expected to be available for use by an entity or the number of production or similar units expected to be obtained from the asset by an entity |
| UKEB | UK Endorsement Board |
| UK GAAP | United Kingdom Generally Accepted Accounting Practice |
| Unincorporated business | A business that does not possess a separate legal identity from its owners |
| Underlying items | Non-identifiable items that form part of an easily identifiable item |
| Wasting asset | An asset whose useful life is limited |
UK Endorsement Board 1 Victoria Street
| London | SW1H 0ET | United Kingdom Web: www.endorsement-board.uk
Footnotes
-
The timeline was updated because preparer engagement in field-testing was greater than anticipated, to allow for further user outreach, and to align with the IASB's timeline. ↩
-
Prior to the adoption of IFRS, UK listed companies measured goodwill under an amortisation and impairment model. ↩
-
The ratio of market capitalisation to net assets. ↩
-
Market capitalisation indicates the market's expectation of the future earnings capacity of a business given the current available information about the entity. ↩
-
Appendix 2 shows a timeline of UK financial reporting requirements for goodwill. ↩↩
-
On 15 June 2022, FASB decided to remove the project on subsequent measurement of goodwill from its technical agenda. Prior to its decision to remove the project from its technical agenda, the FASB had made tentative decisions to reintroduce amortisation, to set a rebuttable assumption for the amortisation, and to require straight-line amortisation. Appendix 3 shows a summary of tentative decisions taken by the FASB before its decision to remove the project from its technical agenda. ↩
-
Under a hybrid model, amortisation would reflect the consumption of the goodwill's service potential and impairment would reflect the extent to which the carrying amount of goodwill is no longer expected to be recovered. See Section 2 for more detail. ↩
-
UKEB analysis of responses to IASB's Discussion Paper. ↩
-
Disclosure of total amortisation and the lines in the statement of profit or loss where it is presented is currently under discussion by IASB as part of its General Presentation and Disclosures project. ↩
-
Preparer data has been anonymised. Preparer profiles are shown in Appendix 4. Preparers represented 5 of the 10 sectors with the highest carrying value of goodwill. ↩
-
The UK Financial Reporting Council (FRC). ↩
-
Preparers have been anonymised. Preparer profiles are shown in appendix 7. ↩↩
-
Field-test participants own assessment, checked for reasonableness in UKEB analysis. ↩
-
Field-test participants own assessment, checked for reasonableness in UKEB analysis. ↩
-
Regarding comparability, several participants highlighted that the changes in the financial reporting regime for goodwill in the UK have led to lack of comparability at present. Some entities will report goodwill that was partially amortised when they transitioned to IFRS. Others will have written off goodwill to reserves prior to FRS 10. ↩
-
Goodwill increased by 69% from £227bn to £383bn for the FTSE 350 between 2005 and 2020. ↩
-
Our public survey was open from 15 November 2021 to 26 November 2021 ↩
-
Source: UKEB calculations based on Eikon data ↩
-
Frozen GAAP is the GAAP prevailing at the time the transaction was entered into. ↩
-
For example, Listing Rules Class tests for transactions Listing Rules 13.5.33b; Disclosure Guidance and Transparency Rules Related Party tests. ↩
-
The average age of goodwill for our field-test participants was 8 years. The age of goodwill ranged between 2 years and 17 years. ↩