3.0 IFRS 17 – Adoption of IFRS 17
Project Type: Endorsement and adoption Project Scope: Significant
Executive Summary
Purpose of the paper
This paper presents an 'Adoption Package' for the project to assess IFRS 17 Insurance Contracts for adoption.
The documents included as part of the 'Adoption Package' are:
- A final Endorsement Criteria Assessment (ECA);
- A Feedback Statement;
- A [draft] Due Process Compliance Statement;
- A [draft] Adoption Statement; and
- The text of UK-adopted international accounting standard IFRS 17.
Summary of the issue
IFRS 17 was issued before the UK's EU Exit and the EU process for adoption had not been completed before the end of the Transition Period. As a result, IFRS 17 must be adopted for use in the UK to ensure UK companies are able to use the standard when preparing their accounts. All UKEB outreach and other assessment work on IFRS 17 has been completed and the results incorporated in the Adoption Package presented to the Board at this meeting.
Decisions for the Board
The Board is asked to:
- Approve certain documents included as part of the 'Adoption Package'.
- Provide a tentative vote on the adoption of IFRS 17 Insurance Contracts for use in the UK.
Recommendation
We recommend that the Board approves the relevant documents in the 'Adoption Package' and supports the adoption of IFRS 17 Insurance Contracts.
Appendices
Appendix 1 Final Endorsement Criteria Assessment (ECA) Appendix 2 Feedback Statement Appendix 3 [Draft] Due Process Compliance Statement Appendix 4 [Draft] Adoption Statement Appendix 5 Annex to the Adoption Statement: UK-adopted international accounting standard IFRS 17 Insurance Contracts
Introduction
1IFRS 17 Insurance Contracts was issued in 2017 and subsequently amended in 2020 and 2021. IFRS 17 is effective for annual reporting periods beginning on or after 1 January 2023, with earlier application permitted as long as IFRS 9 Financial Instruments is also applied from the same date.
2IFRS 17 was not incorporated into domestic UK law as part of UK-adopted international accounting standards at the end of the Transition Period on 31 December 2020, as the European Union's process for adoption of the standard had not been completed before the UK's Exit from the EU1. As a result, IFRS 17 must be adopted for use in the UK to ensure UK companies are able to use the standard when preparing their accounts.
3At its March and April 2022 meetings the Board considered a summary of:
- the work undertaken by the Secretariat to support the Board's assessment of IFRS 17 against the statutory endorsement criteria;
- the assessments conducted by the Board (prior to and subsequent to the publication of the draft ECA); and
- the decisions taken by the Board at previous meetings.
4At its April 2022 meeting the Board considered a final draft of the ECA, including updates in respect of CSM allocation for annuities, and approved the draft subject to certain limited amendments.
5At its April meeting the Board also noted that all outreach and other endorsement assessment work had been completed.
6This paper now presents an 'Adoption Package' of documents for noting and for the Board's approval.
Documents for noting and approval
For noting
- Appendix 1.1: ECA
- Appendix 1.2: Feedback Statement
- Appendix 1.3: [draft] Due Process Compliance Statement (NB: a final DPCS will be presented for noting at the Board's 19 May 2022 meeting)
For approval
- Appendix 1.4: [draft] Adoption Statement
- Appendix 1.5: Annex to Adoption Statement: UK-adopted international accounting standard IFRS 17 Insurance Contracts
ECA
8As noted above, the Board approved the final draft of the ECA at its April 2022 meeting, subject to certain changes identified at that meeting. Changes to the ECA since the version presented at that meeting relate primarily to the description of our approach to the assessment of IFRS 17 against the endorsement criteria. These changes reflect the amendments identified by Board members during the discussion at the April 2022 Board meeting and are in paragraphs 1.24 and 1.25 of Section 1 and the first sentence of paragraph 3.7.
9All other changes are minor editorial and formatting amendments, required in part to reflect the UKEB's latest design template.
Feedback Statement
10The Board approved the final draft of the Feedback Statement at its April 2022 meeting, subject to certain changes identified at that meeting. The main change to the Feedback Statement since the Board's April 2022 meeting reflects the Board's suggested amendments to slide 13 in respect of the Board's overall conclusion on its true and fair view assessment. Other changes are minor editorial amendments only.
[Draft] Due Process Compliance Statement
11The Board approved a revised draft of the Due Process Compliance Statement at its April 2022 meeting. Changes to the draft since the Board's April 2022 meeting reflect updates in respect of project closure steps and amendments identified by the Board in April. In particular, refinements have been made to the introductory paragraph explaining the governance arrangements in place prior to the UKEB becoming operational in May 2021. In addition, where steps are noted as 'required', the Statement clarifies whether the particular step only subsequently became required as a result of the development of the draft Due Process Handbook.
12Final updates to the project closure steps will be made subsequent to this meeting and the final Statement will be presented for noting at the 19 May 2022 meeting.
Voting on the adoption of IFRS 17 Insurance Contracts
13Decisions on the endorsement and adoption of a standard or amendment are made at public Board meetings and follow the requirements of Section 5 of the UKEB's Terms of Reference2.
14At this public meeting Board members are requested to provide a tentative vote on the adoption of IFRS 17 Insurance Contracts for use in the UK.
15This vote will be indicative only and will be formalised by members signing the formal voting form that will be made available to them outside of the meeting. Board members are asked to submit their voting form by 5:00pm on 12 May 2022. The UKEB Terms of Reference require that the outcome will be made public within 3 working days of the formal vote3.
16Should the Board decide to adopt IFRS 17 for use in the UK, an Adoption Statement will be published in the form set out as Appendix 1.4.
Questions for the Board - Voting on the adoption of IFRS 17 Insurance Contracts
17Do Board members tentatively approve:
- the adoption of IFRS 17 Insurance Contracts for use in the UK; and
- the [draft] Adoption Statement?
Next Steps
18The next project milestones are set out in the table below:
| Date | Milestone |
|---|---|
| 12 May 2022 | Deadline for submitting the voting form to the Secretariat. |
| 17 May 2022 | Outcome of the Board's formal vote [and the ‘Adoption Package'] published on the UKEB website. |
| 19 May 2022 Board Meeting | Final Compliance Statement to Board for noting. |
This Endorsement Criteria Assessment (ECA) includes extracts of information from IASB® IFRS 17 Effects Analysis and IASB® IFRS 17 Basis for Conclusions used with permission from the IFRS® Foundation. The IFRS® Foundation retains intellectual property rights including copyright over this material.
Copyright © 2021 IFRS® Foundation
Used with permission of the IFRS Foundation. All rights reserved. Reproduction and use rights are strictly limited. Please contact the IFRS Foundation for further details at [email protected]. Copies of IASB® publications may be obtained from the IFRS Foundation's Publications Department. Please address publication and copyright matters to [email protected] or visit the IFRS Foundation's webshop at http://shop.ifrs.org.
Disclaimer
To the extent permitted by applicable law, the IASB and the IFRS Foundation expressly disclaim all liability howsoever arising from this publication or any translation thereof whether in contract, tort or otherwise to any person in respect of any claims or losses of any nature including direct, indirect, incidental or consequential loss, punitive damages, penalties or costs. Information contained in this publication does not constitute advice and should not be substituted for the services of an appropriately qualified professional.
- Executive Summary
- Introduction
- Documents for noting and approval
- Voting on the adoption of IFRS 17 Insurance Contracts
- Next Steps
- Disclaimer
- Executive Summary
- I. Legislative framework and our approach to the assessment
- Understandability, relevance, reliability and comparability
- Whether IFRS 17 is likely to be conducive to the long term public good in the UK
- The standard is not contrary to the true and fair view requirement for individual and consolidated financial statements
- Structure of this Endorsement Criteria Assessment
- 2 Description of IFRS 17
- 2 – Variable Fee Approach (VFA)
- 3 – Premium Allocation Approach (PAA)
- 3 Technical accounting criteria assessment
- Priority issues
- A: Profit recognition – CSM allocation for annuities
- Initial recognition
- Subsequent measurement
- Insurance coverage
- Investment return service
- Disclosures
- Determination of CSM amortisation – accounting impact
- Initial recognition
- Subsequent measurement
- Recognition of insurance coverage service
- Assessment against the endorsement criteria
- Potential challenges to the endorsement criteria and mitigations
- B: Discount rates
- C: Grouping insurance contracts: profitability buckets and annual cohorts
- D: With-profits: inherited estates
- Overall conclusion on whether IFRS 17 meets the technical accounting criteria
- 4 UK long term public good assessment
- Basis for adoption of international accounting standards
- Structure of the assessment
- The UK insurance sector
- Relevant population of insurers
- Lloyd's of London
- Other entities
- UK branches of foreign entities
- Companies with limited insurance activities (‘non-insurance companies')
- Will IFRS 17 improve the quality of financial reporting?
- Costs and benefits of applying IFRS 17
- Ongoing costs
- Other external sources relating to costs for insurance companies
- SAS Perspectives and approaches to IFRS 17 (2018)
- Benefits
- SAS - A Transformation in Progress - Perspectives and approaches to IFRS 17 (2018)
- Other stakeholders
- Summary of costs and benefits for stakeholders
- Likely effect on the economy of the UK
- Introduction
- Potential impact on business conducted by UK insurance industry
- Onerous contracts
- Effects on competitive landscape of UK insurance industry
- Consideration of the consequences of not adopting the standard
- Overall conclusion on UK long term public good
- Overall conclusion on UK long term public good
- 5 True and fair view assessment
- Appendix A - Glossary
- Appendix B - Assessment of remaining significant issues
- Risk adjustment for non-financial risk
- Interest accretion at the locked-in rate for CSM under the GMM
- Recognition of income from reinsurance to match losses from onerous underlying contracts
- Contracts acquired in their settlement period
- Contracts that change nature over time
- Reinsurance to close (RITC) transactions in the Lloyd's market
- Other comprehensive income option
- Transition requirements
- Other VFA issues: (i) Ineligibility of reinsurance contracts for VFA
- Other VFA issues: (ii) Prohibition of retrospective application of the risk mitigation option
- Other VFA issues: (iii) Eligibility for VFA when there are mutualised cash flows
- Other VFA issues: (iv) Non-profit contracts written by a with-profits fund
- Foreword
- The UK Endorsement Board (UKEB)
- Executive summary
- Principal objective of IFRS 17
- Summary of IFRS 17 principles
- Summary of outreach prior to draft ECA
- UKEB public consultation on the draft ECA
- Our approach to the assessment
- Summary of outreach prior to draft ECA
- UKEB public consultation on the draft ECA
- Our approach to the assessment
- Overall conclusions – Technical accounting criteria
- Overall conclusions – Technical accounting criteria
- Summary of outreach prior to draft ECA
- UKEB public consultation on the draft ECA
- Our approach to the assessment
- UK-adopted international accounting standards: International Financial Reporting Standard 17—Insurance Contracts
- Recognition
- Insurance acquisition cash flows (paragraphs B35A-B35D)
- Measurement (paragraphs B36-B119F)
- Measurement on initial recognition (paragraphs B36-B95F)
- Estimates of future cash flows (paragraphs B36-B71)
- Discount rates (paragraphs B72-B85)
- Risk adjustment for non-financial risk (paragraphs B86-B92)
- Contractual service margin
- Subsequent measurement
- Contractual service margin (paragraphs B96-B119B)
- Onerous contracts
- Premium allocation approach
- Reinsurance contracts held
- Recognition
- Measurement
- Premium allocation approach for reinsurance contracts held
- Investment contracts with discretionary participation features
- Modification and derecognition
- Modification of an insurance contract
- Derecognition
- Presentation in the statement of financial position
- Recognition and presentation in the statement(s) of financial performance (paragraphs B120-B136)
- Disclosure
- Explanation of recognised amounts
- Insurance finance income or expenses
- Transition amounts
- Significant judgements in applying IFRS 17
- Nature and extent of risks that arise from contracts within the scope of IFRS 17
- All types of risk—concentrations of risk
- Insurance and market risks—sensitivity analysis
- Insurance risk—claims development
- Credit risk—other information
- Liquidity risk—other information
- Appendix A Defined terms
- Appendix B
- Definition of an insurance contract (Appendix A)
- Separating components from an insurance contract (paragraphs 10–13)
- Insurance acquisition cash flows (paragraphs 28A-28F)
- Measurement (paragraphs 29–71)
- Non-market variables
- Using current estimates (paragraph 33(c))
- Cash flows within the contract boundary (paragraph 34)
- Contracts with cash flows that affect or are affected by cash flows to policyholders of other contracts
- Discount rates (paragraph 36)
- Risk adjustment for non-financial risk (paragraph 37)
- Initial recognition of transfers of insurance contracts and business combinations (paragraph 39)
- Changes in the carrying amount of the contractual service margin for insurance contracts without direct participation features (paragraph 44)
- Appendix C
- Effective date and transition
- Effective date
- Transition
- Determining the contractual service margin or loss component for groups of insurance contracts with direct participation features
- Insurance finance income or expenses
- Fair value approach
- Asset for insurance acquisition cash flows
- Comparative information
- Entities that first apply IFRS 17 and IFRS 9 at the same time
- Redesignation of financial assets
- Withdrawal of other IFRS Standards
Executive Summary
Background
1The UK Endorsement Board (UKEB) is responsible for endorsement and adoption of international accounting standards (issued by the International Accounting Standards Board in the form of International Financial Reporting Standards, or IFRS) for use in the United Kingdom (UK). The UKEB is therefore the UK's National Standard Setter for IFRS.
2The primary objective of adoption of IFRS for use in the UK is to harmonise the financial information presented by relevant companies in order to ensure:
- a high degree of transparency and international comparability of financial statements; and
- the efficient allocation of capital, including the smooth functioning of capital markets in the United Kingdom4.
3This Endorsement Criteria Assessment (ECA) presents the work performed by the UKEB to assess whether IFRS 17 Insurance Contracts5, issued by the International Accounting Standards Board, meets the UK's statutory requirements for adoption of IFRS as set out in Statutory Instrument 2019/685 (the Regulations)6.
4Although the Regulations refer only to 'adoption', for the purposes of this ECA the term endorsement is generally used when referring to the criteria set out in the Regulations and to the assessment of IFRS 17 against those criteria, reflecting general usage.
5Our assessment addresses the three endorsement criteria set out in the Regulations:
- whether IFRS 17 meets the criteria of understandability, relevance, reliability and comparability required of the financial information needed for making economic decisions and assessing the stewardship of management;
- whether IFRS 17 is likely to be conducive to the long term public good in the UK; and
- whether IFRS 17 is not contrary to the true and fair view principle for individual and consolidated accounts.
6The work to support these assessments has spanned many months and has been responsive to stakeholder input throughout. Key components of this work include:
- extensive technical analysis, including meetings with the UKEB's Insurance Technical Advisory Group and the Association of British Insurers;
- outreach activities including webinars, surveys of insurance companies and users of their accounts, interviews and roundtable discussions; and
- in-house economic analysis and research and review of external studies, including an economic report prepared for the UKEB.
IFRS 17 Insurance Contracts
7A summary of the requirements of IFRS 17 is presented in Section 2 of this ECA. IFRS 17 establishes principles for the recognition, measurement, presentation and disclosure of insurance contracts within the scope of the standard. It is intended to replace the current interim accounting standard on insurance contracts, IFRS 4 Insurance Contracts. IFRS 4 does not prescribe the recognition, measurement or presentation of insurance contracts. Rather it allows entities to use a wide variety of accounting practices, reflecting national accounting requirements. Amongst other things, this means that the financial position and results of subsidiaries included in the group accounts may not be reflected in the group accounts on a consistent basis.
Technical accounting criteria
8Section 3 of this ECA addresses whether IFRS 17 meets the criteria of understandability, relevance, reliability and comparability required of the financial information needed for making economic decisions and assessing the stewardship of management (referred to in this ECA as the technical accounting criteria).
9In carrying out this assessment we have considered all principal aspects of IFRS 17. However, in the interests of efficiency and effectiveness we have reported a detailed analysis against the technical accounting criteria only in relation to significant issues (an 'exceptions-based approach'). In this context 'significant issues' means aspects of the standard:
- where there is a question over whether IFRS 17's requirements on that aspect meet all the technical accounting criteria; and
- which have a potentially significant impact in the UK: that is, the issue is likely to be material to at least some companies and/or the efficient and effective functioning of UK capital markets.
10The process adopted to identifying significant issues, described in more detail in Section 3, spanned many months and has been responsive to stakeholder input throughout that period.
11Insurance contracts create a wide variety of often complex bundles of rights and obligations for the issuer. No international accounting standard could address explicitly every scenario that arises under typical UK insurance contracts. However, our conclusion is that IFRS 17 sets out clear principles that can be applied to insurance contracts typical in the UK and that will result in understandable, relevant, reliable and comparable information for users of the accounts. In some cases, it will be particularly important for management to provide appropriate disclosures, as required by IFRS 17 and more generally by IFRS Standards7, to achieve the objectives of understandability, relevance, reliability and comparability.
12Overall, our conclusion is that IFRS 17 meets the criteria of understandability, relevance, reliability and comparability required of the financial information needed for making economic decisions and assessing the stewardship of management.
UK long term public good
13The UKEB's analysis of whether IFRS 17 is likely to be conducive to the long term public good in the UK is presented in Section 4 of this ECA. That section:
- presents an overview of the insurance sector in the UK and the relevant population of insurance companies that will be directly affected by the UKEB's IFRS 17 adoption decision;
- discusses whether IFRS 17 is likely to improve the quality of financial reporting in the UK;
- considers the costs and benefits likely to result from the use of IFRS 17 in the UK; and
- considers whether the use of IFRS 17 is likely to have an adverse effect on the economy of the UK, including on economic growth.
14Implementing IFRS 17 will lead to improvements in the financial reporting for insurance contracts by specifying a comprehensive set of recognition, measurement, presentation and disclosure requirements for the first time. This will lead to financial reporting that faithfully reflects the substance of the contracts in scope and is prepared and presented on a consistent basis, making it more comparable from year to year, between different companies in the insurance sector as well as across jurisdictions. Such financial information is more useful to existing and potential investors, lenders and other primary users of accounts.
15Aggregate one-off IFRS 17 implementation costs for all UK insurance companies adopting IFRS 17 are estimated at approximately £1.18 billion. Of this, approximately £0.5 billion had been incurred by 30 June 2020 and significant further cost has been incurred since then. While these costs are significant, they represent 1% or less of relevant companies' average annual Gross Written Premiums over the last 5 years. Most insurance companies anticipated only a minor impact on ongoing costs due to the expectation that any additional costs would at least partially be offset by cost savings from operational efficiencies.
16Users of insurance company accounts are the main beneficiaries of the enhanced transparency and comparability expected to result from IFRS 17. This was reflected in our outreach with analysts and other users of accounts. The majority of users of insurance company accounts were optimistic that the changes introduced by IFRS 17 would improve comparability between insurance companies and increase transparency in insurance company accounts. However, they expected to be able to make a more complete assessment only after more detailed engagement with insurance companies on their IFRS 17 implementation.
17Views on the likely impact of IFRS 17 on the cost of capital for insurance companies are mixed. While some stakeholders consider that the cost of capital may increase in the short term, others consider that IFRS 17 may result in a lower cost of capital for UK insurance companies in the longer term.
18Although not quantified, some insurance companies also expect to realise ongoing indirect benefits from improvements in systems and data management, and from process efficiencies resulting from the IFRS 17 implementation.
19As the standard aims to enhance transparency and comparability in financial reporting, the implementation of IFRS 17 should also be beneficial for auditors and regulators.
20Overall, the application of IFRS 17 is not expected to result in significant additional net ongoing costs for stakeholders in the UK insurance sector.
21It is possible that IFRS 17 will prompt some changes to insurance product offerings or pricing strategies. However, those changes are not anticipated to be of substantial detriment to the UK economy. IFRS 17 is not expected to adversely affect competition in the insurance industry between entities applying the standard and those that do not apply it. At an international level, IFRS 17 might increase competition, as large global groups may exploit cross-country synergies post-adoption, leading to positive effects on the UK economy. The EU carve out from IFRS 17's annual cohorts requirement is not expected to have significant consequences for competition for customers and may provide an advantage for UK companies in the competition for capital if they apply IFRS 17 as issued by the IASB.
22IFRS 17 is not expected to have an adverse effect on the economy of the UK in relation to cost of capital and access to finance for insurance companies, as the enhanced transparency and comparability of insurance company accounts expected from use of IFRS 17 is likely to be positively evaluated by investors. Similarly, it is not expected that IFRS 17 will have a significant effect on the investment or hedging strategies of insurance companies.
23The standard is expected to have a minor, non-adverse effect on tax revenues over the medium and long term.
24IFRS 17 is expected to have a neutral to positive effect on economic growth and on financial stability. The expected improvement in the transparency and comparability of insurance company accounts should promote the efficient allocation of capital and the ability of investors to hold management to account. In addition, IFRS 17 is expected to provide new information that will be useful for supervisory monitoring and should allow users of accounts to better evaluate the financial position of insurance companies, leading to greater market confidence.
25As part of our work, we also considered the potential effects on the UK economy of not adopting IFRS 17. Not adopting the standard would result in users of accounts not being able to benefit from the enhanced transparency and comparability expected from reporting under IFRS 17. Assuming other jurisdictions adopt IFRS 17, this would be likely to put UK insurance companies at a relative disadvantage compared with companies applying IFRS 17, with a potential disadvantage in terms of their cost of capital or reduced access to global capital markets.
26Overall, our conclusion is that the use of IFRS 17 is likely to be conducive to the long term public good in the UK.
True and fair view principle
27Section 5 of the ECA addresses whether IFRS 17 is not contrary to the true and fair view principle for individual and consolidated accounts. Responsibility for ensuring that a company's accounts give a true and fair view lies with the directors of the company. The duty of the UKEB under Regulation 7(1)(a) is to determine generically, before a standard is applied to a set of accounts, whether that standard is 'not contrary' to the true and fair view principle. We have therefore considered whether IFRS 17 contains any requirement that would prevent accounts prepared using the standard from giving a true and fair view.
28Our approach is to determine whether IFRS 17 is not contrary to the true and fair view principle in respect of any of the specific items identified in Regulation 7(1)(a) (namely, the assets, liabilities, financial position and profit or loss) in the context of the preparation of the accounts as a whole. A holistic approach has been taken to this assessment, considering the impact of IFRS 17 taken as a whole, including the disclosures it requires and its interaction with other UK-adopted international accounting standards.
29Our assessment has not identified any requirement of IFRS 17 that would prevent individual accounts prepared using the standard from giving a true and fair view of the entity's assets, liabilities, financial position and profit or loss. While feedback from some stakeholders has indicated that preparation of consolidated accounts may in some cases be more complex under IFRS 17, we have not identified any reason why the IFRS 17 true and fair view assessment should conclude differently for consolidated accounts.
30Section 3 of this ECA concludes that IFRS 17 meets the technical accounting criteria, further underpinning the overall true and fair view assessment.
31Overall, therefore, we conclude that IFRS 17 is not contrary to the true and fair view principle set out in Regulation 7 (1) (a) of SI 2019/685.
I. Legislative framework and our approach to the assessment
Purpose of Endorsement Criteria Assessment
1.1The purpose of this Endorsement Criteria Assessment (ECA) is to determine whether IFRS 17 Insurance Contracts, issued by the International Accounting Standards Board (IASB®) in May 2017 and amended in June 2020 and December 20218, meets the UK's statutory requirements for adoption of international accounting standards and whether it should be adopted for use in the UK.
Legislative background to endorsement criteria
1.2The statutory requirements for adoption of an international accounting standard for use in the UK are set out in The International Accounting Standards and European Public Limited-Liability Company (Amendment etc.) (EU Exit) Regulations 2019 No. 685 (the Regulations, or SI 2019/685).
1.3The primary objective of adoption of international accounting standards (referred to in this ECA as 'IFRS® Standards', except when we are referring to them in the context of our obligations under the Regulations) for use in the UK as set out in SI 2019/685 is to harmonise the financial information presented by relevant companies in order to ensure:
- a high degree of transparency and international comparability of financial statements; and
- the efficient allocation of capital, including the smooth functioning of capital markets in the United Kingdom.10
1.4Regulation 7(1) of SI 2019/685 requires that an international accounting standard can only be adopted if:
"(a) the standard is not contrary to either of the following principles-
- an undertaking's accounts must give a true and fair view of the undertaking's assets, liabilities, financial position and profit or loss;
- consolidated accounts must give a true and fair view of the assets, liabilities, financial position and profit or loss of the undertakings included in the accounts taken as a whole, so far as concerns members of the undertaking;
(b) the use of the standard is likely to be conducive to the long term public good in the United Kingdom; and (c) the standard meets the criteria of understandability, relevance, reliability and comparability required of the financial information needed for making economic decisions and assessing the stewardship of management."
1.5The legislation itself therefore provides a broad structure for the endorsement work needed to assess IFRS 17 for use in the UK, including setting out the key questions that must be addressed. The UK Endorsement Board's (UKEB's) approach to these criteria is explained in the following paragraphs.
Approach to the endorsement criteria
1.6This ECA addresses the endorsement criteria in the following order:
- whether the standard meets the criteria of understandability, relevance, reliability and comparability required of the financial information needed for making economic decisions and assessing the stewardship of management (Regulation 7(1)(c));
- whether the standard is likely to be conducive to the long term public good in the UK (Regulation 7(1)(b)); and
- whether the standard is not contrary to the true and fair view requirement for individual financial statements and consolidated financial statements (Regulation 7(1)(a)).
1.7Each of the criteria in paragraph 1.6 above is addressed in a separate section which includes detailed explanations of the criteria and the UKEB's approach. A high-level summary of our approach to the endorsement criteria is set out below.
1.8A holistic approach has been taken to the assessment of whether a standard is not contrary to the principle that both the individual and consolidated financial statements must give a true and fair view (see the full text of the requirement in paragraph 1.4 above), considering the standard as a whole. For this reason, we have reported our assessment of IFRS 17 against this endorsement criterion at the end of this ECA, after having reported our assessment of whether the standard's
- an undertaking's accounts must give a true and fair view of the undertaking's assets, liabilities, financial position and profit or loss;
- consolidated accounts must give a true and fair view of the assets, liabilities, financial position and profit or loss of the undertakings included in the accounts taken as a whole, so far as concerns members of the undertaking;
1.5The legislation itself therefore provides a broad structure for the endorsement work needed to assess IFRS 17 for use in the UK, including setting out the key questions that must be addressed. The UK Endorsement Board's (UKEB's) approach to these criteria is explained in the following paragraphs.
Approach to the endorsement criteria
1.6This ECA addresses the endorsement criteria in the following order:
c) whether the standard meets the criteria of understandability, relevance, reliability and comparability required of the financial information needed for making economic decisions and assessing the stewardship of management (Regulation 7(1)(c));
d) whether the standard is likely to be conducive to the long term public good in the UK (Regulation 7(1)(b)); and
e) whether the standard is not contrary to the true and fair view requirement for individual financial statements and consolidated financial statements (Regulation 7(1)(a)).
1.7Each of the criteria in paragraph 1.6 above is addressed in a separate section which includes detailed explanations of the criteria and the UKEB's approach. A high-level summary of our approach to the endorsement criteria is set out below.
1.8A holistic approach has been taken to the assessment of whether a standard is not contrary to the principle that both the individual and consolidated financial statements must give a true and fair view (see the full text of the requirement in paragraph 1.4 above), considering the standard as a whole. For this reason, we have reported our assessment of IFRS 17 against this endorsement criterion at the end of this ECA, after having reported our assessment of whether the standard's
Understandability, relevance, reliability and comparability
requirements meet the technical accounting criteria and the UK long term public good requirements.
1.9The criteria of understandability, relevance, reliability and comparability required of the financial information needed for making economic decisions and assessing the stewardship of management are derived from the qualitative characteristics of financial statements set out in the Framework for the Preparation and Presentation of Financial Statements adopted by the IASB in April 2001 (the IASB's Framework). These qualitative characteristics became part of the criteria for endorsement and adoption of IFRS for use in the European Union in the EU's IAS Regulation (1606/2002), and, subsequently, in the UK in SI 2019/685.
1.10To ensure we maintain consistency with the on-shored suite of UK-adopted IFRS, our description of these criteria – referred to collectively in this ECA as the 'technical accounting criteria' – and our interpretation of their meaning are therefore based on the analysis included in the IASB's Framework.
1.11Financial information should be readily understandable by users with a reasonable knowledge of business and economic activities and accounting, and a willingness to study the information with reasonable diligence.
1.12Information is relevant if it is capable of making a difference in the decision-making of users or in their assessment of the stewardship of management. The information may aid predictions of the future, confirm or change evaluations of the past or both.
1.13Financial information is reliable if, within the bounds of materiality, it:
- can be depended on by users to represent faithfully the economic substance of what it either purports to represent or could reasonably be expected to represent;
- is complete; and
- is free from material error and bias.
1.14Information is comparable if it enables users to identify and understand similarities in, and differences between, items. Information about an entity should be comparable with similar information about other entities and with similar information about the same entity for another period.
1.15Each technical accounting criterion is viewed as an absolute (objective) standard to attain, rather than as a relative (comparative) test (for example as compared to current UK accounting practice for insurance contracts).
8Refer to Section 3, Technical accounting criteria assessment.
UKEB > IFRS 17 Insurance Contracts > Legislative framework and our approach to the assessment 1.16In carrying out this assessment against the technical accounting criteria, we have considered all principal aspects of IFRS 17, using an exceptions-based approach. This means assessing all UK-specific concerns arising from the requirements in the standard against the technical accounting criteria but reporting the detailed analysis only in relation to priority and other significant issues. Further details on the exceptions-based approach, including the approach taken to identifying topics for consideration, have been included in Section 3.
Whether IFRS 17 is likely to be conducive to the long term public good in the UK
1.17Regulation 7(2) of SI 2019/685 sets out certain matters that have to be considered in the assessment of whether a standard is likely to be conducive to the long term public good in the UK. These are:
"(a) whether the use of the standard is likely to improve the quality of financial reporting;
(b) the costs and benefits that are likely to result from the use of the standard; and
(c) whether the use of the standard is likely to have an adverse effect on the economy of the United Kingdom, including on economic growth.”
1.18The primary objectives of the IASB's project to develop IFRS 17 were to: (i) make insurance companies' financial statements more useful to investors and other users of financial statements; and (ii) insurance accounting practices more consistent across jurisdictions and products. Therefore, our consideration of whether IFRS 17 is likely to improve the quality of financial reporting included testing whether the standard is likely to meet those IASB objectives by comparing the requirements in IFRS 17 with current UK accounting practice for insurance contracts under IFRS 4 Insurance Contracts.
1.19The effective date of IFRS 17 is 1 January 2023 and we are not aware of any company in the UK that intends to apply the standard at an earlier date. Our assessment is therefore entirely an 'ex ante' assessment and is based on our informed expectations and those of stakeholders we have consulted.
1.20Under the terms of the Small Business, Enterprise and Employment Act 201510 the UK Endorsement Board (UKEB) is not a 'relevant regulator', one which is required to undertake impact assessments in accordance with the governance requirements of the Department for Business, Energy and Industrial Strategy (BEIS). This ECA does not therefore include a detailed quantitative analysis of the impact of IFRS 17. Nevertheless, as a matter of good practice, we have considered the BEIS governance requirements as a reference point when assessing whether
9Refer to Section 4: UK long term public good assessment
10https://www.legislation.gov.uk/ukpga/2015/26/contents/enacted
IFRS 17 is likely to be conducive to the long term public good in the UK, in particular in respect of the costs and benefits likely to result from its use.
1.21The Regulations require consideration and assessment of the long term public good in the UK. Therefore, when assessing the costs and benefits arising from the use of IFRS 17, the initial costs of implementation of IFRS 17 were considered together with the expected ongoing costs and benefits in future years, to allow a balanced assessment over the longer-term.
1.22In considering whether IFRS 17 is likely to have an adverse effect on the economy of the UK, the assessment considered the potential impact of the standard on the insurance sector, including on factors such as products, pricing and competition. It went on to assess wider economic effects, including on capital markets, the cost of capital for insurers, tax payments and financial stability.
The standard is not contrary to the true and fair view requirement for individual and consolidated financial statements
1.23The duty of the UKEB under Regulation 7(1)(a) is to determine generically, before a standard is applied to a set of accounts, whether that standard is 'not contrary' to the true and fair view principle. In other words, it is an ex-ante assessment. We have therefore considered whether IFRS 17 contains any requirement that would prevent accounts prepared using the standard from giving a true and fair view.
1.24Our approach is to determine whether IFRS 17 is not contrary to the true and fair view principle in respect of any of the specific items identified in Regulation 7(1)(a) (namely, the assets, liabilities, financial position and profit or loss) in the context of the preparation of the accounts as a whole. A holistic approach has been taken to this assessment, considering the impact of IFRS 17 taken as a whole.
A holistic approach
1.25A holistic approach has been taken to the assessment of IFRS 17 against the endorsement criteria, considering the standard as a whole, including the disclosures it requires and its interaction with other UK-adopted international accounting standards. This is considered appropriate because meaningful assessments against the long term public good and true and fair view criteria can be undertaken only by considering the impact of the standard taken as a whole.
1.26Although the assessment of whether IFRS 17 meets the technical accounting criteria necessarily considers its specific and detailed requirements, including their impact on the accounting for particular contracts and transactions, the conclusion reflects a balanced overall judgement as to whether the standard, taken as a whole, meets the technical accounting criteria.
11Refer to Section 5, True and fair view assessment.
Structure of this Endorsement Criteria Assessment
1.27The remainder of this ECA is structured as follows:
- Description of IFRS 17 and its requirements (Section 2)
- Technical accounting criteria assessment (Section 3)
- UK long term public good assessment (Section 4)
- True and fair view assessment (Section 5)
- Appendices
- Appendix A - Glossary
- Appendix B - Assessment of remaining significant issues
2 Description of IFRS 17
Background, context and objectives
2.1IFRS 17 Insurance Contracts was issued in May 2017 and subsequently amended in June 2020 and December 202112. It replaces IFRS 4 Insurance Contracts and is effective for annual reporting periods beginning on or after 1 January 2023. Earlier application is permitted but only for entities that apply IFRS 9 Financial Instruments on or before the date of initial application of IFRS 17.
2.2This standard is the result of significant work by the International Accounting Standards Board (IASB) over many years, including the publication of several consultation documents13 and consultation with multiple stakeholders14. The IASB's aim was to develop a comprehensive new international accounting standard that can be applied to all types of insurance contracts.
2.3IFRS 17 is intended to replace the current interim accounting standard on insurance contracts, IFRS 4, issued in March 2004. IFRS 4 does not prescribe requirements for the recognition, measurement or presentation of insurance contracts and allows entities to use a wide variety of accounting practices, reflecting national accounting practices.
2.4The objective of IFRS 17 is set out in paragraph 1 of the standard:
"IFRS 17 establishes principles for the recognition, measurement, presentation and disclosure of insurance contracts within the scope of the Standard. The objective of IFRS 17 is to ensure that an entity provides relevant information that faithfully represents those contracts. This information gives a basis for users of financial statements to assess the effect that insurance contracts have on the entity's financial position, financial performance and cash flows.” [IFRS 17: 1]
2.5This section of the Endorsement Criteria Assessment (ECA) provides an overview of the principal requirements of IFRS 17. It does not attempt to represent a comprehensive guide to the standard but sets out only a high-level summary of its key features.
12In December 2021 the IASB issued Initial Application of IFRS 17 and IFRS 9 – Comparative Information (Amendment to IFRS 17). See also paragraph 1.1 and the related footnote above.
13The 2007 Discussion Paper (receiving 162 comment letters), the 2010 Exposure Draft (receiving 251 comment letters), the 2013 Exposure Draft (receiving 194 comment letters) and the 2019 Exposure Draft Amendments to IFRS 17 (receiving 123 comment letters).
14Including users and preparers of financial statements, actuaries, auditors, regulators and others.
Description of IFRS 17's main accounting requirements
Scope
2.6IFRS 17 identifies as insurance contracts those contracts under which the entity accepts significant15 insurance risk from another party (the policyholder) by agreeing to compensate the policyholder if a specified uncertain future event (the insured event) adversely affects the policyholder. [IFRS 17 Appendix A] The definition of insurance contract remains unchanged from that in IFRS 4.
"Like IFRS 4, IFRS 17 applies to all companies that issue insurance contracts and not only to insurance companies”. [IASB Effects Analysis16 p.21]
"Non-financial companies providing insurance services are generally not expected to apply IFRS 17 because of the scope exclusions in the Standard”. [IASB Effects Analysis p.21]
2.7IFRS 17 applies to:
- insurance contracts (including reinsurance contracts) an entity issues;
- reinsurance contracts an entity holds; and
- investment contracts with discretionary participation features17 an entity issues, provided the entity also issues insurance contracts. [IFRS 17: 3]
2.8Investment contracts with discretionary participation features often have characteristics such as long maturities, recurring premiums and high acquisition cash flows which are more commonly found in insurance contracts than in most other financial instruments. These contracts are sometimes linked to the same underlying pool of assets as insurance contracts or share in the performance of insurance contracts. Although these contracts do not meet the definition of insurance contracts (as they do not include a transfer of significant insurance risk), they are accounted for under IFRS 17, subject to some modifications to the general requirements, but only if the entity also issues insurance contracts. Other companies apply IFRS 9 to such contracts.
15IFRS 17: B18-B23 provide application guidance on the assessment of whether the insurance risk is significant.
16IFRS Standards Effects Analysis - IFRS 17 Insurance Contracts (May 2017). See link: IFRS 17 Effects Analysis
17IFRS 17 defines 'investment contract with discretionary participation features' as a financial instrument that provides a particular investor with the contractual right to receive, as a supplement to an amount not subject to the discretion of the issuer, additional amounts:
- that are expected to be a significant portion of the total contractual benefits;
- the timing or amount of which are contractually at the discretion of the issuer; and
- that are contractually based on:
- the returns on a specified pool of contracts or a specified type of contract;
- realised and/or unrealised investment returns on a specified pool of assets held by the issuer; or
- the profit or loss of the entity or fund that issues the contract.
"Feedback received by the Board indicated that few investment contracts with discretionary participation features are issued by non-insurers. As a result, most of these contracts are expected to continue to be accounted for as insurance contracts rather than as financial instruments applying IFRS 9”. [IASB Effects Analysis p.14]
2.9Some 'fixed-fee service contracts', such as roadside assistance contracts, meet the definition of an insurance contract, even though their primary purpose is the provision of services for a fixed fee. IFRS 17 introduces an irrevocable choice to account for such contracts by applying either IFRS 17 or IFRS 15 Revenue from Contracts with Customers if certain conditions are met. An entity can make this irrevocable accounting choice on a contract-by-contract basis.
2.10Some other contracts meet the definition of an insurance contract but limit the compensation for insured events to the amount otherwise required to settle the policyholder's obligation created by the contract (for example, loans with death waivers). An entity is required to make an irrevocable choice to account for these contracts either by applying IFRS 9 or IFRS 17 (unless those contracts are specifically excluded by paragraph 7 of IFRS 17). This irrevocable choice is made for each portfolio of insurance contracts.
2.11The scope of IFRS 17 specifically excludes various items that may meet the definition of an insurance contract, including a) warranties provided by a manufacturer, dealer or retailer in connection with the sale of its goods or services to a customer and b) some credit card contracts (but only if the entity does not reflect an assessment of the insurance risk associated with an individual customer in setting the price of the contract with that customer). An entity applies other relevant IFRS Standards to account for these items.
Separation of components
2.12IFRS 17 separates specified embedded derivatives, distinct investment components and distinct performance obligations from the insurance contracts. An entity applies the requirements in IFRS 17 to the remaining components of the host insurance contract.
2.13The IASB's aim in separating such non-insurance components from an insurance contract is to improve comparability. Accounting for such components using other applicable IFRS standards makes them more comparable to similar contracts issued as separate contracts and it allows users of financial statements to better compare financial information of entities in different businesses or industries.
Level of aggregation
2.14IFRS 17 divides insurance contracts into groups for purposes of recognition and measurement. An entity is required to identify portfolios of insurance contracts. Under IFRS 17, "a portfolio comprises contracts subject to similar risks and managed together". [IFRS 17:14]
2.15In accordance with IFRS 17, once a portfolio is identified, an entity divides it into a minimum of three different sub-groups:
- a group of contracts that are onerous at initial recognition;
- a group of contracts that at initial recognition have no significant possibility of becoming onerous subsequently; and
- a group of the remaining contracts in the portfolio.
2.16An entity is not allowed to include contracts issued more than one year apart in the same group, therefore, further sub-groups might be necessary. This requirement is often referred to as the 'annual cohorts' requirement and is intended to prevent perpetual open portfolios18.
2.17An entity establishes the groups at initial recognition (and adds contracts under certain circumstances) but it does not subsequently reassess the composition of the groups.
Recognition and measurement
2.18An insurance contract typically combines features of a financial instrument and a service contract; these components are commonly interrelated. The measurement models19 in IFRS 17 account for both components. The measurement of obligations at a current value is consistent with the requirements for comparable financial instruments. Recognising profit as services are provided is also consistent with the requirements in IFRS 15. For groups of onerous insurance contracts, recognising expected losses immediately is consistent with the recognition of losses for onerous contracts in accordance with IFRS 15 and IAS 37 Provisions, Contingent Liabilities and Contingent Assets.
2.19IFRS 17 requires entities to measure groups of insurance contracts at:
- a current estimate of the future cash flows, including an adjustment for the timing and risk of those cash flows (the fulfilment cash flows); and
- an amount representing the unearned profit relating to services still to be provided (the contractual service margin).
2.20In the IASB's view, "IFRS 17 provides consistent principles for all aspects of the accounting for insurance contracts. It also removes the diversity in insurance accounting for companies that have been applying IFRS Standards, enabling investors, analysts and others to meaningfully compare companies, contracts and industries." [IASB Effects Analysis p.7]
18For a detailed assessment of the level of aggregation requirements refer to Section 3 priority issue C: Grouping insurance contracts: profitability buckets and annual cohorts.
19There are three measurement models in IFRS 17. These are discussed in more detail in paragraphs 2.42 – 2.77 below: 'Overview of accounting models'.
Profit recognition
2.21Under IFRS 17, an entity recognises the profit from a group of insurance contracts over the period the entity provides insurance contract services, and as the entity is released from risk. If a group of contracts is or becomes loss-making, an entity recognises the loss immediately. As mentioned above, this is broadly consistent with the general principles in IFRS 15 and IAS 37.
2.22IFRS 17 Appendix A defines 'insurance contract services' as comprising insurance coverage, investment return-service (for insurance contracts without direct participation features) and investment-related service (for insurance contracts with direct participation features).
2.23Claims and expenses (other than insurance acquisition expenses – see paragraph 2.56 below) are recognised when incurred.
Modification and derecognition
2.24IFRS 17 requires the derecognition of an insurance contract when, and only when, it is extinguished (i.e. the obligation expires or is discharged or cancelled) or when it is modified in certain specified ways [IFRS 17 paragraph 74].
2.25In certain cases, specified in IFRS 17 paragraph 72, the modification of a contract leads to derecognition of the contract and recognition of the modified contract as a new contract. Such cases include those when the modification would cause the contract to fall outside the scope of IFRS 17, to no longer meet the definition of an insurance contract with direct participation features or to no longer meet the eligibility criteria for the PAA. Other contract modifications are treated as changes in estimates of cash flows [IFRS 17 paragraph 73].
Presentation of income and expenses
2.26IFRS 17 requires entities to present separately insurance revenue (that excludes the receipt of any investment component20), insurance service expenses (that excludes the repayment of any investment components) and insurance finance income or expenses.
2.27As noted above, IFRS 17 requires entities to exclude investment components from insurance revenue and incurred claims. This presentation aims to faithfully represent the similarities between financial instruments (accounted for under IFRS 9) and investment components embedded in insurance contracts, resulting in enhanced comparability with the financial information of entities in other industries, such as banking.
2.28Consistently with IAS 1 Presentation of Financial Statements, requiring insurance finance income or expense to be presented separately from the insurance service
20IFRS 17 defines 'investment component' as the amounts that an insurance contract requires the entity to repay to a policyholder in all circumstances, regardless of whether an insured event occurs.
result aims to provide useful information about different aspects of the entity's performance.
"IFRS 17 is expected to reveal economic volatility of insurance contracts, making the performance of insurance companies more transparent. At the same time, the insurance service result will not be affected by changes in discount rates. IFRS 17 also permits companies to report the effects of changes in discount rates in other comprehensive income”. [IASB Effects Analysis p.87]
2.29Entities are required to make an accounting policy choice for each portfolio of insurance contracts on how to present insurance finance income or expenses. Such insurance finance income or expenses is either all included in profit or loss or is disaggregated between profit or loss and other comprehensive income21.
Disclosures
2.30IFRS 17 paragraph 93 states that "The objective of the disclosure requirements is for an entity to disclose information in the notes that, together with the information provided in the statement of financial position, statement(s) of financial performance and statement of cash flows, gives a basis for users of financial statements to assess the effect that contracts within the scope of IFRS 17 have on the entity's financial position, financial performance and cash flows."
2.31To achieve this disclosure objective, information is required about the amounts recognised in the financial statements, the significant judgements and changes in those judgements, and the nature and extent of risks that arise from insurance contracts. In situations in which complying with the specific disclosure requirements is not sufficient to meet the disclosure objective, IFRS 17 requires an entity to disclose additional information necessary to meet that objective.
2.32By specifying the objective of the disclosures, the IASB aims to ensure that entities provide the information that is most relevant for their circumstances and to emphasise the importance of communication to users of financial statements rather than compliance with detailed and prescriptive disclosure requirements.
Transition
2.33Unless impracticable, an entity is required to apply the standard retrospectively. When full retrospective application is impracticable for a group of contracts, an entity has a free choice to adopt either:
- the modified retrospective approach, or
- the fair value approach.
21For a detailed assessment of the Other comprehensive income option refer to Appendix B Assessment of remaining significant issues, pages 168-170.
2.34The modified retrospective approach permits specific modifications to retrospective application. These modifications allow an entity to determine specified matters at the transition date rather than at initial recognition of a group of insurance contracts and use specified proxies for some requirements.
2.35Under the fair value approach, an entity is required to determine the contractual service margin22 at the transition date. This is calculated as the difference between the measurement of the fair value of a group of insurance contracts and the fulfilment cash flows of the group as at that date.
2.36The choice of transition method is made at the level of a group of contracts23.
Reinsurance
2.37IFRS 17 Appendix A defines a reinsurance contract as "an insurance contract issued by one entity (the reinsurer) to compensate another entity for claims arising from one or more insurance contracts issued by that other entity (underlying contracts)".
2.38An entity that holds a reinsurance contract does not normally have a right to reduce the amounts it owes to the underlying policyholder by amounts it expects to receive from the reinsurer (in other words the entity retains in full the liability to the underlying policyholder). As a result, IFRS 17 requires a reinsurance contract held to be accounted for separately from the underlying insurance contracts to which it relates, to reflect its separate rights and obligations.
2.39The general requirements in IFRS 17 are modified for reinsurance contracts held to reflect the different nature of such contracts.
2.40One key modification relates to income recognition for reinsurance contracts held when they cover onerous groups of underlying insurance contracts. On initial recognition of onerous underlying insurance contracts an entity is required to recognise the loss immediately in profit or loss. Provided that an entity entered into the group of reinsurance contracts held before or at the same time as the onerous underlying insurance contracts are recognised, the entity recognises the corresponding loss recoveries from reinsurance contracts held in profit or loss at the same time24. Subsequently, the adjusted net gain (or net cost) of purchasing the reinsurance contract is recognised in profit or loss over the coverage period of the reinsurance contract.
2.41Reinsurance contracts issued should be accounted for by the reinsurer using either the general model or the premium allocation approach, in the same way as other insurance contracts issued (see the overview of accounting models below).
22Or the loss component of the liability for remaining coverage, in the case of a group of onerous contracts.
23For a detailed assessment of the transition requirements refer to Appendix B Assessment of remaining significant issues, pages 171 - 173.
24For a detailed assessment of the recognition of income from reinsurance to match losses from onerous underlying contracts refer to Appendix B Assessment of remaining significant issues, pages 153-156.
Overview of accounting models
1 - General Measurement Model (GMM)
2.42The GMM is applied to all insurance contracts, unless they are insurance contracts with direct participation features to which the Variable Fee Approach applies (refer to paragraphs 2.60 to 2.71 below) or insurance contracts to which the entity has elected to apply the Premium Allocation Approach (refer to paragraphs 2.72 to 2.77 below).
Initial recognition
2.43On initial recognition25 an entity measures insurance contracts at the total of:
- The fulfilment cash flows, which comprise:
- the present value of probability-weighted expected cash flows (which reflect financial risk); and
- an explicit risk adjustment for non-financial risk (such as insurance risk).
- The contractual service margin (or unearned profit).
Estimates of future cash flows
2.44An entity is required to include in the measurement of a group of insurance contracts all the future cash flows within the boundary of each contract in the group. These:
- incorporate, in an unbiased way, all reasonable and supportable information available without undue cost or effort about the amount, timing and uncertainty of those future cash flows;
- reflect the perspective of the entity (provided that relevant market variables are consistent with observable market prices); and
- are current and explicit.
2.45In accordance with paragraph 34 of IFRS 17, cash flows are within the boundary of an insurance contract "if they arise from substantive rights and obligations that exist during the reporting period in which the entity can compel the policyholder to pay the premiums or in which the entity has a substantive obligation to provide the policyholder with insurance contract services.”
25For a detailed assessment of the IFRS 17 requirements for contracts acquired in their settlement period refer to Appendix B Assessment of remaining significant issues, pages 157 - 159.
Discount rates
2.46IFRS 17 does not prescribe the specific discount rates to be used but sets out high-level principles26. In accordance with IFRS 17 paragraph 36, the discount rates applied to the estimates of future cash flows shall:
"(a) reflect the time value of money, the characteristics of the cash flows and the liquidity characteristics of the insurance contracts;
(b) be consistent with observable current market prices (if any) for financial instruments with cash flows whose characteristics are consistent with those of the insurance contracts, in terms of, for example, timing, currency and liquidity; and
(c) exclude the effect of factors that influence such observable market prices but do not affect the future cash flows of the insurance contracts."
Risk adjustment for non-financial risk
2.47IFRS 17 requires entities to reflect the risk that is inherent in insurance contracts by considering a risk adjustment for non-financial risk in the measurement of the fulfilment cash flows27.
2.48IFRS 17 Appendix A defines risk adjustment for non-financial risk as "the compensation an entity requires for bearing the uncertainty about the amount and timing of the cash flows that arises from non-financial risk as the entity fulfils insurance contracts".
Contractual service margin
2.49The contractual service margin is the balance sheet item representing the unearned profit the entity will recognise as it provides services in respect of a group of insurance contracts.
2.50The contractual service margin is a residual amount, measured at the amount that results in no income or expenses on initial recognition. However, for contracts that are onerous at initial recognition, entities are required to recognise a loss in profit or loss for the net outflow and the contractual service margin is zero.
26For a detailed assessment of the requirements relating to discount rates refer to Section 3 priority issue B: 'Discount rates'.
27For a detailed assessment of the risk adjustment for non-financial risk refer to Appendix B Assessment of remaining significant issues, pages 147 - 149.
Subsequent measurement
2.51The carrying amount of a group of insurance contracts at the end of each reporting period is the sum of:
- the liability for remaining coverage comprising:
- the fulfilment cash flows related to future service allocated to the group at that date;
- the contractual service margin of the group at that date; and
- the liability for incurred claims, comprising the fulfilment cash flows related to past service allocated to the group at that date. [IFRS 17: 40]
2.52Changes in the carrying amounts of the above liabilities are recognised in profit or loss, presenting separately the effects corresponding to insurance revenue, insurance service expenses and insurance finance income or expenses.
Contractual service margin – subsequent measurement
2.53In each period, an entity recognises as insurance revenue an amount of the contractual service margin representing the provision of insurance contract services arising from the group of insurance contracts in that period.
2.54The recognition of the contractual service margin in profit or loss is determined by identifying coverage units that reflect the quantity of benefits provided under the insurance contracts and their expected coverage period28.
2.55At the end of the reporting period, the remaining contractual service margin on the balance sheet represents the profit in the group of insurance contracts that has not yet been recognised in profit or loss because it relates to future service29.
In the UK, the GMM is expected to be applied to insurance contracts such as life insurance (protection business), annuity contracts and longer-term general insurance contracts.
Insurance acquisition expenses
2.56Insurance acquisition expenses are cash flows arising from the costs of selling, underwriting and starting a group of insurance contracts that are directly related to the portfolio to which the group belongs. An allocation of such cash flows is treated as within the boundary of an insurance contract and is included in the estimate of future cash flows.
28For a detailed assessment of IFRS 17's requirements for the allocation of the contractual service margin refer to Section 3 priority issue A: 'Profit recognition – allocation of CSM for annuities'.
29For a detailed assessment of IFRS 17's requirements in respect of interest accretion at the locked-in rate under the GMM refer to Appendix B Assessment of remaining significant issues, pages 150 - 152.
2.57Any insurance acquisition cash flows paid before the relevant group of contracts is recognised are recognised as an asset, and then derecognised and subsumed within the CSM determined on initial recognition of a group of contracts. An entity continues to recognise an asset for insurance acquisition cash flows to the extent that the asset relates to groups that will include insurance contracts expected to arise from renewals.
2.58The standard's approach reduces the CSM at initial recognition. Consequently, as the CSM is released, insurance acquisition expenses are reflected in profit or loss as a reduction in revenue. To recognise the fact that insurance contracts are generally priced to recover acquisition costs, the standard requires the part of the premium that is intended to cover insurance acquisition expenses to be added back to insurance revenue over the coverage period. The same amount is recognised as insurance service expenses over the same period.
2.59At the end of each reporting period an entity is required to assess the recoverability of any asset for insurance acquisition cash flows if facts and circumstances indicate the asset may be impaired.
2 - Variable Fee Approach (VFA)
2.60The VFA is applied to insurance contracts with direct participation features. It was developed to reflect the contractual linkage between certain insurance liabilities and a pool of 'underlying items', which in practice are often the assets held to back those liabilities.
2.61In accordance with IFRS 17 paragraph B101, insurance contracts with direct participation features are "insurance contracts that are substantially investment-related service contracts under which an entity promises an investment return based on underlying items."
2.62In addition, IFRS 17 specifies certain conditions to qualify as an insurance contract with direct participation features. The objective of these conditions is to ensure that insurance contracts with direct participation features are contracts under which the entity's obligation to the policyholder is the net of:
- the obligation to pay the policyholder an amount equal to the fair value of the underlying items; and
- a variable fee for future services.
2.63The variable fee for future services comprises the amount of the entity's share of the fair value of the underlying items, less fulfilment cash flows that do not vary based on the returns on underlying items.
- that are expected to be a significant portion of the total contractual benefits;
- the timing or amount of which are contractually at the discretion of the issuer; and
- that are contractually based on:
- the returns on a specified pool of contracts or a specified type of contract;
- realised and/or unrealised investment returns on a specified pool of assets held by the issuer; or
- the profit or loss of the entity or fund that issues the contract.
2 – Variable Fee Approach (VFA)
2.60The VFA is applied to insurance contracts with direct participation features. It was developed to reflect the contractual linkage between certain insurance liabilities and a pool of 'underlying items', which in practice are often the assets held to back those liabilities.
2.61In accordance with IFRS 17 paragraph B101, insurance contracts with direct participation features are "insurance contracts that are substantially investment-related service contracts under which an entity promises an investment return based on underlying items."
2.62In addition, IFRS 17 specifies certain conditions to qualify as an insurance contract with direct participation features. The objective of these conditions is to ensure that insurance contracts with direct participation features are contracts under which the entity's obligation to the policyholder is the net of:
- the obligation to pay the policyholder an amount equal to the fair value of the underlying items; and
- a variable fee for future services.
2.63The variable fee for future services comprises the amount of the entity's share of the fair value of the underlying items, less fulfilment cash flows that do not vary based on the returns on underlying items.
2.64An entity performs an assessment of the eligibility for the VFA at inception of the contract and it is not reassessed subsequently, unless the contract is modified 30.
2.65Reinsurance contracts issued and reinsurance contracts held cannot be insurance contracts with direct participation features for the purposes of IFRS 17 and hence cannot qualify for the VFA31.
2.66The VFA is largely the same as the GMM, except for the measurement of the contractual service margin after initial recognition, which is adjusted to reflect the variable nature of the fee. The entity's share of the change in fair value of the underlying items is treated as relating to future service and therefore included in the contractual service margin and recognised over time as insurance contract services are provided.
2.67A primary measurement difference between the GMM and the VFA impacts both the timing and the presentation in profit or loss of changes in the fulfilment cash flows arising from the time value of money and financial risks:
- Under the VFA, these changes are regarded as part of the variability of the fee for future service and recognised in the contractual service margin. This is then recognised through insurance revenue in line with the provision of insurance contract services, as the contractual service margin is recognised.
- Under the GMM, these changes are recognised immediately as insurance finance income or expense.
2.68Adjustments to the contractual service margin are determined using current discount rates, unlike under the GMM where the adjustments to the contractual service margin are determined using locked-in discount rates.
Risk Mitigation Option
2.69Insurance entities are exposed to financial risks arising from insurance contracts. When applying the VFA, the contractual service margin is adjusted for these changes so there is not an immediate effect in profit or loss.
2.70Insurance entities often enter into arrangements (for example using derivatives as hedging instruments) to mitigate the effect of financial risks arising from insurance contracts. The effect of these arrangements is generally accounted for in profit or loss.
2.71Provided certain criteria are met, insurance entities applying the VFA are allowed (but not required) to present in profit or loss the income and expenses arising from financial risk on both the insurance contracts and the related risk mitigation arrangements. This allows entities to reduce accounting mismatches that otherwise would occur32.
In the UK, the VFA is expected to be applied to insurance contracts such as unit-linked contracts and with-profits contracts33.
3 – Premium Allocation Approach (PAA)
2.72The PAA is optional. Entities may simplify the measurement of a group of insurance contracts that would otherwise be accounted for under the GMM by using the PAA if, and only if, at inception of the group:
- the PAA provides a reasonable approximation to the GMM; or
- the coverage period of each contract in the group is one year or less.
Initial recognition
2.73The initial measurement of the liability equals the premium received. Unless the group of insurance contracts is onerous, the entity does not identify explicitly the components otherwise used in IFRS 17 to measure the insurance contracts, i.e., the estimate of future cash flows, the time value of money and the effects of risk.
Subsequent measurement
2.74Subsequently, the liability for remaining coverage is recognised over the coverage period on the basis of the passage of time, unless the expected pattern of release from risk differs significantly from the passage of time, in which case it is recognised based on the expected timing of incurred claims and benefits.
2.75Under the PAA, entities:
- should accrete interest on the liability for remaining coverage only for groups of insurance contracts that have a significant financing component; and
- assess whether groups of contracts are onerous only when facts and circumstances indicate that a group of insurance contracts has become onerous.
2.76Under the PAA, entities are permitted to recognise all insurance acquisition cash flows as an immediate expense, provided the coverage period of each contract in the group is no more than one year. Alternatively, insurance acquisition cash flows may be allocated to groups of insurance contracts, and included in the measurement of those groups, as they would be under the GMM (see paragraphs 2.56 – 2.59 above).
2.77The liability for incurred claims is measured using the GMM. However, as a practical expedient the entity is not required to adjust future cash flows for the time value of money and the effect of financial risk if those cash flows are expected to be paid or received in one year or less from the date the claims are incurred.
In the UK, the PAA is expected to be applied to insurance contracts such as short-term general insurance and short-term life contracts. The PAA is similar to current accounting in the UK under IFRS 4 for general insurance contracts.
Presentation requirements
Statement of Financial Position
2.78IFRS 17 simplifies the presentation of the statement of financial position but requires an entity to present groups of insurance (or reinsurance) contracts that are in an asset position separately from groups of insurance (or reinsurance) contracts that are in a liability position.
| IFRS 17 Statement of Financial Position: required insurance-related line items | |
|---|---|
| Insurance contract assets | Insurance contract liabilities |
| Reinsurance contract assets | Reinsurance contract liabilities |
Statement of Financial Performance
2.79IFRS 17 requires an entity to disaggregate the amounts recognised in the statement of profit or loss and other comprehensive income into:
- an insurance service result; and
- insurance finance income or expenses.
2.80An entity is also required to present income or expenses from reinsurance contracts held separately from expenses or income from insurance contracts issued.
| IFRS 17 illustrative Statement of Profit or Loss and Other Comprehensive Income | |
|---|---|
| Insurance revenue | XXX |
| Incurred claims and expenses | (XXX) |
| Net expenses from reinsurance contracts | (XXX) |
| Insurance service result | XXX |
| Investment income34 | XXX |
| Insurance finance income / (expenses) | (XXX) |
| Net finance result | XXX |
| Profit / (loss) | XXX |
| Other comprehensive income | |
| Investment income 35 | XXX |
| Insurance finance income / (expenses) (optional) | (XXX) |
| Total other comprehensive income | XXX |
| Total comprehensive income | XXX |
"The total profit or loss of a group of insurance contracts is the difference between total cash inflows and outflows arising from the contracts.
IFRS 17 does not change the total profit or loss of a group of insurance contracts recognised over the duration of the contracts. IFRS 17 changes the amounts recognised in each reporting period and how the components of the profitability of the contracts are disaggregated in the statement of comprehensive income”. [IASB Effects Analysis p.85]
3 Technical accounting criteria assessment
Approach to the assessment against the technical accounting criteria
3.1SI 2019/685 requires an assessment of whether IFRS 17 "meets the criteria of understandability, relevance, reliability and comparability required of the financial information needed for making economic decisions and assessing the stewardship of management" [regulation 7(1)(c)]. We refer to these criteria collectively as the technical accounting criteria.
3.2An explanation of the basis for and our interpretation of the technical accounting criteria is provided in Section 1.
Development of approach
3.3In carrying out this assessment we have considered all principal aspects of IFRS 17. However, in the interests of efficiency and effectiveness we have reported a detailed analysis against the technical accounting criteria only in relation to significant issues (an 'exceptions-based approach').
3.4There are a number of aspects of the standard in respect of which stakeholders have not raised significant concerns. For example, the measurement of estimated future cash flows for groups of contracts is a fundamental element of IFRS 17 and is addressed in the standard by specific requirements and extensive application guidance. However, based on our work and on information from stakeholders, we are not aware of significant endorsement concerns in relation to these requirements in the UK. Therefore, under an exceptions-based approach, we have not included a detailed report on the assessment of this issue in this Endorsement Criteria Assessment (ECA). Similarly, no significant concerns have been raised concerning IFRS 17's requirements in relation to aspects including the scope of the standard, the definition of insurance risk, recognition and derecognition, or disclosure.
3.5The detailed analyses against the technical accounting criteria in this ECA therefore focus on issues raised by UK stakeholders or on significant issues identified by the UKEB Secretariat. All such issues have been discussed with the Insurance Technical Advisory Group (TAG)36.
3.6The analysis against the technical accounting criteria has been performed on a topic-by-topic basis, rather than on a criterion-by-criterion basis, to minimise repetition. The analysis considers IFRS 17's requirements in full, taking into account presentation and disclosure requirements as well as recognition, measurement, modification and derecognition requirements.
3.7In conducting our overall assessment against the technical accounting criteria we are required to adopt an absolute, rather than a relative, approach. This means that the assessment is an absolute one against the criteria (does IFRS 17 provide information that is understandable, relevant, reliable and comparable?) rather than a relative one (does IFRS 17 provide information that is more understandable, relevant, reliable and comparable than current, or any other, accounting?). When an assessment of a specific significant issue in this section or in Appendix B uses comparative language (e.g. 'more relevant' or 'enhances comparability'), the intended comparison is with the effect of not including the requirement, rather than with current UK accounting practice under IFRS 4. The overall assessment of IFRS 17 against the technical accounting criteria remains an absolute one. Consideration of whether IFRS 17 is likely to improve the quality of financial reporting is separate from this assessment and is included in Section 4 (the IFRS 17 UK long term public good assessment).
Identification of 'significant issues'
3.8In this context 'significant issues' means aspects of the standard:
- where there is a question over whether IFRS 17's requirements on that aspect meet all the technical accounting criteria; and
- which have a potentially significant impact in the UK: that is, the issue is likely to be material to at least some companies and/or the efficient and effective functioning of UK capital markets.
3.9The process adopted to identifying significant issues has spanned a number of months and has been responsive to stakeholder input throughout that period. Principal components of that work included:
- desktop analysis of the standard, the basis for its requirements, and of commentaries and technical analyses issued by, for example, accounting firms and professional bodies;
- consideration of feedback from UK stakeholders (including the Financial Reporting Council) on IFRS 17 as issued in 2017 and their input to the amendments finalised in 2020, including comment letters submitted to the IASB;
- review of submissions to EFRAG from UK stakeholders, discussions with EFRAG staff and review of EFRAG's Draft and Final Endorsement Advice;
- discussions with insurance companies and the Association of British Insurers, and review of responses to the UKEB Preparer survey;
- consideration of investor and analyst views expressed to the IASB during its outreach work37, discussions with UK-based analysts and rating agencies and review of responses to the UKEB User survey;
- input from the Insurance TAG, initially in developing the group's work plan and subsequently in developing its forward agenda on an ongoing basis; and
- input from insurance companies, accounting firms and Lloyd's of London in relation to reinsurance to close (RITC) transactions, including through an RITC Working Group.
3.10A further consideration during this process was to separate out issues that had the potential to be endorsement issues from those that were questions of interpretation or implementation. The distinction between endorsement and interpretation or implementation issues is not always clear cut. However, a number of issues arising from the process set out above have been judged to be interpretation or implementation questions so are not reported on in this ECA. For example, such issues could include requirements of IFRS 17 which are considered to meet the technical accounting criteria but which are complex or require significant judgement to apply to particular fact patterns.
3.11Our outreach has provided assurance that there are no further significant issues of concern to UK stakeholders that we have not addressed. For example, our surveys of insurance companies and users of insurance company accounts asked respondents to highlight issues for consideration during the endorsement assessment. Similarly, in meetings with users of accounts we have asked for them to inform us of any additional issues: no significant new matters have arisen.
3.12The issue of the draft ECA for public consultation provided stakeholders with a further opportunity to raise issues with us and to ensure the completeness of the assessment. Respondents to that consultation raised two further issues for UKEB consideration: the accounting treatment of premium receivables from intermediaries and the application of IFRS 17 to ‘hybrid' contracts. After due consideration the UKEB decided not to include an analysis of those issues in this ECA since it concluded these issues are primarily matters of interpretation (further explanation is provided in the IFRS 17 Feedback Statement). Otherwise, to the extent respondents provided an explicit response to the question, respondents agreed that the assessment captured all significant issues.
Identification of 'priority issues'
3.13A subset of significant issues, referred to as 'priority issues', has been identified. These are issues that are likely to have one or more of the following features:
- they relate to a pervasive aspect of the standard;
- they have generated significant UK public interest and/or controversy;
- they are estimated to be material to UK insurers; and/or
- they are significant to the long term public good assessment of IFRS 17.
3.14Detailed individual assessments of priority issues were presented to the UKEB for discussion at Board meetings.
Presentation in the ECA
3.15As explained above, our approach involves reporting our assessment against the technical accounting criteria for each significant issue.
3.16Assessments of the priority issues have been included in this section of the ECA – see below from paragraph 3.20. The priority issues are:
- Profit recognition – Contractual Service Margin (CSM) allocation for annuities;
- Discount rates;
- Grouping insurance contracts: profitability buckets and annual cohorts; and
- With-profits: inherited estates.
3.17The assessments of the remaining significant issues have been included in Appendix B. The topics assessed there are:
- Risk adjustment for non-financial risk;
- Interest accretion at the locked-in rate for CSM under the General Measurement Model (GMM);
- Recognition of income from reinsurance to match losses from onerous underlying contracts;
- Contracts acquired in their settlement period;
- Contracts that change nature over time;
- Reinsurance to close transactions in the Lloyd's market;
- Other comprehensive income option;
- Transition requirements; and
- Other Variable Fee Approach (VFA) issues:
- Ineligibility of reinsurance contracts for VFA;
- Prohibition of retrospective application of the risk mitigation option;
- Eligibility for VFA when there are mutualised cash flows; and
- Non-profit contracts written by a with-profits fund.
3.19Our overall conclusion on whether IFRS 17 as a whole meets the technical accounting criteria is set out at the end of this Section 3.
Priority issues
A: Profit recognition – CSM allocation for annuities
Introduction
3.20The CSM is the balance sheet item representing the unearned profit the entity will recognise as it provides services in respect of a group of insurance contracts. The issues discussed below relate to the recognition of that profit for annuities, including bulk purchase annuities (BPAs), under IFRS 17's general measurement model (GMM).
3.21IFRS 17 sets out, at a high level, how CSM should be recognised in profit or loss in each period but does not provide detailed guidance or detailed requirements for particular product types. Significant judgement is required to apply the standard's requirements in the case of annuities and BPAs, including in respect of determining coverage units that represent the provision of service under a group of insurance contracts.
3.22There has been extensive debate in the UK over the interpretation of the requirements of IFRS 17 for determining coverage units that appropriately reflect the insurance contract services provided for annuities and BPAs. The main questions include how to determine the insurance coverage and the pattern of profit recognition for this service, and how the quantity of benefits should be split between insurance coverage and investment-return service. In particular, two main interpretations of the standard's requirements in respect of insurance coverage emerged and a technical paper seeking advice from the IASB was submitted by a group of insurers and auditors convened by the ICAEW Insurance Committee38. The submission sought guidance regarding the interpretation of IFRS 17 with respect to the service provided by a life contingent annuity and the application of IFRS 17 principles for recognising that service through the release of the CSM.
3.23The IASB's IFRS Interpretations Committee (the IC) considered the matter and issued a Tentative Agenda Decision that only one of the two approaches set out in the submission met the principle in IFRS 17. While the IC's decision is not yet final (the Tentative Agenda Decision is open for public consultation until 23 May 2022), the analysis in this ECA has been written on the basis that the tentative decision is finalised without major changes.
3.24Some stakeholders are concerned that, following the IC's tentative decision, the accounting will not fairly reflect the economic substance of the transactions, will not provide useful or understandable financial information and will therefore not meet the technical accounting criteria. These stakeholders are also concerned that an inappropriate accounting outcome could have a material impact on annuity providers and a detrimental impact on the UK annuity market (see also Section 4 paragraphs 4.157 – 4.169).
IFRS 17 requirements
Initial recognition
3.25On initial recognition of a group of insurance contracts, IFRS 17 requires an entity to recognise a CSM, a component of the asset or liability for the group of insurance contracts that represents the unearned profit the entity will recognise as it provides insurance contract services in the future. [IFRS 17: 32, 38]
3.26At initial recognition, the CSM is measured at an amount that, unless the group of contracts is onerous, results in no income or expense from:
- the initial recognition of an amount for the fulfilment cash flows;
- any cash flows at initial recognition; and
- the derecognition of any asset or liability from pre-recognition cash flows such as acquisition costs. [IFRS 17: 38]
Subsequent measurement
3.27In each period, an entity will recognise as insurance revenue an amount of CSM representing the insurance contract services provided by the group of insurance contracts in that period. [IFRS 17: 44(e)]
3.28An entity that issues insurance contracts without direct participation features recognises profit when it provides insurance coverage or any service relating to investment activities (investment-return service). [IFRS 17: Appendix A – definition of 'insurance contract services']
3.29The recognition of the CSM in profit or loss is determined by identifying coverage units that reflect the quantity of benefits provided under the insurance contracts and their expected coverage period. [IFRS 17: B119]
3.30At the end of the reporting period, the remaining CSM on the balance sheet represents the profit in the group of insurance contracts that has not yet been recognised in profit or loss because it relates to future service. [IFRS 17: 43]
Insurance coverage
3.31The IC Tentative Agenda Decision notes that the definitions of the liability for incurred claims and the liability for remaining coverage in Appendix A to IFRS 17 describe insurance coverage as 'an entity's obligation to investigate and pay valid claims for insured events'. In addition, paragraphs BC140 and BC141 of the Basis for Conclusions on IFRS 17 explain that an entity can accept insurance risk before it is obliged to perform the insurance coverage service. Therefore, in determining the quantity of the benefits of insurance coverage provided under a contract, an entity considers (a) the periods in which it has an obligation to pay a valid claim if an insured event occurs; and (b) the amount of the claim if a valid claim is made.
3.32The IC observed that, under the terms of the annuity contracts being considered, an entity is obliged to pay a periodic amount from the start of the annuity period for each year of the policyholder's survival (the insured event). Survival in one year does not oblige the entity to pay amounts that compensate the policyholder for surviving in future years; that is, claim amounts payable to the policyholder in future years are contingent on the policyholder surviving in those future years.
3.33The IC therefore concluded that, in determining the quantity of benefits of insurance coverage for survival provided under an annuity contract, a method based on the amount of the annuity payment the policyholder is able to validly claim in the current period meets IFRS 17's principle.
Investment return service
3.34IFRS 17 requires an entity to identify coverage units for insurance contracts considering the quantity of benefits and the expected coverage period of investment-return service, if any, in addition to the insurance coverage. [IFRS 17: BC283A39]
3.35An investment-return service is provided only if:
- an investment component exists, or the policyholder has a right to withdraw an amount;
- the entity expects that amount to include an investment return; and
- the entity expects to perform investment activity to generate that investment return. [IFRS 17: B119B]
3.36IFRS 17 provides no further guidance on determining the relative weighting of investment-return service and insurance coverage, nor on how to determine the amount to recognise in a period in respect of investment-return service. The IC's Tentative Agenda Decision does not address these issues.
Disclosures
3.37Entities are required to disclose quantitative information about when they expect to recognise in profit or loss the CSM remaining at the end of the reporting period, providing time bands. [IFRS 17: 109]
3.38Determining the quantity of benefits provided by an insurance contract considering either investment-return service or investment-related service40 in addition to insurance coverage adds complexity and judgement (IFRS 17: BC366B). IFRS 17 also requires an entity to disclose significant judgements made in applying the standard. This includes the approach used to determine the relative weighting of the benefits provided by insurance coverage and investment-return service. [IFRS 17: 117(c)(v)]
Determination of CSM amortisation – accounting impact
Initial recognition
3.39At initial recognition, the CSM is equal to the present value of risk-adjusted future cash inflows less the present value of risk-adjusted future cash outflows. For a group of profitable insurance contracts, no amount is recognised in profit or loss on initial recognition. Profit is instead deferred on the balance sheet and recognised in profit or loss over the coverage period.
3.40The CSM represents the margin the entity has charged for the services it provides in addition to bearing risk. The expected margin charged for bearing risk is instead represented by the risk adjustment for non-financial risk. [IFRS 17: BC222]
Subsequent measurement
3.41As noted above, IFRS 17 contains no requirements or guidance specifically for annuities and BPAs. IFRS 17's general requirements, however, mean that profits from annuities will be spread over the coverage period. The coverage period is the probability-weighted average duration of the contracts in the group (based on life expectancy). The pattern of CSM release will be a matter of judgement in respect of the 'quantity of benefits' provided and the relative weighting applied to the insurance coverage and investment-return service, if any. [IFRS 17: B119(a)]
3.42The conditions for recognition of an investment-return service (see paragraphs 3.34 – 3.36 above), and in particular the fact that policyholders have no withdrawal rights once the pay-out phase starts, mean that an investment-return service typically cannot be recognised in the annuity pay-out phase.
3.43An exception might arise when guarantee periods apply (i.e. when policyholders or their estate receive payments for the whole of the guaranteed period, irrespective of whether the policyholder dies in that period): in such cases the guaranteed amount is likely to represent an investment component and an investment-return service is likely to be recognised. No CSM for insurance coverage is expected to be recognised in such guarantee periods as no insurance coverage is provided (amounts payable are not contingent on the occurrence of an insured event). CSM for insurance coverage would be recognised in periods after the guaranteed term.
3.44Similarly, in the case of deferred annuities, it is likely that following the IC's tentative decision no insurance coverage can be recognised in the deferral period except to the extent of any death or disability benefit. This is because there can be no insured event leading to a claim during the deferral period. For deferred annuities, therefore, the expectation is for an investment-return service to be recognised in the deferral phase and any guaranteed period, and for insurance coverage to be recognised in the pay-out phase.
3.45When contracts provide both insurance coverage and investment-return services, entities will need to divide CSM between the two services (typically between the deferral and pay-out phases, or between the guaranteed and life-contingent periods of the pay-out phase).
3.46The pattern of expected cash flows and the release of the risk adjustment for non-financial risk are already included in the measurement of the fulfilment cash flows. Therefore, they are not relevant factors in determining the satisfaction of the performance obligation and provision of service. [IFRS 17: BC279(a)]
Recognition of insurance coverage service
3.47Assuming a constant annual benefit under the terms of the annuity contract, the quantity of benefits and hence the amount of CSM recognised in the income statement each period for a group of annuity contracts is expected to decline over the coverage period. This reflects the expectation of policyholder deaths during the coverage period (i.e. the number of contracts in the group).
3.48The pattern of CSM release will also be affected by whether the entity chooses to consider the time value of money in allocating the CSM equally to coverage units provided in the current period and expected to be provided in the future (in other words, whether it discounts the coverage units). Paragraph BC232 of the Basis for Conclusions on IFRS 17 states that this is a matter of judgement by the entity. Where an entity discounts the coverage units, this will increase the degree to which the amount of CSM recognised each period declines.
Assessment against the endorsement criteria
3.49IFRS 17 requires the CSM to be recognised in profit or loss over the coverage period of the group of insurance contracts, and in a pattern that reflects the provision of service. This will result in relevant information because it will enable users to evaluate the performance of an entity in line with the provision of service. This results in faithful representation of an entity's performance obligations and of its financial performance over the coverage period.
3.50Recognising the CSM in line with the provision of both insurance coverage and an investment-return service will provide relevant information to users of financial statements, reflecting the provision of all services under the contract. This benefit will be particularly important for contracts that have an insurance coverage period that differs from the period in which the policyholder benefits from an investment-return service.41 [IFRS 17: BC283B]
3.51Recognition of an investment-return service only when the policyholder benefit is not contingent on an insured event (e.g. policyholder survival) is likely to result in relevant information. In other cases, the investment activity serves to enhance the insurance coverage benefits rather than provide a separate benefit. The fact that the IASB specified conditions that are required to identify, but are not determinative of, the existence of an investment-return service, allows entities to consider their facts and circumstances and apply judgement when determining whether an insurance contract that meets the conditions provides an investment-return service, thereby enhancing relevance. [IFRS 17: BC283E]
3.52The revenue recognition approach in IFRS 17 is broadly consistent with the approach in IFRS 15 Revenue from Contracts with Customers, because revenue is recognised in line with the provision of service. Recognising revenue in this way increases the understandability of insurers' financial statements and the comparability of their accounts with accounts from entities across other industries.
3.53The disclosures required by paragraph 109 of IFRS 17, showing in which future periods an entity expects to recognise the CSM on the balance sheet, will provide users of accounts with useful information about the expected pattern of service provision, increasing the understandability of financial statements. [IFRS 17: BC283F] More generally, the disclosure required by IFRS 17 paragraph 117 of the significant judgements made in applying the standard, including the inputs, assumptions and estimation techniques used, should help users of accounts to assess the specific approach to CSM allocation applied.
Potential challenges to the endorsement criteria and mitigations
3.54IFRS 17 does not prescribe how an entity should determine the quantity of benefits provided under a contract, and thus how to determine the coverage units and their corresponding weighting. Given the possibility that different methods can be used for this calculation, there is a risk that the IFRS 17's requirements in relation to CSM allocation will lead to a divergence in application. This could result in accounts that are not easily comparable or understandable, particularly for annuity products given their long duration.
3.55Determining the quantity of benefits provided under the contract, and hence the amount of CSM to recognise in profit or loss, will require the use of significant judgement. The application of this judgement may lack consistency and/or neutrality and hence introduce a risk to reliability.
3.56In particular, approaches for the allocation of CSM between insurance coverage and investment-return services, and for the weighting of coverage units, are still developing and may not be entirely consistent between entities. This may increase risks to comparability and reliability.
3.57However, the risks to comparability and reliability are balanced by the objective of relevance. The IASB decided not to prescribe detailed methodologies for specific product groups but instead chose to adopt a principle-based approach, consistent with other IFRS Standards, requiring entities to use judgement to determine an appropriate treatment for each product group. As noted by the IASB's Transition
3.57However, the risks to comparability and reliability are balanced by the objective of relevance. The IASB decided not to prescribe detailed methodologies for specific product groups but instead chose to adopt a principle-based approach, consistent with other IFRS Standards, requiring entities to use judgement to determine an appropriate treatment for each product group. As noted by the IASB's Transition Resource Group for IFRS 17 (TRG) in May 2018,42 the determination of coverage units is not an accounting policy choice but involves judgements and estimates, applied in a systematic and rational way, to best achieve the principle of reflecting the services provided in each period.
3.58In the case of annuities under IFRS 17, the impact of an entity's CSM allocation approach may be significant due to the very long term nature of the contracts and the materiality of the amounts involved. However, the level of judgement required is not inherently greater than, or inconsistent with, that required under other IFRS Standards. For example, determining an approach to revenue recognition can require complex judgements in other industries involving long term or complex contracts. The required disclosures (see paragraphs 3.37 - 3.38 above) also mitigate concerns about the degree of judgement required.
3.59The tentative conclusion by the IC in relation to coverage units for insurance coverage potentially removes an element of possible diversity in practice. Over time, it is also possible that greater consensus to determining coverage units and the weighting between types of service, and hence to CSM allocation for typical UK annuity products, will develop. This should reduce the principal concerns over diversity in application and therefore over comparability and reliability of financial information.
3.60Further, once entities have made their initial determination of coverage units, subsequent accounting will not require significant judgement. The application of an entity's approach to determining coverage units will be in essence a mechanistic process and will need to be applied consistently. This will help ensure comparability between periods.
3.61Although additional subjectivity and complexity may be introduced by including an investment-return service in addition to insurance coverage in determining coverage units for insurance contracts without direct participation features, this is balanced by the objective of relevance (see paragraphs 3.49-3.51 above). Further, any resulting challenges will be mitigated by the disclosure required by IFRS 17: 117(c)(v) of the approach used to determine the relative weighting of insurance coverage and investment-return service.
3.62Some stakeholders are concerned that, following the IC's decision, the required approach to determining the quantity of benefits of insurance coverage for survival in the annuity pay-out period will not appropriately reflect the protection service provided. Such stakeholders consider that an approach based solely on the amount of the annuity payment the policyholder is able to validly claim in the period fails adequately to reflect the 'stand-ready' service, that is, the value the policyholder obtains from continued access to insurance coverage until death. Further, CSM allocation will not reflect pricing which in their view is evidence of underlying economics. These stakeholders consider the IC's decision will result in a CSM recognition profile that is too slow, creating risks to both relevance and reliability.
3.63The assessment of the service provided to policyholders in the pay-out phase is a matter of judgement and different views as to an appropriate basis for CSM allocation have been expressed. The IC Tentative Agenda Decision states that a method that would "(i) assign a quantity of benefits to periods for which the entity has no obligation to investigate and pay valid claims for the insured event (for example, to the deferral period of a deferred annuity contract); and (ii) misrepresent the quantity of benefits provided in a period by considering amounts the policyholder is able to claim and benefit from only in future periods" would not meet the principle in IFRS 17: B119.
3.64The staff paper for the IC meeting emphasises that annuity payments for future periods are contingent on policyholder survival in those periods, and that survival in the current period does not provide the policyholder with rights to those future payments. Based on the IC Tentative Agenda Decision, therefore, the value of such future payments is not valid as a primary driver for CSM allocation in the current period. In the IC's view, the 'stand-ready' service is reflected in the risk adjustment (see paragraph 3.40 above).
3.65The staff paper for the IC meeting also states that alignment with pricing is not a valid argument to support an approach to CSM allocation. While agreeing that a younger policyholder would pay more for a life-contingent annuity than an older policyholder, the staff paper notes that this is partly due to the greater uncertainty about how long the policyholder will live and that this is reflected in full in the risk adjustment.
3.66IFRS 17's requirements in this area are not based on a fair value measurement model. The recognition of CSM represents the allocation of a historical amount, namely the expected profit measured at inception. At subsequent dates, therefore, CSM is not intended to represent the profit margin that would be obtained from a market transaction. The price in a market transaction will also reflect other factors not reflected in an allocation of the historic expected profit. One particular such factor is the cost of capital (as determined by solvency requirements) associated with the insurance contracts that are the subject of the transaction.
3.67For the reasons set out in paragraphs 3.59 to 3.66, an approach based on the amount the policyholder is able to claim in the current period, found by the IC to meet the principle in IFRS 17, is one approach that would satisfy the technical accounting criteria.
3.68Some stakeholders also have concerns that IFRS 17's requirements will make it difficult to reflect in the accounts the continuous service that they believe an annuity provides to a policyholder. In particular, the need to recognise different types of service based on different coverage units may make revenue more volatile (for example, on switching between investment-return service and insurance coverage). In addition, some consider that the restriction of investment-return service to only certain periods is artificial. They also note that in the case of some (mainly non-UK) contracts there may be no CSM recognition at all in the deferred period as the relevant criteria for an investment-return service are not met. These stakeholders consider these factors pose challenges to relevance, understandability and, potentially, reliability.
3.69However, the standard's requirements are intended to result in the recognition of performance that reflects the nature of the service being provided. For example, the service provided in a guaranteed period has different economic characteristics from that provided in a life-contingent period, and the related cash payments are therefore different in nature. Further, in pay-out periods, when only insurance coverage is recognised, the inability to recognise investment-return service reflects the fact that the policyholder benefits only on the occurrence of the insured event (survival) and that the policyholder receives the agreed annuity regardless of investment performance. In addition, contracts with no CSM recognition in the deferral period will recognise profit from the risk adjustment to the extent the entity is released from risk. This would reflect the staff paper position that the insurer has taken on risk but is otherwise not transferring services to the policyholder. This also maintains consistency with the treatment of other types of insurance contract. The standard's requirements should therefore support relevance, reliability and, ultimately, understandability.
3.70Whilst the IC's tentative decision resolves one potential source of diversity, there remains the need to use judgement when determining an appropriate approach to allocating CSM. As noted by the IASB's TRG in May 2018, different methods can be used to determine the quantity of benefits as long as they achieve the objective of reflecting the insurance service provided in each period. The standard's objective and principles are clear on this question, and the need for judgement and estimates when applying these principles to annuities does not necessarily indicate that the technical accounting criteria as a whole are not met.
B: Discount rates
Introduction
3.71IFRS 17 requires groups of insurance contracts to be initially measured as the total of the fulfilment cash flows and the contractual service margin (CSM). The fulfilment cash flows represent an explicit, unbiased and probability-weighted estimate of the present value of the future cash flows that will arise as the entity fulfils the insurance contracts, including a risk adjustment for non-financial risk.
3.72The measurement of the fulfilment cash flows involves significant judgements, including the determination of the discount rates used to calculate the present value of future expected cash flows. This judgement is a fundamental element of the standard's measurement requirements and is likely to be significant in the measurement of a large proportion of insurance contracts.
3.73IFRS 17 does not mandate any particular discount rate or, when the appropriate discount rates are not directly observable in the market, any particular estimation technique. Some stakeholders have questioned therefore whether this will impair reliability and/or comparability. In particular, the determination of an illiquidity premium when a bottom-up approach43 is applied is considered to require significant judgement, and some stakeholders have expressed the view that no illiquidity premium should be applied. In addition, some stakeholders consider the fact that the standard provides a choice of approaches (top-down or bottom-up) may present a risk to comparability between insurers.
IFRS 17 requirements
3.74IFRS 17 requires the discount rates applied to estimates of future cash flows to reflect the time value of money, the characteristics of the cash flows and the liquidity characteristics of the insurance contracts. [IFRS 17:36]
3.75The standard also requires the discount rates applied to be consistent with observable current market prices (if any) and to exclude the effect of factors that influence such observable market prices but do not affect the future cash flows of the insurance contracts. [IFRS 17:36]
3.76IFRS 17's application guidance contains further specific requirements regarding the determination of discount rates. When appropriate discount rates are not directly observable in the market, entities shall estimate them. IFRS 17 does not require a particular estimation technique but states that entities shall:
- maximise the use of observable inputs;
- reflect all reasonable and supportable information on non-market variables available without undue cost or effort (which shall not contradict available and relevant market data); and
- reflect current market conditions from the perspective of a market participant. [IFRS 17: B78]
3.77For cash flows of contracts that do not vary based on returns on underlying items, the discount rate reflects the yield curve in the appropriate currency for instruments that expose the holder to no or negligible credit risk, adjusted to reflect the liquidity characteristics of the group of insurance contracts. [IFRS 17: B79]
3.78IFRS 17: B80 states that an entity "may determine discount rates by adjusting a liquid risk-free yield curve to reflect the differences between the liquidity characteristics of the financial instruments that underlie the rates observed in the market and the liquidity characteristics of the insurance contracts (a bottom-up approach)."
3.79IFRS 17: B81 permits an alternative approach to determining the discount rate: "Alternatively, an entity may determine the appropriate discount rates for insurance contracts based on a yield curve that reflects the current market rates of return implicit in a fair value measurement of a reference portfolio of assets (a top-down approach). An entity shall adjust that yield curve to eliminate any factors that are not relevant to the insurance contracts, but is not required to adjust the yield curve for differences in liquidity characteristics of the insurance contracts and the reference portfolio.”
3.80IFRS 17: B74(b) requires cash flows that vary based on the returns on any financial underlying items to be:
- discounted using rates that reflect that variability; or
- adjusted for the effect of that variability and discounted at a rate that reflects the adjustment made.
3.81IFRS 17: B75 clarifies that the variability is a relevant factor whether it arises from contractual terms or because the entity exercises discretion, and regardless of whether the entity holds the underlying items.
3.82When cash flows are subject to a guarantee of a minimum return, IFRS 17: B76 states that this must be reflected in the discount rate by way of an adjustment to the rate that reflects the variability of the returns on the underlying items.
Disclosures
3.83Disclosures required by IFRS 17 on the discount rates used by entities include the following:
- Separate disclosure of amounts in respect of insurance finance income or expenses in the reconciliations from opening to closing balances of insurance contract liabilities (and assets) under IFRS 17: 100-101. [IFRS 17: 105(c)]
- The amount and an explanation of total insurance finance income or expenses, including its relationship with the investment return on assets. [IFRS 17: 110]
- Significant judgements and changes in judgements, including specifying the inputs, assumptions and estimation techniques used. This includes the process for estimating inputs and the approach used to determine discount rates. [IFRS 17: 117]
- The yield curve (or range of yield curves) used to discount cash flows. [IFRS 17: 120]
- A sensitivity analysis for each type of market risk showing how profit or loss and equity would have been affected by changes in risk exposures, including the relationship between these sensitivities and those arising from financial assets held by the entity. [IFRS 17: 128]
Determination of discount rates – accounting impact
Initial recognition
3.84On initial recognition of a group of insurance contracts, the rate used to discount future cash flows affects the measurement of the fulfilment cash flows. For profitable contracts the impact of applying a higher or lower rate is reflected in (and offset by) the CSM so there is no immediate effect on profit or equity, i.e. applying a higher or lower rate does not lead to an upfront profit or loss.
3.85For a group of contracts that is only marginally profitable the precise discount rate applied can affect the likelihood that the group is initially assessed as onerous. For a group of contracts that is onerous on initial recognition, the discount rate applied affects the amount of the loss that is initially recognised.
Subsequent measurement
3.86The unwinding of the discount applied to the fulfilment cash flows is recognised as insurance finance expense, over the period the cash flows are expected to occur. A higher discount rate results in a higher insurance finance expense over that period. For profitable contracts the impact in insurance finance expense of applying a higher or lower rate is offset over the coverage period by the release of the corresponding amount recognised in CSM (see paragraph 3.84 above). There is likely to be a net impact on profit or loss for individual periods as the pattern of CSM release is unlikely to match precisely the pattern of the discount unwind.
3.87Any remeasurement of an illiquidity premium in subsequent periods may result in experience adjustments across the duration of the insurance liabilities. These would be recognised in profit or loss as insurance finance income or expense in the period in which they occurred.
3.88The relationship of total insurance finance income or expenses to total investment income is shown in profit or loss.
Assessment against the endorsement criteria
Recognising the time value of money on a current basis
3.89The timing of cash flows has a significant impact on most insurers' business model. Recognising the time value of money is central to insurance business and as a concept is well-understood by users of insurers' accounts. Reflecting the timing of future cash flows in their measurement is also consistent with the accounting for other items under IFRS Standards such as pensions, provisions and financial assets. Discounting future cash flows therefore provides relevant and understandable information.
3.90The requirement to use updated (current) discount rates promotes a faithful representation of an insurer's economic position and helps ensure that changes in risks are reflected on a timely basis, thereby enhancing the reliability and relevance of the accounting information.
Characteristics of the insurance contract cash flows
3.91IFRS 17 requires the discount rates applied to be based on the characteristics of the cash flows being discounted [IFRS 17: 36]. This means that discount rates – and insurance finance expenses – reflect the nature of the insurance contract liabilities and thereby provide relevant information.
3.92Unless assets held are matched perfectly with the liabilities they back, they are likely to be affected differently by changes in market interest rates. Applying discount rates that reflect the characteristics of the contract cash flows rather than asset-based rates promotes transparency and results in a more faithful representation of the insurer's economic position, enhancing reliability and relevance.
3.93IFRS 17 requires that discount rates reflect the liquidity characteristics of the insurance contracts. Many entities use highly liquid, high quality bonds as a proxy for risk-free rates. However, the holder can often sell such bonds in the market at short notice without incurring significant costs or affecting the market price. By contrast, for many insurance contracts, the insurer cannot be compelled to make payments earlier than when the insured events occur, or before the dates specified in the contract.44 Including liquidity characteristics in the determination of the appropriate discount rate therefore recognises economic characteristics of the liability that are not present in a risk-free but highly liquid asset rate. Considering the effects of liquidity is consistent with the concepts in the IASB Conceptual Framework for Financial Reporting and the requirements in other IFRS Standards such as IAS 36 Impairment of Assets. This leads to a more faithful representation of liabilities and insurance finance expense, enhancing reliability, and to more relevant information.
3.94The 'bottom-up' approach (see paragraph 3.78 above) is based on highly liquid, high-quality bonds, adjusted to include a premium for illiquidity. Given the potential difficulty of identifying an illiquidity premium in isolation, IFRS 17 permits a 'top-down' approach based on the expected returns of a reference portfolio of assets, adjusted to eliminate factors not relevant to the liability, for example market and credit risk (see also paragraph 3.79 above). Judgement is required to determine the credit risk adjustment and the reference portfolio. However, no adjustment for any remaining liquidity differences are required. If, as is expected to generally be the case, the liquidity characteristics of the reference portfolio are closer to those of the insurance liabilities than highly liquid, high-quality bonds, this may help ensure reliable information.45
3.95The use of either a top-down or a bottom-up approach to determining discount rates may be appropriate depending on the characteristics of the liabilities, supporting relevance and reliability.
Discount rates for cash flows that vary based on the returns on underlying items
3.96As noted above, IFRS 17 requires discount rates to reflect the characteristics of the cash flows being discounted. When cash flows vary based on the returns on underlying items, consistency with this principle requires the use of discount rates that reflect that variability (applying B74-76).
3.97The measurement of insurance contract liabilities on this basis thereby provides relevant information. It also results in a more faithful representation of the insurer's economic position, promoting reliability.
Other constraints on the determination of the discount rate
3.98The requirements that discount rates applied are consistent with observable current market prices, reflecting current market conditions from the perspective of a market participant, and maximise the use of observable inputs means that the rates determined are less subjective, as they do not reflect purely an entity view. This supports the provision of information that is reliable and comparable.
3.99The requirements to exclude non-relevant factors and to reflect all reasonable and supportable information on non-market variables available without undue cost or effort (which shall not contradict available and relevant market data) enhance the relevance of the resulting information.
Disclosures
3.100As noted in paragraph 3.83 above, IFRS 17 requires extensive and detailed disclosures in respect of discount rates. These disclosures include explanations of recognised amounts, explanations of significant judgements and the nature and extent of risks arising from the use of discount rates. In addition to these disclosures, IFRS 17: 132 requires disclosures on the liquidity risk arising from insurance contracts, including a description of how the entity manages the liquidity risk and separate maturity analyses for insurance contracts issued and reinsurance contracts held.
3.101In aggregate the disclosures therefore support the relevance and understandability of the accounting impact of the discount rates applied.
Potential challenges to the endorsement criteria and mitigations
3.102The fact that IFRS 17 does not mandate any particular discount rate or, when the appropriate discount rates are not directly observable in the market, any particular estimation technique may be considered by some to present a risk to reliability and/or comparability. In particular, the determination of the illiquidity premium when a bottom-up approach is applied is generally recognised to require considerable judgement. In addition, the fact that the standard provides a choice of approaches (top-down or bottom-up) may be a risk to comparability between insurers.
3.103IFRS 17 acknowledges the inherent limitations in estimating adjustments to observable rates [IFRS 17: B74]. Accounting requirements that involve significant judgement can present a challenge to reliability and often represent a balance between the demands of relevance and reliability. In the case of discount rates in IFRS 17, there are several factors which serve to mitigate concerns regarding reliability:
- As noted above (paragraph 3.98), the requirement for consistency with observable current market prices and for maximum use of observable inputs should help make the determination of discount rates less subjective.
- In principle, the application of judgement in this area should not present major difficulties for insurers, as such judgements and estimates are integral to insurance business and insurers have extensive relevant experience.
- The required disclosures (see paragraph 3.83 above) will provide evidence of the approach taken and facilitate users' assessments of management's judgements.
3.104IFRS 17's overall objective and principles in this area are clear and the standard's requirements and application guidance mitigate the challenge to reliability. The standard's requirements result in a degree of judgement that is consistent with that required under other IFRS Standards.
3.105The approach taken by IFRS 17 results in information that is likely to be relevant and reliable for all entities, rather than a more prescriptive approach which results in information that is appropriate in only some circumstances. Absolute precision is not possible but is also not necessary, and appropriate discount rates can be determined without resulting in excessive measurement uncertainty.
3.106Guidance from international actuarial associations includes information on techniques to determine illiquidity premia.46 Such techniques might include the use of replicating portfolios or comparisons of yields on illiquid and liquid assets with the same or similar degree of credit risk. While judgement may be needed to determine illiquidity premia, it seems likely that generally accepted practice will develop in time.
3.107As noted in paragraphs 3.84 - 3.85 above, unless groups of contracts are onerous or only marginally profitable, the discount rate applied in the measurement of fulfilment cash flows does not have an immediate impact on reported profit or equity. Finance income or expense reported in the income statement, and the related disclosures (see paragraph 3.83(b) above), will provide information on the relationship between insurance finance income or expense and investment income on assets.
3.108Regarding comparability, the requirements for insurers to use discount rates that are consistent with observable market prices and reflect current market conditions, and to maximise observable inputs, serve to reduce concerns over comparability with other entities. In addition, feedback from preparers indicates that similar approaches (i.e. top-down or bottom-up) are likely to be used for similar liability portfolios (for example, a top-down approach for annuities).
3.109The required disclosures also mitigate risks to comparability, in particular those of significant judgements, the inputs, assumptions and estimation techniques used, and the process for estimating inputs and the approach used to determine discount rates. Disclosure of the yield curve used should facilitate comparisons with other insurers. In aggregate the disclosures should highlight differences between entities and facilitate analysis of performance.
C: Grouping insurance contracts: profitability buckets and annual cohorts
Introduction
3.110Risk-pooling is central to the insurance business model.47 Measuring profitability on an individual contract level may not reflect this so some level of aggregation in the accounting for insurance contracts is generally considered appropriate. IFRS 17's requirements aim to balance the loss of information caused by aggregating contracts with the operational burden of collecting information, and to ensure that useful information about profitability is not lost.
3.111The IASB's main objectives in requiring annual cohorts48 include ensuring that:
- changes in profitability are captured;
- losses from onerous contracts are identified and recognised promptly; and
- profits are recognised over the group's coverage period and not longer.
3.112Some stakeholders have expressed concerns that the annual cohort requirement will not result in useful information for contracts that share risks across policyholder cohorts. When the IASB considered proposing amendments to the standard, it considered such concerns and challenges but decided to retain the annual cohort requirement. It therefore did not ask a question on annual cohorts when it issued the Exposure Draft for the 2020 Amendments. Nevertheless, some stakeholders (mostly from the European Union) continued to request changes and exemptions from the annual cohort requirement.49
IFRS 17 requirements
Initial recognition
3.113IFRS 17 requires an entity to recognise and measure groups of insurance contracts. Groups are determined by:
- Identifying portfolios of contracts – a portfolio comprises contracts subject to similar risks and managed together. [IFRS 17:14]
- Dividing portfolios into a minimum of three groups, sometimes referred to as 'profitability buckets':
- a group of contracts that are onerous at initial recognition, if any;
- a group of contracts that at initial recognition have no significant possibility of becoming onerous, if any; and
- a group of the remaining contracts, if any. [IFRS 17: 16]
- Dividing the profitability buckets into groups of contracts issued not more than one year apart (annual cohorts). [IFRS 17:22]
3.114For contracts to which the entity applies the premium allocation approach, an entity assumes that no contracts are onerous at initial recognition, unless facts and circumstances indicate otherwise. [IFRS 17: 18]
Subsequent measurement
3.115Entities must apply IFRS 17's recognition and measurement requirements to the groups of contracts determined as set out above. Entities must not reassess the composition of groups subsequently. [IFRS 17:24]
Disclosures
3.116IFRS 17 does not contain specific disclosure requirements relating to the determination of portfolios, profitability buckets or groups of contracts. However, the standard requires the disclosure of qualitative and quantitative information about the amounts recognised in the accounts and the significant judgements made to enable the effect of insurance contracts on the entity's financial position and performance to be assessed. [IFRS 17: 93] The significant judgements made include the methods used to measure insurance contracts and the processes for estimating the inputs to those methods. It is expected that these disclosures would include the basis for determining portfolios and groups of contracts. [IFRS 17: 117]
Annual cohorts – accounting impact
3.117IFRS 17's level of aggregation requirements are likely to mean an increase in the number of units of account for insurers compared with current practice. Fulfilment cash flows are permitted to be estimated at a higher level of aggregation than a group of contracts as long as they can then be allocated appropriately to groups of contracts to meet the standard's measurement requirements for groups. [IFRS 17:24]
3.118The annual cohorts requirement is expected to lead to the earlier recognition of losses when contracts become onerous subsequent to initial measurement, compared to the outcome if there were no annual cohort requirement.
3.119IFRS 17's objective is to identify contracts that are onerous as individual contracts. However, if an entity can determine that a set of contracts will all be in the same group, then it can measure that set to determine whether in aggregate the contracts are onerous or not. The same principle applies to the identification of contracts that have no significant possibility of becoming onerous subsequently. [IFRS 17: BC129]
Assessment against the endorsement criteria
3.120The insurance business is one of risk pooling and risk sharing so some level of aggregation is appropriate. For example, when an entity issues a number of identical insurance contracts it has an expectation of a particular level of aggregate claims. The probability of claims might change for some contracts within the group with the result that they would be onerous if accounted for on an individual contract basis, even though the aggregate result of the group of contracts remains as expected. Defining IFRS 17's unit of account as a group of contracts therefore provides relevant information.
3.121The requirement to divide portfolios of insurance contracts into 'profitability buckets' provides useful information about loss-making groups of contracts, and hence an entity's pricing decisions, thereby supporting the relevance of the financial statements. This requirement also means that groups of loss-making contracts are not offset against groups of profitable contracts.
3.122For groups of contracts that are not onerous, dividing contracts between groups of contracts that have no significant possibility of becoming onerous and other groups reduces the risk of losses not being recognised on a timely basis, should future changes in conditions make previously profitable contracts loss-making. Such losses might otherwise be offset against profits on other contracts. IFRS 17's requirement therefore supports the relevance and reliability of the financial information.
3.123The prohibition on grouping contracts issued more than one year apart avoids the possibility of perpetually open portfolios and the associated loss of useful information, thereby enhancing relevance, reliability and inter-period comparability:
- Annual cohorts provide information on the development of profitability over time. Without annual cohorts different levels of profitability in different periods would be intermingled and profits would not always be recognised in the period they were earned.
- The requirement for annual cohorts also means that the CSM for a group of contracts cannot persist beyond the duration of contracts in the group: that is, it avoids the continued recognition of CSM for a group for which the contracts are no longer in force.
- Annual cohorts mean that losses from onerous contracts are likely to be identified and recognised promptly, when facts and circumstances change.
3.124IFRS 17's requirements ensure a degree of standardisation in the way entities aggregate insurance contracts, promoting comparability across entities, while permitting entities to identify portfolios in a way which reflects individual business models and circumstances, thereby ensuring relevance.
3.125Disclosures of significant judgements are expected to address methods of determining groups of contracts, and any changes in such methods, enhancing understandability and enabling comparability.
3.126The benefits of including a time-based cohort requirement are set out in the preceding paragraphs. Specifying annual cohorts as the unit of account, while strictly arbitrary, aligns with the traditional underwriting year view of planning and reporting performance and represents a practical convention that is easily understandable.
Potential challenges to the endorsement criteria and mitigations
Profitability buckets
3.127Some stakeholders consider that IFRS 17's requirement to divide contracts between those that 'have no significant possibility of becoming onerous' and 'other' requires a significant degree of judgement and at the fringes might be arbitrary. Further, the requirement does not always reflect the way an insurer manages its business: some entities monitor profitability at the level of portfolios. While there is general support for the objective of avoiding the offset of profitable contracts against onerous ones, these stakeholders perceive a risk that the resulting financial information is less relevant and reliable and hence less useful to users of the accounts.
3.128However, these risks need to be balanced against the benefits of profitability buckets as set out above. Absent IFRS 17's requirements, contracts could be grouped at a higher level of aggregation, for example at the level of the portfolio, with the risk that onerous contracts could be offset against profitable contracts and information about onerous contracts could be lost. Feedback from users indicates that they particularly welcome the fact that IFRS 17 will promote the identification of onerous contracts at initial recognition and subsequently.
3.129Less profitable groups of contracts have less resilience to adverse changes and hence carry a greater risk of becoming onerous. "A difference in the likelihood of a contract being or becoming onerous is an important economic difference between groups of insurance contracts. Grouping contracts that have different likelihoods of becoming onerous reduces the information provided to users of financial statements." [IFRS 17: BC134] By prohibiting the grouping of insurance contracts that have substantially different likelihoods of becoming onerous, IFRS 17 supports the relevance of information provided to users of the accounts. It is therefore appropriate to account for such groups separately.
Risk sharing across annual cohorts
3.130Some stakeholders are concerned that annual cohorts do not provide useful information when insurance contracts share risks across generations of policyholders (i.e. across different annual cohorts). For example, benefits to certain policyholders may be reduced to meet claims of other policyholders, and profits on contracts incepted in one year may support returns to policyholders of contracts incepted in other years. These stakeholders consider that annual cohorts fail to reflect the sharing of risks across cohorts, reducing the relevance of the resulting information.
3.131Risk sharing across different annual cohorts, in particular when management exercises discretion as to the timing and allocation of policyholder profit shares, imposes the need to allocate adjustments to fulfilment cash flows, and hence profits, between cohorts. Some stakeholders are concerned that such allocations will be arbitrary, because profits are not determinable on an annual cohort basis, and in their view will therefore adversely affect relevance and impair reliability.
3.132However, the effect of profit-sharing between generations of policyholders is captured by the requirements of IFRS 17: B67 – B71: the measurement of the fulfilment cash flows takes into account the way that the cash flows of one group affect, or are affected by, cash flows of other groups. Profit-sharing between policyholder cohorts does not mean that the entity's share of profits (captured in the CSM) remains the same over time: this could change from one year to the next and the accounting should reflect this. Scenarios in which the entity bears no share of risk at all are rare. The entity will therefore bear its share, and that share will be different from period to period depending on pricing decisions, on how insurance risks and claim levels evolve and on market conditions.
3.133The annual cohorts requirement therefore provides relevant information about the entity's profitability, irrespective of profit-sharing between cohorts of policyholders. By contrast, removing the annual cohort requirement would result in variable levels of profitability being averaged across cohorts, and a loss of information about changes in profitability. This is particularly important when the effect of guarantees is partly borne by the entity and during periods of challenging market conditions. Profits reported might mask the fact that, for example, newer contracts were subsidising older contracts or, conversely, that aggressive pricing of new business was being subsidised by more profitable established business. Consequently, annual cohorts are likely to support the relevance of financial information, better enabling users of accounts to assess future prospects as well as the stewardship of management. In particular, annual cohorts "ensure that trends in the profitability of a portfolio of contracts [are] reflected in the financial statements on a timely basis". [IFRS 17: BC 136]
3.134Further, even in cases where management has discretion over the allocation of policyholder profits, the overall split between the entity and the body of policyholders as a whole is generally specified (as, for example, in a typical UK with-profits fund). This means that the entity's share is not arbitrary but objectively identifiable, and hence reliable. In any event, this judgement is required to determine the CSM of new business, irrespective of the annual cohort requirement.
3.135The objective of IFRS 17 is to prescribe a level of aggregation that balances the risk of an excessive level of granularity and numbers of groups (disregarding the
certain policyholders may be reduced to meet claims of other policyholders, and profits on contracts incepted in one year may support returns to policyholders of contracts incepted in other years. These stakeholders consider that annual cohorts fail to reflect the sharing of risks across cohorts, reducing the relevance of the resulting information.
3.131 Risk sharing across different annual cohorts, in particular when management exercises discretion as to the timing and allocation of policyholder profit shares, imposes the need to allocate adjustments to fulfilment cash flows, and hence profits, between cohorts. Some stakeholders are concerned that such allocations will be arbitrary, because profits are not determinable on an annual cohort basis, and in their view will therefore adversely affect relevance and impair reliability.
3.132 However, the effect of profit-sharing between generations of policyholders is captured by the requirements of IFRS 17: B67 – B71: the measurement of the fulfilment cash flows takes into account the way that the cash flows of one group affect, or are affected by, cash flows of other groups. Profit-sharing between policyholder cohorts does not mean that the entity’s share of profits (captured in the CSM) remains the same over time: this could change from one year to the next and the accounting should reflect this. Scenarios in which the entity bears no share of risk at all are rare. The entity will therefore bear its share, and that share will be different from period to period depending on pricing decisions, on how insurance risks and claim levels evolve and on market conditions.
3.133 The annual cohorts requirement therefore provides relevant information about the entity’s profitability, irrespective of profit-sharing between cohorts of policyholders. By contrast, removing the annual cohort requirement would result in variable levels of profitability being averaged across cohorts, and a loss of information about changes in profitability. This is particularly important when the effect of guarantees is partly borne by the entity and during periods of challenging market conditions. Profits reported might mask the fact that, for example, newer contracts were subsidising older contracts or, conversely, that aggressive pricing of new business was being subsidised by more profitable established business. Consequently, annual cohorts are likely to support the relevance of financial information, better enabling users of accounts to assess future prospects as well as the stewardship of management. In particular, annual cohorts "ensure that trends in the profitability of a portfolio of contracts [are] reflected in the financial statements on a timely basis". [IFRS 17: BC 136]
3.134 Further, even in cases where management has discretion over the allocation of policyholder profits, the overall split between the entity and the body of policyholders as a whole is generally specified (as, for example, in a typical UK with-profits fund). This means that the entity’s share is not arbitrary but objectively identifiable, and hence reliable. In any event, this judgement is required to determine the CSM of new business, irrespective of the annual cohort requirement.
3.135 The objective of IFRS 17 is to prescribe a level of aggregation that balances the risk of an excessive level of granularity and numbers of groups (disregarding the risk pooling inherent in insurance business), with the risk of the loss of information relating to profitability and the identification of onerous contracts. The annual cohorts requirement represents a practical approach based on a straightforward and understandable convention. Overall, the standard strikes a balance that is likely to provide useful information in the great majority of cases.
D: With-profits: inherited estates
Background
3.136 The Financial Conduct Authority (FCA) describes a with-profits policy as follows:
"A with profits policy is a long term insurance contract. It provides benefits to customers through eligibility to participate in discretionary distributions based on profits arising from the life insurer's business or from a particular part of the life insurer's business. Distributions are typically made in the form of bonuses that are added to the value of the policy annually.” 50
3.137 Inherited estates are a feature of some UK with-profits funds. The inherited estate ('the estate') represents assets in the fund that have built up over time and have not been paid out to policyholders. These assets are surplus to those required to meet current contractual obligations and can be used at the discretion of management to enhance benefits of current and/or future policyholders. The exact sources of the estate are typically unknown, but may be due to seed capital, retention of capital in the business, historic decisions not to distribute all profits as they arose to shareholders and/or policyholders, and the investment return on those profits.
3.138 In the UK the allocation of profits arising in the with-profits fund, including the estate, and the application of the estate to support the business, is generally subject to the fund's Principles and Practices of Financial Management and possibly the entity's Articles of Association and other sources of governance. These documents determine how any profits from the fund are attributed to policyholders and shareholders, typically requiring 90% to be attributed to policyholders.
3.139 The same 90%/10% allocation between policyholders and shareholders respectively typically also applies to the estate, to the extent it is available for distribution and not needed to support current and expected future business. Any surplus attributable to shareholders is not accessible by shareholders except to the extent that policyholder bonuses are declared, or an attribution exercise is approved by the court.
3.140 Most UK with-profits funds are now closed to new business. The closure of a fund may lead to greater clarity over the future use of the inherited estate, including because of a court-approved attribution exercise. For example, some closed with-profits funds (in particular those resulting from demutualisations) do not allow any profits to be allocated to shareholders.
3.141 IFRS 17 does not explicitly address the accounting for inherited estates. However, application of the standard implicitly requires judgements to be made as to the division of the inherited estate between shareholders and policyholders (between equity and liabilities), both on transition and on subsequent measurement.
3.142 As set out in more detail below, a number of technical questions arise including how a liability should be recognised under IFRS 17 for the policyholders' share of the estate and how IFRS 17 requires the shareholders' share to be accounted for.
3.143 The precise accounting will depend on facts and circumstances, but there is an emerging consensus that IFRS 17 requires a liability to be recognised for the policyholders' share of the estate. The principal stakeholder concern, therefore, relates to the accounting for the shareholders' share of the estate.
3.144 The principal concern of some stakeholders is that the accounting treatment under IFRS 17 will not always fairly reflect the entity's contractual position because they think profit will be recognised before shareholders are unconditionally entitled to it. Although the details and the extent of the concern differ depending on whether the fund is open or closed, the fundamental issue can arise in both cases.
3.145 Information on the prevalence and significance of with-profits inherited estates is included in Section 4 (paragraphs 4.170 – 4.180).
IFRS 17 requirements
3.146 IFRS 17 requires the estimates of future cash flows of a group of contracts to include all the future cash flows within the boundary of each contract in the group. Paragraph 33 states that the estimates shall:
- incorporate, in an unbiased way, all reasonable and supportable information available without undue cost or effort about the amount, timing and uncertainty of those future cash flows (see paragraphs B37-B41). To do this, an entity shall estimate the expected value (i.e. the probability weighted mean) of the full range of possible outcomes.
- reflect the perspective of the entity [......]
- be current - the estimates shall reflect conditions existing at the measurement date, including assumptions at that date about the future [.....]
- [.....]."
3.147 IFRS 17's Application Guidance contains specific guidance relating to contracts with cash flows that affect or are affected by cash flows to policyholders of other contracts. 51 This is the case where contracts require the policyholder to share with policyholders of other contracts the returns on the same specified pool of underlying items [IFRS 17: B67]. B68 states that:
"The fulfilment cash flows of each group reflect the extent to which the contracts in the group cause the entity to be affected by expected cash flows, whether to policyholders in that group or to policyholders in another group. Hence the fulfilment cash flows for a group:
- include payments arising from the terms of existing contracts to policyholders of contracts in other groups, regardless of whether those payments are expected to be made to current or future policyholders; and
- exclude payments to policyholders in the group that, applying (a), have been included in the fulfilment cash flows of another group.”
3.148 IFRS 17: B70 clarifies that "different practical approaches can be used to determine the fulfilment cash flows of groups of contracts that affect or are affected by cash flows to policyholders of contracts in other groups. In some cases, an entity might be able to identify the change in the underlying items and resulting change in the cash flows only at a higher level of aggregation than the groups. In such cases, the entity shall allocate the effect of the change in the underlying items to each group on a systematic and rational basis."
3.149 IFRS 17: B71 explains that an entity is also permitted to establish a residual liability that is not allocated to specific groups:
"After all insurance contract services have been provided to the contracts in a group, the fulfilment cash flows may still include payments expected to be made to current policyholders in other groups or future policyholders. An entity is not required to continue to allocate such fulfilment cash flows to specific groups but can instead recognise and measure a liability for such fulfilment cash flows arising from all groups."
3.150 For insurance contracts with direct participation features, the CSM is adjusted by the change in the amount of the entity's share of the fair value of the underlying items [IFRS 17: 45(b)]. The entity's obligation to the policyholder is the net of (a) the obligation to pay the policyholder an amount equal to the fair value of the underlying items and (b) a variable fee that the entity deducts from (a). [IFRS 17: B104]
3.151 The CSM is defined in IFRS 17 Appendix A as "A component of the carrying amount of the asset or liability for a group of insurance contracts representing the unearned profit the entity will recognise as it provides insurance contract services under the insurance contracts in the group”.
Disclosures
3.152 IFRS 17 does not contain disclosure requirements relating specifically to with-profits contracts or inherited estates. Such contracts would be included in the disclosures required generally to explain recognised amounts (IFRS 17 paragraphs 97 to 116).
3.153 IFRS 17 paragraph 117 also requires an entity to disclose significant judgements and changes in judgements, including specifying the inputs, assumptions and estimation techniques used to measure insurance contracts.
3.154 In addition, IFRS 17 paragraph 94 contains the general requirement that, if the specific disclosures required by the standard are not enough to meet the overall objective of enabling users of the accounts to assess contracts' effect on the entity's financial position, financial performance and cash flows, an entity shall disclose additional information necessary to meet this objective.
With-profits inherited estates - accounting impact
Transition
3.155 Given the number of years since the inception of most with-profits contracts, it is expected that a fully retrospective transition approach will be impracticable in many cases. It is likely, therefore, that for many groups of contracts entities will apply a fair value approach (FVA) on transition.
3.156 Under the FVA, the CSM is determined as the difference between the fair value of a group of contracts at transition and the fulfilment cash flows at that date. For funds with an inherited estate, an assessment would need to be made of the extent to which a proportion of the inherited estate should be included in the calculation, because of an expectation it will be paid out to policyholders in the future. The amount of the inherited estate considered attributable to policyholders would be included in the measurement of fulfilment cash flows with the difference from fair value being the CSM. Any remaining excess of assets backing the estate would be recognised as equity on transition.
3.157 The analysis between CSM and equity on transition will be a matter of judgement based on the specific facts and circumstances of the inherited estate, which may differ depending on whether the fund is open or closed to new policyholders. There is likely to be greater certainty over the amount and timing of payments out of the estate to policyholders in the case of a closed fund. However, our understanding is that entities will recognise an increase in equity on transition: this is because while under current accounting in the UK the amount of an inherited estate is generally treated in full as a liability, under IFRS 17 at least some of the amount will be treated as attributable to shareholders and recognised as equity.
Subsequent measurement
3.158 Under IFRS 17, UK with-profits business generally will be accounted for under the Variable Fee Approach (VFA), as policyholders participate in a clearly defined pool of underlying items. This reflects the contracts' nature as primarily investment-related contracts with participation features.
3.159 IFRS 17 recognises that some insurance contracts have cash flows that affect the cash flows to policyholders of other contracts, as is generally the case for UK with-profits contracts. The standard requires the fulfilment cash flows of each group to reflect the extent to which contracts in the group cause the entity to be affected by expected cash flows, whether to policyholders in that group or to policyholders in another group, regardless of whether those payments are expected to be made to current or future policyholders [IFRS 17: B68].
3.160 After transition, changes in the fair value of the inherited estate (e.g. due to investment return) will need to be allocated between policyholders and shareholders in accordance with the fund's Principles and Practices of Financial Management. Again, this will be a matter of judgement based on the specific facts and circumstances of the case, and stakeholders have differing views as to the precise mechanics under IFRS 17. However, there seems to be consensus that the policyholders' share (typically 90%) is required to be recognised as a fulfilment cash flow liability under IFRS 17: B70 or B71 (see paragraphs 3.148 and 3.149 above).
3.161 The shareholders' share (typically 10%) of any change in fair value of the inherited estate will then be recognised as either CSM or directly as profit. The analysis under IFRS 17 does not seem clear cut, and stakeholder views may differ depending on whether the fund is closed or open:
- If the inherited estate assets are considered to be 'underlying items' for current with-profits contracts, then the shareholders' share will form part of the variable fee under the VFA and will adjust the CSM. The CSM will then be released to profit as investment services are provided, for example in line with asset shares. This may be the assessment for a closed fund.
- Alternatively, and typically for an open fund, some stakeholders consider that (a) the inherited estate assets are not underlying items as they support both current and future policyholders, and (b) no CSM can be recognised because IFRS 17 does not allow for a CSM other than for groups of current contracts. In this case the shareholders' share will be recognised directly as profit.
Assessment against the endorsement criteria
Recognising the interests of policyholders and shareholders
3.162 IFRS 17 does not explicitly address the inherited estates that have arisen in UK with-profits funds. These are UK-specific features and give rise to some areas of judgement and complexity in applying IFRS 17's requirements.
3.163 However, generally it will be clear from the entity's Principles and Practices of Financial Management or other governance documents that the surplus represented by the estate will be shared by both policyholders and shareholders. This may also be clear from regulation and past business practice, which are required to be taken into account in determining an entity's substantive rights and obligations. [IFRS 17: 2] Typically in the UK, policyholders collectively (both current and future, if the fund is still open) have expectations to share in the estate. This may be through the process of smoothing returns or meeting guarantees in adverse economic conditions, special distributions of excess surplus or as a result of an attribution exercise. Recognising the relative interests of policyholders and shareholders in the estate, as will be required by IFRS 17, should enable a faithful representation of the insurer's economic position. This is not the case under current accounting, under which a liability is recognised for both the policyholder and shareholder shares, although these is no present obligation for the latter, so IFRS 17 will support relevance and reliability.
3.164 Treating the policyholders' share (typically 90%) as part of fulfilment cash flows within insurance contract liabilities will result in relevant and understandable information. It is clear from IFRS 17's requirements that fulfilment cash flows are the entity's best estimate of cash flows and should consider all potential scenarios (see paragraph 3.146 above). The fact that the ultimate attribution of the estate may be subject to uncertainty does not affect this principle. 52 This treatment will also be comparable with that for other insurance contract liabilities, whether from with-profits or other business, enhancing consistency within the entity. This is not the case under current accounting (IFRS 4 Insurance Contracts as applied in the UK), under which the accounting is triggered by the declaration of policyholder bonuses and is thereby subject to management discretion. Consequently, IFRS 17 will support comparability.
3.165 As explained above, the recognition of the shareholders' share (typically 10%) in equity on transition or as profit on subsequent measurement (whether via CSM release or directly to profit or loss) may differ depending on the entity's application of judgement to its particular facts and circumstances. However, recognition of the shareholders' interest in the estate in some form reflects the fact that the amount represents surplus which has arisen from past activities and is in excess of the fulfilment cash flow liability. This treatment provides relevant and understandable information because it is based on the underlying contractual arrangements and the constitution of the company, and so is consistent with shareholders' reasonable expectations.
Disclosures
3.166 As noted in paragraph 3.152 above, IFRS 17 does not require specific disclosures in respect of UK with-profits contracts or inherited estates. However, disclosures required by IFRS 17 include explanations of recognised amounts, explanations of significant judgements and estimates and the nature and extent of risks arising from insurance contracts (see paragraphs 3.153 – 3.154 above). Sufficient disclosures will need to be provided in respect of any with-profits inherited estate to meet IFRS 17's general disclosure objective. 53
3.167 In aggregate these disclosure requirements extend beyond those in IFRS 4 and should support the understandability of the impact of inherited estates on the entity's financial position, financial performance and cash flows.
Potential challenges to the endorsement criteria and mitigations
3.168 While there may be several implementation or interpretation challenges when applying IFRS 17 to UK with-profits business, the principal concern raised by some stakeholders relates to the treatment of the shareholders' interest in the inherited estate.
3.169 These stakeholders note that the estate supports both current and future contracts and that its ownership is not yet determined. In their view IFRS 17 will lead to surplus (profit) being recognised before all potential services in respect of that surplus have been provided. In addition, as transfers to shareholders can be made only on the basis of declared bonuses, or on court approval of a reattribution scheme, profit will be recognised before shareholders are unconditionally entitled to it. Some stakeholders therefore consider that the accounting will not faithfully represent the entity's contractual position, impairing relevance and reliability.
3.170 Discussions with stakeholders, including at the UKEB's Insurance Technical Advisory Group, indicated that recognition of the shareholders' interest as equity (whether directly in equity on transition or through profit or loss) was not considered a clear-cut decision but, on balance and having explored other possibilities, was seen as the most appropriate treatment. It was noted that the inherited estate arose from past service and past events and, although it might be utilised to support current and future policyholders, no current service obligation existed.
3.171 Treatment as equity would be in accordance with the IASB's Conceptual Framework, which by definition classifies claims against the entity's assets that are not liabilities as equity. Recognition in equity does not necessarily mean there is an earned profit from past events (consider for example capital contributions, grant income or credits arising on equity-settled share-based payments), nor that the amount is immediately accessible by shareholders.
3.172 Profit recognition under IFRS 17 will inevitably be different from current practice, under which shareholder profits are recognised only when transfers to shareholders take place based on bonus declarations. The profit recognition regime under IFRS 4 as applied in the UK is therefore very different from the asset/liability framework that underpins IFRS.
3.173 Stakeholders also note that it is not unique for profit to be recognised in accounts without it necessarily being immediately accessible to shareholders. They note that an estate can function as a resource even if not accessible immediately in cash or other transferable form. Even if ring-fenced, an inherited estate can still earn profit for the entity, including by supporting the issue of future policies in which the entity will have an interest. Reflecting the shareholders' interest in the inherited estate in equity therefore reflects the entity's underlying economic position.
3.174 As noted in paragraphs 3.157 and 3.161 above, the analysis between CSM and equity may differ depending on facts and circumstances including whether the fund is open or closed. To the extent there is diversity in practice in reporting similar underlying circumstances, this may impair comparability between funds and between insurance companies. To the extent that different accounting reflects different circumstances this may in fact enhance comparability. In addition, in certain circumstances and depending on the treatment applied, certain stakeholders consider the accounting may result in counterintuitive impacts (for example, if amounts already recognised in equity are transferred to CSM on closure of a fund), representing a potential risk to understandability. However, such circumstances may not be frequent and such risks will be mitigated by disclosures (see also next paragraph). In addition, stakeholder feedback suggests that practical approaches may be developed that avoid accounting outcomes that pose a risk to understandability.
3.175 The required disclosures (see paragraphs 3.166 – 3.167 above) are designed to provide evidence of the approach taken and facilitate users' assessments of management's judgements. The required disclosures also enhance relevance and will mitigate risks to comparability, in particular those of the inputs, assumptions and estimation techniques used. In aggregate the disclosures should highlight differences between entities, in terms of facts and circumstances and management's expectations, and facilitate analysis of performance.
3.176 Users of accounts informed us that they were familiar with assessing the extent to which profit is immediately accessible or 'locked in’. Clear disclosure and potentially separate presentation (e.g. in equity) would continue to be important as users felt it unlikely that the accounting alone could ‘tell the whole story'. 54 Further, specialist insurance investors broadly understand the nature of the estate and already receive additional disclosures in this area (both within and outside the annual accounts) on which to base their own analysis. Such additional information might include analyses of the inherited estate and expectations as to its future use and can continue to be provided. 55
3.177 The fact that IFRS 17 does not contain detailed requirements in this area means that entities must develop an accounting treatment that reflects their particular facts and circumstances and is therefore relevant and understandable. This is not unexpected when implementing a major new international standard. International financial reporting standards are developed as principle-based to allow widespread use and cannot include specific accounting requirements for every type of product or transaction. This facilitates consistent application of measurement and presentation requirements without excessive prescriptive rule-making. IFRS 17 will need to be interpreted and practical approaches and appropriate disclosures developed which reflect the underlying economics and are in line with the standard's principal objectives.
Overall conclusion on whether IFRS 17 meets the technical accounting criteria
3.178 In drawing our conclusion as to whether IFRS 17 meets the technical accounting criteria we have considered:
- requirements of the standard that do not give rise to any significant issues, and on which we have therefore not reported in detail in this ECA (see paragraph 3.4 above);
- priority issues stakeholders have raised with us, set out above; and
- remaining significant issues, set out in Appendix B.
3.179 In assessing the priority and other significant issues we identified some risks to the technical accounting criteria either through our own analysis or through stakeholder feedback. We have also set out mitigating factors that we believe must be weighed against those risks. Such risks often arise from the balance that needs to be struck between competing objectives, for example between the objectives of relevance and comparability, or between reliability and comparability. The identification of risks in an assessment does not necessarily imply that, on balance, for that particular set of IFRS 17's requirements the technical accounting criteria are not met.
3.180 Insurance contracts create a wide variety of often complex bundles of rights and obligations for the issuer. No international accounting standard could explicitly address every scenario that arises under typical UK insurance contracts. However, our conclusion is that IFRS 17 sets out clear principles that can be applied to insurance contracts typical in the UK and that will result in understandable, relevant, reliable and comparable information for users of the accounts. In some cases, including in the case of those significant issues addressed in this ECA, it will be particularly important for management to provide appropriate disclosures as required both by IFRS 17 and more generally by IFRS Standards to achieve the objectives of understandability, relevance, reliability and comparability. We have taken account of such disclosure requirements in our assessment and in coming to our conclusion.
3.181 Overall, therefore, we conclude that IFRS 17 meets the criteria of understandability, relevance, reliability and comparability required of the financial information needed for making economic decisions and assessing the stewardship of management.
4 UK long term public good assessment
Basis for adoption of international accounting standards
4.1 SI 2019/685 regulation 7 (1) (b) permits the adoption of an accounting standard only when use of the standard is likely to be conducive to the long term public good in the United Kingdom.
4.2 SI 2019/685 regulation 7 (2) requires that:
"In deciding whether the use of a standard is likely to be conducive to the long term public good in the United Kingdom, the Secretary of State 56 must have regard, in particular, to the following matters—
- whether the use of the standard is likely to improve the quality of financial reporting;
- the costs and benefits that are likely to result from the use of the standard; and
- whether the use of the standard is likely to have an adverse effect on the economy of the United Kingdom, including on economic growth.”
Structure of the assessment
4.3 Each of the requirements of SI 2019/685 regulation 7 (2) has been addressed in turn in the following sections of this report, and in the order set out in that regulation. Our approach and the evidence underpinning our assessment are explained within each section.
4.4 First, however, to provide context for the assessments against the three long term public good criteria, in paragraphs 4.5 – 4.29 below we have provided an overview of the UK insurance sector.
The UK insurance sector
4.5 This section provides contextual information about the UK insurance sector, our population of interest (insurance companies that apply UK-adopted IFRS) and its economic significance.
4.6 The UK insurance and long-term savings 57 industry is strategically important for the UK economy. It is the largest in Europe and the fourth largest in the world, with estimated annual total gross written premiums of £264 billion 58 and employing approximately 310,000 people, just over one third of whom are employed directly by insurance companies.
4.7 At £2.04 trillion 59 the amount of assets managed by UK insurance undertakings is highly significant. According to a Credit Suisse 2021 Wealth Report, at the end of 2020 UK household wealth amounted to £11 trillion 60, meaning that insurance companies' assets were equivalent to approximately 18% of UK household wealth. This amount was invested in the following asset classes (AUM = assets under management):
UK Insurance Companies – AUM – Q4 2020: Total: £2.04tr
A pie chart showing the breakdown of assets under management (AUM) for UK Insurance Companies in Q4 2020, totaling £2.04 trillion. The categories and their percentages are:
- 30% Bonds
- 16% Equity
- 40% CIU*
- 5% Cash
- 6% Other
- 2% Property
*CIU: Collective Investment Undertaking. These include Undertakings for the Collective Investment in Transferable Securities (UCITS), mutual funds that are issued in Europe and comply with European regulation.
Source: EIOPA. *CIU: Collective Investment Undertaking. These include Undertakings for the Collective Investment in Transferable Securities (UCITS), mutual funds that are issued in Europe and comply with European regulation.
4.8 The insurance sector can be divided between two major classes of business, life and non-life (general) insurance 61.
- Life insurers provide protection products (e.g. term life insurance), retirement products (e.g. annuities) and savings and investment products (e.g. endowment policies).
- General insurers provide health, motor, home, travel, commercial and other protection insurance.
4.9 In 2020 life insurers accounted for 70% of gross written premiums in the UK and 87.7% of assets under management. General insurers made up 30% of gross written premiums and 12.3% of assets under management 62.
Relevant population of insurers
4.10 To provide insurance services in the UK, a company must be authorised by the Prudential Regulation Authority (PRA), a regulatory body that is part of the Bank of England (BoE). This is true also for subsidiaries of foreign insurance companies.
4.11 As of July 2021, the PRA had authorised 362 entities in the UK 63 to issue insurance contracts. The list includes subsidiaries of non-insurance entities, such as banking groups. The list encompasses entities that prepare accounts using UK-adopted IFRS (IFRS before 1 January 2021), as well as entities that prepare accounts using UK GAAP. It also includes entities that are inactive.
4.12 Section 403(1) of the Companies Act 2006 specifies that the group accounts of a parent company whose securities are, on its balance sheet date, admitted to trading on a UK regulated market 64 must be prepared in accordance with UK-adopted IFRS. Where a UK listed company is not required to prepare consolidated accounts, its accounts may be prepared in accordance with either UK GAAP or UK-adopted IFRS 65.
4.13 UK companies listed on unregulated markets such as AIM 66 (a UK market for trading securities that is not a 'regulated market') are not required (but are permitted) to prepare annual accounts in accordance with UK-adopted IFRS under the Companies Act 2006. However, market rules stipulate the use of UK-adopted IFRS when preparing annual accounts.
4.14 UK unlisted companies have the option to prepare their accounts using either UK-adopted IFRS or UK GAAP. 67
4.15 Foreign companies listed on UK regulated markets are permitted to use IFRS Standards as issued by the International Accounting Standards Board (IASB) or other standards, as deemed by UK legislation to be equivalent to UK-adopted IFRS 68.
4.16 Based on the above, the population of insurers that will be directly affected by the UK's IFRS 17 adoption decision therefore comprises:
- UK companies listed on a UK regulated market or AIM, and required to apply UK-adopted IFRS in their consolidated accounts; and
- listed and unlisted UK companies that voluntarily apply UK-adopted IFRS.
4.17 The table below provides information on this population of insurers, with the data taken from the latest available financial information (2020 in most cases).
UK insurance companies applying IFRS
| Entity Name | Class of Business | Listed in the UK? | Turnover (GWP) (£'M) | % of IFRS Reporters Total |
|---|---|---|---|---|
| Prudential plc | Life insurance | Yes | 33,166 69 | 21.2% |
| Aviva plc | Composite insurer | Yes | 29,015 | 18.5% |
| Legal & General Group Plc | Life insurance | Yes | 12,545 | 8.0% |
| Scottish Widows Limited 70 | Life insurance | Yes | 8,205 | 5.2% |
| RSA Insurance Group Limited 71 | Non-Life insurance | See footnote 71 | 7,282 | 4.6% |
| Total: 5 largest insurance companies by GWP | 90,213 | 56.54% |
4.14UK unlisted companies have the option to prepare their accounts using either UK-adopted IFRS or UK GAAP.67
4.15Foreign companies listed on UK regulated markets are permitted to use IFRS Standards as issued by the International Accounting Standards Board (IASB) or other standards, as deemed by UK legislation to be equivalent to UK-adopted IFRS68.
4.16Based on the above, the population of insurers that will be directly affected by the UK's IFRS 17 adoption decision therefore comprises:
- UK companies listed on a UK regulated market or AIM, and required to apply UK-adopted IFRS in their consolidated accounts; and
- listed and unlisted UK companies that voluntarily apply UK-adopted IFRS.
4.17The table below provides information on this population of insurers, with the data taken from the latest available financial information (2020 in most cases).
UK insurance companies applying IFRS
| Entity Name | Class of Business | Listed in the UK? | Turnover (GWP) (£'M) | % of IFRS Reporters Total |
|---|---|---|---|---|
| Prudential plc | Life insurance | Yes | 33,16669 | 21.2% |
| Aviva plc | Composite insurer | Yes | 29,015 | 18.5% |
| Legal & General Group Plc | Life insurance | Yes | 12,545 | 8.0% |
| Scottish Widows Limited70 | Life insurance | Yes | 8,205 | 5.2% |
| RSA Insurance Group Limited71 | Non-Life insurance | See footnote 71 | 7,282 | 4.6% |
| Total: 5 largest insurance companies by GWP | 90,213 | 56.54% |
| Entity Name | Turnover (GWP) (£'M) | % of IFRS Reporters Total |
|---|---|---|
| Remaining UK listed insurance companies (or part of UK listed groups) | 32,272 | 20.22% |
| All UK listed insurance companies | 122,485 | 76.76% |
| Unlisted UK insurance companies applying IFRS | 37,083 | 23.24% |
| All UK insurance companies applying IFRS | 159,568 | 100.0% |
Source: UKEB calculation based on insurance companies' annual reports, as filed at Companies House. The list of authorised insurers was taken from the PRA (see paragraph 4.11 above).
4.18We identified 60 insurance companies that use IFRS in the UK, with total gross written premiums of approximately £159 billion. This represents roughly 60% of gross written premiums in the total UK market. These figures include banking groups that have an insurance subsidiary.
4.19Of these 60 companies, 20 are listed insurance groups (including one listed on AIM). Their total market capitalisation was nearly £134 billion as of end of year 202172.
Lloyd's of London
4.20Lloyd's of London is an insurance and reinsurance market place. In 2020 it accounted for £35.5 billion in gross written premiums. Lloyd's of London produces pro-forma financial statements on an aggregated basis under UK GAAP73 Individual entities operate on the market through syndicates. While the syndicates apply UK GAAP, the groups that participate in those syndicates may apply IFRS in their consolidated accounts in the same way as any other group – and are required to do so if they are listed. We are aware of four such UK listed insurance companies with Lloyd's of London operations that produce group accounts using IFRS.
Other entities
4.21Other entities that issue or might issue insurance contracts as defined in IFRS 17 are not included in the above assessment for the following reasons.
UK branches of foreign entities
4.22Prior to the end of the UK's transition period (31 December 2020), insurers established in any European Economic Area (EEA) member state could use the passporting regime to establish a branch or provide services (without a UK branch) in the UK without being authorised by the PRA74.
4.23After 31 December 2020 such insurers are still able to conduct insurance business in the UK if the insurer successfully applied to the UK's Temporary Permissions Regime (TPR) before 31 December 2020. However, as they are not required to report according to IFRS Standards, foreign branches are not directly affected by the UKEB's decision on adoption of IFRS 17.
4.24All insurers within the TPR must obtain PRA authorisation within three years, or they will be required to wind down their UK activities75.
4.25In 2019 branches of foreign companies made up only 0.15% of total gross written premiums in the UK76. Their relevance is expected to dwindle even further following the expiry of TPR77.
Companies with limited insurance activities (‘non-insurance companies')
4.26IFRS 17 provides scope exclusions78 in respect of certain specific types of contract or obligation that might otherwise meet the definition of an insurance contract. The scope exclusions provided by IFRS 17 can be expected to cover a large proportion of insurance contracts issued by non-insurance companies. Therefore, although a significant impact on an individual entity cannot be ruled out, in general the impact of IFRS 17 on non-insurers in the UK is expected to be minor79.
4.27Should non-insurance companies not meet the scope exclusions allowed in IFRS 17, it is expected that many of these insurance contracts will qualify for the Premium Allocation Approach (PAA), as the contracts are for coverage periods of one year or less. The PAA model provides a simplified measurement model including an option to not apply discounting if the liability for incurred claims is expected to be settled one year or less from the date the claims were incurred. (For further information on the PAA see Section 2.)
4.28The intention of the IASB was that the impact of IFRS 17 outside the insurance sector should be minimal. Given the scope exclusions, together with the simplifications provided by the PAA, it is expected that this will be the case in the UK.
4.29Accordingly, the impact of IFRS 17 on non-insurance companies is not included in this UK long term public good assessment.80
For the avoidance of doubt, insurance companies that are subsidiaries of non-insurance companies (e.g. banks) are included in the assessment.
Will IFRS 17 improve the quality of financial reporting?
4.30Regulation 7(2)(a) of SI 2019/685 requires the UK long term public good assessment to have particular regard to whether the use of the standard is likely to improve the quality of financial reporting. The purpose of this section of the ECA is to address Regulation 7(2)(a).
IFRS 17's objectives
4.31IFRS 17 paragraph 1 sets out the objective of the standard:
"IFRS 17 Insurance Contracts establishes principles for the recognition, measurement, presentation and disclosure of insurance contracts within the scope of the Standard. The objective of IFRS 17 is to ensure that an entity provides relevant information that faithfully represents those contracts. This information gives a basis for users of financial statements to assess the effect that insurance contracts have on the entity's financial position, financial performance and cash flows.”
4.32IFRS 17 replaces IFRS 4 Insurance Contracts. As an interim standard, IFRS 4 did not prescribe the measurement of insurance contracts but grandfathered existing local accounting practices, permitting changes only if they were deemed to be an improvement on those existing practices. For this reason there is currently diversity in practice between jurisdictions and within the consolidated accounts of some insurance groups. By contrast, IFRS 17 is a comprehensive international accounting standard that establishes principles for the recognition, measurement and presentation of insurance contracts for the first time.
4.33The IASB Effects Analysis81 states on page 3 that "IFRS 17 addresses many inadequacies in the existing wide range of insurance accounting practices" and in Section 4.1 provides an overview of improved requirements introduced by the standard. The following paragraphs highlight the principal areas where IFRS 17 is likely to lead to improvements in the accounting for insurance contracts in the UK and is by no means a comprehensive analysis of all possible improvements.
4.34First, however, this section provides a brief overview of the basis for current UK accounting practice for insurance contracts under IFRS 4.
Basis for current UK accounting practice under IFRS 4
4.35Many UK insurers that currently apply UK-adopted IFRS adopted IFRS in 2005. IFRS 4 permits the continuation of previously applied local Generally Accepted Accounting Practice (GAAP) so current accounting for insurance contracts in the UK is heavily based on accounting under old (pre-2005) UK GAAP.
4.36For UK accounting purposes insurance business is divided between general insurance and long-term (or ‘life') insurance. These categories follow definitions contained in law82 and accounting requirements and practices have developed over time to accommodate the differences between the two categories.
4.37Current UK accounting practice for insurance contracts under IFRS 4 is a confluence of several elements:
- Company law – although companies applying IFRS do not have to comply with the presentation requirements and accounting principles and rules of the Companies Act83, companies may have opted to continue to apply certain presentation and other accounting requirements of the Act.
- Prudential regulation – prudential reporting requirements are relevant because the provisions calculated for regulatory purposes84 form the basis for the provisions reported in the accounts. In particular, long-term business provisions are determined using a modified statutory solvency basis, except for with-profits business which is determined using the regulatory realistic capital basis. Companies could choose, but were not required, to update their accounting policies for the effect of Solvency II.
- Accounting standard – insurers that adopted IFRS from 2005 agreed85 to apply the only insurance specific accounting standard issued by the then UK Accounting Standards Board (ASB), FRS 27 Life Assurance. The principal requirement of FRS 27 was for with-profits liabilities to be determined using the 'realistic balance sheet approach' (i.e. another modified regulatory basis).
- Industry guidance – the Statement of Recommended Practice for Insurance Business published by the Association of British Insurers (the ABI SORP)86 provided recommended accounting practice for both general and long-term insurance business. For the measurement of long-term business, the ABI SORP confirmed the modified statutory solvency basis.
4.38Together the above elements provide the basis for current UK accounting under IFRS 4. Comprising a mixture of law, regulation and accounting requirements they lack a coherent conceptual basis and do not provide consistent principles to underpin insurance accounting.
4.39The ASB formally acknowledged that UK accounting for life insurance was in need of improvement in its 2005 report to HM Treasury titled 'Financial Reporting for Life Assurance’87, published after the issuance of FRS 27 Life Assurance. In its report, the ASB noted that through FRS 27 it had addressed some of the more significant issues identified from its work on life assurance. However, it concluded that there were "major issues relating to life assurance accounting that will need to be addressed by the IASB". These issues included:
- measurement of liabilities (including the treatment of undeclared future bonuses on with-profits policies);
- profit recognition (even after FRS 27 the ASB noted that the profit recognition regime was very different from that which underpinned most developments in financial reporting outside insurance); and
- equity versus liability classification.
As explained in more detail in Section 388, IFRS 17 will require or facilitate improvements in these areas.
Improvements introduced by IFRS 17
4.40One of the main improvements brought about by IFRS 17 is the removal of the IFRS 4 exemption from the requirements in IAS 8 Accounting Policies, Changes in Accounting Estimates and Errors on the development and application of accounting policies. Specifically, that exemption means that an insurer applying IFRS 4 to contracts in the scope of that standard is not required to consider whether its accounting policies are consistent with the IASB's Framework89 or other IFRS Standards, nor whether its accounting policies result in information that is relevant and reliable.
4.41According to the IASB:
"IFRS 17 removes this exemption in IFRS 4 so that, when applying IFRS 17, accounting policies for insurance contracts must result in information that is useful for users of financial statements.” [IASB Effects Analysis, p. 34]
On this basis alone, IFRS 17 represents an improvement in financial reporting.
Consistent principles
4.42IFRS 17 specifies particular accounting models to recognise and measure insurance contracts, replacing the current accounting practice that lacks consistent principles. The accounting models result in measurement of the liability for remaining coverage and revenue and profit recognition that are broadly consistent with IFRS 1590, and measurement of the liability for incurred claims that is broadly consistent with IAS 37.91 This change will lead to significant improvements in comparability and understandability of the resulting financial information.
4.43IFRS 4 permits companies to depart from the requirement in IFRS Standards to apply uniform accounting policies for similar transactions. In consolidated accounts, therefore, multinational insurers may currently use a combination of different accounting frameworks (e.g. consolidating information prepared using IFRS, UK GAAP, US GAAP or other local GAAPs). IFRS 17 specifies the use of uniform accounting policies and consistent application of its requirements to all the financial information included in the accounts. This will significantly improve comparability between insurers.
Improved scope
4.44Compared with that of IFRS 4, the scope of IFRS 17 has been improved by the provision of an option to apply IFRS 15 to fixed fee service contracts (see paragraph 2.9 in Section 2).92 This means that companies that issue such service contracts (for example for maintenance or roadside assistance) but that do not otherwise issue insurance contracts will not have to apply IFRS 17, reducing their costs and enhancing the understandability of their accounts.
4.45The scope of IFRS 17 has also been improved by the option to exclude from IFRS 17 contracts that meet the definition of an insurance contract but limit the compensation for insured events to the amount otherwise required to settle the policyholder's obligation created by the contract (for example, loans with death waivers).93 In addition, a company need apply IFRS 17 to credit cards and similar contracts only if it reflects an assessment of the insurance risk associated with an individual customer in setting the price of the contracts. In many cases the application of IFRS 9 Financial Instruments to such contracts will provide more relevant information and will reduce costs for companies. 94
Transparent liability measurement
4.46The measurement of insurance liabilities under current UK accounting lacks transparency, as typically it includes implicit margins for risk and prudence. IFRS 17 requires an explicit risk adjustment for non-financial risk to be calculated, included in the measurement and disclosed. It also requires an unbiased estimate of the present value of future cash flows to be determined, included in the measurement and disclosed. IFRS 17 will therefore provide greater insight into the risks associated with an entity's insurance contracts, and insurance contract liabilities measured and disclosed in accordance with IFRS 17 will represent more relevant information and a more faithful representation of the entity's obligations.
4.47Under current UK accounting, non-life insurance contract liabilities may be measured on a discounted or undiscounted basis, typically influenced by conditions set out in law. IFRS 17 requires all estimated future cash flows to be reported on a discounted basis.95 This will enhance consistency between insurance liabilities and other long term liabilities that are also measured on a discounted basis (including financial liabilities, provisions and pensions), and provide a more faithful representation of an entity's financial position.
4.48In addition, IFRS 17 requires discount rates to be updated, to be consistent with observable current market prices, and to reflect the characteristics of the cash flows and the liquidity of the contracts. Under current accounting, discount rates are sometimes based on the return on the assets backing the insurance liabilities. IFRS 17 will provide a more faithful representation of an entity's economic position and the economic cost of insurance claims for all insurance contracts. In particular, any economic mismatches between the insurance liabilities and the assets backing them will be reported.
Grouping of contracts
4.49Current UK accounting under IFRS 4 contains no consistent requirements regarding the level of aggregation of contracts (the 'unit of account'). By introducing clear requirements on this that apply to all types of insurance business, IFRS 17 will ensure that insurers group contracts in similar ways. Further, IFRS 17's requirements for the identification of ‘profitability buckets' and the annual cohorts restriction mean that onerous contracts will be promptly and transparently identified, at inception and subsequently. IFRS 17 will therefore provide more relevant and reliable information on an entity's profitability and changes in its profitability, and greater consistency with the accounting for other types of contracts.
Consistent profit recognition
4.50Profit recognition under current accounting in the UK for insurance contracts lacks a consistent basis. For example, current profit recognition bases for annuities and with-profits contracts are very different, resulting in very different profit recognition profiles: for annuities a significant proportion of profit is recognised at inception but for with-profits contracts the majority of profit is recognised towards the end of the contract term.97 IFRS 17 requires the application of a consistent approach that is not dependent on product type. The IASB Effects Analysis describes the approach as follows:
"IFRS 17 requires a company to recognise profit according to the way it is earned from:
- the contractual service margin – recognised as profit as the company provides services over the coverage period; and
- the risk adjustment – recognised in profit or loss as the company is released from risk over the coverage period and the settlement period.
IFRS 17 requires a consistent approach for the recognition and measurement of the contractual service margin, and for the determination of explicit risk adjustments." [IASB Effect Analysis p. 33]
4.51The accounting model applied (whether the General Measurement Model, Variable Fee Approach or Premium Allocation Approach see Section 2 above) will depend on the economic characteristics of the relevant group of contracts rather than on regulatory definitions, improving the relevance of the financial information and ensuring the accounting provides a faithful representation of the effect of the contracts.
4.52The current practice of recognising premiums for some long-term contracts on a receivable basis will be changed on implementation of IFRS 17. Further, IFRS 17 specifies that deposit components are excluded from revenue, consistent with the treatment of deposits in financial instruments. Revenue will be recognised as services are provided, improving comparability and consistency of revenue recognition with other types of contracts under IFRS.
4.53The reconciliation of changes in the Contractual Service Margin (CSM) referred to below (paragraph 4.60) will also provide useful insight into profitability:
"The Board expects that such information about the current and future profitability of insurance contracts will significantly improve the transparency of reporting for insurance contracts and provide important additional information for investors and other users of financial statements for their decision-making.” [IASB Effects Analysis p.43]
Improved presentation
4.54Current accounting provides no consistent presentation of revenue from insurance contracts. The metric ‘earned premiums' is usually presented as representing revenue for general insurance but not for life insurance business. Under IFRS 17 insurance revenue will be consistently presented for all insurance contracts, 98 enhancing comparability between insurers and with entities in other sectors.
4.55The standardised structure of the income statement introduced by IFRS 17,99 and in particular the separation of the insurance service result from insurance finance income or expenses, will enhance comparability between insurers and improve the understanding of the drivers of performance. The requirement to explain the relationship between insurance finance income or expenses and the investment return on the entity's assets will provide a clearer insight into the effect of economic changes on an entity's assets and liabilities, and of any economic mismatches.
4.56Current insurance entity income statements include a variety of line items that can lack transparency. For example, the commonly used line item 'change in insurance contract liabilities' may incorporate several elements, including the implicit accretion of the liability, the effect of changes in assumptions, the effect of new business and the impact of premiums presented as revenue but not yet reflected in profit. However, these elements are not always consistently disclosed and may not be the same in each entity.
4.57IFRS 17 will mean that similar transactions are presented similarly by all insurance companies. This has not always been the case under IFRS 4. For example, UK insurance companies have presented deferred acquisition costs in a variety of ways, including as an intangible asset, as a prepayment or as an asset of indeterminate classification.
4.58Under current accounting in the UK, components of the rights and obligations arising from insurance contracts are presented in different line items on the balance sheet (for example, in deferred acquisition costs, receivables and insurance contract liabilities). The requirement under IFRS 17 to present a single insurance contract asset or liability for a group of contracts, comprising all insurance components of the contracts (with further disaggregation in the notes), will represent a simplification and enhance understandability.
Enhanced disclosures
4.59IFRS 17's extensive and standardised disclosure requirements will enhance transparency and understandability. For example, IFRS 17 requires reconciliations from the opening to the closing balances of key balance sheet items100 including the liability for remaining coverage, any loss component and the liability for incurred claims. Separate reconciliations are also required for the estimate of the present value of future cash flows, the risk adjustment and the CSM. These extensive new disclosures will provide users of accounts with greater understanding of how the carrying amounts of insurance contracts have changed.
4.60Similarly, the extensive disclosures required by IFRS 17 of changes in the CSM101 and of when the entity expects to recognise CSM in future102 will provide more consistent insight into developments in an entity's past and expected profitability.
Changes in the CSM relate mainly to the recognition of income in profit or loss reflecting the provision of services in the period. However, they may arise for other reasons, including the effect of new contracts added to the group and changes in claims expectations, and the reconciliations will explain such changes, enhancing transparency and understandability.
Costs and benefits of applying IFRS 17
Introduction
4.61Regulation 7(2)(b) of SI 2019/685 requires the UK long term public good assessment to have particular regard to the costs and benefits that are likely to result from the use of the standard.
4.62The purpose of this section of the ECA is to address Regulation 7(2)(b). Consideration has been given to costs and benefits for insurance companies, primary users of insurance company accounts and other stakeholders.
4.63Other sections of this ECA also address what are, in a broad sense, the likely costs and benefits of applying IFRS 17. In particular, the section above concerning whether the standard is likely to improve the quality of financial reporting sets out key benefits of the standard, and aspects of the assessment below of IFRS 17's wider economic impact also describe costs and benefits likely to result from the standard. While this section makes reference to such wider costs and benefits, its focus is on the more direct effects on expenditure and operational benefits.
4.64In its IFRS 17 Effects Analysis the IASB advised stakeholders that applying IFRS 17 may involve significant time, effort and cost to gather new information, employ or develop people with appropriate skills and make changes to their financial systems. In addition, the IASB noted that transition to IFRS 17 will require a significant level of engagement with, and education of, users.
4.65While stakeholders have generally quantified the costs of implementing IFRS 17, they have not quantified the costs of complying with IFRS 17 on an ongoing basis. In addition, the evaluation of anticipated benefits is primarily qualitative, due largely to the challenges of quantifying benefits accurately prior to implementation.
4.66Information on costs and anticipated benefits has been sourced from UKEB User and Preparer surveys 103, a User roundtable104 and webinars105 as well as from interviews with individual stakeholders. Sixteen insurance companies responded to the Preparer survey, representing approximately 67% of the total gross written premiums of all UK insurance companies using IFRS. Twenty-one users participated in the User survey with representation from analysts, ratings agencies and investor associations. Nine analysts also attended the User roundtable to discuss the key themes identified in the User survey. In addition, we also held a series of interviews with preparers, users and regulators in September 2021 to validate aspects of our assessment.
4.67The assessment has also considered external research from a range of third parties, as referenced in this section.
Costs
Insurance companies: implementation costs
Direct costs
4.68A 2018 KPMG report106 observed that IFRS 17 "marks the biggest single change to insurance accounting - bigger than the introduction of IFRS itself, since up till now IFRS has carried forward the use of pre-existing bases of accounting for insurance contracts with minimal harmonization.”
4.69This is reflected in the feedback from insurance companies that participated in the Preparer survey. Survey participants anticipated implementation costs in the range of £3.5m to £191m, with the aggregate cost being approximately £783m107. Life insurance companies' costs were typically greater (69% of the aggregate survey costs) than other types of insurance companies due to the longer coverage periods of their contracts and the higher volumes of data required to meet the requirements of IFRS 17.
4.70Extrapolating the aggregated costs from the survey for all UK IFRS reporters equates to an approximate total implementation cost of £1.18 billion108. For context, most survey participants in the Preparer survey noted that the costs represented 1% or less of their annual Gross Written Premiums, calculated as an average over the last 5 years. One user considered that the overall cost of implementation was relatively small in the context of the balance sheet of the insurance industry and that the costs typically have been recognised as an expense over several periods.
Indirect costs
4.71Some participants in the Preparer survey found that achieving compliance with IFRS 17 would require major change programmes extending outside the finance and actuarial functions109 and impacting data, systems and processes.
Consequently, many IFRS 17 implementation programmes have required significant investment and are several years in duration.
4.72Survey participants took a range of approaches to achieve compliance with IFRS 17 based on a 'gap analysis' from their current state to their target compliant state. These included narrow scope 'compliance only' approaches through to wider scope 'finance transformations' delivering wider operational changes in addition to achieving compliance with IFRS 17.
4.73Examples of wider transformational activities included:
- the upgrade, replacement or decommissioning of legacy finance or actuarial systems;
- creation of 'data lakes' to store finance and actuarial data including tools to interrogate and visualise that data;
- process re-engineering, automation and documentation, particularly around key governance controls and the working day timetable; and
- enhanced data policies, architecture, sourcing, remediation and controls.
4.74In some cases, the costs of these wider transformation approaches were included in the reported total cost of IFRS 17 compliance. One survey participant noted their total reported IFRS 17 implementation cost included a significant level of actuarial and finance transformation costs and therefore should not be interpreted as directly attributable to the cost of compliance. However, due to the integrated nature of the programme it was difficult to isolate the actual compliance cost.
4.75Other participants viewed these types of costs, for example replacing a general ledger, as direct costs of compliance on the basis that the costs would not necessarily have been incurred had they not been a factor in enabling IFRS 17 compliance.
4.76It is likely, therefore, that not all the reported costs are directly attributable to achieving IFRS 17 compliance and that the total may to some extent be over-stated.
4.77Survey participants advised that the cost of implementing IFRS 17 was significant due to a range of factors including:
- Insurance companies operating legacy finance and actuarial systems, inflexible operational environments or with data integrity issues were required to make significant investments in strategic solutions.
- Delays to the finalisation of IFRS 17 by the IASB had the effect of slowing industry consensus and engagement with audit firms. This also impeded third party providers from offering 'production ready' calculation tools, meaning that a significant amount of the research and development fell to insurance companies.
- Brexit negotiations caused uncertainty relating to whether UK companies were required to comply with EU or UK-adopted IFRS.
- The Covid-19 pandemic introduced unexpected delays and additional costs as resources and management attention were diverted from the implementation of the standard.
4.78A respondent to the consultation on the draft ECA added that implementation costs were also high due to the complexity caused by the requirements for annuity contracts that had vested from with-profits contracts and the inability under IFRS 17 to unbundle hybrid contracts.
4.79Most UK insurance companies plan to apply IFRS 9 Financial Instruments at the same time as they apply IFRS 17 (1 January 2023). Nearly all survey participants considered the implementation costs of IFRS 9 to be 'negligible'. Most were delivering IFRS 9 requirements as part of the wider IFRS 17 programme or as part of business as usual.
Ongoing costs
4.80The IASB Effects Analysis notes that the IASB "expects companies to incur incremental costs in applying IFRS 17 on an ongoing basis". They also acknowledged that the "ongoing costs to maintain accounting and actuarial systems, processes and internal controls are expected to be higher for many companies compared with those incurred when applying IFRS 4."
4.81Most survey participants had yet to fully assess and quantify the impact of IFRS 17 on 'business as usual' costs as their solutions were still in development. However, 64% anticipated that costs were likely to increase to ‘some extent' while 36% expected no material change. Examples of additional ongoing costs included additional audit fees, licence costs for IFRS 17 specialist software and additional finance and actuarial resources to manage the reporting processes.
4.82However, the majority noted they were anticipating either neutral or negligible net cost increases after identifying operational efficiencies in their transformation programmes.
4.83The requirements of the standard that survey participants anticipated causing the most significant on-going costs were:
- The grouping of contracts into profitability buckets – this requirement is considered to significantly increase the amount of management review required.
- The grouping of contracts into annual cohorts - maintaining, processing and storing significantly more data is expected to require additional data warehousing and new visualisation tools and licence fees for third-party software.
- The use of historic 'locked-in' discount rates as well as current rates – would require more management time and new or upgraded actuarial models, incurring extended or new licence fees.
- Risk adjustment – as the computation and disclosure of the risk adjustment and related confidence levels were considered highly judgmental, they would require additional modelling capabilities and management time.
- Disclosures and granularity of reporting - The new and extensive disclosures would result in increased ongoing reporting costs both internally (e.g. skilled reporting resources) and externally (e.g. audit costs).
- Eligibility testing for determining VFA at an individual contract level – e.g. when new business is written by a with-profit fund.
4.84Of the survey participants that were responding on behalf of a group, 45% expected subsidiaries to have to prepare individual entity accounts using policies other than IFRS 17. Of these, all expected that this would lead to both greater differences in accounting between subsidiary and group and increased annual financial reporting costs.
Other external sources relating to costs for insurance companies
EFRAG - Final Endorsement Advice Appendix III (June 2020)
4.85EFRAG amended their 2018 insurance company survey in June 2020 and separately identified the four UK participants. Overall, they found that implementation costs had significantly increased for participants since 2018. For context, EFRAG also noted that each of the listed participants had paid average annual dividends in excess of €1 billion for the past 5 years (excluding share repurchases).
EFRAG Estimated costs and savings profile (Appendix III)
| Estimated Costs | €M | Range €M (minimum – maximum) | No. of participants |
|---|---|---|---|
| Europe (excluding UK) | |||
| On-off costs | 2,332 | 10-395 | 15 |
| Ongoing costs | 180 | 4-50 | 8 |
| Cost savings | (68) | (3) – (50) | 4 |
| UK | |||
| On-off costs | 744 | 38-326 | 4 |
| Ongoing costs | 13 | 0.1 | 1 |
| Cost savings | (76) | (76) | 1 |
4.86The four UK participants' implementation costs, when converted to pounds equate to an aggregate of £630m with a range of £32m - £275m and cost savings (for one participant) of £64m.110
4.87In the Preparer survey, the four participants with the largest implementation costs had a lower aggregate cost of £565m and a narrower cost range of £91m to £191m, with no cost savings reported. During the follow up interviews with a sample of insurance companies in September, all advised that their implementation cost profiles had not significantly changed. The reasons for the apparent differences from EFRAG's results are unclear111.
4.88However, in broad alignment with the Preparer survey112, EFRAG also found that for all participants by mid-2020, 42% of insurance company implementation costs had already been incurred at the time of their assessment.
4.89EFRAG noted that 21% of their total participants had identified material estimated cost savings. These related mainly to internal changes including increased use of automation, a switch to internal solutions, improved interfaces between group and local entities and other operational efficiencies113.
SAS Perspectives and approaches to IFRS 17 (2018)
4.90SAS surveyed 100 senior executives working in the UK insurance industry and identified that insurance companies were preparing for major changes to their data and accounting and actuarial systems to achieve compliance with IFRS 17. They also found that over 80% of respondents anticipated having to make significant investments in these areas.
4.91The SAS survey also found that nearly all their survey participants (97%) expected IFRS 17 would increase the cost and complexity of their operations. Their respondents (90%) also anticipated that the costs would exceed those incurred for the implementation of Solvency II.
Users: costs
4.92The UKEB User survey found that most users consider the accounts their 'most important' source of information when assessing insurance companies. Approximately two thirds of users anticipated significant operational changes relating to collecting new data, rebuilding valuation model inputs, updating processes and training staff. However, despite these anticipated operational changes, most did not consider either implementation or ongoing costs would be significant.
Sunk costs
4.93In developing IFRS 17 the IASB undertook an evaluation of the costs and benefits of the standard to decide whether the standard should be issued. However, the assessment of costs and benefits in this ECA is being performed in accordance with the statutory endorsement criteria in SI 2019/685, and relates to the separate, and later, decision by the UKEB as to whether to adopt IFRS 17 for use in the UK.
4.94Guidance in the Government's ‘Green Book’115 indicates that expenditure ‘already incurred' (i.e. incurred prior to the implementation of a policy or regulation) should in principle be excluded from the appraisal of costs and benefits i.e., treated as 'sunk cost'. The rationale is that only costs and benefits affected by decisions still to be made should be included in the analysis.
4.95Although the UKEB is not required to comply with the Green Book, in this context it has adhered to Green Book principles as far as possible. The Green Book approach to sunk costs has therefore been referred to in determining an appropriate approach for our assessment of IFRS 17. This approach to sunk costs is also broadly consistent with the requirement of SI 2019/685, which requires consideration of "the costs and benefits that are likely to result from the use of the standard" in the context of a UK long term public good assessment [emphasis added].
4.96IFRS 17 was issued by the IASB in May 2017 with an effective date of January 2021. However, the effective date was postponed to January 2023 following further amendments proposed in June 2019116, which were finalised in June 2020.
4.97As the lead-in time for compliance with IFRS 17 spans several years, insurance companies could not afford to defer the commencement of their implementation programs until after the formal adoption of the standard for use in the UK. Survey participants indicated that approximately 44% (£347m) of their total implementation costs had been incurred by 30 June 2020. Based on the estimated overall industry implementation cost of £1.18 billion, this would suggest that £518m (i.e. 44%) had been incurred by the industry by 30 June 2020.
4.98Determining an appropriate point before which IFRS 17 implementation costs should be treated as sunk is a matter of judgement. Key factors considered include:
- the date all significant recognition, measurement and presentation requirements in IFRS 17 were finalised by the IASB;
- the month in which a substantive IFRS 17 UK endorsement project commenced; and
- the date from which stakeholders could reasonably be considered to have a legitimate expectation that the UKEB will adopt IFRS 17 for use in the UK.
4.99Both a) and b) occurred during quarter 2 of 2020. A legitimate expectation that the UKEB will adopt IFRS 17 is considered to have arisen on the sharing of the complete draft IFRS 17 ECA package for the UKEB's 28 October 2021 Board meeting. On this basis, the costs incurred by insurance companies up to the end of June 2020 represent the minimum that should be viewed as sunk costs. Although not quantified, significant further costs have been incurred by insurance companies since that date and would therefore also fall to be treated as sunk costs.
4.100Whilst the analysis of costs above recognises the significant implementation costs incurred by insurance companies, the UKEB took into account the fact that, were it to decide not to adopt IFRS 17 for use in the UK, it is unlikely that implementation costs incurred to date could be reversed or recouped. Therefore, the focus of the assessment of costs in this ECA and the basis for the adoption decision are the net long term costs from use of IFRS 17.
4.101Insurance companies have incurred most of the implementation costs and some have identified indirect benefits from that investment. To the extent those benefits arise directly from the costs incurred prior to October 2021, those benefits would also be excluded. These indirect benefits are very difficult to quantify. However, as most participants in the Preparer survey noted limited or no benefits, any such benefits would be highly unlikely to have a significant impact on the assessment of total net sunk costs or on an adoption decision.
Benefits
Insurance companies: benefits
Direct benefits
4.102The Preparer survey found that approximately two thirds of participants anticipated negligible or no benefits from the implementation of IFRS 17. This view was not unexpected as most of the IFRS 17 implementation costs fall on insurance companies while most of the expected benefits arise for users of their accounts.
4.103Most survey participants anticipated moderate benefits from the opportunity to streamline internal systems and processes and gain a better understanding of their data. Of those responding on behalf of a group most also anticipated moderate benefits from achieving greater consistency of accounting treatment between entities in the group. Two large insurance groups rated these benefits as significant117.
4.104The top five most common potential benefits identified by insurance companies in the preparer survey were:
- Greater comparability with other insurance companies - disclosure of risk adjustments and related confidence levels will enable the level of risk in reserves to be assessed more accurately. The CSM, and its projection for new business, will demonstrate the actual profitability achieved.
- Internal systems streamlining – enhancements of actuarial and finance systems and the removal of legacy systems and associated maintenance costs and risks.
- A better understanding of data - greater insight into financial performance through increased granularity of profitability information.
- More useful information for users – by providing a better understanding of insurance businesses the sector may potentially become more attractive to investors.
- Greater alignment with Solvency II – due to the importance shareholders and other external stakeholders place on understanding the capital position and dividend capacity.
4.105Some insurance companies also observed during interviews that they were likely to find the additional disclosures required by IFRS 17 useful for gaining insight into their peers' approaches and performance. Given a single international basis of accounting, international insurance groups should also benefit from reduced training costs and from more flexible deployment of staff.
Indirect benefits
4.106In addition to achieving compliance, some participants commented that they had identified several non-financial indirect benefits. These were difficult to quantify as they related to a range of areas such as improvements in the completeness and accuracy of policy and claims data, more efficient processes and effective controls or refreshed technology infrastructure. It is therefore possible that wider recognition of the benefits to insurance companies of implementing IFRS 17 and applying the standard on an ongoing basis may emerge over time118.
4.107While several Preparer survey participants noted similar indirect benefits, they did not disclose quantifiable cost savings. In follow-up interviews participants noted that, where cost savings had been identified, they were not considered significant and had been used to offset anticipated increases in business-as-usual costs. Others noted that while they were expecting to realise operational improvements and efficiencies, these had not resulted in any significant cost savings.
4.108From paragraph 4.249 we discuss cost of capital for insurance companies. Although stakeholder views were mixed, the conclusion is that in the long-term insurance companies may potentially benefit from a lower cost of capital and improved access to capital. Given the scale of insurance company balance sheets, even a small reduction in cost of capital could result in significant gains to insurance companies over the long term.
External sources relating to benefits for insurance companies
EFRAG - Final Endorsement Advice Appendix III (June 2020)
4.109EFRAG noted that none of the four UK participants in their survey considered that the benefits of IFRS 17 would outweigh the costs. This contrasted with the result for the other participants in their survey, 38 per cent of whom considered that the benefits of applying the standard would outweigh the costs. EFRAG's assessment also noted that some insurance companies viewed IFRS 17 as an opportunity to improve internal data, processes and systems and that many companies noted these as significant improvements that would have long term benefits for their organisations.
SAS - A Transformation in Progress - Perspectives and approaches to IFRS 17 (2018)
4.110SAS found that 84 per cent of their survey participants believed that the changes from IFRS 17 would deliver additional benefits for their organisation beyond compliance, while only 12 per cent viewed the implementation of the standard as purely a compliance exercise.
4.111In contrast to the UKEB Preparer survey results, SAS also found that UK insurance companies broadly welcomed the standard and that "87 per cent believe it will either be crucial for the survival of the insurance industry or will at least increase robustness for the future".
4.112While the reasons for the apparent disparity between the results of the SAS survey and the UKEB Preparer survey are unclear, factors could include the role and seniority of participants and the timing of the survey. The SAS participants may have placed greater weight on a longer term, strategic and post-implementation perspective while the UKEB survey sought responses from participants directly involved with implementation and who may have reflected a more technical view based on their experiences. In addition, the UKEB Preparer survey was more recent (2020 compared with 2018), so respondents would have had more exposure to the practical challenges and implications of implementation.
Users: benefits
4.113Based on feedback from the User survey, roundtable and interviews, most users considered that accounts prepared under IFRS 17 would represent an improvement over current accounting by insurance companies and that, for them, the benefits would exceed the costs.
4.114Nearly all participants in the User survey anticipated that IFRS 17 would result in better comparability between the financial statements of insurance companies and were optimistic about the realisation of the intended benefits. Most also expressed frustration with the current accounting for insurance contracts, with several highlighting challenges arising from inconsistent accounting practices and less insightful disclosures.
4.115Users anticipated that insurance companies would start to share detailed information on the impact of IFRS 17 in Q2 or Q3 of 2022119, and expressed a desire for more and earlier engagement from insurance companies. They noted that until they had access to accounts prepared on an IFRS 17 basis it would be challenging to provide a definitive view on the overall potential benefits.
4.116User survey participants were asked to rank anticipated benefits in order of their significance. The top five are summarised below120:
- Consistent revenue and profit recognition - users considered that IFRS 17 should help resolve the main causes of the lack of comparability of financial information presented by insurance companies. The recognition of revenue as services are provided over the coverage period would result in more consistent recognition of revenue and profits. In addition, for life companies in particular, the relationship between new business and the back book would become more transparent.
- Detailed disclosure of key assumptions and estimates - disclosures of discount rates were considered a significant improvement that would provide greater insight regarding management expectations and the level of prudence inherent in estimates. The requirement for explicit differentiation between the risk adjustment for non-financial risk and the CSM was expected to provide greater insight into the emergence of profit.
- Measurement principles being closer to Solvency II - users anticipated that the fact that the IFRS 17 measurement basis (broadly best estimate plus risk adjustment) aligned more closely to Solvency II would make it easier to understand and interpret an entity's accounting and capital positions.
- Separate reporting of underwriting and investing results - users will be able to distinguish between and assess management performance in respect of the main drivers of profitability from insurance company activities i.e., the provision of insurance coverage and investment activities.
- Identification of onerous contracts - as gains and losses on these contracts can no longer be offset, they will become transparent to users through the loss component.
4.117A majority of users surveyed did not consider that the principle-based nature of the standard would allow excessive judgement by insurance companies. However, a majority thought that alternative performance measures would still be required.
4.118The UKEB conducted a roundtable discussion with users in June 2021. In addition to the points noted above, in relation to benefits, that discussion also identified that users valued the greater simplicity and clarity of the statement of profit or loss and other comprehensive income under IFRS 17. It was expected to provide them with much greater insight into the separate sources of income and expenses of insurance companies.
4.119Further information on the expected improvements in financial reporting which will benefit users of insurance accounts is set out earlier in this Section 4 under the heading ‘Will IFRS 17 improve the quality of financial reporting'.
External sources relating to benefits for users
EFRAG - Final Endorsement Advice Appendix III (June 2020)
4.120EFRAG also concluded that overall, most users anticipated greater benefits than costs. Key benefits identified were similar to those identified in the UKEB outreach and related to "the identification of onerous contracts, profit earned as services are provided, disclosure of the assumptions used and measurement being closer to Solvency II, split of the underwriting and investing results”.
KPMG: analysts' views on IFRS 17 and the insurance reporting landscape (December 2018)
4.121KPMG conducted a global survey of 20 insurance analysts and noted that they found the current financial information challenging to use (see diagram below). The most common challenges were noted as "different discount rates currently used to discount liabilities, the different allowances insurers make for prudent margins and the use of inconsistent measurement bases”.
Comparability of financial performance information provided by insurers with other insurers
A bar chart titled "Comparability of financial performance information provided by insurers with other insurers". The y-axis ranges from 0 to 60, and the x-axis shows categories for comparing insurers, labeled "1 Very easy", "2", "3 Neutral", "4", "5 Very difficult to compare insurers with each other". The bars represent percentages: "3 Neutral" is 20%, the category between "3 Neutral" and "4" is 15%, the category between "4" and "5 Very difficult" is 15%, and "5 Very difficult" is 50%. The visual representation shows varying degrees of difficulty in comparing insurers.
4.122KPMG concluded that analysts expected some significant benefits from IFRS 17. However, at the time of the survey they were not sufficiently familiar with the requirements of the standard to draw firm, detailed conclusions.
Aon - The Impact of IFRS 17 on Key Performance Indicators (February 2020)
4.123Aon hosted a roundtable in London with representatives from rating agencies (AM Best, Moodys, Fitch, Standard & Poor's), auditors (BDO and Deloitte) and investment banking (Berenberg) to seek a high-level consensus on the shape of future insurance company KPIs.
4.124Analysts foresaw that the change in the CSM would form the basis of a KPI within the life insurance sector. This was because it "...shows trends in performance by making it clearer how expenses, claims, strength of underwriting interact with the profitability of groups."
4.125Participants in the Aon roundtable discussion also noted that under IFRS 17 the income statement may 'more transparently' demonstrate the actual value of the investment function for the first time. Participants expected the reported relationship between investment income and the unwinding of the discount on insurance liabilities would provide new insights into the investment function.
4.126Overall, Aon roundtable participants supported the standard, noting that "although the requirements are complex, analysts consider IFRS 17 a major improvement to financial reporting in the insurance industry".
Other stakeholders
Auditors: costs and benefits
4.127Auditors are likely to be required to undertake specialist training on the requirements of IFRS 17 and audit teams may require additional expertise in relation to actuarial methodology, systems and data analytics. Auditors may also need to invest in new tools and technologies to assess data and to replicate actuarial modelling.
4.128Accountancy Europe122 advised EFRAG that auditors were likely to require “...significant investments in technology such as digital auditing platforms, big data analysis and the required computational capabilities in actuarial models" to conduct IFRS 17 audits123.
4.129In the UK most insurance companies are audited by the largest audit firms. These firms have been preparing for the impact of IFRS 17 on their audits and advisory work for some time and have sufficient resources to scale up as necessary. In addition, participants in the Preparer survey expect some of these costs to be passed on to insurance companies through advisory fees and increased audit fees. While some costs may be borne by auditors to enhance their offering, the assumption is that the majority is likely to be passed on to insurance companies due to the increased complexity of the audit. The investment in developing IFRS 17 expertise can also be shared across international networks, not borne solely in the UK.
4.130Auditors are expected to benefit from having a comprehensive set of accounting requirements to audit against and from being able to benchmark more readily due to a higher level of consistency in insurance company accounting practices124. In addition, there may also be benefits for auditors from not being required to understand the range of local GAAPs currently used by insurance companies, and from the increased transferability of staff across international networks.
Regulators: costs and benefits
4.131The IASB Effects Analysis notes that IFRS 17 "...is not designed with the objective of being suitable for regulatory and tax frameworks." The IASB also stated that they would only expect regulators and tax authorities to incur costs if their requirements depended on financial reporting.
4.132The IASB Effects Analysis also notes that due to the consistency introduced by the standard there could be a potential reduction in the costs associated with "...analysing differences between financial reporting data and regulatory or tax reporting data of insurance companies that may be currently incurred by regulators and tax authorities”.
4.133In the UK, the main regulators relevant to insurance companies are the Prudential Regulation Authority (PRA) and the Financial Conduct Authority (FCA), responsible for the prudential regulation and supervision of insurance companies.
4.134The PRA does not use company accounts as the primary basis for the regulation of insurance companies so it is not likely that the introduction of IFRS 17 will significantly change their activities or costs.
4.135As IFRS 17 aims to enhance transparency and comparability in insurance company financial reporting, the implementation of IFRS 17 is in general expected to be beneficial for regulators.
4.136As the UK regulator for auditors, accountants and actuaries, the FRC has an interest in promoting improvements in financial reporting and in audit quality. Feedback from the FRC indicates that IFRS 17 will enhance the FRC's ability to conduct reviews of both insurance company accounts and audits of those accounts. This is because IFRS 17 establishes comprehensive requirements for the recognition, measurement and presentation of insurance contracts under IFRS for the first time. In particular, the FRC welcomes the fact that IFRS 17 will require recognition and measurement principles for insurance contracts that are more consistent with IFRS as a whole, and considers that the improved comparability expected under IFRS 17 will enable users to better benchmark insurance company accounts, both within the UK and across other jurisdictions. In addition, the FRC expects that the application of IFRS 17 will assist it in identifying best practice in the audit of insurance company accounts.
4.137HMRC is likely to incur costs in familiarising staff with IFRS 17, evaluating the impacts and delivering any legislative change that might be required. The standard should produce greater consistency in insurance company accounts and assist HMRC's ability to identify tax risk.
Summary of costs and benefits for stakeholders
| Insurance Companies | Users | Auditors and Regulators | |
|---|---|---|---|
| Direct | High £0.7 billion for IFRS reporters125 |
Low Limited set up costs |
Low Costs absorbed as business-as-usual or in part passed on |
| Implementation Costs | Indirect | ? Where wider organisational changes were required or desired |
N/a |
| Ongoing Costs | Direct | Low Largely offset through operational efficiency gains |
Low Limited impact on business-as-usual |
| Indirect | Low Most insurance companies anticipate limited benefits |
High Significant improvement in financial reporting expected (to be confirmed based on first IFRS 17 accounts) |
|
| Ongoing Benefits | Indirect | Medium Improvements in systems, data and processes Potential lower cost of capital in longer term |
N/a |
Likely effect on the economy of the UK
Introduction
4.138Regulation 7(2)(c) of SI 2019/685 requires the UK long term public good assessment to have particular regard to whether the use of the standard is likely to have an adverse effect on the economy of the UK, including on economic growth. The purpose of this section of the ECA is to address Regulation 7(2)(c). This evaluation is one of the elements of the broader assessment of whether the standard is conducive to the UK long term public good (see paragraph 4.2 above).
4.139IFRS 17 is expected to lead to substantial changes in the way insurers account for insurance contracts, with consequential effects on the way their financial position and profitability are reported in their accounts.
4.140Financial reporting standards are developed to report the economic activities and transactions undertaken by companies in a way that is useful to users, including being transparent and understandable to their investors. However, it is possible that such changes in how companies report their activities will bring about an indirect change to how they conduct their business.
4.141Any material changes to how business is conducted by individual insurance companies may, in turn, have an impact on the UK economy. As evidenced in the sector overview (paragraphs 4.5 - 4.29 above), the insurance sector is an important industry for the UK, accounting for £264 billion of gross written premiums in 2020 and managing over £2 trillion of assets, indicating the potential macroeconomic impact. Moreover, insurance companies using IFRS represent an important share of the UK industry, accounting for approximately 60% of the gross written premiums.
4.142In this section, therefore, we consider the potential impact of IFRS 17 on the UK economy, focusing on the following areas:
- business conducted by the insurance industry, including product mix and pricing strategies;
- competitive landscape of the UK insurance industry;
- wider use of IFRS; and
- macroeconomic impact, in particular on:
- cost of capital and investment decisions by investors;
- investment decisions by insurance companies;
- credit ratings;
- financial stability and tax revenues; and
- economic growth.
4.144Our assessment is based on evidence gathered from stakeholders by the UKEB (including the Economic Report126, the Preparer survey, the User survey, the User roundtable and follow-up interviews), additional quantitative analyses, third party studies and an in-house economic assessment. See paragraph 4.66 for further detail.
Potential impact on business conducted by UK insurance industry
Impact on product mix and pricing strategies
4.145As set out in Section 2, IFRS 17 will change the way insurance companies report their profits. Changes to accounting and reporting requirements do not alter the underlying economics of a business, only the way those same economics are reflected in the companies' accounts. In theory, therefore, changes in insurance product design, mix or price should not arise as a direct result of applying IFRS 17 (see also IASB Effects Analysis).
4.146In practice, however, new accounting standards can bring more clarity to the underlying economics of transactions, sometimes highlighting risks or costs that were previously less apparent. For example, under IFRS 17 the reporting of profits and losses in individual years may change significantly in some cases127. This may bring about changes in underlying business practices, including changes to product offering and pricing. Such effects are considered to be more likely and significant for life insurance companies than for general insurers, given the greater impact of IFRS 17 on long duration contracts (see also IASB Effects Analysis).
4.147As part of our work, we considered specific aspects of IFRS 17 which may have an impact on products and pricing: reporting of onerous contracts and CSM allocation. In addition, we refer specifically to the standard's impact on two particular product types – annuities and with-profits contracts – addressed as priority areas within Section 3 above. These represent a significant proportion of UK insurance business and stakeholders have asserted that their accounting treatment is particularly affected by IFRS 17. Finally, our assessment of these topics considered the views of UK stakeholders and then concludes by evaluating whether the potential impacts on products and pricing are likely to have an adverse effect on the UK economy.
Onerous contracts
4.148As explained in Section 2, IFRS 17 requires the separate identification of groups of contracts that are onerous at inception as well as the regular updating of
Onerous contracts
4.148As explained in Section 2, IFRS 17 requires the separate identification of groups of contracts that are onerous at inception as well as the regular updating of fulfilment cash flows. The latter requirement facilitates the prompt identification of groups of contracts that subsequently become onerous. Losses on onerous contracts are required to be recognised immediately in profit or loss. This greater transparency may prompt some insurance companies to change product offerings, reprice existing products or withdraw entirely from a particular product segment.
4.149Evidence collected in-house is consistent with the idea that IFRS 17's requirements for recognition of onerous contracts might affect product offering or pricing. For example, the Economic Report noted that reporting requirements concerning onerous contracts may deter offering products that are onerous at the outset.
4.150The majority of respondents to the User survey believe that IFRS 17 is likely or very likely to have an impact on product offering (57% of the respondents) and pricing (52% of the respondents). According to several respondents, pricing strategies are expected to change due to the recognition of onerous contracts at the outset. One respondent said that "the identification of onerous or less profitable groups of contracts may lead to a re-evaluation of the pricing of those products" and another noted that "separate disclosure and immediate recognition of onerous contracts could lead insurers to focus on reducing the extent of onerous contracts, possibly by price changes".
4.151Views expressed by insurance companies during interviews varied according to the nature of their business. General insurers were more likely to expect IFRS 17 to have an impact, as the ability to bundle together onerous and non-onerous contracts of different types (say home and car insurance) will be lost. For example, one insurance company commented that new business teams would need to be aware of the accounting impact of onerous contracts and that this would influence the business written, and another noted that onerous contract accounting under IFRS 17 would probably affect product offering and pricing. However, two insurers offering predominantly annuities did not anticipate any significant impact, as they are unlikely to write onerous business.
4.152Evidence collected by third party organisations is also consistent with the expectation that IFRS 17's requirements regarding onerous contracts might affect product offering or pricing. For example, using survey-based evidence, EFRAG noted that some of their respondents would probably avoid pricing methods leading to the recognition of onerous contracts at inception[^128].
CSM allocation
4.153IFRS 17 will require an insurance company to recognise the contractual service margin (CSM) (the unearned profit that the company expects to recognise) as it provides services over the insurance coverage period. For some products this will represent a significant change from current accounting practice in the UK under IFRS 4 (see paragraphs 4.50 – 4.53 above).
4.154The Economic Report (page 23) noted that "while the underlying economics (of the insurance business) is unchanged, the way that profits are reported annually will change. It is possible that this will prompt some changes in insurers' product mix and pricing, either because they think this is necessary to secure investor confidence and a low cost of capital or because the financial incentives of individual senior managers depend on reported profits".
4.155This view is widespread amongst users of financial statements. A majority of respondents to the User survey believe that IFRS 17 is likely or very likely to have an impact on product offering and pricing. They largely anticipated changes to take place in the life insurance sector, with one respondent stating that "life insurance products will require redesign to maximise performance under IFRS 17", and another commenting that "life insurance products [will] become more attractive due to the ability to identify profit emergence in audited accounts". One user noted that annuity contracts could lose their attractiveness as less profit would be recognised at inception, while another considered that fewer products with guarantees may be offered.
4.156Insurance companies also appear to share this view. For example, one noted that IFRS 17 was particularly likely to affect annuities, as the majority of profit will no longer be recognised at inception.
CSM allocation for annuities
4.157As explained in Section 3, some UK stakeholders are concerned that IFRS 17's requirements may result in accounting outcomes that have a material and potentially detrimental impact on the UK annuity market[^129].
4.158Annuity business is long term business, with average policy duration of around 15 years for individual annuities[^130]. Average duration in the bulk purchase annuities (BPA)[^131] market is longer, as a significant proportion of contracts is still in the investment phase (deferred annuities). In both cases, however, groups of contracts generally have a very long tail: that is, a relatively small minority of contracts in a cohort may be in force for many decades (for example where contract benefits pass to a much younger individual).
4.159The UK annuity market includes a mix of both individual and BPA but these businesses differ in levels of maturity:
Individual annuities
- The individual annuity market is mature and declining, due largely to pensions freedoms introduced by the 2014 Pensions Reform Act[^132]. For example, in a 2018 report,[^133] PwC noted that new individual annuities sold in the UK declined by 78% between 2013 and 2016.
- Nevertheless, the size of the back book means this remains a major business. ABI data from 2019 indicates there were 6.1m pension annuities in the UK[^134]. FCA information shows that new business was provided by roughly 20 entities, though business is now concentrated in only five main groups[^135].
Bulk purchase annuities
- By contrast, the BPA business is increasing in significance and is the main growth area within the UK insurance market. BPA transactions amounted to £31.6bn in 2020, as reported by PensionAge[^136], and Hymans Robertson report that almost £150bn BPA business has been written by eight active market participants in the period 2009 to 2020[^137].
- Hymans Robertson forecast BPA transactions to average around £40bn per year up to 2030. Although declining after 2030, their forecast shows continued high levels of BPA transactions up to 2040 (average over £20bn p.a.). The level of transactions is driven by pension schemes' de-risking strategies and buy-outs.
Assets under management backing annuity liabilities amount to more than £350 billion[^138].
4.160Current accounting under IFRS 4 is heavily based on accounting under old (pre-2005) UK GAAP, as set out in the ABI SORP. At inception, conservative reserves are established for expected future cash outflows. However, the premiums received (typically single upfront premiums) generally exceed the reserves and the difference is recognised immediately as profit (sometimes referred to as 'day 1 gains'). In addition to any gains or losses from experience variances and changes in assumptions, further future margins generally arise from the unwinding of the reserves. The typical profit profile includes a large day 1 gain followed by smaller and declining gains spread over the contract life.
4.161IFRS 17 by contrast stipulates that profit is recognised in line with the provision of service over the coverage period. Under IFRS 17 the profit profile for a group of contracts is expected to be smoother, though also declining[^139]. However, the absence of day 1 gains means that profit recognition will be significantly slower than under current practice.
4.162It is not possible to assess accurately the impact of different annuity profit recognition approaches as data is not publicly available. The graph below illustrates the cumulative profit that might be recognised for a BPA transaction assuming a mix of deferred and immediate annuities and reflecting an insurer's actuarial estimates. The graph shows the difference between (i) the profit recognition profile under current accounting practice; and (ii) the expected IFRS 17 profit recognition profiles under the two approaches considered by the IFRS Interpretations Committee[^140]. The difference between current practice and IFRS 17 arises mainly at inception. As evident from the graph, however, cumulative profits eventually converge in the long run, demonstrating that, over the life of the contracts, profits earned are not affected by IFRS 17.
Cumulative profits for a BPA transaction (mix of deferred and immediate annuities)
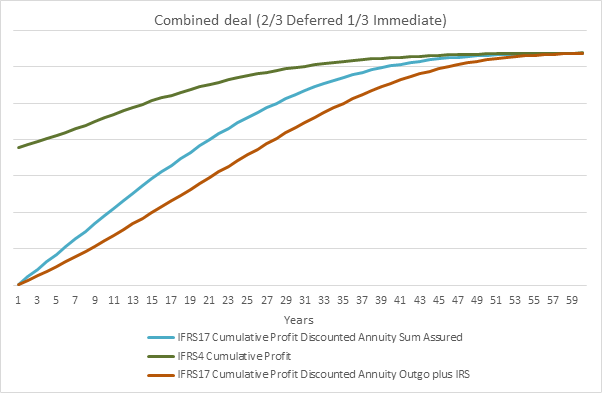
Source: illustrative example provided by an insurance company
4.163No data is available on the likely transitional impact from this change across the industry, but stakeholders expect material reductions in equity. The scale of the impact will further depend on the approach adopted on transition to IFRS 17: a retrospective approach is expected to result in greater transitional impacts than a fair value approach[^141]. A fair value approach is expected to be adopted for a large proportion of individual annuity business reflecting the maturity of the market and the impracticality of retrospective application[^142]. By contrast, retrospective approaches are expected to be applied to a large proportion of BPA business since the recent expansion in this market lends itself to easier access to inception data and application of the retrospective approaches.
4.164Overall, it is clear that IFRS 17 will have an impact on the reported profits of annuity providers, with profits from annuity contracts expected to be recognised significantly more slowly under IFRS 17 compared with current practice. The nature and extent of the impact will depend on the precise transition and CSM allocation methodologies applied, which are still under discussion.
4.165Some insurance companies have suggested that a potential consequence of enforcing a slower method of CSM allocation is that it may encourage structuring transactions. This could enable groups of contracts to be traded to release profit that has built up in the CSM. Although the impact of such transactions is likely to need disclosure in the accounts, the transactions may result in uneven profit recognition.
4.166Further, in the view of some companies IFRS 17 could discourage investment in the annuity and BPA business and provide an advantage to companies not required to apply IFRS 17.
4.167However, given the profitable and growing nature of the BPA business and that cash flows from annuity contracts will not change as a direct result of IFRS 17, it seems unlikely that financial reporting changes brought about by implementation of IFRS 17 will directly result in a significant reduction in this market. In addition, from interviews with annuity providers it emerged that they are not planning to change their product offering/pricing as a direct result of IFRS 17. Further, all major UK annuity providers report using IFRS and any adverse effect on the competitive position of these insurers from entities not applying IFRS as issued by the IASB is unlikely to be significant (for further details, see paragraphs 4.214– 4.218 below).
4.168This view was supported by feedback from users of accounts that metrics based on Solvency II are currently prevalent since regulatory reporting typically drives the generation of surplus capital and distributable profits. IFRS 17 will not change core Solvency II reporting and it is likely that companies will continue to rely on regulatory and other alternative performance measures as they try to explain business performance to investors. In the short term at least, feedback from insurers indicates that the IFRS accounts are unlikely to act as the biting constraint on distributable profits. Users also noted that profit recognition for annuities under IFRS 17 might have a positive benefit on insurance company governance, as it would enforce a longer-term perspective.
4.169Although for annuity providers the transitional impact of applying IFRS 17 is expected to be significant, the impact on these insurers' accounts of accounting for annuities under IFRS 17 will not necessarily be material for individual periods immediately post-implementation. However, because insurers expect this business to continue to grow, through the acquisition of portfolios of contracts under BPA transactions, the cumulative impact on balance sheets is likely to grow over time. In addition, insurers are currently still finalising their detailed approaches to CSM recognition for annuities. For these reasons, it will be important to consider the effect of IFRS 17 on annuity providers' accounts as part of the IFRS 17 post-implementation review. It will then be possible to assess the standard's impact on the basis of actual accounting information and with the benefit of users' detailed analyses.
With-profits business
4.170With-profits business has been a feature of the UK long-term investment and savings industry for several decades and the assets under management of with-profits funds amount to in excess of £250bn[^143] (roughly 12.5% of the total assets under management for insurance companies in the UK).
4.171However, a significant proportion of UK with-profits funds is now closed to new business and the market is in decline. The FCA reported that "total with-profits assets were approximately £426bn as at 2001, £411bn as at 2005, £333bn as at 2010 and £296bn as at 2015". As of 2017, the FCA reported £274bn[^144]. UKEB Secretariat estimates, based on Barnett Waddingham reports (see footnote 144) and review of company annual reports, suggest that nearly half of the assets under management attributable to with-profit funds are linked to closed funds.
4.172Of these closed funds, a number will already have been subject to inherited estate[^145] attribution exercises. In these cases, the ownership of any inherited estate may have been established by court-approved schemes, so some of the principal judgements under IFRS 17 will be less challenging.
4.173Some UK mutual entities have open with-profits funds; however, it is understood that these entities do not plan to use IFRS 17 to prepare their accounts.
4.174Based on feedback from stakeholders and our analysis, we estimate that the principal remaining UK inherited estates amount to approximately £30 billion in aggregate, held by three listed UK insurance groups. Of this, a significant proportion (roughly one third) relates to closed funds. Based on the 90/10 profit-sharing arrangements typical in the UK, this implies a shareholders' share of the inherited estate of approximately £3 billion across the three insurance groups. On an ongoing basis, it is only the annual change in the value of the inherited estate that would directly affect profits.
4.175In Section 3 we discuss the effect that IFRS 17 is expected to have on the accounting for with-profits contracts. In general, that analysis suggests that profits from with-profits contracts will be recognised earlier than is the case under current accounting under IFRS 4. In particular, the shareholders' share of any inherited estate may be recognised as profit. Further information on this effect and the potential impact for the insurance industry is considered below.
Current UK accounting practice under IFRS 4
4.176In the UK, with-profits business is generally accounted for in accordance with FRS 27 Life Assurance, as permitted by IFRS 4 grandfathering rules. FRS 27 states that the Fund for Future Appropriations (FFA) is the balance sheet item required by Schedule 9A to the Companies Act 1985 to comprise all funds the allocation of which, either to policyholders or to shareholders, has not been determined by the end of the accounting period. Consequently, the inherited estate formed part of the FFA. In the UK, under IFRS 4, the inherited estate is generally treated in full as a liability.
4.177Generally, current profit recognition practices closely reflect the regulatory requirements. Profit is recognised equal to the shareholder transfer for a period and is determined with reference to the declared policyholder bonuses. Regulatory requirements mean that insurers are not permitted to make any payment to shareholders out of the with-profits fund unless it can be financed by the fund without causing a deficit and it is made at the same time as the related distribution to policyholders. Changes in the value of the estate (e.g. resulting from investment returns) do not result directly in distributions to policyholders so remain part of the FFA and do not impact the income statement. Since UK with-profits policies typically involve a significant terminal bonus, profits tend to be 'back end loaded'.
The impact of IFRS 17
4.178Under IFRS 17, UK with-profits business is expected to be accounted for under the Variable Fee Approach (VFA). This reflects the contracts' nature as primarily investment-related contracts with participation features whereby policyholders participate in a clearly defined pool of underlying items. In broad terms this means that the shareholders' share of changes in the fair value of the underlying pool of assets will form part of the variable fee, which is taken to the CSM. The future release of the CSM to profit or loss is designed to reflect the provision of investment services.
4.179On implementation of IFRS 17, profit recognition for such contracts is expected to be significantly accelerated compared with current practice under IFRS 4, where profits are 'back-ended' as referred to in paragraph 4.177 above. Net credits to equity in respect of with-profits business may therefore arise on transition to IFRS 17, although quantitative data on the likely impact is not available at the time of writing.
4.180Overall, this analysis, when taken together with the scale of the relevant listed insurance groups (whose aggregate annual profits amount to several £ billion), indicates that the treatment under IFRS 17 of with-profits inherited estates or the accelerated profit recognition of with-profits business are unlikely to have a significant adverse effect on the UK insurance industry or on the wider UK economy.
Reinsurance to close transactions at Lloyd's
Background
4.181Insurance business at Lloyd's is written through syndicates. The nature of underwriting at Lloyd's is that each syndicate member is responsible for its share of each contract underwritten based on the proportion of capital each member has contributed to the syndicate. All the syndicate's assets, liabilities, income and expenses are shared in proportion to the capital contributed.
4.182In its accounts, a corporate member aggregates its shares of the assets and liabilities of each year of account in which it participates.
4.183The Lloyd's year of account mechanism is premised on Lloyd's members providing capital for one underwriting year of account at a time. Having underwritten one year of account, each member can decide whether to continue underwriting for the next year of account. Each individual year of account is a separate annual venture.
4.184Lloyd's members cannot take their profit for a year of account at the end of that year. Instead, they must wait a period, typically three years from the beginning of the year of account, before they receive a profit, or are asked to make good losses, from that year of account.
4.185RITC is a mechanism to ‘transfer' insurance liabilities from one year of account to the next, typically at the end of three calendar years. It may be viewed as the reinsurance of an entire year of account, effected by the payment of a reinsurance premium by the members of the 'closing' year (the ceding members) to the members of the 'accepting' year (the reinsuring members). This occurs even if members wish to maintain their participation in the syndicate. Following an RITC transaction, a ceding member is allowed to withdraw its capital in respect of the closing year of account.
4.186The RITC typically reinsures the liabilities into the next year of account of the same syndicate, though it could also be to a different syndicate. The level of participation of a member in a syndicate may vary from one year of account to the next, and members may enter or exit a syndicate.
Current accounting practice under IFRS 4
4.187Under IFRS 4 (and under UK GAAP), RITC contracts have generally not been viewed as reinsurance contracts. Instead, they have been treated as transferring obligations under insurance contracts from the members participating in one year-of-account to those participating in a later year of account. The ceding members of the syndicate derecognise the relevant insurance liabilities and the receiving (reinsuring) members recognise the liabilities on the same basis. In practice, changes in the level of participation may be achieved by simply adjusting the relevant balances, as for a change in estimates.
Expected impact of IFRS 17 on relevant entities
4.188Although not definitive, the developing consensus in the UK appears to be that RITC contracts will be treated as reinsurance contracts under IFRS 17, and that the criteria for derecognising the corporate member's interest in the earlier year of account (the original insurance contract liabilities) are unlikely to be met. Similarly, it seems unlikely that an RITC contract represents the modification of the terms of an insurance contract under IFRS 17.
4.189On the basis of the expectation summarised in the previous paragraph, a corporate member would be expected to continue recognising the insurance liabilities from the earlier year of account even after entering into an RITC contract.
4.190In the case of a corporate member that reduces or ceases its participation in a syndicate by entering into an RITC contract, this means that its interest in the earlier and later years of account would need to be recognised, to the extent of the decreased participation, on a 'gross' basis (i.e. it would present liabilities and a corresponding reinsurance asset).
4.191Many corporate members will apply only the Premium Allocation Approach (PAA) to their original insurance contract liabilities.[^146] When a member increases its participation in a syndicate under an RITC contract, in many cases the additional reinsurance liability recognised will be a liability for remaining coverage accounted for under the General Measurement Model (GMM). Additional accounting systems will need to be established and two measurement bases will be applied to the same group of contracts. In cases where the original insurance contract liabilities are accounted for under the GMM, two different CSMs and potentially also two different risk adjustments will need to be recognised for the same group of contracts.
4.192In each of these circumstances, complexity and the operational burden for the insurer would increase if there were further RITC transactions in subsequent years for the same contracts.
4.193Compared with current accounting practice, therefore, additional complexity and hence cost is expected to arise for relevant entities, both in scenarios in which a corporate member increases its participation in a syndicate and in scenarios in which its participation declines or ceases.
4.194However, we are aware of only four UK listed insurance companies with Lloyd's operations that produce group accounts using IFRS. Three of these companies responded to our preparer survey. While all three reported in the survey that they expected ongoing costs to increase under IFRS 17, only one referred specifically to RITC in that context. That respondent also provided the only quantification of the related expected annual cost increase: £1.1m in total (i.e. not just for RITC accounting), equal to approximately 1% of annual operating costs. These costs are factored into the overall cost benefit assessment in this Section 4.
4.195Stakeholders acknowledge that, based on activity in recent years, the accounting issues arising from the application of IFRS 17 to RITC contracts were not material to UK IFRS reporters. While such issues could potentially become more significant in future, based on the above analysis, it seems unlikely that the application of IFRS 17 to RITC transactions in the UK would have a significant impact on the UK insurance industry.
Potential wider impact on the Lloyd's of London market
4.196Stakeholders have the following key concerns:
- Market efficiency: RITC is considered an effective method of transferring liabilities and corresponding assets and ensures low barriers to market entry and exit. If exiting the market were made significantly more difficult, this could damage the attractiveness of the Lloyd's market.
- Competition: IFRS reporters could be at a disadvantage to corporate members reporting using a different GAAP that permits less complex accounting.
- Availability of data: the necessary data to enable exiting members to continue to account for the original insurance contract liabilities would not be available to members exiting the syndicate entirely given current Lloyd's market practices. Data required for the ongoing accounting is currently provided only to the reinsuring members.
4.197We understand that alternatives to the current RITC mechanism would include novation of liabilities or Part VII transfers but that both alternatives would require considerably more time and resources on behalf of the Lloyds members to achieve.
4.198The estimated annual gross written premiums (GWP) of the total UK insurance market amounts to £264bn, of which £160bn, or 60%, relates to UK insurance companies applying IFRS (for sources, see paragraphs 4.5 – 4.17 above).
4.199The Lloyd's market accounted for £35.5bn of GWP in 2020 (see paragraph 4.20 above). However, this amount includes business included in the accounts of non-UK companies and companies not applying IFRS. The proportion accounted for by non-UK business is unclear but is estimated to comprise a significant proportion of the total Lloyd's market.
4.200The four UK listed companies participated in 16[^147] of the 76 syndicates active at Lloyd's. We estimate that in 2020 these groups accounted for between £5.5bn and £6bn of gross written premiums (GWP) at Lloyd's, or between 15% and 17% of the aggregate GWP of the Lloyd's market.[^148] Some of this business is transacted through fully aligned syndicates (i.e. where the member has a 100% share), so is unlikely to be significantly affected in the short term by the application of IFRS 17.
4.201Preliminary information from Lloyd's indicates that as at 31 December 2020 there were five or six third-party RITC transactions[^149], involving gross reserves of approximately £1.8bn. These transactions did not involve current UK IFRS reporters. We understand from Lloyd's that there are at least five syndicates currently dedicated to acquiring legacy/run-off business through RITC transactions.
4.202All members participating in a syndicate need to receive sufficient data to enable the preparation of IFRS accounts, irrespective of the existence of RITC transactions. The additional administrative burden on application of IFRS 17 appears to arise primarily from the need to widen the distribution of the information to prior members who may have transferred their participation. We are not aware of any fundamental barrier to making the data available to those members in future, although the lack of historical data is expected to prevent retrospective application of IFRS 17's requirements on transition.
4.203As previously noted, non-UK entities also participate extensively in Lloyd's syndicates, including entities that apply IFRS and that will be adopting IFRS 17 once it becomes effective.[^150] Any UK-only modification of the standard or other unilateral step is therefore unlikely to provide an effective solution to concerns over the impact of IFRS 17 on the Lloyd's market.
4.204On the basis of the analysis above, while recognising the additional operational burden likely to result from the application of IFRS 17 to RITC transactions compared with current accounting practice, it seems unlikely that in this respect IFRS 17 will have a significant adverse impact on the UK insurance industry or wider UK economy.
Products and pricing – other feedback
4.205Third party studies also point towards a potential impact of IFRS 17 on product offering and pricing. For example, surveys by Deloitte and EFRAG concluded that IFRS 17 is likely to have some impact on product mix and pricing[^151].
4.206While users expect some changes to product offering and pricing arising from implementation of IFRS 17, insurance companies generally expect such impact to be negligible except in the case of annuity business. Some 80% of the respondents to the Preparer survey believed that IFRS 17 will have a negligible impact on product design and pricing, 13% thought it might have a moderate impact, and only 7% (one respondent) thought it might have a significant impact[^152]. Respondents who believe the impact will be negligible stated that it is "unlikely that a financial reporting standard will change the product design", and that "the economics are not impacted”.
4.207The evidence we collected is consistent with that gathered within the EU. For example, the European Insurance and Occupational Pensions Authority (ΕΙΟΡΑ) published a report in 2018 suggesting that IFRS 17 would be akin to a regulatory intervention that would not alter the economics of the insurance business[^153]. Similarly, the EFRAG Economic Study pointed out that "according to the majority of industry stakeholders interviewed, financial reporting does not play a big role in product mix and pricing", while capital requirements and regulation do. Finally, evidence collected by EFRAG in their stakeholder engagement suggested that some changes to product offering/pricing might be expected, but that these were minor and it would be difficult to predict and quantify their direction.
Products and pricing – summary
4.208Our current analysis indicates a low magnitude of changes to product offering and pricing in the UK arising as a result of implementation of IFRS 17, and the overall impact to be insignificant when compared with the overall insurance business in the UK.
4.209One potential impact of the implementation of IFRS 17 may be a generalised increase in premiums as more onerous contracts are recognised in the accounting and insurance companies try to enhance the profitability of such contracts. However, we believe that another more probable response is that insurance companies wishing to improve the profitability of their contracts will look to enhance their initial screening processes to better reflect the underlying risks in their contract offerings or increase premiums for risky contracts only[^154].
4.210Regarding annuity business, our conclusion is that the impact is more likely to be dependent on the precise CSM allocation methodologies applied than on the requirements of the standard itself. However, it seems unlikely that the change in financial reporting caused by IFRS 17 will have a direct and adverse impact on UK annuity business.
4.211Given the scale of the relevant listed insurance groups, our analysis of the impact of IFRS 17 on with-profits business indicates that the treatment under IFRS 17 of with-profits inherited estates, or the accelerated profit recognition of with-profits business compared with current practice, are unlikely to have a significant adverse effect on the UK insurance industry.
4.212In the main, the aspects of the standard that stakeholders have identified as likely to affect product offering or pricing are intended to better reflect the underlying economics of the insurance business (see Section 2). The changes will arguably result in better economic performance by insurance companies and enhanced capital allocation. There is little evidence to indicate that such changes may lead to an adverse effect on the UK economy, including on economic growth.
Effects on competitive landscape of UK insurance industry
4.213We have identified the following ways in which IFRS 17 may influence competition in the insurance sector:
- In the UK, the significant implementation costs and increased transparency of financial position and profitability associated with IFRS 17 may give a competitive advantage to companies not required to use IFRS 17.
- At an international level, the standard might encourage competition among multinational companies. In addition, insurers in jurisdictions that adopt the standard with carve-outs (as the EU is expected to do) may enjoy a competitive advantage (through reduced implementation costs or reduced transparency) over companies from jurisdictions where the standard is adopted in full.
- IFRS 17 might affect mergers and acquisitions (M&A) in the industry.
Competition in the UK from insurers not required to apply IFRS 17
4.214As explained in detail above (paragraphs 4.68 – 4.91), companies applying IFRS 17 will incur significant implementation costs and, potentially, marginally increased ongoing costs. In addition, IFRS 17 is expected to result in enhanced reporting transparency, in particular in relation to onerous contracts (see Section 2 and paragraph 4.49 above). Entities not applying IFRS 17 will not incur the additional costs associated with implementation of the standard and might retain more flexibility in their product offering and pricing (see paragraphs 4.145 – 4.152 above), giving those companies a competitive advantage. These asymmetries may lead to differences in products, pricing or services offered by the two different types of companies.
4.215We have considered whether IFRS 17 might adversely affect the competitive position of UK insurers applying IFRS 17 compared with insurers not required to apply IFRS 17, mainly unlisted UK insurers[^155]. Several factors indicate that any such adverse effect is unlikely to be significant.
- The cost of implementing IFRS 17, while significant in absolute terms, is not expected to be very significant in relative terms (see paragraph 4.70 above). In addition, the primary cost impact relates to initial implementation rather than ongoing costs, so represent a one-time impact.
- The 60 UK insurance companies applying IFRS account for roughly 60% of gross written premiums in the UK (see paragraph 4.18 above). The remaining 40% of revenues are dispersed among more than 150 companies using UK GAAP.
- Some of the largest unlisted insurance companies already apply IFRS voluntarily and have not indicated that they intend to revert to UK GAAP.
4.216In an industry in which scale can provide a competitive advantage, these potential advantages of not applying IFRS 17 are unlikely to prove decisive. The impact of applying IFRS 17 on competition within the UK market is therefore not likely to be significant.
4.217This view is supported by other evidence we obtained:
- The Economic Report noted that: "the general impression gained from insurer interviews was that IFRS 17 will not affect the competitiveness of UK insurers materially. While there were administrative costs associated with the change that were significant for the units within insurers responsible for providing financial reporting materials, these costs spread out across all the policies sold were unlikely to materially affect costs and therefore competitiveness."
- Most respondents (67%) to the Preparer survey either perceived the competitive impacts from insurers not required to apply IFRS 17 as negligible or had yet to fully assess the impact on their competitiveness. Out of 16 respondents, only one expected a significant impact on competition (but did not provide any rationale) and four a 'moderate' impact.
- Most respondents to the User survey did not perceive any significant domestic or international disadvantages to UK insurers from applying IFRS 17.
- Participants at the User roundtable noted that IFRS 17 should create no significant disadvantages to UK insurers either domestically or internationally.
4.218In conclusion, based on the evidence collected we do not expect IFRS 17 to alter domestic competition equilibrium.
International competition
4.219The IASB asserted that the application of IFRS 17 is expected to reduce costs for international businesses, and by implication make them relatively more competitive, as they may be able to exploit synergies with other jurisdictions where IFRS 17 will be applied. This is because "insurance companies with
operations in multiple jurisdictions are expected to reduce costs by applying a globally consistent model for their insurance contracts" [^156].
4.220This may help UK multinational insurance companies to enhance their competitiveness and consolidate their positions abroad, leading to positive effects on the UK economy.
4.221The Economic Report noted that "for pan-European businesses IFRS 17 would increase synergies with European offices. This might also make the UK market more attractive for insurers based in jurisdictions which adopt IFRS 17.”
4.222While this might be seen by individual UK insurers as a challenge, enhanced competition from international companies would likely benefit the UK economy as a whole, for example in terms of more affordable premiums for policyholders or an enhanced variety of products. Currently, however, there is no evidence to suggest any potential effect is likely to be significant.
EU carve out
4.223In November 2021 the European Commission adopted IFRS 17 including an optional exemption from the standard's annual cohorts requirement for intergenerationally-mutualised and cash flow matched contracts (the 'carve out').
4.224The carve out would permit companies not to apply paragraph 22 of IFRS 17 [^157] to these contracts, described in the Regulation as:
- groups of insurance contracts with direct participation features and groups of investment contracts with discretionary participation features as defined in Appendix A to the Annex [^158] to this Regulation, and with cash flows that affect or are affected by cash flows to policyholders of other contracts as laid down in paragraphs B67 and B68 of Appendix B of that Annex;
- groups of insurance contracts that are managed across generations of contracts and that meet the conditions laid down in Article 77b of Directive 2009/138/EC and have been approved by supervisory authorities for the application of the matching adjustment."
4.225Such contracts comprise a majority of the life insurance markets in several EU jurisdictions [^159].
4.226The Regulation states that the European Commission should review the exemption by 31 December 2027, taking into account the IASB's post-implementation review of IFRS 17.
4.227The EU carve out is optional, so it will be possible for EU-listed entities – those registered in the EU as well as foreign registrants – to apply IFRS 17 as issued by the IASB. Informal feedback from some stakeholders indicates that insurance companies in some EU Member States are not likely to use the carve out option. However, some listed entities from EU Member States with large insurance businesses, including France, Spain and Italy, are currently expected to use the optional carve out. We have therefore considered the potential implications of an EU carve out for UK entities, should the UK adopt IFRS 17 as issued.
4.228No UK insurance entities have listings on an exchange in the EEA, and we are aware of only one EU-listed insurance group which also has a UK listing [^160].
4.229Operational factors such as cost and complexity may affect groups operating across the EU and the UK differently:
- UK-based groups with operations in the EU: based on stakeholder feedback, UK life businesses have only limited operations in the EU. The accounting needs of any EU subsidiaries would depend on the financial reporting requirements in the relevant jurisdiction, but it is likely that such subsidiaries would need to prepare local GAAP accounts. They are currently reporting under two different accounting frameworks so are unlikely to be significantly affected by a difference between UK and EU-adopted IFRS.
- EU-based groups with operations in the UK: UK subsidiaries [^161] of EU listed entities will be required to prepare UK entity accounts in accordance with UK law, i.e. applying either UK GAAP or UK-adopted IFRS. Should the subsidiary need to prepare accounts on a different basis for consolidation purposes, the subsidiary would incur additional implementation and ongoing costs. However, based on our analysis there are few UK subsidiaries of EU listed parents with significant life business, and those parent companies may not elect to use the carve out.
4.230The EU carve out may have an impact on competition for capital. The carve out is expected to reduce the recognition of losses on onerous contracts (as defined under the standard), thereby potentially concealing economic losses and enhancing perceived performance. However, EU entities making use of the EU carve out would have to disclose the fact that they are using the carve out. Although the greater flexibility in financial reporting afforded by a carve out might appear an advantage from a preparer perspective, from the Users roundtable it emerged that investors are concerned that this will hamper comparability between insurance companies, as the carve-out will reduce transparency about onerous contracts. According to the participants at the roundtable, insurance companies choosing to use the carve out will need to justify their position. This user reaction could indicate that companies adopting the carve-out might become less attractive for investors.
4.231The stakeholder outreach and the Economic Report suggest that accounting differences such as a carve out for annual cohorts are unlikely to affect the competitiveness of insurers in the product market. Decisions regarding pricing and product offering are likely to be made at portfolio level and driven more by capital requirements and taxation. Although lower accounting costs might theoretically offer an advantage, in the context of the relevant insurers' total cost base this seems unlikely to have an impact.
4.232Overall, the proposed EU carve out is not expected to have significant consequences for competition for insurance companies in the UK or internationally. In competition for capital, an overall advantage is expected for UK insurance companies in the enhanced transparency afforded by applying IFRS 17 as issued by the IASB, making them more attractive to potential investors.
Impact on mergers and acquisitions (M&A)
4.233In general, M&A activity brings synergies and productivity enhancements in an industry. In recent years, a significant amount of M&A activity has taken place in the insurance sector, both globally and in the UK. Deloitte, for example, reported a total of nearly 40 M&A events in the European insurance sector, with a value of over EUR 22 billion, during 2017 [^162]. More recently, EY reported that in the UK during H1 2021 a total of 33 deals was observed, with a market value of £3.9 billion [^163]. We have therefore considered whether IFRS 17 might negatively impact M&A activity.
4.234Respondents to the Preparer survey had mixed views: a third considered IFRS 17 will have a negligible effect on M&As, while another third had not yet assessed its impact. 27% of respondents expected some moderate effects on M&A activity. Two insurance companies took the view that "IFRS 17 disclosures and consistency of reporting make it easier for potential acquirers to identify and evaluate takeover targets" and could potentially spur M&A activity. On the other hand, some insurers thought that IFRS 17 might deter M&A activity, especially in the non-life segment. One respondent noted that "IFRS 17 will encourage diversified product portfolios and be a potential barrier to entry. This may impact mergers and acquisitions in the insurance industry".
4.235Feedback from insurance companies during interviews suggested that:
- In the short run, IFRS 17 might result in fewer M&As due to transitional disruption (lack of familiarity with the new financial information). In the long-run M&A activity may be easier as valuation would be easier.
- IFRS 17 might make the acquisition of a life book less desirable for insurers not already applying the general measurement model (GMM), due to the costs involved in establishing GMM accounting systems. However, dividends, cash and solvency measurement will not change so the influence of the standard is expected to be limited in the longer term.
- One participant noted "the treatment of onerous contracts could... deter insurers subject to IFRS 17 from acquiring firms not subject to the standard" and another reported that "IFRS 17 may affect takeover prices in the short term, as acquiring firms have to think about the administrative costs with bringing the target firm's reporting systems into line with the new standard". However, this respondent "did not foresee it having a major bearing on firms' acquisition policies".
4.236The lack of a clear consensus in insurance companies' opinions indicates that the likely impact of IFRS 17 on M&As is difficult to predict. The fact that IFRS 17 is expected to enhance transparency and comparability of financial information produced by insurance companies, thus enhancing the ability to identify and value potential targets, might result in an increase in M&A activity and the resultant synergy and productivity enhancements. On the other hand, improved valuations resulting from such enhanced transparency may reduce the number of attractively priced targets.
4.237Overall, it is considered unlikely that IFRS 17 will have a significant impact on UK M&A activity. We expect no or at most a slightly positive impact on the UK economy in this regard.
Wider impacts of IFRS 17
Better governance processes
4.238The academic literature documents a positive relationship between financial reporting practices and governance [^164]. At a microeconomic level, standardised, comparable and clear reporting practices, which lead to a fair and transparent picture of a company's economic activity, are important in holding management accountable for its decisions. This reduces management's incentives to act in its own interest, encouraging the alignment of its interests to those of the company (the principal/agent problem) [^165].
4.239No corporate governance practice could fully align the principals' and the agents' interests in the absence of objective documentation of management's decisions. At a national level, however, a correlation between good accounting practices and stringent governance practices is generally observed, as good accounting practices support investors' ability to hold management accountable for their decisions.
4.240Given the expectation that IFRS 17 is expected to improve the quality of insurers' financial reporting (see paragraphs 4.30 – 4.60 above), we would anticipate a generalised improvement in governance processes among insurance companies following the application of IFRS 17 [^166].
4.241In interviews with insurance companies, views were mixed, but a few expressed the view that IFRS 17 might lead to improved internal governance processes:
- One company expected risk and audit committees to become more involved as more detailed data and analysis will be provided in external statements.
- Another company expected closer working across the actuarial and accounting teams arising from the need to harmonise the two functions. Implementation of IFRS 17 has helped increase mutual awareness, improved the organisational culture and reduced operational risk.
- Another company identified the possibility of enhancements to the processes in place for the production of accounts disclosures.
4.242Enhanced governance practices have broader consequences that are likely to positively affect the UK long term public good. The academic literature has found that better corporate governance practices are associated with enhanced institutional ownership, especially across borders, which in turns stimulates good corporate governance practices, triggering a virtuous cycle [^167].
Use of IFRS 17 by unlisted companies
4.243As noted in paragraph 4.12, UK legislation requires that IFRS is mandatory only for the consolidated accounts of companies listed on a regulated market, with other companies permitted to apply IFRS on a voluntary basis. Approximately 30 unlisted UK insurance entities currently voluntarily apply IFRS, but a greater number use UK GAAP. We have considered whether the adoption of IFRS 17 in the UK may affect unlisted insurers' choice of accounting framework.
4.244Unlisted companies decide to adopt IFRS for different reasons. Generally, privately held companies adopt IFRS with the view to obtaining better funding opportunities as well as a viable exit for private equity backers, for example when preparing for a future public equity listing [^168].
4.245Given the scale of one-off implementation costs that the application of IFRS 17 entails, it seems unlikely in the short term that privately held UK insurance companies will have a significant incentive to move from UK GAAP to IFRS 17. In the longer term, as understanding and experience with IFRS 17 increases and if, as expected, the standard becomes recognised as the basis for higher quality financial reporting, the perception of the balance of costs and benefits for privately held UK insurers may change.
4.246Another reason privately held insurance companies may be interested in moving to using IFRS and IFRS 17 is if they are currently applying FRS 101 Reduced Disclosure Framework under UK GAAP. FRS 101 requires the application of UK-adopted IFRS recognition and measurement requirements but with reduced disclosures. If IFRS 17 formed part of UK-adopted IFRS, however, UK insurance companies would no longer be permitted to apply FRS 101 [^169].This is because the definition of an entity qualifying for the reduced disclosure framework excludes entities that are required to comply with Schedule 3 of The Large and Medium-sized Companies and Groups (Accounts and Reports) Regulations 2008 (SI 2008/410) (i.e. insurance companies) and that have contracts within the scope of IFRS 17. Such companies would therefore need to choose between UK GAAP recognition and measurement and IFRS. When held by parents reporting under IFRS and preparing IFRS accounting information for consolidation purposes, the preparation of individual accounts using IFRS would avoid the need for such insurance companies to prepare two sets of accounting records. This scenario could affect unlisted insurers that are part of either UK or overseas groups.
4.247It is possible that some unlisted insurers already applying IFRS might revert to UK GAAP to avoid having to apply IFRS 17 and incur the associated costs with its implementation. Mutual insurance companies accounted for approximately £20 billion gross written premiums in 2016 [^170]. Two of the largest mutual insurers [^171] recently decided to move from IFRS to UK GAAP, raising the question of whether IFRS 17 was a determinant of their decision, and to what extent. In discussion, only one of the two identified IFRS 17 as a reason for moving away from IFRS. One mutual insurer's decision was based primarily on operational factors and it stated that there were no technical accounting issues that would have prevented them applying IFRS 17. In addition, the entity recognised they might have to move back to IFRS in the future. The other, however, considered that IFRS 17 would lead to less useful information given their mutual structure (particular concerns related to uncertainty over the relevance of IFRS 17's CSM and risk adjustment accounting requirements in a mutual context).
4.248As a general principle, the more businesses that apply IFRS the larger the benefits in terms of transparency and comparability for users of accounts as well as the wider market. The two mutual entities identified above represent less than 1% of UK gross written premiums. Further, we are not aware of any other insurers reverting to UK GAAP. It is therefore unlikely that an adverse effect on the UK economy will result from any insurance companies moving to UK GAAP to avoid implementation of IFRS 17.
Macroeconomic impact
Cost of capital and investment decisions by investors
4.249IFRS 17 aims to enhance the transparency of insurers' accounts and, as noted above, enhanced comparability of financial information within the sector is one of the main perceived benefits of the standard. The following paragraphs consider whether increased transparency and comparability might potentially result in greater confidence in the accounts and whether this might translate into benefits for insurance companies such as attracting capital from a wider range of investment sources at a lower cost.
4.250There is a substantial body of academic evidence that points to a negative relationship between the quality of financial disclosure and cost of capital. Diamond and Verrecchia (1991) demonstrate theoretically that better information arising from financial disclosure should translate into lower cost of capital. [^172] Since this contribution, empirical papers have largely confirmed this theoretical prediction. Lambert, Leuz and Verrecchia (2006) show that the quality of accounting information is associated with a reduction in the cost of capital. [^173] Barth, Konchitchki and Landsman (2013) focus specifically on the earnings-returns relationship, showing that firms with more transparent earnings are associated with a lower cost of capital. [^174] Daske, Hail, Leuz and Verdi (2013) show that voluntary IAS/IFRS adopters that seriously commit to the reporting standard (as opposed to 'label' adopters who do not fundamentally change their reporting) do enjoy better stock liquidity and lower cost of capital. [^175] [^176]
4.251Since IFRS 4 does not prescribe the measurement or presentation of insurance contracts but largely permits the continuation of existing local practices, the impact of the application of IFRS 17 by insurance companies would be comparable to the transition to IFRS Standards by other companies.
4.252To perform the evaluation, quantitative analysis of insurance company share price data was conducted to assess their cost of capital. To assess whether IFRS 17 might be associated with a reduction in the cost of capital, qualitative data was collected through stakeholder engagement and evidence from third-party studies.
4.253The following graph compares Weighted Average Cost of Capital (WACC) for life and non-life insurance companies listed in the UK. For illustrative purposes, the average WACC for FTSE 100 companies and for banks [^177] is also included. WACC is a commonly used cost of capital measure that takes into account both equity and debt cost of capital.
WACC – Insurance companies This line graph shows the Weighted Average Cost of Capital (WACC) for Banks, Life Insurance, Non-life insurance, and FTSE 100 from December 2015 to June
- The y-axis represents WACC values from 0 to 9. The x-axis represents dates from 1/12/15 to 1/6/21.
- Banks (light blue line) fluctuates between approximately 4% and 7%.
- Life Insurance (orange line) generally shows higher WACC, often between 5% and 8%.
- Non-life Insurance (grey line) typically has WACC values between 3% and 6%.
- FTSE 100 (dark blue line) shows a pattern similar to Banks, fluctuating between 3% and 7%. All lines show volatility with dips and peaks, especially around late 2019 to early
- Life Insurance generally maintains the highest WACC, followed by Banks/FTSE 100, and then Non-life Insurance.
Source: LSEG (for the list of companies), Thompson Reuters Eikon (for WACC). The period 2015 to 2021 was selected based on the availability of data.
4.254As evident from the graph, for the period considered, life insurance companies are characterised by a higher WACC than both the banking sector and the non-life insurance segment, with the difference in WACC between life insurance and banking companies averaging 0.6 percentage points over the period considered, and the difference in WACC between life and non-life insurance companies averaging 1.2 percentage points over the period considered. The non-life insurance segment has a WACC more comparable to that of the banking sector. The reasons for the differences in WACC are likely to relate to a variety of factors, including perhaps investors' current perception that life insurance company accounts lack transparency. The analysis suggests that life insurance companies are likely to benefit more than general insurance companies should IFRS 17 lead in the long term to a lower cost of capital for insurance companies, as some suggest (see stakeholder views from paragraph 4.263).
4.255We have also considered current indicators of market volatility. We calculated market betas by running a Carhart four factor model [^178] to estimate market betas for life insurance, non-life insurance and, for illustrative purposes, banking companies [^179]. Market betas are a measure of market volatility that tells whether the market excess returns of a portfolio over risk-free returns are less, equally or more volatile than the market excess returns. A beta higher (lower) than one in absolute terms indicates that a portfolio excess returns are more (less) volatile than the excess returns on the market. [^180] In addition, they are positively correlated with the equity cost of capital, i.e. a higher beta translates into a higher cost of equity for a given portfolio.
Carhart 4-factor model – beta estimates This line graph displays beta estimates from the Carhart 4-factor model for Banks, Life Insurance, and Non-life Insurance from January 2010 to September
- The y-axis ranges from -0.5 to 2.5, representing beta values. The x-axis shows monthly periods.
- Banks (light blue line) generally fluctuates between 0.5 and 2.0.
- Life Insurance (orange line) shows similar fluctuations to Banks, often between 0.5 and 2.0.
- Non-life Insurance (grey line) consistently shows lower beta values, mostly between 0 and 1.0, indicating less volatility.
The graph illustrates that Life Insurance and Banks exhibit higher and more volatile beta estimates compared to Non-life Insurance over the sample period.
Source: UKEB calculations based on data provided by the LSEG (for the list of companies), Thompson Reuters Eikon (for individual companies' EoD prices) and Tharyan (2018) (for the four factor model indicators: market returns minus risk free returns, HML, SMB, momentum). The estimate is performed for the 2010 to 2017 period because more recent data is currently not available.
4.256As evident from the graph, life insurance companies have similar betas to banking companies, and a higher beta than non-life insurance companies. Over the sample period, banking companies had an average beta equal to 1.14, life insurance companies had an average beta equal to 0.99 and non-life insurance companies had an average beta equal to 0.41. These results suggest that returns of life insurance companies move broadly in line with market conditions, while non-life insurance companies are less volatile. Therefore, the equity cost of capital for non-life insurance companies is expected to be lower than for life insurance companies.
4.257To cross-validate the results above, we considered the volatility as measured by the standard deviation of returns, an indicator of uncertainty strongly correlated with the equity cost of capital. We looked at the difference between life and non-life insurance companies and, as above, we compared these estimates with those for the banking sector and the FTSE 100 for illustrative purposes.
4.258The following chart reports daily volatility, calculated as the rolling standard deviations of daily returns over a 20-day period:
Stock price volatility This line graph illustrates stock price volatility for Banks, Life Insurance, Non-life Insurance, and FTSE 100 from April 2010 to April
- The y-axis shows volatility from 0 to 0.08, and the x-axis represents dates.
- Banks (light blue line) and Life Insurance (orange line) generally show similar levels of volatility, with several peaks, notably a significant one around early 2020 (likely corresponding to the COVID-19 market shock), reaching above 0.07.
- Non-life Insurance (grey line) consistently exhibits lower volatility, mostly below 0.03, and does not show the sharp peak observed in early 2020 for the other categories.
- FTSE 100 (dark blue line) also shows volatility comparable to Banks and Life Insurance, including the peak in early 2020.
The graph indicates that non-life insurance companies are less volatile than life insurance companies, banks, and the broader market represented by FTSE 100.
Source: UKEB calculations based on data provided by the LSEG (for the list of companies), Thompson Reuters Eikon (for individual companies' EoD prices).
4.259From the graph it appears that life insurance companies are characterised by overall levels of volatility comparable both with companies in the banking sector and the market as a whole (confirming the findings from the four-factor model estimate above), while non-life insurance companies face lower volatility levels.
4.260These analyses, taken together, further suggest that life insurance companies have the most to gain from the enhanced transparency and comparability in financial reporting expected from use of IFRS 17 in terms of equity cost of capital, general cost of capital (as measured by the WACC) and stock market volatility.
4.261The Economic Report suggested "that the potential impacts of IFRS 17 on the cost of capital for insurers could differ", with "the transparency implied by the new reporting standards [likely to] benefit life insurers more, since existing problems with understanding financial reports in the sector are more pronounced in that sector given the longer duration of policies in this sector." The study also noted that gains for UK insurance companies were anticipated to be lower than for companies in some other jurisdictions as the UK insurance industry was already considered relatively transparent.
4.262The Economic Report also made the point that in the short run investors (and in particular generalist investors) might need time to adapt to the financial information produced as a result of implementation of the new standard.
4.263Feedback from both preparers and users reflects those mixed views. Some believe that in the short-term uncertainty about how to interpret insurance company results might temporarily push the cost of capital up. In the long term some stakeholders expect IFRS 17 to be associated with a reduction in the cost of capital for insurance companies.
4.264Most respondents to the Preparer survey did not expect IFRS 17 to result in a decrease in the cost of capital for insurance companies. The investor relations department of one UK insurance company confirmed during outreach that they didn't expect the cost of capital to go down as a result of IFRS 17, as they perceived that generalist investors would struggle to understand the industry.
4.265Half of the respondents to the User survey did not anticipate IFRS 17 to affect the cost of capital of insurance companies, as they believe this is largely driven by Solvency II and economic fundamentals. 30% believe that the cost of capital will go up in the short-run due to a lack of investor familiarity, and only 15% expect the cost of capital to go down in the long-run due to increased transparency. 65% of the respondents agree that changes to the cost of capital, if present, will mostly affect the life insurance segment.
4.266According to participants in the User roundtable, IFRS 17 created a 'toolkit' which users could use to perform better analyses of insurance companies. However, they noted that generalist investors might still struggle to understand insurers' financials due to the inherently specialised nature of insurance business. Users suggested that educational materials and early engagement with insurance companies will be important to help users interpret the accounts correctly upon first use of IFRS 17.
4.267Participants in the User roundtable also noted that IFRS 17 will provide greater insight into the underlying economics and provide an additional lens through which to view insurers. This may result in a change in the cost of capital. However, there was no consensus on the direction of the change.
4.268In the long run, we anticipate enhanced transparency and comparability to have a small positive or neutral effect on the cost of capital for UK insurance companies. While some consider that the cost of capital for insurance companies might go up in the short term, evidence suggests that insurance companies are planning mitigating steps such as educating and actively engaging with investors, thus limiting any short-term volatility and decreasing uncertainty on transition. This was confirmed during our outreach with insurance companies in September 2021 – they indicated that they are actively educating internal stakeholders and are expecting (and preparing) to engage with users of financial reports during 2022, mostly during the second half of the year.
4.269On balance, and based on the quantitative analyses and the stakeholder feedback and work by third-party organisations [^181], IFRS 17 is not expected to have an adverse effect on the economy of the UK in relation to cost of capital and access to finance for insurance companies.
Investment decisions by insurance companies
4.270As set out above (paragraph 4.7), UK insurers manage just over £2trn of investment assets. We have therefore considered whether IFRS 17 might affect the investment behaviour of insurance companies in relation to asset allocation. The likely impact of IFRS 17 on investment and hedging strategies was assessed using third-party studies and qualitative data collected through stakeholder engagement.
4.271The Economic Report supports the EFRAG study conclusion that the joint application of IFRS 9 and IFRS 17 is likely to have a limited impact on UK insurance companies, as current value accounting is already their predominant practice for investment assets [^182].
4.27280% of respondents to the Preparer survey expected IFRS 17 to have a negligible impact on investment strategies, which in their view were driven primarily by the need to achieve satisfactory returns for policyholders while maintaining regulatory compliance. One comment summarises their position as follows: "Our investment strategy is to seek to secure the highest total return whilst maintaining an acceptable overall risk level, having regard to the currency, nature and outstanding duration of the liabilities. This is not expected to change significantly as a result of IFRS 17".
4.273The Preparer survey also asked whether hedging strategies were likely to change as a result of IFRS 17. Most insurance companies considered that hedging strategies were unlikely to be affected, with 60% of respondents expecting IFRS 17 to have a negligible impact. Instead, regulatory compliance was cited as more important, with four insurers mentioning Solvency II or solvency considerations as the main drivers for hedging strategies [^183].
4.274Based on this evidence, IFRS 17 is not expected to have a significant effect on investment or hedging strategies.
Impact on credit ratings
4.275Feedback from credit rating agencies indicated that IFRS 17 is not expected to have a significant impact on their assessment of insurance companies. One credit rating agency noted that they anticipate the standard will provide better insight into insurance companies' performance and financial position and make the economics more visible and therefore understandable, though they do not expect ratings changes as a direct result of IFRS 17.
4.276Similar conclusions were drawn by EFRAG: "In terms of rating, two major rating agencies (FITCH and S&P) commented that IFRS 17 is unlikely to directly affect insurers' ratings because the economic substance of their balance sheets will not change" [^184].
Financial stability
4.277Insurance companies are large and integrated financial institutions that could pose challenges to national, supranational (i.e. European) and global financial stability in case of a default [^185]. The Financial Stability Board (FSB) identified nine insurers as global systemically important financial institutions [^186]. Of those, two (Aviva and Prudential) are UK listed insurers.
4.278As set out in paragraphs 4.30 – 4.60, IFRS 17 is expected to improve the quality of financial reporting of insurers. By enhancing transparency and comparability, and in particular by requiring the prompt recognition of losses from onerous contracts and reducing the possibility of day 1 profit recognition, IFRS 17 should better reflect the profitability and financial position of insurance companies. This in turn should promote the efficient allocation of capital and the ability of investors to hold management to account for their stewardship. Therefore, over the long term, IFRS 17 is expected on balance to have a positive impact on UK financial stability.
4.279The evidence on the topic supports this view. For example, EIOPA draws the conclusion that "IFRS 17 is expected to reflect volatility in the balance sheet of insurers through a current valuation based on current inputs from financial markets... That is a reflection of economic reality and to the extent that economic reality is reflected, the impact on financial stability is nevertheless positive, as market participants do expect changes in the valuation and equity when economic reality changes" [^187].
4.280The Bank of International Settlements (BIS) surveyed 20 insurance supervisors globally (including the PRA [^188]) to assess their view on the role of IFRS 17 in enhancing financial stability, as well as the wider impact of the standard on the insurance business. Most of the surveyed jurisdictions indicated that they expected IFRS 17 to contribute positively to financial stability. In addition, IFRS 17 disclosure requirements are expected to provide new sets of information that will be useful for supervisory monitoring of insurance companies.
4.281According to the same report, however, few of the jurisdictions plan to adopt IFRS 17 for regulatory purposes. In the UK, the PRA does not plan to use IFRS 17 for regulatory purposes [^189], [^190].
4.282Overall, IFRS 17 is likely to improve the ability of users of insurance company accounts to better assess insurers' financial position. This may lead to less volatility in insurance companies' stock prices in the long run (especially for life insurance companies). Additionally, given the size of the insurance sector's total market capitalisation in the UK, the reduced volatility is likely to contribute to enhancing the market's stability overall. IFRS 17 is therefore expected to have a neutral to positive effect on financial stability.
Tax revenues
4.283Insurance companies are an important contributor to UK tax revenues. It is therefore important to assess whether IFRS 17 is likely to impact those revenue streams. To evaluate if it is likely to be the case, this report uses quantitative data on the insurance business, and qualitative data collected through stakeholder engagement.
4.284According to the City of London and PwC, the financial services industry as a whole was the source of £75.6 billion in tax revenues for 2020, of which ABI members contributed £16.1 billion [^191].
4.285However, not all of this tax revenue will be affected by IFRS 17. For example, £6 to £7 billion can be attributed to Insurance Premium Tax (IPT), [^192] an indirect tax on insurance revenues that affects non-life insurers (and, according to ABI estimates,
accounts for nearly 60% of their tax contribution). Further, a proportion of the tax contribution from life insurers relates to tax deducted at source, of which, according to the ABI, nearly 40% can be attributed to Pay As You Earn (PAYE) taxes on annuities.
4.286IFRS 17 will only directly affect corporation tax payments. The starting point for the determination of corporation tax liabilities is the profit reported in the financial statements, so any changes in reported profits caused by IFRS 17 will impact corporation tax liabilities. IFRS 17 is expected to affect the reported profits of life insurance contracts more than those of general insurance contracts, resulting in a greater potential effect on the corporation tax payments of life insurance companies.
4.287However, as over the life of a contract the amount of profit will remain the same, the effect is not expected to be significant at a national level. In addition, the acceleration of profit recognition for some contracts is expected broadly to be offset by slower recognition of profit for other contracts. Furthermore, according to HMRC data, the corporation tax revenue attributable to life insurance companies amounted to £0.9 billion for fiscal year 2018-2019. By comparison, corporation tax attributable to the financial sector was over £11 billion. Corporation tax attributable to non-life insurance business was included in tax revenues attributable to the financial sector as a whole and was therefore not separately quantifiable. However, as the non-life industry is smaller than the life industry, corporation tax payments by non-life businesses are not expected to be significantly in excess of those from life businesses. As a consequence, IFRS 17 is expected to directly affect only a small proportion of the total tax contribution from the insurance sector in the UK.
4.288The transition to IFRS 17 is expected to result in significant one-off adjustments to UK insurance company equity balances. To the extent they relate to UK business, a significant proportion of these adjustments is expected to be subject to UK corporation tax. For the UK insurance industry as a whole, there could therefore be a one-off impact on tax payments from the sector on implementation of IFRS 17.
4.289This potential transitional impact on tax revenues has not yet been quantified. The UK government proposes to introduce regulations for insurance companies to spread the transitional impact of IFRS 17 for corporation tax purposes.
4.290Although IFRS 17 might have a significant impact on the tax liabilities of an individual insurance company in the short term, the standard is not expected to have a major effect at a national level. IFRS 17 directly affects only a relatively small proportion of the industry's total tax contribution which is unlikely to change significantly. As a consequence, it is not considered likely that IFRS 17's impact on tax revenues will have an adverse effect on the UK economy.
Economic growth
4.291The insurance sector is a significant part of the UK economy and insurance companies applying IFRS represent a majority of the revenues in the industry. As a result, it is important to consider whether the use of IFRS 17 may have an impact on economic growth.
4.292The supply of insurance products in the UK is not expected to decrease as a result of the use of the standard. In general, IFRS 17 is likely to have only a minor effect on product offering and pricing, the direction of which is difficult to predict at this stage. Insurance companies most likely to be affected by IFRS 17, annuity providers, confirmed they do not anticipate direct changes to product offering or pricing as a result of implementing IFRS 17. These companies envisage a potential impact on the prevalence of transfers of business between insurance companies, but this is dependent on the precise CSM allocation methodologies applied and, even if this effect materialises, it is not expected to impair economic growth.
4.293We have not found any evidence that the demand for insurance products will decline as a result of use of the standard.
4.294In absence of major anticipated changes to either the supply or demand of insurance products, the overall size of the industry should remain stable. No significant change in the overall level of investing activity by insurance companies is therefore expected (see also paragraphs 4.270 – 4.274 above).
4.295The transparency brought about by IFRS 17 is expected to have some positive long-term effects on the attractiveness of insurance companies to investors. This may in turn improve insurance companies' valuation on stock markets, reducing their cost of capital in the long-run and enhancing their access to capital markets. In addition, there might be positive effects on internal governance processes. International competition is expected to improve, as is the standing of UK insurance companies at the international level, all leading to likely positive effects on UK policyholders.
4.296Considering the points above, insurance companies are likely to be equally or more competitive in the long run. This is anticipated to have a neutral to positive effect on economic growth.
Consideration of the consequences of not adopting the standard
4.297In this section we consider the consequences for insurance companies, for users of their financial statements and for the wider UK economy if IFRS 17 as a whole is not adopted for use in the UK (the ‘non-adoption scenario’). We have assumed that IFRS 17 is or remains adopted in other jurisdictions, including, in the EU, with an optional carve out of the annual cohorts requirement for certain types of contracts (see paragraphs 4.223 – 4.232).
Users of insurance company accounts
4.298Paragraphs 4.30 – 4.60 set out the ways in which IFRS 17 is expected to result in improved financial reporting. Under the non-adoption scenario, the benefits that users of financial statements would be expected to gain from IFRS 17 would not be realised. Insurance companies would continue to apply IFRS 4 and users would therefore not benefit from more comparable and transparent financial reporting. Although users of insurance company accounts would avoid IFRS 17 familiarisation costs, as explained in paragraph 4.92 above, these are not expected to be significant.
Insurance companies
4.299In a non-adoption scenario, a potential outcome could be that UK and foreign capital markets funds would flow towards companies providing the more transparent financial reporting, those residing in jurisdictions that apply IFRS 17. However, the size and importance of the UK insurance sector, together with the fact that investors consider a plurality of information sources (not only financial statements) when making investment decisions, are likely to continue to play a key role in retaining investor interest and capital. Therefore, non-adoption of IFRS 17 is likely to have a small adverse long-term effect on the cost of capital for UK insurance companies.
4.300If foreign insurance companies using IFRS 17 were to benefit from more sources of capital and potentially from a lower cost of capital, this could in turn provide those companies with a competitive advantage over UK companies.
4.301From a cost perspective, a decision not to adopt IFRS 17 at this stage would enable insurance companies to terminate their IFRS 17 implementation programs and potentially avoid further expenditure. However, as evidenced in our assessment of the costs of applying IFRS 17 (paragraphs 4.68 – 4.91 above), UK insurance companies have long prepared for the transition to IFRS 17 and have already invested considerable resources in the expectation that the standard will be adopted for use in the UK. In particular, implementation of the systems changes needed to provide the data required by IFRS 17 have been underway for some time. A non-adoption scenario would mean that a large proportion of the implementation costs incurred by insurance companies so far would be ‘lost’. Further, the wider potential benefits to insurance companies of applying IFRS 17 128 would not be realised.
4.302Overall, therefore, non-adoption of IFRS 17 would be a potentially negative outcome from the perspective of the UK long term public good:
- Investors and other users of insurance company financial statements would not benefit from more comparable and transparent financial reporting.
- In the long term, capital investment might flow from UK insurance companies to other sectors or insurance companies residing in IFRS 17-adopting jurisdictions. As a result, UK insurance companies would not benefit from more abundant, more differentiated and potentially cheaper capital in the long term. This could potentially give insurance companies from IFRS 17-adopting jurisdictions a competitive advantage over UK insurance companies.
- UK insurance companies would lose much of the resource already invested to ensure compliance with IFRS 17 as well as failing to realise the wider potential benefits of applying the standard.
4.303These considerations suggest that non-adoption of IFRS 17 for use in the UK would not be likely to be conducive to the UK long term public good.
Overall conclusion on UK long term public good
Quality of financial reporting
4.304Overall, implementing IFRS 17 will lead to improvements in the quality of financial reporting for insurance contracts by specifying a comprehensive set of recognition, measurement, presentation and disclosure requirements for the first time. This will lead to financial reporting that is more useful to investors and other users of accounts, providing information that is consistent and comparable and that faithfully reflects the economic substance of the contracts in scope.
4.305Key aspects of IFRS 17 that are expected to lead to improvements in financial reporting include the following:
- improved scope;
- more transparent liability measurement;
- consistent profit recognition;
- more consistent and clearer presentation of items in the primary financial statements; and
- extensive specified disclosures.
4.306Since IFRS 17 represents a fundamental change in the accounting for insurance contracts, transition to the new standard may be complex in some cases. It is likely to take time for preparers and users of insurance company accounts to become familiar with the new requirements, including with the presentation of the primary statements. However, our assessment indicates that the longer-term benefits are expected to outweigh these complexities. As one user commented to us:
"There will be a lot of headaches on day one but it's a price worth paying if the market gravitates to a consistent approach.”
Costs and benefits
4.307Participants in the Preparer survey anticipate aggregate IFRS 17 implementation costs of £783m. These are one-off costs related to the implementation of IFRS 17. Extrapolating these costs for all UK IFRS reporters gives a total implementation cost of approximately £1.18 billion. Some £0.5 billion of this total had been incurred by 30 June 2020 and significant further cost has been incurred since then.
4.308While these costs are significant when taken in isolation, most participants in the UKEB Preparer survey advised that they represent 1% or less of their average annual Gross Written Premiums over the last 5 years.
4.309At the time of the survey and again in recent follow up interviews insurance companies advised they had yet to determine the impact of IFRS 17 on ongoing costs. However, most anticipated only a minor impact due to the expectation that any additional costs would at least partially be offset by cost savings from operational efficiencies.
4.310Users of insurance company accounts, including regulators, are not expected to incur significant additional cost because of IFRS 17. While auditors may bear some of the additional cost themselves, preparers expect a significant proportion to be passed on to them due to the increased complexity of audits.
4.311Users of insurance company accounts are the main beneficiaries of the enhanced transparency and comparability expected to result from IFRS 17. This was reflected in our outreach with investors and other users of accounts. Most users surveyed were optimistic that the changes introduced by IFRS 17 would improve comparability between insurance companies and increase transparency in insurance company accounts. They expected to be able to make a more complete assessment of the overall benefits following more detailed engagement with insurance companies and review of companies' initial accounts prepared under IFRS 17.
4.312One consequence of enhanced transparency is the potential impact on cost of capital for insurance companies. Although there was no clear consensus on this, in the longer term insurance companies may potentially benefit from lower cost of capital and improved access to capital. Given the scale of insurance company balance sheets, even a small reduction in cost of debt capital could result in significant gains to insurance companies over the long term.
4.313Some respondents to the Preparer survey also recognised that enhanced transparency and consistency in financial reporting would provide them with greater insight into competitor performance. Other respondents, who had undertaken a wider transformation approach to compliance, also expected to realise ongoing indirect benefits from improvements in systems and data management and from process efficiencies. These benefits had not been quantified.
4.314Auditors are expected to benefit from having a more comprehensive set of accounting requirements to audit against, and from a higher level of consistency in insurance company accounting practices. As the standard aims to enhance transparency and comparability in financial reporting, the implementation of IFRS 17 should also be beneficial for regulators.
4.315Overall, therefore, the application of IFRS 17 is not expected to result in significant additional net ongoing costs for stakeholders in the insurance sector.
Effect on the economy of the UK
4.316IFRS 17 may have some effects on insurance companies' product mix or pricing, though changes are not anticipated to be substantial or detrimental for UK policy holders. Providers of annuities, the product most likely to be influenced by the use of IFRS 17 according to stakeholder feedback, have indicated that they do not plan to change their product offering as a direct result of the standard. However, they highlight that the impact on annuity business is likely to depend on the CSM allocation method applied.
4.317IFRS 17 is not expected to adversely affect competition between insurance companies applying the standard and those that do not apply it. The cost advantage arising from not applying IFRS 17 is unlikely to give the smaller insurance companies that do not use IFRS a competitive edge over the typically larger companies applying IFRS.
4.318IFRS 17 may increase competition at an international level, as large global groups may exploit synergies post-adoption. This is likely to have a positive impact on the UK economy. The EU carve out is not expected to have significant consequences for competition for customers and may provide an advantage for UK companies in the competition for capital if they apply IFRS 17 as issued by the IASB. There is no clear consensus on the expected impact of IFRS 17 on M&A activity. Overall, however, it is considered unlikely that IFRS 17 will have a significant impact on UK M&A activity. We expect no or a slightly positive impact on the UK economy in this regard.
4.319IFRS 17 is not expected to lead to any major insurance companies changing their accounting framework to UK GAAP. IFRS 17 could lead to some insurance companies, particularly those currently applying FRS 101, switching to IFRS to avoid the use of multiple GAAPs within a group. The use of IFRS 17 may also improve internal governance processes.
4.320IFRS 17 is expected to have a neutral to positive effect on the cost of capital of insurance companies, as the enhanced transparency and comparability of insurance company accounts expected from use of IFRS 17 is likely to be positively evaluated by investors in the long term. If changes occur, life insurance companies are expected to benefit most from any potential reductions in the cost of capital.
4.321IFRS 17 is not expected to have any significant negative effect on the investment or hedging strategies of insurance companies.
4.322IFRS 17 is expected to have a neutral to positive effect on financial stability. The expected improvement in the transparency and comparability of insurance company accounts should promote the efficient allocation of capital and the ability of investors to hold management to account. In addition, IFRS 17 is expected to provide new information that will be useful for supervisory monitoring and should allow users of accounts to better evaluate the financial position of insurance companies, leading to greater market confidence and a potential reduction in share price volatility in the long run.
4.323The standard is expected to have a minor, non-adverse effect on tax revenues over the medium and long term.
4.324Our assessment did not find evidence that IFRS 17 will lead to significant changes in either demand or supply of insurance products, or in the overall level of investing activity by insurance companies. Further, the additional transparency brought by the standard may have a beneficial impact on capital markets for insurance companies and on competition for UK policyholders. Overall, therefore, IFRS 17 is expected to have a neutral to positive effect on economic growth.
4.325Not adopting IFRS 17 would be likely to have a negative effect on the UK economy. Users of accounts would not be able to benefit from the enhanced transparency and comparability expected to be achieved under IFRS 17. In turn, UK insurance companies would not benefit from any potential reduction in their cost of capital in the long run and would not benefit from improved access to capital markets compared with under the current accounting regime. This would likely put UK insurance companies at a relative disadvantage compared with IFRS-adopting companies in other jurisdictions.
4.326The use of IFRS 17 is therefore not expected to have an adverse effect on the UK economy, including on economic growth.
Overall conclusion on UK long term public good
4.327Overall, therefore, and based on the above assessments, the use of IFRS 17 is likely to be conducive to the long term public good in the United Kingdom.
5 True and fair view assessment
Legislative basis and our approach to the assessment
5.1The UKEB is required to consider whether an international accounting standard being assessed for use in the UK meets certain legislative criteria set out in Regulation 7 (1) of SI 2019/685. The first criterion set out in that regulation requires that an international accounting standard can be adopted only if:
"the standard is not contrary to either of the following principles -
- an undertaking's accounts must give a true and fair view of the undertaking's assets, liabilities, financial position and profit or loss;
- consolidated accounts must give a true and fair view of the assets, liabilities, financial position and profit or loss of the undertakings included in the accounts taken as a whole, so far as concerns members of the undertaking; [....]"129
5.2In this section of the ECA we consider whether IFRS 17 meets this endorsement criterion. For the sake of brevity, we refer to our assessment against this endorsement criterion as ‘the true and fair view assessment’ and to the principles set out in Regulation 7 (1) (a) as the ‘true and fair view principle’. However, these abbreviated expressions do not imply that our assessment has considered anything other than the full terms of the endorsement criterion set out above.
5.3The duty of the UKEB under Regulation 7(1)(a) is to determine generically, before a standard is applied to a set of accounts, whether that standard is ‘not contrary’ to the true and fair view principle. In other words, it is an ex-ante assessment. We have therefore considered whether IFRS 17 contains any requirement that would prevent accounts prepared using the standard from giving a true and fair view.
5.4Our approach is to determine whether IFRS 17 is not contrary to the true and fair view principle in respect of any of the specific items identified in Regulation 7(1)(a) (namely, the assets, liabilities, financial position and profit or loss) in the context of the preparation of the accounts as a whole. A holistic approach has been taken to this assessment, considering the impact of IFRS 17 taken as a whole, including the disclosures it requires and its interaction with other UK-adopted international accounting standards.
5.5For the purposes of our assessment, we consider the requirement in IAS 1 for financial statements to "present fairly the financial position, financial performance and cash flows of an entity" 130 to be equivalent to the Companies Act 2006 requirement for accounts to give a true and fair view.
5.6Our assessment is separate from the duty of directors under section 393(1) of the Companies Act 2006, which requires directors to be satisfied that a specific set of accounts gives a true and fair view of an undertaking's or group's assets, liabilities, financial position and profit or loss.
Interaction with other UK-adopted international accounting standards
5.7We have considered whether any requirement of IFRS 17 would necessarily create distortions in its interaction with other UK-adopted international accounting standards. As insurance companies typically have significant holdings of financial assets, our assessment included consideration of whether distortions would necessarily arise from the interaction of IFRS 17 with the requirements in IFRS 9 Financial Instruments.
5.8IFRS 17 requires the measurement of insurance obligations at a current value, consistent with the requirements for comparable financial instruments. Most UK insurers account for the majority of their financial assets at fair value through profit or loss. Accounting mismatches arising from the application of IFRS 17 and IFRS 9 (which are not a feature of the underlying economics but instead originate from the accounting requirements) are therefore not expected to be significant or widespread. Where any such accounting mismatches do arise, IFRS 17 and IFRS 9 together provide accounting tools that enable companies to mitigate their effect. Such tools include the risk mitigation option for contracts to which the variable fee approach applies 131 and the other comprehensive income option for insurance finance income and expense in IFRS 17 132, and hedge accounting and the fair value option in IFRS 9. However, where accounting mismatches remain, and where these are significant to an entity's accounts, companies may need to make additional disclosures to explain their effect, in accordance with the requirements of IFRS 17.
5.9Feedback from stakeholders and our own assessments of significant technical accounting issues in Section 3 above and in Appendix B have not indicated that any distortions arising from the interaction of IFRS 17 with other UK-adopted international accounting standards are a major concern for UK stakeholders.
Assessment
5.10Consultation feedback on the DECA indicated that stakeholders generally agreed with the UKEB's tentative conclusion that IFRS 17 was not contrary to the true and fair view principle. Only one respondent who addressed this specific question disagreed with this tentative conclusion, on the basis of their concerns in respect of the application of the standard to annuities.
5.11Section 3 of this ECA concludes that IFRS 17 meets the technical accounting criteria. The technical accounting criteria refer to reliability which includes the notion of faithful representation of the economic substance of transactions and events (see Section 1 above). The technical accounting criteria assessment therefore further underpins the overall true and fair view assessment.
5.12Our assessment has not identified any requirement of IFRS 17 that would prevent individual accounts prepared using the standard from giving a true and fair view of the entity's assets, liabilities, financial position and profit or loss.
5.13SI 2019/685 requires an assessment of whether IFRS 17 is not contrary to the true and fair view principle for both individual and consolidated accounts. While feedback from some stakeholders has indicated that preparation of consolidated accounts may in some cases be more complex under IFRS 17, we have not identified any reason why the IFRS 17 true and fair view assessment should conclude differently for consolidated accounts.
Overall conclusion
5.14Overall, therefore, we conclude that IFRS 17 is not contrary to the true and fair view principle set out in Regulation 7 (1) (a) of SI 2019/685.
Appendix A - Glossary
| Term | Description |
|---|---|
| ABI | Association of British Insurers |
| AIM | Alternative Investment Market. A sub-market of the London Stock Exchange that is not a ‘regulated market’ |
| ASB | Accounting Standards Board in the UK effective until 2012, when it was replaced by the Financial Reporting Council |
| AUM | Assets under management |
| BEIS | Department for Business, Energy and Industrial Strategy |
| BIS | Bank for International Settlements |
| BoE | Bank of England |
| BPA | Bulk purchase annuities |
| CSM | Contractual Service Margin |
| ECA | Endorsement Criteria Assessment |
| Economic Report | the economic report on the impact of IFRS 17 prepared by Europe Economics and finalised in November 2020 |
| EEA | European Economic Area |
| EFRAG | European Financial Reporting Advisory Group |
| EFRAG Economic Study | the economic study prepared for EFRAG by LE Europe and VVA Group, updated and finalised in June 2020 |
| EIOPA | European Insurance and Occupational Pensions Authority |
| EU | European Union |
| FCA | the Financial Conduct Authority |
| FRA | the fully retrospective approach to transition to IFRS 17 |
| FRC | Financial Reporting Council |
| FRS 101 | FRS 101 Reduced Disclosure Framework under UK GAAP |
| FTSE 100 | a share index of the 100 companies listed on the London Stock Exchange with the highest market capitalisation |
| FVA | the fair value approach to transition to IFRS 17 |
| GAAP | Generally Accepted Accounting Practice |
| GMM | General Measurement Model in IFRS 17 |
| HMRC | Her Majesty's Revenue & Customs, the UK tax authority |
| IAS 37 | IAS 37 Provisions, Contingent Liabilities and Contingent Assets |
| IASB | International Accounting Standards Board |
| IASB Effects Analysis | the IFRS Standards Effects Analysis for IFRS 17, issued by the IASB in May 2017 |
| IASB Conceptual Framework | the IASB's Conceptual Framework for Financial Reporting, issued in 2010 and revised in 2018 |
| IASB Framework | Framework for the Preparation and Presentation of Financial Statements adopted by the IASB in April 2001 |
| IFRS | International Financial Reporting Standard |
| IFRS 4 | IFRS 4 Insurance Contracts |
| IFRS 9 | IFRS 9 Financial Instruments |
| IFRS 15 | IFRS 15 Revenue from Contracts with Customers |
| IFRS 17 | IFRS 17 Insurance Contracts |
| IFRS Standards | the suite of international accounting standards issued by the IASB |
| M&A | Mergers and acquisitions |
| MRA | the modified retrospective approach to transition to IFRS 17 |
| PAA | Premium Allocation Approach in IFRS 17 |
| PRA | the Prudential Regulation Authority, part of the Bank of England |
| Preparer survey | the on-line survey of insurance companies conducted by the UKEB in September and October 2020 |
| RITC | reinsurance to close, a type of reinsurance contract used at Lloyd's of London |
| RMO | Risk Mitigation Option in IFRS 17 |
| SI 2019/685 | The International Accounting Standards and European Public Limited-Liability Company (Amendment etc.) (EU Exit) Regulations 2019 No. 685 |
| Solvency II | a directive in EU law that codified and harmonised EU insurance regulation. It governs the amount of capital that EU insurance companies must hold to reduce the risk of insolvency |
| TAG | Insurance Technical Advisory Group (TAG) - provided technical support to the UK Endorsement Board secretariat in developing advice regarding the assessment of IFRS 17 against the endorsement criteria. The Insurance TAG is an advisory group rather than a decision-making body and its advice forms one element only of the evidence considered by the UKEB in coming to an adoption decision |
| TPR | Temporary Permissions Regime |
| TRG | the IASB's Transition Resource Group for IFRS 17 |
| UKEB | the UK Endorsement Board |
| User roundtable | the roundtable discussion for users of insurance company accounts hosted by the UKEB in June 2021 |
| User survey | the on-line survey of users of insurance company accounts conducted by the UKEB in May 2021 |
| VFA | Variable Fee Approach in IFRS 17 |
| WACC | Weighted Average Cost of Capital |
Appendix B - Assessment of remaining significant issues
Our approach to the assessment of IFRS 17 against the technical accounting criteria specified in SI 2019/685 regulation 7 (1) (c) is set out in Section 3 of this ECA.
The remaining significant technical accounting issues assessed in this Appendix cover:
- Risk adjustment for non-financial risk;
- Interest accretion at the locked-in rate for CSM under the GMM;
- Recognition of income from reinsurance to match losses from onerous underlying contracts;
- Contracts acquired in their settlement period;
- Contracts that change nature over time;
- Reinsurance to close transactions in the Lloyd's market
- Other comprehensive income option;
- Transition requirements; and
- Other VFA issues:
- Ineligibility of reinsurance contracts for VFA;
- Prohibition of retrospective application of the risk mitigation option;
- Eligibility for VFA when there are mutualised cash flows; and
- Non-profit contracts written by a with-profits fund.
Broadly, issues relating to measurement have been presented first, followed by issues related to presentation and transition. The ‘other VFA issues’ at the end represent narrower issues that are expected to affect fewer insurers and/or be less significant (material).
Our approach to the assessment of IFRS 17 against the technical accounting criteria specified in SI 2019/685 regulation 7 (1) (c) is set out in Section 3 of this ECA.
The remaining significant technical accounting issues assessed in this Appendix cover:
- Risk adjustment for non-financial risk;
- Interest accretion at the locked-in rate for CSM under the GMM;
- Recognition of income from reinsurance to match losses from onerous underlying contracts;
- Contracts acquired in their settlement period;
- Contracts that change nature over time;
- Reinsurance to close transactions in the Lloyd's market
- Other comprehensive income option;
- Transition requirements; and
- Other VFA issues:
- Ineligibility of reinsurance contracts for VFA;
- Prohibition of retrospective application of the risk mitigation option;
- Eligibility for VFA when there are mutualised cash flows; and
- Non-profit contracts written by a with-profits fund.
Broadly, issues relating to measurement have been presented first, followed by issues related to presentation and transition. The ‘other VFA issues' at the end represent narrower issues that are expected to affect fewer insurers and/or be less significant (material).
Risk adjustment for non-financial risk
IFRS 17 requirements
IFRS 17 defines the risk adjustment for non-financial risk (RA) as "the compensation an entity requires for bearing the uncertainty about the amount and timing of the cash flows that arises from non-financial risk as the entity fulfils insurance contracts". [IFRS 17 Appendix A] An entity shall apply the RA to the estimate of the present value of future cash flows when measuring a group of insurance contracts. [IFRS 17:37]
The RA also reflects the degree of diversification benefit the entity includes when determining the compensation it requires for bearing non-financial risk, and both favourable and unfavourable outcomes in a way that reflects the entity's degree of risk aversion. [IFRS 17: B88]
The RA shall be included in the measurement of insurance contracts in an explicit way, as it is conceptually separate from the estimates of future cash flows and the discount rates that adjust those cash flows. [IFRS 17: B90]
IFRS 17 is principle-based and does not specify the estimation technique(s) to be used to determine the RA, but states the characteristics that the RA shall have. [IFRS 17: B91] An entity shall apply judgement when determining an appropriate estimation technique for the RA. When applying that judgement, an entity shall also consider whether the technique provides concise and informative disclosure so that users of financial statements can benchmark the entity's performance against the performance of other entities. [IFRS 17: B92]
In the case of reinsurance contracts held, an entity shall determine the RA so that it represents the amount of risk being transferred by the holder of the group of reinsurance contracts to the issuer of those contracts. [IFRS 17: 64 and Illustrative Example 11]
Disclosures
Disclosures are required about significant judgements and changes in judgements made by an entity in applying IFRS 17. Specifically, an entity shall disclose the inputs, assumptions and estimation techniques used, such as the approach used to determine the RA, including whether changes in the RA are disaggregated into an insurance service component and an insurance finance component or are presented in full in the insurance service result. [IFRS 17:117(c)(ii)]
An entity shall also disclose the confidence level used to determine the RA. If an entity uses a technique other than the confidence level technique for determining the RA, it shall disclose the technique used and the confidence level corresponding to the results of that technique. [IFRS 17: 119]
Accounting impact
Initial recognition
- On initial recognition of a group of insurance contracts, the RA affects the measurement of the fulfilment cash flows. [IFRS 17:32] For profitable contracts the impact of applying a higher or lower RA is reflected in (and offset by) the contractual service margin (CSM) so there is no immediate effect on profit or equity.
For a group of contracts that is only marginally profitable the RA applied can affect the likelihood that the group is initially assessed as onerous. For a group of contracts that is onerous on initial recognition, the RA applied affects the amount of the loss that is initially recognised. Subsequent measurement
- Since the RA is part of the fulfilment cash flows [IFRS 17: 32(a)(iii)], changes in the RA that relate to prior/current service are recognised in profit or loss in the period in which they occur. The portion of the RA relating to the liability for remaining coverage is recognised in insurance revenue as the risk is released, while the portion of the RA relating to the liability for incurred claims is recognised in insurance service expenses [IFRS 17: 41a, 42a-b]. Changes in the risk adjustment that relate to future service adjust the contractual service margin as specified in paragraphs B96-B100 [IFRS 17: 44c].
An entity is permitted (but not required) to disaggregate the change in the RA between the insurance service result and insurance finance income or expenses. If an entity does not make such a disaggregation, it shall include the entire change in the RA as part of the insurance service result. [IFRS 17:81]
Current UK accounting standards do not require an explicit risk adjustment over and above best estimate liabilities, but this risk is typically included in the measurement as an implicit margin. It is expected that all UK insurance entities will be affected by the application of the RA requirements in IFRS 17, and many entities are likely to encounter some complexities in its calculation. The relative size of the RA compared with the present value of estimated future cash flows will vary depending on the expected variability in insurance outcomes, diversification benefits and the entity's risk appetite.
Assessment against the technical accounting criteria
The fact that there is a market for risk is a core principle of the insurance industry, and therefore it is relevant to include an explicit RA in an insurer's financial statements. This:
- Provides a clearer insight into the insurance contracts, distinguishing risk-generating liabilities from risk-free liabilities.
- Results in a profit recognition pattern that reflects both the profit recognised for bearing risk and the profit recognised for providing services.
- Reveals circumstances in which the entity has charged insufficient premiums for bearing the risk that the claims might ultimately exceed expected premiums.
- Reports changes in estimates of risk promptly and in an understandable way.
The complexity of the methods needed to calculate the RA might introduce a risk to the reliability of these estimates. The RA, and in particular the RA for certain products such as non-proportional reinsurance, is difficult to estimate reliably without the use of complex actuarial methodologies, which might represent a challenge for smaller entities. However, this risk is mitigated by the fact that even relatively small insurers are likely to need to calculate the risks covered by the RA for the purpose of current regulatory reporting.
The degree of flexibility allowed in the calculation of the RA, as well as the level of expert judgement needed, in particular for some lines of business and within consolidated insurance and reinsurance group structures, may present a challenge to reliability and comparability, both between different entities and between successive reporting periods. However, this flexibility is consistent with the principle-based approach elsewhere in IFRS 17 and with the approach for a similar risk adjustment for non-financial risk in IFRS 13 Fair Value Measurement.
The RA is a new concept in financial reporting under IFRS for insurers and reinsurers. The calculation of the RA is a technically challenging area and the details of the calculation may present a challenge to the understandability of financial statements for some users of accounts. Further, the RA will potentially be volatile between reporting periods in ways that are complex and therefore difficult to relate directly to the performance of the business, and this may therefore lead to reduced understandability of accounts.
However, the overall concept of allowing for the uncertainty in estimates of insurance liabilities is not complex, can be explained by insurers and is generally already understood by users of insurers' accounts. In addition, disclosures such as those on significant judgements, estimation techniques used and the confidence level will mitigate concerns over reliability, comparability and understandability of the RA and will help users of financial statements gain an understanding of its nature and impact.
The option to either disaggregate the RA between the insurance service result and insurance finance income or expenses or to present the full RA in the insurance service result may reduce comparability between entities. However, this risk is balanced by the fact that optionality allows entities to assess the relative costs and benefits of disaggregation in their particular circumstances.
Overall, the inclusion of a separate RA improves transparency in an insurer's financial statements and hence enhances the relevance of the information. Coupled with IFRS 17's disclosure requirements, the transparency of an explicit RA also enables comparisons between entities within the insurance industry and between successive reporting periods, enhancing comparability.
Interest accretion at the locked-in rate for CSM under the GMM
IFRS 17 requirements
Entities applying the general measurement model (GMM) are required to measure the fulfilment cash flows and the contractual service margin (CSM) at two different types of discount rates:
- Fulfilment cash flows are measured based on current discount rates. [IFRS 17: 40 and B72(a)]
- The CSM is measured based on the discount rate determined at initial recognition (the locked-in discount rate). This means the locked-in rates are used for:
- Accreting interest on the CSM.
- An entity shall apply discount rates determined at the date of initial recognition and applicable to nominal cash flows that do not vary based on the returns of any underlying items. [IFRS 17: 44 and B72(b)]
- Measuring changes to the CSM arising from changes in fulfilment cash flows that relate to future service, such as:
- Experience adjustments arising from premiums received in the period that relate to future service and related cash flows.
- Changes in estimates of the present value of the future cash flows in the liability for remaining coverage (except for those related to the effects of the time value of money and financial risk).
- An entity shall apply the discount rates which reflect the characteristics of the cash flows determined on initial recognition of the group of insurance contracts. [IFRS 17: 44 and B72(c)]
- Accreting interest on the CSM.
Accounting impact
The application of current discount rates for fulfilment cash flows and *locked-in
- discount rates for CSM leads to a difference that represents the cumulative effect of changes in financial variables on the underlying change in estimates between the date the insurance contracts were initially recognised and the date of the change in estimates.
Such a difference gives rise to a gain or loss that is included in profit or loss or other comprehensive income, depending on the accounting policy choice an entity makes for the presentation of insurance finance income or expenses. [IFRS 17: BC275] (For more information on this accounting policy choice refer to the Other Comprehensive Income Option assessment in this Appendix below). We expect most UK insurers will account for their financial assets at fair value through profit or loss under IFRS 9 *Financial Instruments
- and will therefore not use the OCI option available in IFRS 17 to disaggregate the presentation of insurance income or expenses. This means that, for most UK insurers, the impact of changes in interest rates arising from both their financial assets and the fulfilment cash flows of their insurance contracts accounted for under the GMM will be recognised in profit or loss. The gain or loss resulting from the use of a locked-in rate for the CSM may therefore result in volatility in profit or loss.
This issue is likely to be more significant for long-duration insurance contracts accounted for under the GMM. The financial impact of applying a locked-in rate rather than a current rate cannot yet be quantified, but stakeholders have estimated that it could be significant.
Using locked-in rather than current rates is expected to increase operational complexity.
Assessment against the technical accounting criteria
The CSM does not represent future cash flows but represents the unearned profit in the contract, measured at the point of initial recognition and adjusted only for specified amounts. [IFRS 17: BC274] Changes in financial conditions do not give rise to changes in the value of future margins, as the amount paid by a policyholder when they receive services does not change in line with interest rates. Using a locked-in rate for calculating interest on the CSM means performance reflects contract pricing at the time the insurance contract was written and therefore enhances relevance.
When changes in fulfilment cash flows (such as changes in estimates and experience adjustments) relate to future service, the expected profit relating to that future service changes and therefore adjusts the CSM. [IFRS 17: BC276C] Using a locked-in rate to determine adjustments to the CSM for changes in estimates of cash flows that relate to future service provides relevant information as it ensures consistency with the measurement of the CSM on initial recognition and avoids reflecting adjustments for changes in assumptions relating to financial risk.
A core benefit introduced by IFRS 17 is the presentation of insurance income and expenses separately from the insurance service result. The use of locked-in rates allows the insurance service result to be unaffected by changes in interest rates, to be more clearly separable from the insurance finance result and therefore to assist users of financial statements in understanding an entity's performance.
The requirement to calculate interest on the CSM is consistent with IFRS 15 Revenue from Contracts with Customers, which requires an entity to adjust the promised consideration to reflect the time value of money if the contract has a significant financing component. This consistency with IFRS 15 therefore enhances comparability with other entities.
Applying locked-in interest rates to the CSM could potentially impair the relevance of the insurance finance result as it could be distorted by cumulative finance adjustments (such as to reflect the cumulative effect of changes in financial variables on underlying changes in estimates). This could result in volatility in the insurance finance result, the direction and size of which are not a function of the underlying features of the contract but rather the changes in interest rates since initial recognition of the insurance contracts. Due to its complex nature this adjustment may also impair understanding of an entity's performance.
However, some insurers could potentially mitigate this volatility in profit or loss by electing to disaggregate its insurance finance income or expense in profit or loss and other comprehensive income, effectively transferring such volatility to the other comprehensive income.
IFRS 17's disclosure requirements should also help to mitigate concerns over understandability: IFRS 17: 110 requires an entity to explain the total amount of insurance finance income or expenses and its relationship with the investment return on assets. Such disclosures should assist users in understanding the information presented in an entity's financial statements.
Recognition of income from reinsurance to match losses from onerous underlying contracts
IFRS 17 requirements
IFRS 17 requires a company to account for reinsurance contracts held separately from underlying insurance contracts issued. [IFRS 17: BC 298]
On initial recognition of, or on addition of onerous contracts to, groups of insurance contracts that are expected to be loss making, a company must recognise the loss immediately in profit or loss. When such insurance contracts are covered by reinsurance contracts held, IFRS 17 requires an entity to recognise corresponding income from reinsurance in profit or loss [IFRS 17: 66A] at the same time if, and only if, the entity enters into the group of reinsurance contracts held before or at the same time as the onerous underlying insurance contracts are recognised. [IFRS 17: B119C]
The income recognised from a group of reinsurance contracts held is calculated by multiplying:
- the loss recognised on the underlying insurance contracts; and
- the percentage of claims on the underlying insurance contracts that the entity expects to recover from the group of reinsurance contracts held. [IFRS 17: B119D]
If the group of onerous underlying insurance contracts includes contracts that are not covered by reinsurance, the Standard permits an entity to apply a systematic and rational method of allocation to determine the proportion of losses recognised that relate to insurance contracts covered by the group of reinsurance contracts held. [IFRS 17: B119E]
The standard requires an entity to establish a loss-recovery component of the asset for remaining coverage of a group of reinsurance contracts held that determines amounts that entities will recognise in profit or loss in subsequent periods as reversals of recoveries of losses. [IFRS 17: 66B]
The loss-recovery component is adjusted subsequently to reflect changes in the loss component of the onerous group of underlying insurance contracts. The carrying amount of the loss-recovery component cannot exceed the portion of the carrying amount of the loss component of the onerous underlying insurance contracts the entity expects to recover from reinsurance. [IFRS 17: B119F]
Disclosures
IFRS 17 requires the separate presentation of amounts relating to reinsurance contracts held and underlying insurance contracts in profit or loss [IFRS 17: 82] and on the balance sheet [IFRS 17: 78]. An entity is also required to adapt the disclosure requirements of paragraphs 100-109 to reflect the features of reinsurance contracts held that are different from insurance contracts issued. [IFRS 17: 98]
Accounting impact
Subject to certain requirements being met, an entity is permitted to recognise income from reinsurance to offset the upfront loss recognised at initial recognition of onerous underlying contracts. This reduces the negative effect on profit or loss on day one. The recognition of income in profit or loss is not dependent on whether the group of reinsurance contracts held is in a net gain or a net cost position.
Although the overall ultimate net cost of reinsurance over its coverage period remains unaffected, entities with net cost reinsurance will effectively increase the amount of losses deferred – income is recognised immediately, in the form of the loss recovery, but the net cost deferred over time is increased, as illustrated by the following example.
| Insurance contracts issued | Reinsurance contracts held | Total |
|---|---|---|
| Premiums 100 | Reinsurance premiums (65) | Net premiums 35 |
| Claims (150) | Claim recoveries 60 | Net claims (90) |
| Loss (50) | Net cost (5) | Net position (55) |
The percentage of claims expected to be recovered from reinsurance is 40% and the loss-recovery is 20.
| Recognised at inception | Recognised over time | |
|---|---|---|
| Insurance revenue | 0 | 100 |
| Insurance service expenses | (50) | (100) |
| Insurance contracts issued | (50) | 0 |
| Reinsurance premiums | 0 | (65) |
| Amounts recovered from reinsurance | 20 | 40 |
| Reinsurance contracts held | 20 | (25) |
| Profit/(loss) | (30) | (25) |
The adjustment to determine the amount of income to recognise in profit or loss is calculated by multiplying a claims recovery percentage by the loss on the onerous underlying contracts, disregarding any contribution to the loss on those contracts made by other expenses or the risk adjustment. Such expenses are frequently not recoverable from reinsurers.
Assessment against the technical accounting criteria
Recognising information about the expected loss recoveries from reinsurance contracts provides relevant information because it complements the information about expected losses on underlying insurance contracts. IFRS 17's requirement ensures that income from reinsurance is recognised at the same time that losses are recognised on the underlying contracts, thereby avoiding a mismatch.
Recognising corresponding income on reinsurance contracts held that are in a net gain position provides relevant information because it reflects the right that the entity has to recover the losses from reinsurance and therefore better reflects the economics of the transaction. Stakeholders have informed us that this situation is prevalent for UK protection products because it is not uncommon for the underlying contracts to be onerous when considered in isolation, but profitable after reinsurance.
Conversely, recognising income on reinsurance contracts held in a net cost position, and thereby deferring recognition of the net cost of the reinsurance contracts, may not faithfully represent the economics of the contracts and may seem imprudent, impairing reliability. However, an entity has the right to recover claims from the reinsurer regardless of whether claim recoveries are expected to be higher or lower than the reinsurance premiums paid. Further, it is consistent with the principles of IFRS 17 that the cost of the reinsurance coverage (the premiums paid by the entity to the reinsurer) is recognised over the duration of the contract as the reinsurer provides service. This treatment also reflects the fact that the entity has the right to recover not only expected claims but also unexpected claims.
The recognition of income upfront when the group of reinsurance contracts held is in a net cost position might impair the understandability of financial performance for users of the accounts. It will not necessarily be readily apparent from the accounts whether the relevant group of reinsurance contracts held is in a net cost or net gain position, nor will the extent to which future losses on reinsurance are expected be immediately apparent. This may also impair comparability. However, losses and loss recoveries will be presented in separate line items in profit or loss and separately in the notes, providing useful information and mitigating the risk to understandability and comparability. Users with a more sophisticated level of understanding should be able to interpret the financial information and identify that the loss-recovery component carried forward will be recognised as an additional cost in future periods.
The timing constraint in IFRS 17 paragraph B119C may result in income statement volatility, reducing relevance. For example, the income offset is not available for underlying insurance contracts issued during the period of a reinsurance contract renegotiation even though such contracts may be shielded by reinsurance during this period. Furthermore, the timing constraint results in complexities for insurance contracts covered by 'losses occurring during' reinsurance contracts, as some contracts eligible to be reinsured under the contract would not meet the requirements for income offset.
However, stakeholders had also expressed concerns that the recognition of upfront income from reinsurance would be open to abuse, enabling entities to achieve a desired accounting outcome by entering into reinsurance contracts with the intention of deferring losses on underlying contracts. The requirement to have entered into the group of reinsurance contracts held before, or at the same time, as the loss is recognised on the group of onerous underlying insurance contracts, mitigates this risk to reliability. The timing constraint therefore strikes a balance between the objectives of relevance and reliability.
The calculation of the loss-recovery component is determined by the overall loss on the underlying insurance contracts, including expenses that may not be recoverable under the reinsurance contract held. The accounting implies that the reinsurance contract covers elements of the loss that will in fact not be recovered, so may not give a faithful representation of the transaction, impairing reliability. However, stakeholders have indicated that they do not anticipate the expenses to be a material item in the fulfilment cash flows. Furthermore, the simplifying assumption that the loss on insurance contracts is caused solely by claims reduces complexity and cost to preparers.
Contracts acquired in their settlement period
IFRS 17 requirements
In accordance with the principles of IFRS 3 Business Combinations, IFRS 17 requires entities to account for insurance contracts acquired (whether in a transfer of insurance contracts that do not form a business, or in a business combination within the scope of IFRS 3) as if they had entered into the contracts on the date of the transaction. [IFRS 17: B93] Therefore, an entity must assess whether a contract meets the definition of an insurance contract based on the facts and circumstances available on the date of the transaction.
In the case of insurance contracts acquired in their settlement period, paragraph B5 of IFRS 17 states that when insurance contracts cover events that have already occurred, but the financial effect of which is still uncertain, the insured event is the determination of the ultimate cost of those claims. 133 As the insured event has not yet occurred, the insurance contract liability is classified as a liability for remaining coverage.
When the insurance contracts are acquired, unless the premium allocation approach (PAA) is applied, the acquirer recognises a contractual service margin (CSM) equal to any positive difference between the consideration received or paid and the fulfilment cash flows at the acquisition date.
If the insurance contracts acquired are onerous, the excess of the fulfilment cash flows over the consideration paid or received is either recognised as part of goodwill or a gain on a bargain purchase for contracts acquired in a business combination, or as a loss in profit or loss for contracts acquired in a transfer. A loss component is established and subsequently measured in accordance with IFRS 17: 49-52. [IFRS 17: B95A]
As the contract is in its settlement period and the ultimate cost of the claims remains uncertain, the acquirer recognises a liability for remaining coverage. On subsequent measurement, the acquirer recognises insurance revenue for the reduction in the liability for remaining coverage for services provided in the period. The CSM is recognised in profit or loss as insurance revenue over the expected claims settlement period, based on coverage units. Insurance service expenses will be recognised in profit or loss based on the actual claims settlement amounts in each reporting period.
Disclosures
Entities are required to separately present amounts resulting from contracts acquired from other entities in transfers of insurance contracts or business combinations. [IFRS 17: 108(a)]
Accounting impact
Certain IFRS 17 requirements create a difference in accounting between contracts issued by the entity and contracts acquired in portfolio transfers or business combinations. The classification of the insurance contract liability as a liability for remaining coverage or incurred claims does not affect the calculation of the fulfilment cash flows but does affect other aspects of recognition and measurement. Claims liabilities for contracts issued by an entity are accounted for as a liability for incurred claims. However, if the same contracts are acquired, and assuming the ultimate cost of the claims is uncertain, the insurance contract liabilities are expected to be accounted for as a liability for remaining coverage. This in turn means that insurance revenue is recognised and that such contracts may be recognised under the general measurement model (GMM), for example when the period to ultimate settlement is greater than one year. This may create an operational burden for insurance companies that might otherwise only apply the PAA to contracts they issue.
Assessment against the technical accounting criteria
Treating the insured event as the determination of the ultimate cost of the claims and recognising insurance revenue in profit or loss over the period that insurance service is provided is consistent with IFRS 17's general measurement model and the requirements of IFRS 15 Revenue from Contracts with Customers. The required treatment of acquired contracts therefore provides relevant and more comparable information.
IFRS 17's requirements for acquired contracts are broadly consistent with acquisition accounting under IFRS 3. This should promote understandability and comparability with other areas of accounting and with other IFRS reporters, enhancing the transparency of insurance companies' financial information.
Initially, IFRS 17's requirements for contracts acquired in their settlement period may potentially reduce understandability because the recognition of insurance revenue may not be aligned with users' current expectations. It may be unclear what insurance service is provided to the policyholder, and therefore why insurance revenue is recognised by the acquirer. Some stakeholders have also questioned whether analysts will need to adjust reported revenue and may request additional disclosures to enable analysis of performance.
However, concerns about understandability are likely to decline over time and will be mitigated by IFRS 17's disclosure requirements. In particular, the standard requires separate disclosure of the effect on the balance sheet of contracts acquired from other entities in the period, enhancing understandability. [IFRS 17: 108] The treatment of contracts acquired in their settlement period required by IFRS 17 might reduce *comparability
- between insurance contracts acquired pre- and post-transition to IFRS 17. A transition relief available in the modified retrospective approach 134 permits an entity to account for a liability for claims settlement of a contract acquired before the date of transition as a liability for incurred claims, rather than as a liability for remaining coverage. Insurance contracts acquired in their settlement period after the date of transition must be accounted for as a liability for remaining coverage.
However, the risk to comparability from this relief is outweighed by the considerations around practicability, which significantly enhances reliability, because reliable information cannot be provided in the absence of the required information.
IFRS 17's requirements might also reduce comparability between acquired and issued contracts. Contracts in their settlement period that were issued by the entity would be accounted for as a liability for incurred claims. Changes in the liability for incurred claims would be recognised in profit or loss as insurance service expenses, not insurance revenue. Conversely, if acquired, the entity would account for the same obligations as a liability for remaining coverage, because the insured event becomes the determination of the ultimate cost of the claims.
However, where acquisitions of insurance contracts are a significant part of its business, or significant in the context of a reporting period, an entity is likely to need to explain the impact of acquisitions to users of the accounts in any event. The disclosure requirements noted above, and the general IFRS 17 requirement to provide additional disclosures where necessary to enable users of the accounts to assess the effect of contracts on the entity's financial position, financial performance and cash flows [IFRS 17: 94], mitigate these risks to comparability.
Stakeholders have expressed similar concerns with reference to the expected accounting for reinsurance to close (RITC) transactions in the Lloyd's market (see separate assessment below).
IFRS 17's requirements will mean a change to current accounting practice in the UK so may pose initial risks to understandability. However, these risks need to be balanced with the objective of consistency with other IFRS Standards and hence enhanced comparability and relevance.
Contracts that change nature over time
IFRS 17 requirements
UK with-profits savings contracts commonly contain a guaranteed annuity option (GAO) giving the policyholder the option to take out an annuity at retirement at a guaranteed rate. These contracts typically have participating features during the savings phase but there is no participation once the annuity option vests.
Under IFRS 17, the accounting model applied is determined at inception or, in some circumstances, may be assessed at transition under the modified retrospective and fair value approaches. [IFRS 17: B102, C9(b), C21(b)]
The entity's contractual obligations and the policyholder's overall costs and benefits under the contract do not change at the point the annuity vests. Therefore, it is unlikely that the contract boundary requirements in paragraph 34 of IFRS 17 are met at the annuity vesting date. The contract boundary therefore includes both a with-profits savings phase and an annuity pay-out phase that would be accounted for under separate measurement models were they stand-alone contracts: the with-profits savings phase would probably be accounted for under the variable fee approach (VFA) and the annuity pay-out phase would probably be accounted for under the general measurement model (GMM). If IFRS 17's contract boundary requirements are not met, the entire contract will be accounted for under a single approach and it is likely that some, but not all, of these contracts will meet the VFA eligibility criteria. This is partly dependent on the assessment date and whether the guarantee is 'in the money' at that date.
A main measurement difference between the GMM and the VFA is that changes in the fulfilment cash flows arising from time value of money and financial risks are:
- regarded as part of the variability of the fee for future service and recognised in the contractual service margin (CSM) under the VFA [IFRS 17:45]; and
- recognised immediately in profit or loss as insurance finance income or expense (IFIE) under the GMM. [IFRS 17: 87]
Accounting impact
If IFRS 17's contract boundary requirements are not met, then the insurer will not account for a new contract at the vesting date, but rather for a single contract that includes both the savings phase and the annuity pay-out phase. The result of IFRS 17's requirements is that:
- the VFA may be applied to the vested annuity despite there being no significant savings element or underlying items post-vesting (see A below); or
- the entire contract including the participating phase may fail VFA eligibility testing and require measurement under the GMM, despite there being a significant savings element and underlying items prior to vesting (see B below).
The primary measurement difference between the accounting models impacts both the timing and presentation in profit or loss of changes in the fulfilment cash flows arising from time value of money and financial risks:
- Under the VFA, changes will be recognised in line with the provision of service, as the CSM is recognised, through insurance revenue; and
- Under the GMM, changes will be recognised immediately as IFIE.
Scenario B is expected to be more prevalent in the UK since this type of contract was predominantly issued a number of years ago and, since the accounting model will therefore often be determined at transition, it is less likely that the VFA eligibility criteria will be met.
A- Accounting for annuities under the VFA
Adjusting the CSM for changes in the fulfilment cash flows arising from the time value of money and financial risks can reduce the reported CSM. This is because, as the discount rate on the fulfilment cash flows is unwound, the corresponding expense is adjusted against the CSM. Ignoring any changes in discount rates, the unwind of the discounting will increase the likelihood that the CSM reduces to zero and the contracts become onerous, thereby resulting in greater volatility in profit or loss.
Accounting for annuities under the VFA will therefore result in a decrease in insurance revenue, as the reduction in CSM reduces the corresponding amounts recognised in profit or loss.
The risk mitigation option (RMO), under which changes in the effect of the time value of money and financial risks are recognised in profit or loss rather than in CSM, would be effective in reducing these issues, however eligibility is dependent on each insurer's risk management practices.
B- Accounting for with-profits contracts under the GMM
Under the GMM, the unwind of the discounting and changes in financial risks that under the VFA would be within the 'variable fee' earned on with-profits contracts, will be recognised directly in IFIE in profit or loss. This has the opposite effect to that for annuities under the VFA, increasing both insurance revenue (because the CSM is not reduced) and insurance finance expense over the life of the contract.
The fulfilment cash flows during the savings phase will include the future cashflows relating to the annuity pay-out phase, bringing the profit margin that the annuity company or fund expects to make into the CSM. This is likely to introduce mismatches with the returns on backing assets that are managed on a Solvency II basis (which typically includes the cost of the GAO to the with-profits fund at market prices), and which will also be recognised directly in profit or loss.
The additional complexities of including cash flows beyond vesting in with-profits fulfilment cash flows, and applying different accounting models to annuities depending on whether they are stand-alone or arose from a savings contract with a GAO, will
increase implementation costs for impacted insurers. However, while these costs may be significant they are not expected to be prohibitive.
The primary measurement difference between the accounting models impacts both the timing and presentation in profit or loss of changes in the fulfilment cash flows arising from time value of money and financial risks: * Under the VFA, changes will be recognised in line with the provision of service, as the CSM is recognised, through insurance revenue; and * Under the GMM, changes will be recognised immediately as IFIE.
Scenario B is expected to be more prevalent in the UK since this type of contract was predominantly issued a number of years ago and, since the accounting model will therefore often be determined at transition, it is less likely that the VFA eligibility criteria will be met.
A- Accounting for annuities under the VFA
Adjusting the CSM for changes in the fulfilment cash flows arising from the time value of money and financial risks can reduce the reported CSM. This is because, as the discount rate on the fulfilment cash flows is unwound, the corresponding expense is adjusted against the CSM. Ignoring any changes in discount rates, the unwind of the discounting will increase the likelihood that the CSM reduces to zero and the contracts become onerous, thereby resulting in greater volatility in profit or loss.
Accounting for annuities under the VFA will therefore result in a decrease in insurance revenue, as the reduction in CSM reduces the corresponding amounts recognised in profit or loss.
The risk mitigation option (RMO), under which changes in the effect of the time value of money and financial risks are recognised in profit or loss rather than in CSM, would be effective in reducing these issues, however eligibility is dependent on each insurer's risk management practices.
B- Accounting for with-profits contracts under the GMM
Under the GMM, the unwind of the discounting and changes in financial risks that under the VFA would be within the 'variable fee' earned on with-profits contracts, will be recognised directly in IFIE in profit or loss. This has the opposite effect to that for annuities under the VFA, increasing both insurance revenue (because the CSM is not reduced) and insurance finance expense over the life of the contract.
The fulfilment cash flows during the savings phase will include the future cashflows relating to the annuity pay-out phase, bringing the profit margin that the annuity company or fund expects to make into the CSM. This is likely to introduce mismatches with the returns on backing assets that are managed on a Solvency II basis (which typically includes the cost of the GAO to the with-profits fund at market prices), and which will also be recognised directly in profit or loss.
The additional complexities of including cash flows beyond vesting in with-profits fulfilment cash flows, and applying different accounting models to annuities depending on whether they are stand-alone or arose from a savings contract with a GAO, will increase implementation costs for impacted insurers. However, while these costs may be significant they are not expected to be prohibitive.
Assessment against the technical accounting criteria
Including all phases of the contract in the fulfilment cashflows will faithfully represent all the insurers' rights and obligations that arise from policyholders' options in these contracts, and thereby provide relevant information. The inability to reassess the measurement model ensures that IFRS 17 maintains clear and consistent contract boundary requirements across all types of insurance contracts, promoting comparability of financial information.
Treating annuities sold on a stand-alone basis separately from annuities resulting from a savings contract with a GAO reflects the facts that a combined contract might be priced differently from a stand-alone contract, and that pricing is likely to have been at different times and under different market conditions. Further, even when the option is not at a guaranteed rate, the annuity may not always vest at pure market rates. IFRS 17's requirements are therefore likely to provide more relevant information.
The VFA model was developed by the IASB to give a faithful representation of the different nature of the fee in participating contracts. Therefore, the inability to apply the VFA to the with-profits phase of the contract may be considered to provide less relevant information during that phase. However, it would have been difficult to define any exception sufficiently tightly to prevent unintended consequences. Further, any exception would probably have needed to be optional, impairing comparability.
Applying the VFA to the non-participating annuity phase of the contract may result in less relevant information as the entity's profit from an annuity is not earned as a variable fee. In the annuity pay-out phase, entities apply asset-liability matching strategies, to position themselves to satisfy their performance obligations. If contracts in the annuity pay-out phase are measured under the VFA, movements in the value of assets are reflected in profit or loss, and movements in the value of insurance liabilities will adjust the CSM, resulting in accounting volatility in profit or loss that arguably does not reflect the economic position, resulting in less relevant information. However, the risk mitigation option is likely to be effective in reducing these issues. In addition, as explained above, this scenario is likely to be less prevalent.
While a sophisticated user of the accounts might understand how the entity earns profit from with-profits contracts and from annuities, the impact of IFRS 17's requirements means that the accounts may be more difficult to understand. In addition, due to the timing of the accounting model determination, which under the MRA and FVA135 may be at transition, some with-profits contracts with GAOs will meet the eligibility requirements for the VFA and others will not. Entities will therefore apply different measurement models to similar contracts, potentially impairing comparability.
IFRS 17 requires an entity to disclose quantitative and qualitative information about amounts recognised in its financial statements, any significant judgements and changes in those judgements, and the nature and extent of risks from insurance contracts. An entity must consider the level of detail necessary to satisfy the disclosure requirements and additional disclosures could mitigate the challenge to understandability and comparability.
The inability to reassess the accounting model at the annuity vesting point will create the need for significant judgements, including: the likelihood of the annuity option vesting; the apportionment of CSM between the savings phase and the annuity phase; appropriate discount rates given changes in cash flow liquidity characteristics and risks between the phases of the contract. This degree of judgement may create a risk to the comparability and reliability of financial statements. However, IFRS 17 will require significant judgments in a number of areas and those required in this case do not introduce a significant level of additional judgement. A similar level of judgement is also required under current accounting and regulatory reporting.
Reinsurance to close (RITC) transactions in the Lloyd's market
IFRS 17 requirements
RITC contracts are a mechanism in the Lloyd's market to 'transfer' insurance liabilities from one year of account to the next. RITC transactions take the form of the reinsurance of those liabilities, effected by the payment of a reinsurance premium by the members of the closing year (the ceding members) to the members of the accepting year (the reinsuring members).
IFRS 17 does not explicitly address the accounting for RITC transactions in the Lloyd's market. The requirements of IFRS 17 most directly relevant to the accounting questions arising in respect of RITC transactions are those relating to (i) eligibility for the premium allocation approach (PAA); (ii) the presentation of reinsurance assets and liabilities; and (iii) derecognition of insurance liabilities.
IFRS 17 requires that reinsurance contracts issued are accounted for by the reinsurer using either the general measurement model (GMM) or the PAA, in the same way as for other insurance contracts issued. The PAA is optional and may be used if at inception of the group of contracts (a) the entity reasonably expects that the PAA would produce a measurement of the liability for remaining coverage that would not differ materially from that under the GMM or (b) the coverage period of each contract in the group is one year or less. [IFRS 17:53]
IFRS 17 requires a reinsurance contract held to be accounted for separately from the underlying insurance contracts to which it relates, to reflect its separate rights and obligations. [IFRS 17: BC298] IFRS 17 also requires the separate presentation of amounts relating to reinsurance contracts held and underlying insurance contracts on the balance sheet and in profit or loss. [IFRS 17: 78 and 82]
IFRS 17 requires the derecognition of an insurance contract when, and only when, it is extinguished (i.e. the obligation expires or is discharged or cancelled) or when it is modified in certain specified ways. [IFRS 17:74]
Disclosures
RITC transactions would be included in the disclosures required generally to explain recognised amounts (IFRS 17 paragraphs 97 to 116). These include separate reconciliations for reinsurance contracts held showing how the net carrying amounts of contracts changed during the period. [IFRS 17: 98] Separate disclosure is also required of the effect of reinsurance contracts held initially recognised in the period and of when the CSM relating to reinsurance contracts remaining at the end of the reporting period is expected to be recognised. [IFRS 17: 107 and 109]
In addition, IFRS 17 paragraph 94 contains the general requirement that, if the specific disclosures required by the standard are not enough to meet the overall objective of enabling users of the accounts to assess contracts' effect on the entity's financial position, financial performance and cash flows, an entity shall disclose additional information necessary to meet this objective.
Accounting impact
Although not yet definitive, developing consensus in the UK appears to be that an RITC is a reinsurance transaction, so the following assessment is based on that assumption.
Parties to an RITC contract are other syndicate members: it does not involve policyholders or change any terms of the underlying insurance contracts. An RITC contract is therefore unlikely to represent the modification of the terms, or the extinguishment, of the underlying insurance contracts. Derecognition of the underlying insurance contract liabilities by the members of the closing year of account (the ceding members) is therefore unlikely.
On this basis, under IFRS 17 a member would continue to recognise insurance liabilities from earlier years of account after entering into an RITC contract. The member's interests in the earlier and later years of account would need to be recognised on a gross, consolidated basis.
The impact of IFRS 17 will depend on whether a member's participation in a syndicate increases, decreases or remains unchanged. When a member's share increases, the additional share of insurance obligations assumed is expected to be recognised as a reinsurance liability. Conversely, when a member's share decreases, the original insurance liability is expected to continue to be recognised together with a reinsurance asset representing the share of insurance obligations reinsured by other members through the RITC. If a member's participation level remains the same, then the RITC contract is not expected to have a significant accounting effect.
Under IFRS 17, when insurance contracts cover events that have already occurred, but the financial effect of which is still uncertain, the insured event is the determination of the ultimate cost of those claims.136 [IFRS 17: B5] In the case of an increase in participation, as the insured event has not yet occurred, the reinsurance liability recognised for the increased participation is classified as a liability for remaining coverage. For many RITC contracts, as the period to ultimate settlement will be greater than one year, such reinsurance liabilities may need to be accounted for under the GMM.
This may create an operational burden for insurance companies that might otherwise only apply the PAA to contracts they issue. In cases where the original insurance contract liabilities are accounted for under the GMM, two different CSMs and potentially also two different risk adjustments would need to be recognised for the same group of contracts137. In each of these cases, complexity and the operational burden would be increased if there were further RITC transactions in subsequent years for the same contracts. The measurement of expected cash flows, however, is expected to be on the same basis for both the originally recognised liability for incurred claims and the reinsurance liability for remaining coverage.
Conversely, if a corporate member decreased its participation in a syndicate, including in cases when it exited a syndicate completely via a RITC transaction, it would still need to maintain its accounting for its participation in the earlier year of account (i.e. it would present liabilities and a corresponding reinsurance asset). Such accounting would be required until the liability was extinguished, which in some cases could be a number of years.
For both increases and decreases in participation, the recognition of reinsurance balances may give rise to CSM amounts that would then need to be allocated to relevant coverage periods. In cases when a reinsurance asset is recognised, the transaction may give rise to either a credit balance CSM, leading to profit or loss impacts over the coverage period, or a day one loss.
A fully retrospective approach to transition will in many cases not be possible since the necessary records for the liabilities previously derecognised under IFRS 4 will generally not be available to members.
Assessment against the technical accounting criteria
Under IFRS 4 (and under UK GAAP), RITC contracts have generally not been accounted for as reinsurance contracts and, in practice, changes in the level of participation in a syndicate have typically been reported by simply adjusting relevant insurance liability balances (including derecognising liabilities when participation decreases). On the assumption that RITC contracts are accounted for as reinsurance, the application of IFRS 17's requirements to RITC contracts is likely to result in greater complexity compared with current accounting practice. In addition, the recognition of reinsurance assets and/or liabilities and the application of the GMM may not be aligned with users' or preparers' current expectations. Some stakeholders are concerned that these factors may initially reduce understandability.
The industry considers the likelihood of ceding members being called upon to settle insurance liabilities from the earlier year of account to be remote (given the security arrangements operating in the Lloyd's market and in particular the fact that Lloyd's Council may use its discretion to apply the Lloyd's Central Fund in cases when reinsuring members cannot meet their obligations). The inability for ceding members to derecognise such liabilities is considered by some stakeholders to present a risk to reliability and understandability of their financial position.
However, where a member's participation increases, the accounting under IFRS 17 reflects the fact that the additional portion is a reinsurance liability by nature, that it was 'acquired' from third parties, and that the member incurred it at a different time and potentially at a different price from the original liability, reflecting the view of insurance risk at the time of the RITC. Where relevant, the application of a different accounting model (i.e. GMM rather than PAA) would reflect the fact that the uncertain obligation relates to the settlement of incurred claims rather than to whether a claim would arise in the first place. Similarly, in a case where a member's participation has declined, the expected accounting reflects the fact that the member retains the ultimate legal liability for the underlying insurance contracts but has received (and paid for) reinsurance coverage from third parties. In both scenarios, the expected accounting under IFRS 17 fairly reflects the underlying contractual substance, enabling a more complete understanding and enhancing reliability.
The expected accounting for RITC contracts under IFRS 17 is consistent with that for reinsurance more generally and also with that for transfers of insurance contracts138, enhancing comparability.
Further, the application of IFRS 17's derecognition requirements to RITC contracts will result in consistency of treatment with other (re)insurance contracts and with financial liabilities more generally. Under IFRS 9 Financial Instruments a financial liability is derecognised when, and only when, it is extinguished139 or when it is substantially modified140. Similarly, under IAS 32 Financial Instruments: Presentation, even when 'back-to-back transactions' ensure that specific financial assets and liabilities are precisely matched, gross recognition is required except where there is a legal right of set-off141. Such consistency enhances comparability and, ultimately, broader understandability.
The application of IFRS 17 may lead companies to reconsider their existing accounting treatment of RITC contracts in the UK so may pose a minor risk to understandability on initial application of IFRS 17. However, such concerns are likely to decline over time and will be mitigated by IFRS 17's disclosure requirements. Further, these risks need to be balanced with the enhanced reliability derived from an accurate presentation of the underlying contractual substance of transactions, and with the objective of consistency with other IFRS Standards and hence enhanced comparability.
Other comprehensive income option
IFRS 17 requirements
In accordance with IFRS 17, Insurance Finance Income or Expenses (IFIE) mainly comprises the change in the carrying amount of the group of insurance contracts arising from the effect of (and changes in) the time value of money and financial risk. [IFRS 17: 87 (a) and (b)]
For IFIE not arising from risk mitigation activities142, IFRS 17 allows an entity to make an accounting policy choice (the OCI Option) between:
- including IFIE for the period in profit or loss; or
- disaggregating IFIE for the period between profit or loss and Other Comprehensive Income (OCI). [IFRS 17: 88-90]
An entity shall apply its choice of accounting policy to portfolios of insurance contracts. In assessing the appropriate accounting policy for a portfolio of insurance contracts, applying paragraph 13143 of IAS 8 Accounting Policies, Changes in Accounting Estimates and Errors, the entity shall consider for each portfolio the assets that the entity holds and how it accounts for those assets. [IFRS 17: B129]
IFRS 17 prescribes three specific approaches or bases of disaggregation of IFIE between profit or loss and OCI, which depend on the method that the entity applies to account for the insurance contract (i.e. the general measurement model, the variable fee approach or the premium allocation approach), and whether the IFIE relates to insurance contracts with direct participation features for which the entity holds the underlying items. [IFRS 17: B130-B134 and Illustrative Examples 15 and 16]
For insurance contracts with direct participation features, an entity's eligibility for one of the disaggregation approaches may change depending on whether it holds the underlying items. In such circumstances, an entity would change the basis of disaggregation accordingly and IFRS 17 provides specific guidance on how to account for that change. [IFRS 17: B135-B136]
Disclosures
An entity shall disclose and explain the total amount of IFIE in the reporting period. In particular, an entity shall explain the relationship between IFIE and the investment return on its assets, to enable users of its financial statements to evaluate the sources of finance income or expenses recognised in profit or loss and OCI. [IFRS 17: 110]
If an entity chooses to disaggregate IFIE into amounts presented in profit or loss and amounts presented in OCI, the entity shall disclose an explanation of the methods used to determine the IFIE recognised in profit or loss. [IFRS 17: 118]
For contracts with direct participation features, if an entity changes the basis of disaggregation (i.e. when there is a change in whether an entity holds the underlying items), it shall disclose, in the period when the change in approach occurred:
- the reason why the entity was required to change the basis of disaggregation;
- the amount of any adjustment for each financial statement line item affected; and
- the carrying amount of the group of insurance contracts to which the change applied at the date of that change. [IFRS 17: 113]
Accounting impact
The measurement of insurance contracts under IFRS 17 results in possible accounting mismatches because of the different possible bases of accounting for assets backing the insurance contracts. The OCI Option enables entities to reduce any such accounting mismatches.
If disaggregated, the amount in profit or loss is based on a systematic allocation of the expected IFIE over the duration of the group of insurance contracts. This would allow the partial offset in profit or loss of the IFIE arising from financial assets held by the entity. The remaining amount of IFIE (the impact of changes in financial assumptions, e.g. for interest rates) is presented in OCI. For insurance contracts with direct participation features for which the entity holds the underlying items, an amount that eliminates accounting mismatches is included in profit or loss rather than an amount based on a systematic allocation.
We do not expect the disaggregation of IFIE in profit or loss and OCI to be widely adopted in the UK as most UK insurers account for the majority of their financial assets at fair value through profit or loss.
Assessment against the technical accounting criteria
In circumstances when it enables insurers to reduce or in certain cases eliminate accounting mismatches between insurance liabilities and their supporting investment assets, disaggregating IFIE between profit or loss and OCI will provide more relevant and understandable information. Aligning the accounting treatment of investment assets (which in some cases are accounted for at amortised cost or at fair value through OCI under IFRS 9 Financial Instruments) and related insurance liabilities will reduce volatility in profit or loss and enable performance to be interpreted more clearly.
A potential consequence of the OCI Option is that profit or loss becomes a less complete measure of an insurer's economic position and hence could be seen as less reliable. Isolating the effect of changes in financial assumptions and reporting it in OCI might make an insurer's profit or loss appear more stable. Investors and other users of financial statements might need to perform additional analysis to fully understand an insurer's overall performance, and entities may need to introduce new accounting ratios or performance measures.
However, the disclosure requirements (including the explanation of the disaggregation methods used to determine the amount of IFIE presented in profit or loss and OCI) will mitigate this risk to reliability, enabling users to compare approaches and performance more easily between insurers. Further, the use of OCI to report certain effects of financial reporting is not unfamiliar to users of financial statements (for example, under IAS 39 Financial Instruments: Recognition and Measurement, IFRS 9 or other IFRS Standards), so the accounts should be understandable.
The IASB introduced the OCI Option as an accounting policy choice to allow entities to avoid the costs and complexity of using OCI when the benefits of doing so do not outweigh those costs. Any optionality within a standard reduces comparability. Similar accounting ratios calculated for different entities may disguise different underlying performance depending on whether the option is adopted. This may impede users from adequately comparing the results of different insurers. Furthermore, the OCI Option is applicable on a portfolio-by-portfolio basis. This means that performance between portfolios will be less comparable.
However, it is anticipated that the OCI Option will be more appropriate for certain types of business, depending on the accounting policy applied to the assets backing the insurance liabilities. Therefore, in practice the option may be applied consistently by type of business or by entities employing similar asset/liability strategies. This could mitigate the extent to which comparability is compromised across insurers on these bases.
The mechanism for determining the disaggregation between profit or loss and OCI is potentially complex. Entities will need to apply a significant degree of judgement, introducing a risk to the reliability and comparability of financial statements. However, the standard's requirements do not result in a degree of judgement that is inconsistent with that required under other IFRS Standards, and the disclosure requirements referred to above should serve to mitigate these risks.
Any risks to comparability or reliability need to be balanced against the enhanced relevance of the financial information in cases when use of the OCI Option enables entities to reduce or eliminate accounting mismatches. The specific disclosures required by IFRS 17 should also mitigate these risks. Users of insurers' accounts are likely to need to become familiar with new performance measures in any event, as IFRS 17 introduces significant change in a number of areas.
Transition requirements
IFRS 17 requirements
IFRS 17 requires an entity to restate comparative information about insurance contracts for the annual period immediately before the date of initial application. [IFRS 17: C1]
Unless it is impracticable to do so, IFRS 17 requires an entity to apply the standard retrospectively. [IFRS 17: C3]
If, and only if, it is impracticable to apply IFRS 17 fully retrospectively an entity can adopt:
- the modified retrospective approach, or
- the fair value approach. [IFRS 17: C5]
The choice of transition method is made at the level of a group of contracts. [IFRS 17: C5]
The modified retrospective approach (MRA) permits specific modifications to retrospective application. They allow an entity to determine specified matters at the transition date rather than at initial recognition of a group of insurance contracts and use specified proxies for some requirements.
Under the fair value approach (FVA), IFRS 17 requires an entity to determine the contractual service margin (CSM) or loss component of the liability for remaining coverage at the transition date. This is calculated as the difference between the measurement of the fair value of a group of insurance contracts and the fulfilment cash flows of the group as at that date. [IFRS 17: C20]
Disclosures
An entity is required to explain how it determined the measurement of insurance contracts at the transition date, to enable users to understand the nature and significance of the methods used and judgements made. [IFRS 17: 115]
An entity is required to disclose separate reconciliations of the CSM and insurance revenue for:
- insurance contracts that existed at the transition date to which the entity has applied the MRA;
- insurance contracts that existed at the transition date to which the entity has applied the FVA; and
- all other insurance contracts. [IFRS 17: 114]
Additional disclosures are required for groups of insurance contracts for which the entity disaggregates insurance finance income or expenses between profit or loss and other comprehensive income. [IFRS 17: 116]
Accounting impact
The FVA may result in more significant measurement differences compared to the full retrospective approach (FRA) or MRA. IFRS 13 *Fair Value Measurement
-
indicates that the fair value includes the profit margin required by a market participant to accept the obligations under the insurance contracts. Therefore, a CSM is likely to arise under the FVA, whereas if the same groups of contracts were measured under the FRA or MRA no CSM might be recognised. An entity's choice between transition approaches will impact shareholder's equity on transition and the release of profit in subsequent periods from the insurance contracts in force at transition. Profits from some groups of insurance contracts may be recognised as an adjustment to equity on transition, bypassing profit or loss. Profits on other groups may be recognised in profit or loss twice, once under IFRS 4 *Insurance Contracts
-
and again through the CSM under IFRS 17.
The higher the CSM on transition, the lower the accumulated profit from groups of insurance contracts recognised in shareholders' equity and the more profit to be recognised in future periods. This may impact the ability of insurers to pay dividends, meet solvency capital requirements or the determination of tax payments. There may also be implications for users of financial statements, in terms of assessing performance of the entity on transition and at future dates.
The cost and complexity of the different transition approaches will depend on an entity's circumstances. It is likely to be more expensive to apply the FRA or MRA to insurance contracts issued a significant time before the transition date, whereas the FVA may be more complex than the FRA or MRA for short term contracts and contracts issued close to transition, where the availability of information is greater.
Assessment against the technical accounting criteria
Restating comparatives for all in-force contracts at transition is expected to give rise to consistent reporting before and after transition, leading to increased relevance and comparability of results.
Retrospective application is considered to result in relevant and reliable information because insurance contracts would be recognised and measured as if IFRS 17 had always been applied. The MRA is not considered to result in significantly less relevant or reliable information than the FRA because it enables entities to achieve the closest outcome to a full retrospective application, without undue cost or effort.
The conditional alternatives permitted under the transition requirements can give rise to a possible impact on comparability because of the resulting diversity in practice.
The FVA is not a proxy for the FRA or MRA and therefore will not result in an application that is directly comparable. Whilst the MRA intends to achieve an outcome as close to the FRA as possible, using specified simplifications, the FVA aims to determine the CSM in the absence of historical cash flow information. For example, when measuring groups of onerous contracts at the transition date, applying the market participant's view under the FVA is likely to result in recognition of a CSM, because the market participant will need to be compensated to take on the insurance obligations. Therefore, future profits will be recorded on these previously onerous groups of contracts. These profits would not have arisen had a retrospective approach been followed.
The availability of the FVA option may reduce the application of the MRA, as preparers elect to apply the FVA, avoiding the need to obtain historical cash flow information and incur associated costs.
There is a potential risk that the availability of a choice between the MRA and the FVA will reduce the reliability of financial information because preparers may have an incentive to apply an approach because of the impact it has on reported performance. Further, it may be difficult to measure reliably the fair value of insurance contracts under the FVA because there is a lack of observable market inputs and the FVA will require a high degree of judgement.
The IASB acknowledged that the choice of transition methods would reduce comparability but noted that if an entity has relatively little reasonable and supportable information available, and would therefore need to use many of the permitted modifications, the cost of the MRA might exceed the benefits. [IFRS 17: BC373]
The comparability effects are therefore mitigated by the benefits in terms of practicality, which significantly enhance reliability because reliable information cannot be provided in the absence of the required information.
In addition, the reduced comparability could be mitigated by the separate disclosures required for each transition approach that an entity applies. Disclosures are required to enable users to understand the nature and significance of the methods used and judgements applied. These will increase the reliability, understandability and comparability of the financial statements because they require the separate presentation of different groups of contracts, facilitating analysis and comparison.
Other VFA issues: (i) Ineligibility of reinsurance contracts for VFA
IFRS 17 requirements
The variable fee approach (VFA) was introduced to account for insurance contracts with direct participation features. In these contracts, the insurer shares in the performance of underlying items with the policyholders. The VFA modifies the general measurement model (GMM) in IFRS 17 to reflect that these contracts are substantially investment-related service contracts, and that the entity charges a fee for those services, based on its share of the fair value of the underlying items.
IFRS 17 defines insurance contracts with direct participation features [IFRS 17: B101] and requires the VFA eligibility assessment to be performed at an individual contract level.
Reinsurance contracts held and reinsurance contracts issued cannot be insurance contracts with discretionary participation features under IFRS 17 [IFRS 17: B109] and are therefore ineligible for the VFA. The IASB noted that an entity and the reinsurer do not share in the returns on underlying items, so reinsurance contracts held do not meet the VFA eligibility criteria in paragraph B101 of IFRS 17. Furthermore, the IASB considered that a reinsurance contract held should be accounted for separately from the underlying insurance contracts issued. [IFRS 17: BC248]
Disclosures
Entities applying the VFA are required to make additional disclosures about the composition of the underlying items and their fair value. [IFRS 17: 111]
If an entity chooses to apply the risk mitigation option (RMO) in paragraph B115 of IFRS 17, it is required to disclose the effect of that choice on the adjustment to the contractual service margin (CSM) in the current period. [IFRS 17: 112]
Accounting impact
Reinsurance contracts held are measured under the GMM. When underlying business is measured under the VFA this can give rise to accounting mismatches in respect of the treatment of changes in financial risks. Under the VFA, the impact of changes in financial risks (including the time value of money) adjust the CSM [IFRS 17: 45; B113], whereas under the GMM the impact of such changes is recognised directly in profit or loss.
Subject to certain conditions in paragraph B116 of IFRS 17, the standard permits the use of the RMO to reduce any accounting mismatches. Under the RMO, when applying the VFA an entity may choose not to recognise in the CSM the effect of some or all of the changes in the time value of money and financial risk on the entity's share of underlying items and the fulfilment cash flows. The effect is instead recognised directly in profit or loss [IFRS 17: B115], as it is under the GMM.
The RMO may be applied when reinsurance contracts held are used to mitigate financial risk as part of a previously documented risk-management objective and strategy. [IFRS 17: B116]
Feedback received notes that there are instances of reinsurance transactions in the UK when the reinsurer is responsible for tracking and providing the benefits that are ultimately paid under the underlying VFA contracts. This might occur, for example, in intra-group reinsurance arrangements or when a book of with-profits business is disposed of and reinsurance is put in place prior to a formal legal transfer becoming effective. In such instances, some stakeholders consider the reinsurance contracts might meet the VFA eligibility criteria described in paragraph B101 of IFRS 17, but this would be overridden by the prohibition imposed by paragraph B109 of IFRS 17.
Assessment against the technical accounting criteria
In principle, the inability to apply the same measurement model to the underlying insurance contracts and the corresponding reinsurance contracts held may result in accounting mismatches that are difficult to explain to users of financial statements, reducing their understandability.
However, accounting for reinsurance contracts held independently from the corresponding underlying contracts issued appropriately reflects the entity's separate contractual rights and obligations, thereby ensuring a more faithful representation thus enhancing reliability.
Accounting for the reinsurance contract held under the VFA simply because the underlying contracts were eligible for the VFA would not give a faithful representation of the entity's contractual position (because the entity and the reinsurer do not share in the returns on underlying items) and hence could impair reliability.
When reinsurance is a means of transferring the economic risk and reward of the underlying VFA portfolio to the reinsuring entity, such contracts could meet the VFA eligibility criteria set out in IFRS 17. However, the specific prohibition on measuring reinsurance under the VFA may result in such contracts being accounted for under a measurement model that does not reflect the intended economic effect of the transaction. In such instances the information is likely to be less relevant.
However, application of the RMO is expected to eliminate most of the accounting mismatches that could arise from applying the VFA to the underlying insurance contracts and the GMM to the reinsurance contracts held, although it may not remove them entirely. IFRS 17 therefore provides a means to mitigate this risk to relevance.
Furthermore, if such mismatches arise from intra-group arrangements they are unlikely to affect the consolidated accounts prepared for investors and other external users of the accounts. If residual mismatches arise in connection with disposals, they are likely to be short-term and if material can be explained by way of additional disclosures.
Removing the prohibition on applying the VFA to reinsurance contracts might give rise to other unintended consequences that would need addressing.
Other VFA issues: (ii) Prohibition of retrospective application of the risk mitigation option
IFRS 17 requirements
Under the variable fee approach (VFA), the impact of changes in financial risk on the entity's share of underlying items adjusts the contractual service margin (CSM). If an entity uses certain contracts to mitigate financial risk, however, the impact of changes in financial risk on those items is recognised directly in profit or loss. Subject to certain conditions in paragraph B116 of IFRS 17, the standard permits an entity, when using the VFA, to apply the risk mitigation option (RMO) to reduce such accounting mismatches. Applying the RMO, an entity may choose not to recognise in the CSM the effect of some or all of the changes in the time value of money and financial risk. The effect is instead recognised directly in profit or loss. [IFRS 17: B115]
The RMO is available to entities that mitigate the effect of financial risk on either the amount of the entity's share of the underlying items or the fulfilment cash flows set out in paragraph B113(b) of IFRS 17, provided that the entity uses derivatives, reinsurance contracts held or non-derivative financial instruments measured at fair value through profit or loss for risk mitigation. [IFRS 17: B115, B116]
IFRS 17 does not permit entities to apply the RMO to periods before the transition date. Entities can apply the RMO prospectively on or after the date of transition as long as the risk mitigation relationships are designated before application. [IFRS 17: C3(b)]
If certain conditions are met, an entity that could otherwise apply IFRS 17 retrospectively is permitted instead to apply the fair value transition approach to groups of insurance contracts with direct participation features. The conditions are that the entity must choose to apply the RMO to the groups prospectively from the transition date and, prior to the transition date, the entity must have been using derivatives, reinsurance contracts held or non-derivative financial instruments measured at fair value through profit or loss to mitigate financial risk arising from the group of insurance contracts. [IFRS 17: C5A]
Disclosures
If an entity chooses not to adjust the CSM for some changes in the fulfilment cash flows, applying paragraph B115 (i.e. applying the RMO), it must disclose the effect of that choice on the adjustment to the CSM in the current period.
Accounting impact
The inability to apply the RMO in periods before the transition date may result in mismatches between changes in the value of assets and liabilities, even though entities may have adopted risk mitigation strategies. The impact of changes in financial variables on insurance liabilities will be recognised in the CSM on transition, but the corresponding impact of changes in measurement of related assets will be recognised in retained earnings.
Applying the fair value approach to transition, this mismatch does not exist because the group of insurance contracts will be measured using current estimates of financial assumptions and the derivatives (or the non-derivative financial instruments) will be measured at fair value. Therefore, equity on the transition date reflects the impact of previous changes in financial variables on both the fulfilment cash flows and the fair value of the financial instruments.
Assessment against the technical accounting criteria
Stakeholders have expressed concerns that the inability to apply the RMO to periods prior to transition will lead to a distortion of brought-forward amounts, in particular retained earnings and the CSM. Mismatches between changes in value of assets and liabilities may arise on transition even when entities are adopting risk mitigation strategies. The presence of these accounting mismatches may make financial statements less understandable to users.
The RMO was introduced to more effectively represent the economic effects of the entity's transactions and therefore to reduce accounting mismatches arising from the treatment of insurance liabilities and the instruments used to hedge them. The inability to apply the RMO retrospectively could result in less relevant information as accounting mismatches could arise on transition to IFRS 17.
However, consistent with the transition requirements for hedge accounting in IFRS 9 Financial Instruments, the IASB concluded that retrospective application of the RMO would give rise to the risk of use of hindsight. This risk is heightened by the fact that the application of the RMO is optional and documentation after the event would enable entities to elect the risk mitigation relationships to which they would apply the option (IFRS 17: BC393). Therefore, prohibiting retrospective application of the RMO reduces the risk of bias and therefore promotes more reliable financial information.
The prohibition of retrospective application of the RMO has the potential to reduce comparability between the accounting for groups of insurance contracts for which entities apply risk mitigation before and after the transition date (IFRS 17: BC393B). The RMO can be applied prospectively, reducing accounting mismatches arising on or after the transition date, but accounting mismatches present prior to transition will not be eligible to be mitigated.
However, if it had been permitted, retrospective application of the RMO would have been optional, so might have given rise to other concerns about comparability in any event. Further, the option to apply the fair value approach to transition under IFRS 17: C5A will enable entities to avoid the distortion related to risk mitigation activities from previous periods. This option may be appropriate in some circumstances and for some types of contracts, mitigating concerns over the relevance of financial information.
Other VFA issues: (iii) Eligibility for VFA when there are mutualised cash flows
IFRS 17 requirements
IFRS 17 requires insurance contracts with direct participation features to be accounted for under the variable fee approach (VFA). Contracts with direct participation features are substantially investment-related service contracts under which an entity promises an investment return based on underlying items. These contracts are characterised by: the policyholder participating in a share of a clearly identifiable pool of underlying items; the expectation that the policyholder will receive a substantial share of the fair value returns on the underlying items; and the payments to policyholders varying with the change in fair value of the underlying items. [IFRS 17: B101]
Paragraph B107 of IFRS 17 requires an entity to perform the assessment for VFA eligibility at a contract level, rather than at the level of the group of insurance contracts.
If insurance contracts in a group affect the cash flows to policyholders of contracts in other groups, when assessing whether an insurance contract meets the eligibility requirements for the VFA, the standard requires an entity to consider the cash flows that the entity expects to pay the policyholders determined by applying paragraphs B68-B70. [IFRS 17: B103]
Paragraph B69 of IFRS 17 sets out the following simplified example of contracts with cash flows that affect or are affected by cash flows to policyholders of other contracts:
- An entity has 2 groups of insurance contracts (Group A and Group B) where the policyholders share returns on the same specified pool of underlying items and some policyholders are required to bear a reduction in their share of the return because of guaranteed payments to other policyholders. In this case the future payments to policyholders in Group A are expected to be reduced from a share in the returns on underlying items of CU350 to CU250 because of payments of a guaranteed amount to policyholders in Group B. The fulfilment cash flows of Group A would include the payment of CU100 (i.e. would be CU 350) and the fulfilment cash flows of Group B would exclude the amount of CU100.
Accounting impact
The eligibility assessment under IFRS 17: B101 determines whether contracts are measured using the VFA. In the case of mutualised insurance contracts, two opposing views have arisen to determine the cash flows the entity expects to pay to the policyholder when performing the VFA eligibility assessment:
- Approach 1: The amounts include only those the entity expects to pay to the current policyholders of the contracts in the group (i.e. the post-mutualisation cash flows of CU250 in the example above).
- Approach 2: The amounts include all the cash flows the entity expects to pay to all policyholders – those in the group and those in other groups that the cash flows are shared with – in the current and future periods (i.e. the pre-mutualisation cash flows of CU350 in the example above).
Stakeholders note that the example in B69 (see above) does not necessarily indicate the correct approach to the VFA eligibility assessment since B69 is in a section of IFRS 17 dealing with which cash flows are within the contract boundary, rather than VFA eligibility.
Stakeholders suggest that Approach 2 (performing the VFA eligibility assessment based on pre-mutualisation cash flows) will result in more contracts being eligible for the VFA than Approach 1.
On transition to IFRS 17, the date of assessment for VFA eligibility of a contract depends on the transition approach applied. The assessment date used may also affect whether or not a contract meets the VFA eligibility requirements. For example, a savings contract with investment guarantees which are in-the-money at the transition date but not in the money at inception might satisfy the variability criterion under B101(c) if assessed at inception but not if assessed at the transition date.
The VFA eligibility assessment is particularly relevant to UK with-profits business. Although most UK with-profits funds are closed to new business, there are still significant assets under management within with-profits funds where there is mutualisation of cash flows.
Assessment against the technical accounting criteria
The relevance and understandability of financial information is increased if insurance contracts are accounted for under an accounting model that is designed for the characteristics of the insurance contracts. The VFA eligibility criteria help ensure that the VFA is applied only to contracts that are substantially investment-related service contracts with direct participation features. Stakeholder feedback indicates that Approach 2 above is likely to lead to appropriate accounting outcomes for many products.
IFRS 17 may be open to interpretation when determining which estimated cash flows to include when performing the VFA eligibility assessment. There is a risk that the different interpretations of the standard's requirements will result in a divergence in practice, reducing comparability, because insurance contracts sharing similar characteristics will be accounted for under different measurement models by different entities.
However, the assessment of VFA eligibility is already an area of significant judgement so this particular aspect of the assessment may not result in a material additional impairment of comparability. Further, stakeholder feedback suggests that, when facts and circumstance align, there is likely to be industry consensus on the applicable approach, mitigating concerns about comparability.
The fact that different approaches to transition may affect the VFA eligibility assessment also has the potential to result in inconsistent application in practice, reducing comparability.
However, when an entity does not have reasonable and supportable information to apply a fully retrospective transition approach, the choice of which date to apply the VFA eligibility assessment on transition permits entities to apply judgement and measure the contracts under the measurement model that more closely aligns with the characteristics of the contracts, thereby enhancing relevance.
Other VFA issues: (iv) Non-profit contracts written by a with-profits fund
IFRS 17 requirements
As noted above (see Other VFA issue (iii): Eligibility for VFA when there are mutualised cash flows), IFRS 17 requires insurance contracts with direct participation features to be accounted for under the variable fee approach (VFA). Contracts with direct participation features are substantially investment-related service contracts under which an entity promises an investment return based on underlying items.
These contracts are characterised by: the policyholder participating in a share of a clearly identifiable pool of underlying items; the expectation that the policyholder will receive a substantial share of the fair value returns on the underlying items; and the payments to policyholders varying with the change in fair value of the underlying items. [IFRS 17: B101]
For insurance contracts with direct participation features, the contractual service margin (CSM) is adjusted by the change in the amount of the entity's share of the fair value of the underlying items [IFRS 17: 45(b)]. The entity's obligation to the policyholder is the net of (a) the obligation to pay the policyholder an amount equal to the fair value of the underlying items and (b) a variable fee that the entity deducts from (a). [IFRS 17: B104]
In some cases, non-participating insurance contracts ('non-profit contracts') have been written by with-profits funds. Under these arrangements, profits and losses from such non-profit contracts sometimes accrue to an inherited estate, and sometimes to the with-profits policyholders. In the latter case, this means that the non-profit contracts function as underlying items for the with-profits contracts.
IFRS 17 does not include any specific requirements addressing this scenario.
Accounting impact
In cases when surpluses from non-profit contracts accrue to with-profits policyholders, as 'underlying items' for the with-profits contracts the non-profit contracts must be measured at fair value for the purpose of the VFA accounting. This may result in an accounting mismatch with the measurement of the non-profit contracts as insurance contracts in their own right under IFRS 17.
For example, the measurement of the non-profit contracts as insurance contracts will generally involve the release of risk adjustment and CSM to profit as revenue. These amounts are unlikely to precisely match (offset) the change in their fair value as underlying items, reflected in the VFA accounting for the with-profits contracts and included as insurance finance expense. While ultimately a timing issue which unwinds, the mismatch will impact reported profit for the periods affected.
Assessment against the technical accounting criteria
Stakeholders acknowledged the likelihood of accounting mismatches arising under IFRS 17, as described above. In principle, accounting standards should avoid creating accounting mismatches, as they can impair relevance and understandability.
However, mismatches in some specific cases are an inevitable consequence of the mixed measurement framework that underpins IFRS.
In discussions with stakeholders at the UKEB's Insurance Technical Advisory Group, members of that group noted that such an accounting mismatch might also occur with other types of underlying items, whenever such investment assets were not accounted for at fair value. Further, these stakeholders noted that accounting mismatches occurred in other areas of accounting so the scenario was not unique.
In considering this issue during the finalisation of the standard, the IASB decided not to create exceptions to the normal requirements because doing so would add significant complexity to the standard and would risk unduly disrupting implementation.
We understand that this specific issue affects only a very small number of entities and, overall, risks to relevance and understandability need to be balanced against the objective of reducing complexity.
Contact Us
UK Endorsement Board 1 Victoria Street
| London | SW1H 0ET | United Kingdom
[email protected]
Web: www.endorsement-board.uk
IFRS 17 Insurance Contracts Endorsement Criteria Assessment (ECA)
May 2022
- Executive Summary
- Introduction
- Documents for noting and approval
- Voting on the adoption of IFRS 17 Insurance Contracts
- Next Steps
- Disclaimer
- Executive Summary
- I. Legislative framework and our approach to the assessment
- Understandability, relevance, reliability and comparability
- Whether IFRS 17 is likely to be conducive to the long term public good in the UK
- The standard is not contrary to the true and fair view requirement for individual and consolidated financial statements
- Structure of this Endorsement Criteria Assessment
- 2 Description of IFRS 17
- 2 – Variable Fee Approach (VFA)
- 3 – Premium Allocation Approach (PAA)
- 3 Technical accounting criteria assessment
- Priority issues
- A: Profit recognition – CSM allocation for annuities
- Initial recognition
- Subsequent measurement
- Insurance coverage
- Investment return service
- Disclosures
- Determination of CSM amortisation – accounting impact
- Initial recognition
- Subsequent measurement
- Recognition of insurance coverage service
- Assessment against the endorsement criteria
- Potential challenges to the endorsement criteria and mitigations
- B: Discount rates
- C: Grouping insurance contracts: profitability buckets and annual cohorts
- D: With-profits: inherited estates
- Overall conclusion on whether IFRS 17 meets the technical accounting criteria
- 4 UK long term public good assessment
- Basis for adoption of international accounting standards
- Structure of the assessment
- The UK insurance sector
- Relevant population of insurers
- Lloyd's of London
- Other entities
- UK branches of foreign entities
- Companies with limited insurance activities (‘non-insurance companies')
- Will IFRS 17 improve the quality of financial reporting?
- Costs and benefits of applying IFRS 17
- Ongoing costs
- Other external sources relating to costs for insurance companies
- SAS Perspectives and approaches to IFRS 17 (2018)
- Benefits
- SAS - A Transformation in Progress - Perspectives and approaches to IFRS 17 (2018)
- Other stakeholders
- Summary of costs and benefits for stakeholders
- Likely effect on the economy of the UK
- Introduction
- Potential impact on business conducted by UK insurance industry
- Onerous contracts
- Effects on competitive landscape of UK insurance industry
- Consideration of the consequences of not adopting the standard
- Overall conclusion on UK long term public good
- Overall conclusion on UK long term public good
- 5 True and fair view assessment
- Appendix A - Glossary
- Appendix B - Assessment of remaining significant issues
- Risk adjustment for non-financial risk
- Interest accretion at the locked-in rate for CSM under the GMM
- Recognition of income from reinsurance to match losses from onerous underlying contracts
- Contracts acquired in their settlement period
- Contracts that change nature over time
- Reinsurance to close (RITC) transactions in the Lloyd's market
- Other comprehensive income option
- Transition requirements
- Other VFA issues: (i) Ineligibility of reinsurance contracts for VFA
- Other VFA issues: (ii) Prohibition of retrospective application of the risk mitigation option
- Other VFA issues: (iii) Eligibility for VFA when there are mutualised cash flows
- Other VFA issues: (iv) Non-profit contracts written by a with-profits fund
- Foreword
- The UK Endorsement Board (UKEB)
- Executive summary
- Principal objective of IFRS 17
- Summary of IFRS 17 principles
- Summary of outreach prior to draft ECA
- UKEB public consultation on the draft ECA
- Our approach to the assessment
- Summary of outreach prior to draft ECA
- UKEB public consultation on the draft ECA
- Our approach to the assessment
- Overall conclusions – Technical accounting criteria
- Overall conclusions – Technical accounting criteria
- Summary of outreach prior to draft ECA
- UKEB public consultation on the draft ECA
- Our approach to the assessment
- UK-adopted international accounting standards: International Financial Reporting Standard 17—Insurance Contracts
- Recognition
- Insurance acquisition cash flows (paragraphs B35A-B35D)
- Measurement (paragraphs B36-B119F)
- Measurement on initial recognition (paragraphs B36-B95F)
- Estimates of future cash flows (paragraphs B36-B71)
- Discount rates (paragraphs B72-B85)
- Risk adjustment for non-financial risk (paragraphs B86-B92)
- Contractual service margin
- Subsequent measurement
- Contractual service margin (paragraphs B96-B119B)
- Onerous contracts
- Premium allocation approach
- Reinsurance contracts held
- Recognition
- Measurement
- Premium allocation approach for reinsurance contracts held
- Investment contracts with discretionary participation features
- Modification and derecognition
- Modification of an insurance contract
- Derecognition
- Presentation in the statement of financial position
- Recognition and presentation in the statement(s) of financial performance (paragraphs B120-B136)
- Disclosure
- Explanation of recognised amounts
- Insurance finance income or expenses
- Transition amounts
- Significant judgements in applying IFRS 17
- Nature and extent of risks that arise from contracts within the scope of IFRS 17
- All types of risk—concentrations of risk
- Insurance and market risks—sensitivity analysis
- Insurance risk—claims development
- Credit risk—other information
- Liquidity risk—other information
- Appendix A Defined terms
- Appendix B
- Definition of an insurance contract (Appendix A)
- Separating components from an insurance contract (paragraphs 10–13)
- Insurance acquisition cash flows (paragraphs 28A-28F)
- Measurement (paragraphs 29–71)
- Non-market variables
- Using current estimates (paragraph 33(c))
- Cash flows within the contract boundary (paragraph 34)
- Contracts with cash flows that affect or are affected by cash flows to policyholders of other contracts
- Discount rates (paragraph 36)
- Risk adjustment for non-financial risk (paragraph 37)
- Initial recognition of transfers of insurance contracts and business combinations (paragraph 39)
- Changes in the carrying amount of the contractual service margin for insurance contracts without direct participation features (paragraph 44)
- Appendix C
- Effective date and transition
- Effective date
- Transition
- Determining the contractual service margin or loss component for groups of insurance contracts with direct participation features
- Insurance finance income or expenses
- Fair value approach
- Asset for insurance acquisition cash flows
- Comparative information
- Entities that first apply IFRS 17 and IFRS 9 at the same time
- Redesignation of financial assets
- Withdrawal of other IFRS Standards
Foreword
"The UK Endorsement Board is pleased to present a summary of the feedback received from UK stakeholders on the draft Endorsement Criteria Assessment (ECA) for IFRS 17 Insurance Contracts.
We are grateful for the constructive and insightful views from UK stakeholders at such a critical stage in this endorsement project.
Stakeholder views are summarised in this Feedback Statement and, where appropriate, have been addressed in the final ECA.
We look forward to continuing to engage with UK stakeholders during the implementation and initial application of the Standard.”
Pauline Wallace,
Chair, UK Endorsement Board
The UK Endorsement Board (UKEB)
The UKEB is responsible for endorsement and adoption of IFRS for use in the UK and is therefore the UK's National Standard Setter for IFRS. The UKEB also leads the UK's engagement with the IFRS Foundation on the development of new standards, amendments and interpretations.
The purpose of this Feedback Statement
This document presents the views of UK stakeholders received during the UKEB's public consultation on the draft ECA of IFRS 17 Insurance Contracts (IFRS 17) and explains how the UKEB has addressed those views in the final ECA.
Executive summary
| Page | |
|---|---|
| Summary of IFRS 17 objective and principles | 6-7 |
| Summary of outreach prior to draft ECA | 8 |
| UKEB public consultation on the draft ECA | 9 |
| Our approach to the assessment | 10 |
| Overall conclusions | 11-14 |
Principal objective of IFRS 17
IFRS 17 establishes principles for the recognition, measurement, presentation and disclosure of insurance contracts within the scope of the Standard.
The objective of the Standard, as set out by the IASB, is to ensure that an entity provides relevant information that faithfully represents those insurance contracts.
Such information gives a basis for users of financial statements to assess the effect that insurance contracts have on the entity's financial position, financial performance and cash flows.
Summary of IFRS 17 principles
The key principles of IFRS 17 are that an entity:
i. Identifies its insurance contracts within the scope of the Standard (and separates non-insurance components which are accounted for under other relevant IFRS Standards).
ii. Divides the insurance contracts into groups and measures them at: * A current estimate of the future cash flows (including adjustments for the timing and risk of those cash flows); and * An amount representing the unearned profit relating to services still to be provided (the contractual service margin).
iii. Recognises the profit from a group of insurance contracts over the period the entity provides insurance contract services, and as the entity is released from risk. If a group of contracts is or becomes loss-making, an entity recognises the loss immediately.
iv. Presents separately insurance revenue, insurance service expenses and insurance finance income or expenses.
v. Discloses information that gives a basis for users of financial statements to assess the effects that insurance contracts have on the entity's financial position, financial performance and cash flows.
- Identifies its insurance contracts within the scope of the Standard (and separates non-insurance components which are accounted for under other relevant IFRS Standards).
- Divides the insurance contracts into groups and measures them at:
- A current estimate of the future cash flows (including adjustments for the timing and risk of those cash flows); and
- An amount representing the unearned profit relating to services still to be provided (the contractual service margin).
- Recognises the profit from a group of insurance contracts over the period the entity provides insurance contract services, and as the entity is released from risk. If a group of contracts is or becomes loss-making, an entity recognises the loss immediately.
- Presents separately insurance revenue, insurance service expenses and insurance finance income or expenses.
- Discloses information that gives a basis for users of financial statements to assess the effects that insurance contracts have on the entity's financial position, financial performance and cash flows.
Summary of outreach prior to draft ECA
Preparers
- Preparer webinar
- 100 registrations / 129 views
- Joint webinar with IASB
- Preparer survey
- 16 respondents
- Qualitative and quantitative information gathered
- Preparer interviews
- 23 one to one meetings
- Follow-up to survey and technical analysis
Investors/other users
- Investor webinar
- 159 registrations / 525 views
- Joint webinar with IASB, analyst and ratings agency
- User survey
- 21 respondents
- Survey to gather qualitative responses
- User roundtable
- 11 users participated
- Joint discussion on key themes identified in User survey
- User interviews
- 14 one to one meetings
- Structured interviews to gather investor perspectives
Other elements
- Economic Report
- Data gathering and analysis by external consultants to assess the potential economic impact of IFRS 17 on the UK
- Insurance Technical Advisory Group (TAG)
- 10 TAG meetings
- Diverse group of insurance specialists providing specialist knowledge and technical advice
- Other discussions
- Periodic calls with other stakeholders including audit firms, regulators and an industry body (Association of British Insurers)
- International liaison
- Periodic liaison with the European Financial Reporting Advisory Group (EFRAG) and other National Standard Setters
UKEB public consultation on the draft ECA
The UKEB's public consultation on its draft IFRS 17 ECA took place between 11 November 2021 and 3 February 2022.
All stakeholder comments received by the UKEB were considered in reaching the UKEB's final assessment of the Standard. Stakeholder submissions received were made public* on the UKEB website.
During the consultation period, the UKEB and its Secretariat promoted awareness of its draft IFRS 17 ECA and encouraged stakeholders to respond through News Alerts, speaking engagements, ongoing outreach to UK stakeholders and advertising through the usual channels.
| Stakeholder type | Number of responses |
|---|---|
| Users of accounts (including 3 representative bodies**) | 6 |
| Preparers of accounts (including 2 representative bodies**) | 7 |
| Accounting firms | 6 |
| Professional bodies | 2 |
| Total | 21 |
* Except for those from two respondents who requested that their comments were not shared publicly. ** Representative bodies represent the views of multiple members, often encompassing a variety of stakeholder types.
Our approach to the assessment
Do you have any comments on our approach to the assessment presented in Section 1 of our [Draft] Endorsement Criteria Assessment (ECA)? [Q.1]
| UKEB tentative assessment | Stakeholder views | UKEB final assessment | | --- | --- | | Summary of IFRS 17 principles | |
The key principles of IFRS 17 are that an entity:
- Identifies its insurance contracts within the scope of the Standard (and separates non-insurance components which are accounted for under other relevant IFRS Standards).
- Divides the insurance contracts into groups and measures them at:
- A current estimate of the future cash flows (including adjustments for the timing and risk of those cash flows); and
- An amount representing the unearned profit relating to services still to be provided (the contractual service margin).
- Recognises the profit from a group of insurance contracts over the period the entity provides insurance contract services, and as the entity is released from risk. If a group of contracts is or becomes loss-making, an entity recognises the loss immediately.
- Presents separately insurance revenue, insurance service expenses and insurance finance income or expenses.
- Discloses information that gives a basis for users of financial statements to assess the effects that insurance contracts have on the entity's financial position, financial performance and cash flows.
Summary of outreach prior to draft ECA
Preparers
- Preparer webinar
- 100 registrations / 129 views
- Joint webinar with IASB
- Preparer survey
- 16 respondents
- Qualitative and quantitative information gathered
- Preparer interviews
- 23 one to one meetings
- Follow-up to survey and technical analysis
Investors/other users
- Investor webinar
- 159 registrations / 525 views
- Joint webinar with IASB, analyst and ratings agency
- User survey
- 21 respondents
- Survey to gather qualitative responses
- User roundtable
- 11 users participated
- Joint discussion on key themes identified in User survey
- User interviews
- 14 one to one meetings
- Structured interviews to gather investor perspectives
Other elements
- Economic Report
- Data gathering and analysis by external consultants to assess the potential economic impact of IFRS 17 on the UK
- Insurance Technical Advisory Group (TAG)
- 10 TAG meetings
- Diverse group of insurance specialists providing specialist knowledge and technical advice
- Other discussions
- Periodic calls with other stakeholders including audit firms, regulators and an industry body (Association of British Insurers)
- International liaison
- Periodic liaison with the European Financial Reporting Advisory Group (EFRAG) and other National Standard Setters
UKEB public consultation on the draft ECA
The UKEB's public consultation on its draft IFRS 17 ECA took place between 11 November 2021 and 3 February 2022.
All stakeholder comments received by the UKEB were considered in reaching the UKEB's final assessment of the Standard. Stakeholder submissions received were made public* on the UKEB website.
During the consultation period, the UKEB and its Secretariat promoted awareness of its draft IFRS 17 ECA and encouraged stakeholders to respond through News Alerts, speaking engagements, ongoing outreach to UK stakeholders and advertising through the usual channels.
| Stakeholder type | Number of responses |
|---|---|
| Users of accounts (including 3 representative bodies**) | 6 |
| Preparers of accounts (including 2 representative bodies**) | 7 |
| Accounting firms | 6 |
| Professional bodies | 2 |
| Total | 21 |
* Except for those from two respondents who requested that their comments were not shared publicly. ** Representative bodies represent the views of multiple members, often encompassing a variety of stakeholder types.
Our approach to the assessment
Do you have any comments on our approach to the assessment presented in Section 1 of our [Draft] Endorsement Criteria Assessment (ECA)? [Q.1]
| UKEB tentative assessment | Stakeholder views | UKEB final assessment |
|---|---|---|
| Summary of IFRS 17 principles | ||
| The key principles of IFRS 17 are that an entity: | ||
| i. Identifies its insurance contracts within the scope of the Standard (and separates non-insurance components which are accounted for under other relevant IFRS Standards). | ||
| ii. Divides the insurance contracts into groups and measures them at: | ||
| • A current estimate of the future cash flows (including adjustments for the timing and risk of those cash flows); and | ||
| • An amount representing the unearned profit relating to services still to be provided (the contractual service margin). | ||
| iii. Recognises the profit from a group of insurance contracts over the period the entity provides insurance contract services, and as the entity is released from risk. If a group of contracts is or becomes loss-making, an entity recognises the loss immediately. | ||
| iv. Presents separately insurance revenue, insurance service expenses and insurance finance income or expenses. | ||
| V. Discloses information that gives a basis for users of financial statements to assess the effects that insurance contracts have on the entity's financial position, financial performance and cash flows. | ||
|
| UKEB tentative assessment | Stakeholder views | UKEB final assessment | |:---------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------|:------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------ | The UKEB's assessment of the requirements of its statutory obligations in relation to the true and fair view principle are reflected in the final ECA. Prudence is not one of the criteria set out in Sl 2019/685. The UKEB's assessment is only against those criteria specified in the SI. The description of the approach to the true and fair view assessment has been revised to ensure it fully and accurately reflects the UKEB's assessment work. | | As the comment regarding the TAG was not related directly to a specific assessment in the DECA no changes were made in the final ECA. | | The technical accounting criteria assessment was completed in accordance with the criteria set out in SI 2019/685, which is separate from the IASB's Conceptual Framework and does not require or indicate a weighting between criteria. On this basis no amendment was made in the final ECA for this point. | | The UKEB considers it would be appropriate to address the power to amend standards for use in the UK in an ECA only in circumstances when such amendment was actively being considered. As that is not the case in respect of IFRS 17, no change was made in the final ECA. |
Overall conclusions – Technical accounting criteria
Do you agree with our overall [tentative] conclusion that IFRS 17 meets the criteria of understandability, relevance, reliability and comparability required of the financial information needed for making economic decisions and assessing the stewardship of management (paragraphs 3.158 – 3.161)? [Q.9]
| UKEB tentative assessment | Stakeholder views | UKEB final assessment | |:---------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------|:------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------ ------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------ | The UKEB's assessment of the requirements of its statutory obligations in relation to the true and fair view principle are reflected in the final ECA. Prudence is not one of the criteria set out in Sl 2019/685. The UKEB's assessment is only against those criteria specified in the SI. The description of the approach to the true and fair view assessment has been revised to ensure it fully and accurately reflects the UKEB's assessment work. | | As the comment regarding the TAG was not related directly to a specific assessment in the DECA no changes were made in the final ECA. | | The technical accounting criteria assessment was completed in accordance with the criteria set out in SI 2019/685, which is separate from the IASB's Conceptual Framework and does not require or indicate a weighting between criteria. On this basis no amendment was made in the final ECA for this point. | | The UKEB considers it would be appropriate to address the power to amend standards for use in the UK in an ECA only in circumstances when such amendment was actively being considered. As that is not the case in respect of IFRS 17, no change was made in the final ECA. |
Overall conclusions – Technical accounting criteria
Do you agree with our overall [tentative] conclusion that IFRS 17 meets the criteria of understandability, relevance, reliability and comparability required of the financial information needed for making economic decisions and assessing the stewardship of management (paragraphs 3.158 – 3.161)? [Q.9]
| UKEB tentative assessment | Stakeholder views | UKEB final assessment | |:---------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------|:---------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------- -----------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------## Summary of the public consultation on the UK Endorsement Board's (UKEB) draft statement on IFRS 17 Insurance Contracts
1. Introduction
1.1 Purpose of this document
The UK Endorsement Board (UKEB) is responsible for endorsing and adopting International Financial Reporting Standards (IFRSs) for use in the UK, as prescribed by Regulation 7 of the International Accounting Standards and European Public Limited-Liability Company (Amendment etc.) (EU Exit) Regulations 2019 (SI 2019/685) (the 'SI') which designates the UKEB as the UK body with responsibility for adopting International Accounting Standards and Interpretations. The UKEB is also responsible for monitoring and influencing the development of IFRSs internationally.
Before the UKEB can adopt an IFRS, the Regulation requires it to perform an Endorsement Criteria Assessment (ECA). This assessment considers whether the adoption of the IFRS would be:
- conducive to the long-term public good (LTPG) in the UK;
- consistent with the true and fair principle; and
- meet the technical accounting criteria specified in Regulation 7(1)(c) of the SI, namely that:
- the Standard is not contrary to the principle that a true and fair view must be given of the assets, liabilities, financial position and profit or loss of a company;
- the Standard is relevant to the needs of users of financial statements;
- the Standard is reliable; and
- the Standard is comparable and understandable.
In addition, the UKEB must also consider the costs and benefits of adopting the Standard. This document summarises the key findings from the UKEB's public consultation on its draft ECA for IFRS 17 *Insurance Contracts
- (the 'draft ECA'). The consultation invited stakeholders to respond to 19 questions, which covered the UKEB's assessment of IFRS 17 against the above criteria, as well as the proposed conclusion on whether the Standard should be adopted in the UK.
1.2 IFRS 17 Insurance Contracts
IFRS 17 *Insurance Contracts
- (IFRS 17 or the 'Standard') was issued by the International Accounting Standards Board (IASB) in May 2017 and is effective for annual periods beginning on or after 1 January 2023. IFRS 17 replaces IFRS 4 Insurance Contracts.
IFRS 17 applies to all insurance contracts (insurance and reinsurance) regardless of the type of entity that issues them, provided certain criteria are met. It provides comprehensive guidance on accounting for all aspects of insurance contracts by insurers, including recognition, measurement, presentation and disclosure. The objective of IFRS 17 is to provide relevant information that faithfully represents those contracts. This information gives a basis for users of financial statements to assess the effect that insurance contracts have on the entity's financial position, financial performance and cash flows.
2. Summary of IFRS 17 principles
The key principles of IFRS 17 are that an entity:
- Identifies its insurance contracts within the scope of the Standard (and separates non-insurance components which are accounted for under other relevant IFRS Standards).
- Divides the insurance contracts into groups and measures them at:
- A current estimate of the future cash flows (including adjustments for the timing and risk of those cash flows); and
- An amount representing the unearned profit relating to services still to be provided (the contractual service margin).
- Recognises the profit from a group of insurance contracts over the period the entity provides insurance contract services, and as the entity is released from risk. If a group of contracts is or becomes loss-making, an entity recognises the loss immediately.
- Presents separately insurance revenue, insurance service expenses and insurance finance income or expenses.
- Discloses information that gives a basis for users of financial statements to assess the effects that insurance contracts have on the entity's financial position, financial performance and cash flows.
Summary of outreach prior to draft ECA
Preparers
- Preparer webinar
- 100 registrations / 129 views
- Joint webinar with IASB
- Preparer survey
- 16 respondents
- Qualitative and quantitative information gathered
- Preparer interviews
- 23 one to one meetings
- Follow-up to survey and technical analysis
Investors/other users
- Investor webinar
- 159 registrations / 525 views
- Joint webinar with IASB, analyst and ratings agency
- User survey
- 21 respondents
- Survey to gather qualitative responses
- User roundtable
- 11 users participated
- Joint discussion on key themes identified in User survey
- User interviews
- 14 one to one meetings
- Structured interviews to gather investor perspectives
Other elements
- Economic Report
- Data gathering and analysis by external consultants to assess the potential economic impact of IFRS 17 on the UK
- Insurance Technical Advisory Group (TAG)
- 10 TAG meetings
- Diverse group of insurance specialists providing specialist knowledge and technical advice
- Other discussions
- Periodic calls with other stakeholders including audit firms, regulators and an industry body (Association of British Insurers)
- International liaison
- Periodic liaison with the European Financial Reporting Advisory Group (EFRAG) and other National Standard Setters
UKEB public consultation on the draft ECA
The UKEB's public consultation on its draft IFRS 17 ECA took place between 11 November 2021 and 3 February 2022.
All stakeholder comments received by the UKEB were considered in reaching the UKEB's final assessment of the Standard. Stakeholder submissions received were made public* on the UKEB website.
During the consultation period, the UKEB and its Secretariat promoted awareness of its draft IFRS 17 ECA and encouraged stakeholders to respond through News Alerts, speaking engagements, ongoing outreach to UK stakeholders and advertising through the usual channels.
| Stakeholder type | Number of responses |
|---|---|
| Users of accounts (including 3 representative bodies**) | 6 |
| Preparers of accounts (including 2 representative bodies**) | 7 |
| Accounting firms | 6 |
| Professional bodies | 2 |
| Total | 21 |
* Except for those from two respondents who requested that their comments were not shared publicly. ** Representative bodies represent the views of multiple members, often encompassing a variety of stakeholder types.
Our approach to the assessment
Do you have any comments on our approach to the assessment presented in Section 1 of our [Draft] Endorsement Criteria Assessment (ECA)? [Q.1]
| UKEB tentative assessment | Stakeholder views | UKEB final assessment | |:---------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------|:---------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------- ----------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------
|:---------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------|:------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------ ----------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------| | UKEB tentative assessment | Stakeholder views | UKEB final assessment | | The factors relevant to assessing the other significant issues presented in Appendix B of the DECA are the same as those set out in respect of the overall assessment against the technical accounting criteria – see slide 11. Overall, IFRS 17 meets the criteria of understandability, relevance, reliability and comparability required of the financial information needed for making economic decisions and assessing the stewardship of management. | Nine respondents (four preparers, three accounting firms and two professional bodies) agreed with the UKEB's tentative assessment. Ten respondents did not comment on this section. The remaining two respondents (one preparer and one industry representative body) agreed on most topics but did not agree with the UKEB's tentative assessment on the following: • Interest accretion at the locked-in rate for CSM under the GMM; • Contracts acquired in their settlement period; • Other VFA issues – Prohibition of retrospective application of the risk mitigation option. | Final assessment consistent with UKEB's tentative assessment. Analysis enhanced to reflect stakeholder feedback on the following: • Interest accretion at the locked-in rate for CSM under the GMM – Addition to note that using locked-in rather than current rates is expected to increase operational complexity. • Contracts acquired in their settlement period – clarification related to (i) understandability and comparability with other areas of accounting and with other IFRS reporters and (ii) enhancing transparency of financial information. • Other VFA issues: Prohibition of retrospective application of the risk mitigation option – clarification in relation to the reduction of the risk of bias and promoting reliable financial information. In addition, the information on RITC contracts is now presented as a separate topic. |
| UKEB tentative assessment | Stakeholder views | UKEB final assessment |
|---|---|---|
| UKEB tentative assessment | Stakeholder views | UKEB final assessment | |:------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------ | UKEB tentative assessment | Stakeholder views | Tentative Assessment | Stakeholder Views (from UKEB assessment) | UKEB Final Assessment | |:------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------| UKEB Final Assessment | UKEB final assessment | | :-------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------
| UKEB tentative assessment | Stakeholder views | UKEB final assessment | |:--------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------| UKEB final assessment | UKEB final assessment | UKEB final assessment | | :------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------ UKEB. (2023). IFRS 17 Insurance Contracts Initial Assessment. https://www.endorsement-board.uk/wp-content/uploads/2023/12/IFRS-17-Initial-Assessment.pdf
UK-adopted international accounting standards: International Financial Reporting Standard 17—Insurance Contracts
22 An entity shall not include contracts issued more than one year apart in the same group. To achieve this the entity shall, if necessary, further divide the groups described in paragraphs 16–21.
23 A group of insurance contracts shall comprise a single contract if that is the result of applying paragraphs 14–22.
24 An entity shall apply the recognition and measurement requirements of IFRS 17 to the groups of contracts determined by applying paragraphs 14–23. An entity shall establish the groups at initial recognition and add contracts to the groups applying paragraph 28. The entity shall not reassess the composition of the groups subsequently. To measure a group of contracts, an entity may estimate the fulfilment cash flows at a higher level of aggregation than the group or portfolio, provided the entity is able to include the appropriate fulfilment cash flows in the measurement of the group, applying paragraphs 32(a), 40(a)(i) and 40(b), by allocating such estimates to groups of contracts.
Recognition
25 An entity shall recognise a group of insurance contracts it issues from the earliest of the following:
- the beginning of the coverage period of the group of contracts;
- the date when the first payment from a policyholder in the group becomes due; and
- for a group of onerous contracts, when the group becomes onerous.
26 If there is no contractual due date, the first payment from the policyholder is deemed to be due when it is received. An entity is required to determine whether any contracts form a group of onerous contracts applying paragraph 16 before the earlier of the dates set out in paragraphs 25(a) and 25(b) if facts and circumstances indicate there is such a group.
27 [Deleted]
28 In recognising a group of insurance contracts in a reporting period, an entity shall include only contracts that individually meet one of the criteria set out in paragraph 25 and shall make estimates for the discount rates at the date of initial recognition (see paragraph B73) and the coverage units provided in the reporting period (see paragraph B119). An entity may include more contracts in the group after the end of a reporting period, subject to paragraphs 14–22. An entity shall add a contract to the group in the reporting period in which that contract meets one of the criteria set out in paragraph 25. This may result in a change to the determination of the discount rates at the date of initial recognition applying paragraph B73. An entity shall apply the revised rates from the start of the reporting period in which the new contracts are added to the group.
Insurance acquisition cash flows (paragraphs B35A-B35D)
28A An entity shall allocate insurance acquisition cash flows to groups of insurance contracts using a systematic and rational method applying paragraphs B35A–B35B, unless it chooses to recognise them as expenses applying paragraph 59(a).
28B An entity not applying paragraph 59(a) shall recognise as an asset insurance acquisition cash flows paid (or insurance acquisition cash flows for which a liability has been recognised applying another IFRS Standard) before the related group of insurance contracts is recognised. An entity shall recognise such an asset for each related group of insurance contracts.
28C An entity shall derecognise an asset for insurance acquisition cash flows when the insurance acquisition cash flows are included in the measurement of the related group of insurance contracts applying paragraph 38(c)(i) or paragraph 55(a)(iii).
28D If paragraph 28 applies, an entity shall apply paragraphs 28B–28C in accordance with paragraph B35C.
28E At the end of each reporting period, an entity shall assess the recoverability of an asset for insurance acquisition cash flows if facts and circumstances indicate the asset may be impaired (see paragraph B35D). If an entity identifies an impairment loss, the entity shall adjust the carrying amount of the asset and recognise the impairment loss in profit or loss.
28F An entity shall recognise in profit or loss a reversal of some or all of an impairment loss previously recognised applying paragraph 28E and increase the carrying amount of the asset, to the extent that the impairment conditions no longer exist or have improved.
Measurement (paragraphs B36-B119F)
29 An entity shall apply paragraphs 30–52 to all groups of insurance contracts within the scope of IFRS 17, with the following exceptions:
- for groups of insurance contracts meeting either of the criteria specified in paragraph 53, an entity may simplify the measurement of the group using the premium allocation approach in paragraphs 55–59.
- for groups of reinsurance contracts held, an entity shall apply paragraphs 32–46 as required by paragraphs 63–70A. Paragraph 45 (on insurance contracts with direct participation features) and paragraphs 47–52 (on onerous contracts) do not apply to groups of reinsurance contracts held.
- for groups of investment contracts with discretionary participation features, an entity shall apply paragraphs 32–52 as modified by paragraph 71.
30 When applying IAS 21 The Effects of Changes in Foreign Exchange Rates to a group of insurance contracts that generate cash flows in a foreign currency, an entity shall treat the group of contracts, including the contractual service margin, as a monetary item.
31 In the financial statements of an entity that issues insurance contracts, the fulfilment cash flows shall not reflect the non-performance risk of that entity (non-performance risk is defined in IFRS 13 Fair Value Measurement).
Measurement on initial recognition (paragraphs B36-B95F)
32 On initial recognition, an entity shall measure a group of insurance contracts at the total of:
- the fulfilment cash flows, which comprise:
- estimates of future cash flows (paragraphs 33–35);
- an adjustment to reflect the time value of money and the financial risks related to the future cash flows, to the extent that the financial risks are not included in the estimates of the future cash flows (paragraph 36); and
- a risk adjustment for non-financial risk (paragraph 37).
- the contractual service margin, measured applying paragraphs 38–39.
Estimates of future cash flows (paragraphs B36-B71)
33 An entity shall include in the measurement of a group of insurance contracts all the future cash flows within the boundary of each contract in the group (see paragraph 34). Applying paragraph 24, an entity may estimate the future cash flows at a higher level of aggregation and then allocate the resulting fulfilment cash flows to individual groups of contracts. The estimates of future cash flows shall:
- incorporate, in an unbiased way, all reasonable and supportable information available without undue cost or effort about the amount, timing and uncertainty of those future cash flows (see paragraphs B37–B41). To do this, an entity shall estimate the expected value (ie the probability-weighted mean) of the full range of possible outcomes.
- reflect the perspective of the entity, provided that the estimates of any relevant market variables are consistent with observable market prices for those variables (see paragraphs B42–B53).
- be current—the estimates shall reflect conditions existing at the measurement date, including assumptions at that date about the future (see paragraphs B54–B60).
- be explicit—the entity shall estimate the adjustment for non-financial risk separately from the other estimates (see paragraph B90). The entity also shall estimate the cash flows separately from the adjustment for the time value of money and financial risk, unless the most appropriate measurement technique combines these estimates (see paragraph B46).
34 Cash flows are within the boundary of an insurance contract if they arise from substantive rights and obligations that exist during the reporting period in which the entity can compel the policyholder to pay the premiums or in which the entity has a substantive obligation to provide the policyholder with insurance contract services (see paragraphs B61–B71). A substantive obligation to provide insurance contract services ends when:
- the entity has the practical ability to reassess the risks of the particular policyholder and, as a result, can set a price or level of benefits that fully reflects those risks; or
- both of the following criteria are satisfied:
- the entity has the practical ability to reassess the risks of the portfolio of insurance contracts that contains the contract and, as a result, can set a price or level of benefits that fully reflects the risk of that portfolio; and
- the pricing of the premiums up to the date when the risks are reassessed does not take into account the risks that relate to periods after the reassessment date.
35 An entity shall not recognise as a liability or as an asset any amounts relating to expected premiums or expected claims outside the boundary of the insurance contract. Such amounts relate to future insurance contracts.
Discount rates (paragraphs B72-B85)
36 An entity shall adjust the estimates of future cash flows to reflect the time value of money and the financial risks related to those cash flows, to the extent that the financial risks are not included in the estimates of cash flows. The discount rates applied to the estimates of the future cash flows described in paragraph 33 shall:
- reflect the time value of money, the characteristics of the cash flows and the liquidity characteristics of the insurance contracts;
- be consistent with observable current market prices (if any) for financial instruments with cash flows whose characteristics are consistent with those of the insurance contracts, in terms of, for example, timing, currency and liquidity; and
- exclude the effect of factors that influence such observable market prices but do not affect the future cash flows of the insurance contracts.
Risk adjustment for non-financial risk (paragraphs B86-B92)
37 An entity shall adjust the estimate of the present value of the future cash flows to reflect the compensation that the entity requires for bearing the uncertainty about the amount and timing of the cash flows that arises from non-financial risk.
Contractual service margin
38 The contractual service margin is a component of the asset or liability for the group of insurance contracts that represents the unearned profit the entity will recognise as it provides insurance contract services in the future. An entity shall measure the contractual service margin on initial recognition of a group of insurance contracts at an amount that, unless paragraph 47 (on onerous contracts) or paragraph B123A (on insurance revenue relating to paragraph 38(c)(ii)) applies, results in no income or expenses arising from:
- the initial recognition of an amount for the fulfilment cash flows, measured by applying paragraphs 32–37;
- any cash flows arising from the contracts in the group at that date;
- the derecognition at the date of initial recognition of:
- any asset for insurance acquisition cash flows applying paragraph 28C; and
- any other asset or liability previously recognised for cash flows related to the group of contracts as specified in paragraph B66A.
39 For insurance contracts acquired in a transfer of insurance contracts or in a business combination within the scope of IFRS 3, an entity shall apply paragraph 38 in accordance with paragraphs B93–B95F.
Subsequent measurement
40 The carrying amount of a group of insurance contracts at the end of each reporting period shall be the sum of:
- the liability for remaining coverage comprising:
- the fulfilment cash flows related to future service allocated to the group at that date, measured applying paragraphs 33–37 and B36–B92;
- the contractual service margin of the group at that date, measured applying paragraphs 43–46; and
- the liability for incurred claims, comprising the fulfilment cash flows related to past service allocated to the group at that date, measured applying paragraphs 33–37 and B36–B92.
41 An entity shall recognise income and expenses for the following changes in the carrying amount of the liability for remaining coverage:
- insurance revenue—for the reduction in the liability for remaining coverage because of services provided in the period, measured applying paragraphs B120–B124;
- insurance service expenses—for losses on groups of onerous contracts, and reversals of such losses (see paragraphs 47–52); and
- insurance finance income or expenses—for the effect of the time value of money and the effect of financial risk as specified in paragraph 87.
42 An entity shall recognise income and expenses for the following changes in the carrying amount of the liability for incurred claims:
- insurance service expenses—for the increase in the liability because of claims and expenses incurred in the period, excluding any investment components;
- insurance service expenses—for any subsequent changes in fulfilment cash flows relating to incurred claims and incurred expenses; and
- insurance finance income or expenses—for the effect of the time value of money and the effect of financial risk as specified in paragraph 87.
Contractual service margin (paragraphs B96-B119B)
43 The contractual service margin at the end of the reporting period represents the profit in the group of insurance contracts that has not yet been recognised in profit or loss because it relates to the future service to be provided under the contracts in the group.
44 For insurance contracts without direct participation features, the carrying amount of the contractual service margin of a group of contracts at the end of the reporting period equals the carrying amount at the start of the reporting period adjusted for:
- the effect of any new contracts added to the group (see paragraph 28);
- interest accreted on the carrying amount of the contractual service margin during the reporting period, measured at the discount rates specified in paragraph B72(b);
- the changes in fulfilment cash flows relating to future service as specified in paragraphs B96–B100, except to the extent that:
- such increases in the fulfilment cash flows exceed the carrying amount of the contractual service margin, giving rise to a loss (see paragraph 48(a)); or
- such decreases in the fulfilment cash flows are allocated to the loss component of the liability for remaining coverage applying paragraph 50(b).
- the effect of any currency exchange differences on the contractual service margin; and
- the amount recognised as insurance revenue because of the transfer of insurance contract services in the period, determined by the allocation of the contractual service margin remaining at the end of the reporting period (before any allocation) over the current and remaining coverage period applying paragraph B119.
45 For insurance contracts with direct participation features (see paragraphs B101–B118), the carrying amount of the contractual service margin of a group of contracts at the end of the reporting period equals the carrying amount at the start of the reporting period adjusted for the amounts specified in subparagraphs (a)–(e) below. An entity is not required to identify these adjustments separately. Instead, a combined amount may be determined for some, or all, of the adjustments. The adjustments are:
- the effect of any new contracts added to the group (see paragraph 28);
- the change in the amount of the entity's share of the fair value of the underlying items (see paragraph B104(b)(i)), except to the extent that:
- paragraph B115 (on risk mitigation) applies;
- the decrease in the amount of the entity’s share of the fair value of the underlying items exceeds the carrying amount of the contractual service margin, giving rise to a loss (see paragraph 48); or
- the increase in the amount of the entity’s share of the fair value of the underlying items reverses the amount in (ii).
- the changes in fulfilment cash flows relating to future service, as specified in paragraphs B101–B118, except to the extent that:
- paragraph B115 (on risk mitigation) applies;
- such increases in the fulfilment cash flows exceed the carrying amount of the contractual service margin, giving rise to a loss (see paragraph 48); or
- such decreases in the fulfilment cash flows are allocated to the loss component of the liability for remaining coverage applying paragraph 50(b).
- the effect of any currency exchange differences arising on the contractual service margin; and
- the amount recognised as insurance revenue because of the transfer of insurance contract services in the period, determined by the allocation of the contractual service margin remaining at the end of the reporting period (before any allocation) over the current and remaining coverage period applying paragraph B119.
46 Some changes in the contractual service margin offset changes in the fulfilment cash flows for the liability for remaining coverage, resulting in no change in the total carrying amount of the liability for remaining coverage. To the extent that changes in the contractual service margin do not offset changes in the fulfilment cash flows for the liability for remaining coverage, an entity shall recognise income and expenses for the changes, applying paragraph 41.
Onerous contracts
47 An insurance contract is onerous at the date of initial recognition if the fulfilment cash flows allocated to the contract, any previously recognised insurance acquisition cash flows and any cash flows arising from the contract at the date of initial recognition in total are a net outflow. Applying paragraph 16(a), an entity shall group such contracts separately from contracts that are not onerous. To the extent that paragraph 17 applies, an entity may identify the group of onerous contracts by measuring a set of contracts rather than individual contracts. An entity shall recognise a loss in profit or loss for the net outflow for the group of onerous contracts, resulting in the carrying amount of the liability for the group being equal to the fulfilment cash flows and the contractual service margin of the group being zero.
48 A group of insurance contracts becomes onerous (or more onerous) on subsequent measurement if the following amounts exceed the carrying amount of the contractual service margin:
- unfavourable changes relating to future service in the fulfilment cash flows allocated to the group arising from changes in estimates of future cash flows and the risk adjustment for non-financial risk; and
- for a group of insurance contracts with direct participation features, the decrease in the amount of the entity’s share of the fair value of the underlying items.
Applying paragraphs 44(c)(i), 45(b)(ii) and 45(c)(ii), an entity shall recognise a loss in profit or loss to the extent of that excess.
49 An entity shall establish (or increase) a loss component of the liability for remaining coverage for an onerous group depicting the losses recognised applying paragraphs 47–48. The loss component determines the amounts that are presented in profit or loss as reversals of losses on onerous groups and are consequently excluded from the determination of insurance revenue.
50 After an entity has recognised a loss on an onerous group of insurance contracts, it shall allocate:
- the subsequent changes in fulfilment cash flows of the liability for remaining coverage specified in paragraph 51 on a systematic basis between:
- the loss component of the liability for remaining coverage; and
- the liability for remaining coverage, excluding the loss component.
- solely to the loss component until that component is reduced to zero:
- any subsequent decrease relating to future service in fulfilment cash flows allocated to the group arising from changes in estimates of future cash flows and the risk adjustment for non-financial risk; and
- any subsequent increases in the amount of the entity’s share of the fair value of the underlying items.
Applying paragraphs 44(c)(ii), 45(b)(iii) and 45(c)(iii), an entity shall adjust the contractual service margin only for the excess of the decrease over the amount allocated to the loss component.
51 The subsequent changes in the fulfilment cash flows of the liability for remaining coverage to be allocated applying paragraph 50(a) are:
- estimates of the present value of future cash flows for claims and expenses released from the liability for remaining coverage because of incurred insurance service expenses;
- changes in the risk adjustment for non-financial risk recognised in profit or loss because of the release from risk; and
- insurance finance income or expenses.
52 The systematic allocation required by paragraph 50(a) shall result in the total amounts allocated to the loss component in accordance with paragraphs 48–50 being equal to zero by the end of the coverage period of a group of contracts.
Premium allocation approach
53 An entity may simplify the measurement of a group of insurance contracts using the premium allocation approach set out in paragraphs 55–59 if, and only if, at the inception of the group:
- the entity reasonably expects that such simplification would produce a measurement of the liability for remaining coverage for the group that would not differ materially from the one that would be produced applying the requirements in paragraphs 32–52; or
- the coverage period of each contract in the group (including insurance contract services arising from all premiums within the contract boundary determined at that date applying paragraph 34) is one year or less.
54 The criterion in paragraph 53(a) is not met if at the inception of the group an entity expects significant variability in the fulfilment cash flows that would affect the measurement of the liability for remaining coverage during the period before a claim is incurred. Variability in the fulfilment cash flows increases with, for example:
- the extent of future cash flows relating to any derivatives embedded in the contracts; and
- the length of the coverage period of the group of contracts.
55 Using the premium allocation approach, an entity shall measure the liability for remaining coverage as follows:
- on initial recognition, the carrying amount of the liability is:
- the premiums, if any, received at initial recognition;
- minus any insurance acquisition cash flows at that date, unless the entity chooses to recognise the payments as an expense applying paragraph 59(a); and
- plus or minus any amount arising from the derecognition at that date of:
- any asset for insurance acquisition cash flows applying paragraph 28C; and
- any other asset or liability previously recognised for cash flows related to the group of contracts as specified in paragraph B66A.
- at the end of each subsequent reporting period, the carrying amount of the liability is the carrying amount at the start of the reporting period:
- plus the premiums received in the period;
- minus insurance acquisition cash flows; unless the entity chooses to recognise the payments as an expense applying paragraph 59(a);
- plus any amounts relating to the amortisation of insurance acquisition cash flows recognised as an expense in the reporting period; unless the entity chooses to recognise insurance acquisition cash flows as an expense applying paragraph 59(a);
- plus any adjustment to a financing component, applying paragraph 56;
- minus the amount recognised as insurance revenue for services provided in that period (see paragraph B126); and
- minus any investment component paid or transferred to the liability for incurred claims.
56 If insurance contracts in the group have a significant financing component, an entity shall adjust the carrying amount of the liability for remaining coverage to reflect the time value of money and the effect of financial risk using the discount rates specified in paragraph 36, as determined on initial recognition. The entity is not required to adjust the carrying amount of the liability for remaining coverage to reflect the time value of money and the effect of financial risk if, at initial recognition, the entity expects that the time between providing each part of the services and the related premium due date is no more than a year.
57 If at any time during the coverage period, facts and circumstances indicate that a group of insurance contracts is onerous, an entity shall calculate the difference between:
- the carrying amount of the liability for remaining coverage determined applying paragraph 55; and
- the fulfilment cash flows that relate to remaining coverage of the group, applying paragraphs 33–37 and B36–B92. However, if, in applying paragraph 59(b), the entity does not adjust the liability for incurred claims for the time value of money and the effect of financial risk, it shall not include in the fulfilment cash flows any such adjustment.
58 To the extent that the fulfilment cash flows described in paragraph 57(b) exceed the carrying amount described in paragraph 57(a), the entity shall recognise a loss in profit or loss and increase the liability for remaining coverage.
59 In applying the premium allocation approach, an entity:
- may choose to recognise any insurance acquisition cash flows as expenses when it incurs those costs, provided that the coverage period of each contract in the group at initial recognition is no more than one year.
- shall measure the liability for incurred claims for the group of insurance contracts at the fulfilment cash flows relating to incurred claims, applying paragraphs 33–37 and B36–B92. However, the entity is not required to adjust future cash flows for the time value of money and the effect of financial risk if those cash flows are expected to be paid or received in one year or less from the date the claims are incurred.
Reinsurance contracts held
60 The requirements in IFRS 17 are modified for reinsurance contracts held, as set out in paragraphs 61–70A.
61 An entity shall divide portfolios of reinsurance contracts held applying paragraphs 14–24, except that the references to onerous contracts in those paragraphs shall be replaced with a reference to contracts on which there is a net gain on initial recognition. For some reinsurance contracts held, applying paragraphs 14–24 will result in a group that comprises a single contract.
Recognition
62 Instead of applying paragraph 25, an entity shall recognise a group of reinsurance contracts held from the earlier of the following:
- the beginning of the coverage period of the group of reinsurance contracts held; and
- the date the entity recognises an onerous group of underlying insurance contracts applying paragraph 25(c), if the entity entered into the related reinsurance contract held in the group of reinsurance contracts held at or before that date.
62A Notwithstanding paragraph 62(a), an entity shall delay the recognition of a group of reinsurance contracts held that provide proportionate coverage until the date that any underlying insurance contract is initially recognised, if that date is later than the beginning of the coverage period of the group of reinsurance contracts held.
Measurement
63 In applying the measurement requirements of paragraphs 32–36 to reinsurance contracts held, to the extent that the underlying contracts are also measured applying those paragraphs, the entity shall use consistent assumptions to measure the estimates of the present value of the future cash flows for the group of reinsurance contracts held and the estimates of the present value of the future cash flows for the group(s) of underlying insurance contracts. In addition, the entity shall include in the estimates of the present value of the future cash flows for the group of reinsurance contracts held the effect of any risk of non-performance by the issuer of the reinsurance contract, including the effects of collateral and losses from disputes.
64 Instead of applying paragraph 37, an entity shall determine the risk adjustment for non-financial risk so that it represents the amount of risk being transferred by the holder of the group of reinsurance contracts to the issuer of those contracts.
65 The requirements of paragraph 38 that relate to determining the contractual service margin on initial recognition are modified to reflect the fact that for a group of reinsurance contracts held there is no unearned profit but instead a net cost or net gain on purchasing the reinsurance. Hence, unless paragraph 65A applies, on initial recognition the entity shall recognise any net cost or net gain on purchasing the group of reinsurance contracts held as a contractual service margin measured at an amount equal to the sum of:
- the fulfilment cash flows;
- the amount derecognised at that date of any asset or liability previously recognised for cash flows related to the group of reinsurance contracts held;
- and any cash flows arising at that date; and
- any income recognised in profit or loss applying paragraph 66A.
65A If the net cost of purchasing reinsurance coverage relates to events that occurred before the purchase of the group of reinsurance contracts held, notwithstanding the requirements of paragraph B5, the entity shall recognise such a cost immediately in profit or loss as an expense.
66 Instead of applying paragraph 44, an entity shall measure the contractual service margin at the end of the reporting period for a group of reinsurance contracts held as the carrying amount determined at the start of the reporting period, adjusted for:
- the effect of any new contracts added to the group (see paragraph 28);
- interest accreted on the carrying amount of the contractual service margin, measured at the discount rates specified in paragraph B72(b);
- income recognised in profit or loss in the reporting period applying paragraph 66A;
- reversals of a loss-recovery component recognised applying paragraph 66B (see paragraph B119F) to the extent those reversals are not changes in the fulfilment cash flows of the group of reinsurance contracts held;
- changes in the fulfilment cash flows, measured at the discount rates specified in paragraph B72(c), to the extent that the change relates to future service, unless:
- the change results from a change in fulfilment cash flows allocated to a group of underlying insurance contracts that does not adjust the contractual service margin for the group of underlying insurance contracts; or
- the change results from applying paragraphs 57–58 (on onerous contracts), if the entity measures a group of underlying insurance contracts applying the premium allocation approach.
- the effect of any currency exchange differences arising on the contractual service margin; and
- the amount recognised in profit or loss because of services received in the period, determined by the allocation of the contractual service margin remaining at the end of the reporting period (before any allocation) over the current and remaining coverage period of the group of reinsurance contracts held, applying paragraph B119.
66A An entity shall adjust the contractual service margin of a group of reinsurance contracts held, and as a result recognise income, when the entity recognises a loss on initial recognition of an onerous group of underlying insurance contracts or on addition of onerous underlying insurance contracts to a group (see paragraphs B119C–B119E).
66B An entity shall establish (or adjust) a loss-recovery component of the asset for remaining coverage for a group of reinsurance contracts held depicting the recovery of losses recognised applying paragraphs 66(c)(i)–(ii) and 66A. The loss-recovery component determines the amounts that are presented in profit or loss as reversals of recoveries of losses from reinsurance contracts held and are consequently excluded from the allocation of premiums paid to the reinsurer (see paragraph B119F).
67 Changes in the fulfilment cash flows that result from changes in the risk of non-performance by the issuer of a reinsurance contract held do not relate to future service and shall not adjust the contractual service margin.
68 Reinsurance contracts held cannot be onerous. Accordingly, the requirements of paragraphs 47–52 do not apply.
Premium allocation approach for reinsurance contracts held
69 An entity may use the premium allocation approach set out in paragraphs 55–56 and 59 (adapted to reflect the features of reinsurance contracts held that differ from insurance contracts issued, for example the generation of expenses or reduction in expenses rather than revenue) to simplify the measurement of a group of reinsurance contracts held, if at the inception of the group:
- the entity reasonably expects the resulting measurement would not differ materially from the result of applying the requirements in paragraphs 63–68; or
- the coverage period of each contract in the group of reinsurance contracts held (including insurance coverage from all premiums within the contract boundary determined at that date applying paragraph 34) is one year or less.
70 An entity cannot meet the condition in paragraph 69(a) if, at the inception of the group, an entity expects significant variability in the fulfilment cash flows that would affect the measurement of the asset for remaining coverage during the period before a claim is incurred. Variability in the fulfilment cash flows increases with, for example:
- the extent of future cash flows relating to any derivatives embedded in the contracts; and
- the length of the coverage period of the group of reinsurance contracts held.
70A If an entity measures a group of reinsurance contracts held applying the premium allocation approach, the entity shall apply paragraph 66A by adjusting the carrying amount of the asset for remaining coverage instead of adjusting the contractual service margin.
Investment contracts with discretionary participation features
71 An investment contract with discretionary participation features does not include a transfer of significant insurance risk. Consequently, the requirements in IFRS 17 for insurance contracts are modified for investment contracts with discretionary participation features as follows:
- the date of initial recognition (see paragraphs 25 and 28) is the date the entity becomes party to the contract.
- the contract boundary (see paragraph 34) is modified so that cash flows are within the contract boundary if they result from a substantive obligation of the entity to deliver cash at a present or future date. The entity has no substantive obligation to deliver cash if it has the practical ability to set a price for the promise to deliver the cash that fully reflects the amount of cash promised and related risks.
- the allocation of the contractual service margin (see paragraphs 44(e) and 45(e)) is modified so that the entity shall recognise the contractual service margin over the duration of the group of contracts in a systematic way that reflects the transfer of investment services under the contract.
Modification and derecognition
Modification of an insurance contract
72 If the terms of an insurance contract are modified, for example by agreement between the parties to the contract or by a change in regulation, an entity shall derecognise the original contract and recognise the modified contract as a new contract, applying IFRS 17 or other applicable Standards if, and only if, any of the conditions in (a)–(c) are satisfied. The exercise of a right included in the terms of a contract is not a modification. The conditions are that:
- if the modified terms had been included at contract inception:
- the modified contract would have been excluded from the scope of IFRS 17, applying paragraphs 3–8A;
- an entity would have separated different components from the host insurance contract applying paragraphs 10–13, resulting in a different insurance contract to which IFRS 17 would have applied;
- the modified contract would have had a substantially different contract boundary applying paragraph 34; or
- the modified contract would have been included in a different group of contracts applying paragraphs 14–24.
- the original contract met the definition of an insurance contract with direct participation features, but the modified contract no longer meets that definition, or vice versa; or
- the entity applied the premium allocation approach in paragraphs 53–59 or paragraphs 69–70 to the original contract, but the modifications mean that the contract no longer meets the eligibility criteria for that approach in paragraph 53 or paragraph 69.
73 If a contract modification meets none of the conditions in paragraph 72, the entity shall treat changes in cash flows caused by the modification as changes in estimates of fulfilment cash flows by applying paragraphs 40–52.
Derecognition
74 An entity shall derecognise an insurance contract when, and only when:
- it is extinguished, ie when the obligation specified in the insurance contract expires or is discharged or cancelled; or
- any of the conditions in paragraph 72 are met.
75 When an insurance contract is extinguished, the entity is no longer at risk and is therefore no longer required to transfer any economic resources to satisfy the insurance contract. For example, when an entity buys reinsurance, it shall derecognise the underlying insurance contract(s) when, and only when, the underlying insurance contract(s) is or are extinguished.
76 An entity derecognises an insurance contract from within a group of contracts by applying the following requirements in IFRS 17:
- the fulfilment cash flows allocated to the group are adjusted to eliminate the present value of the future cash flows and risk adjustment for non-financial risk relating to the rights and obligations that have been derecognised from the group, applying paragraphs 40(a)(i) and 40(b);
- the contractual service margin of the group is adjusted for the change in fulfilment cash flows described in (a), to the extent required by paragraphs 44(c) and 45(c), unless paragraph 77 applies; and
- the number of coverage units for expected remaining insurance contract services is adjusted to reflect the coverage units derecognised from the group, and the amount of the contractual service margin recognised in profit or loss in the period is based on that adjusted number applying paragraph B119.
77 When an entity derecognises an insurance contract because it transfers the contract to a third party or derecognises an insurance contract and recognises a new contract applying paragraph 72, the entity shall instead of applying paragraph 76(b):
- adjust the contractual service margin of the group from which the contract has been derecognised, to the extent required by paragraphs 44(c) and 45(c), for the difference between (i) and either (ii) for contracts transferred to a third party or (iii) for contracts derecognised applying paragraph 72:
- the change in the carrying amount of the group of insurance contracts resulting from the derecognition of the contract, applying paragraph 76(a).
- the premium charged by the third party.
- the premium the entity would have charged had it entered into a contract with equivalent terms as the new contract at the date of the contract modification, less any additional premium charged for the modification.
- measure the new contract recognised applying paragraph 72 assuming that the entity received the premium described in (a)(iii) at the date of the modification.
Presentation in the statement of financial position
78 An entity shall present separately in the statement of financial position the carrying amount of portfolios of:
- insurance contracts issued that are assets;
- insurance contracts issued that are liabilities;
- reinsurance contracts held that are assets; and
- reinsurance contracts held that are liabilities.
79 An entity shall include any assets for insurance acquisition cash flows recognised applying paragraph 28B in the carrying amount of the related portfolios of insurance contracts issued, and any assets or liabilities for cash flows related to portfolios of
reinsurance contracts held (see paragraph 65(b)) in the carrying amount of the portfolios of reinsurance contracts held.
Recognition and presentation in the statement(s) of financial performance (paragraphs B120-B136)
80 Applying paragraphs 41 and 42, an entity shall disaggregate the amounts recognised in the statement(s) of profit or loss and other comprehensive income (hereafter referred to as the statement(s) of financial performance) into:
- an insurance service result (paragraphs 83–86), comprising insurance revenue and insurance service expenses; and
- insurance finance income or expenses (paragraphs 87–92).
81 An entity is not required to disaggregate the change in the risk adjustment for non-financial risk between the insurance service result and insurance finance income or expenses. If an entity does not make such a disaggregation, it shall include the entire change in the risk adjustment for non-financial risk as part of the insurance service result.
82 An entity shall present income or expenses from reinsurance contracts held separately from the expenses or income from insurance contracts issued.
Insurance service result
83 An entity shall present in profit or loss insurance revenue arising from the groups of insurance contracts issued. Insurance revenue shall depict the provision of services arising from the group of insurance contracts at an amount that reflects the consideration to which the entity expects to be entitled in exchange for those services. Paragraphs B120–B127 specify how an entity measures insurance revenue.
84 An entity shall present in profit or loss insurance service expenses arising from a group of insurance contracts issued, comprising incurred claims (excluding repayments of investment components), other incurred insurance service expenses and other amounts as described in paragraph 103(b).
85 Insurance revenue and insurance service expenses presented in profit or loss shall exclude any investment components. An entity shall not present premium information in profit or loss if that information is inconsistent with paragraph 83.
86 An entity may present the income or expenses from a group of reinsurance contracts held (see paragraphs 60–70A), other than insurance finance income or expenses, as a single amount; or the entity may present separately the amounts recovered from the reinsurer and an allocation of the premiums paid that together give a net amount equal to that single amount. If an entity presents separately the amounts recovered from the reinsurer and an allocation of the premiums paid, it shall:
- treat reinsurance cash flows that are contingent on claims on the underlying contracts as part of the claims that are expected to be reimbursed under the reinsurance contract held;
- treat amounts from the reinsurer that it expects to receive that are not contingent on claims of the underlying contracts (for example, some types of ceding commissions) as a reduction in the premiums to be paid to the reinsurer;
- treat amounts recognised relating to recovery of losses applying paragraphs 66(c)(i)–(ii) and 66A–66B as amounts recovered from the reinsurer; and
- not present the allocation of premiums paid as a reduction in revenue.
Insurance finance income or expenses (see paragraphs B128-B136)
87 Insurance finance income or expenses comprises the change in the carrying amount of the group of insurance contracts arising from:
- the effect of the time value of money and changes in the time value of money; and
- the effect of financial risk and changes in financial risk; but
- excluding any such changes for groups of insurance contracts with direct participation features that would adjust the contractual service margin but do not do so when applying paragraphs 45(b)(ii), 45(b)(iii), 45(c)(ii) or 45(c)(iii). These are included in insurance service expenses.
87A An entity shall apply:
- paragraph B117A to insurance finance income or expenses arising from the application of paragraph B115 (risk mitigation); and
- paragraphs 88 and 89 to all other insurance finance income or expenses.
88 In applying paragraph 87A(b), unless paragraph 89 applies, an entity shall make an accounting policy choice between:
- including insurance finance income or expenses for the period in profit or loss; or
- disaggregating insurance finance income or expenses for the period to include in profit or loss an amount determined by a systematic allocation of the expected total insurance finance income or expenses over the duration of the group of contracts, applying paragraphs B130–B133.
89 In applying paragraph 87A(b), for insurance contracts with direct participation features, for which the entity holds the underlying items, an entity shall make an accounting policy choice between:
- including insurance finance income or expenses for the period in profit or loss; or
- disaggregating insurance finance income or expenses for the period to include in profit or loss an amount that eliminates accounting mismatches with income or expenses included in profit or loss on the underlying items held, applying paragraphs B134–B136.
90 If an entity chooses the accounting policy set out in paragraph 88(b) or in paragraph 89(b), it shall include in other comprehensive income the difference between the insurance finance income or expenses measured on the basis set out in those paragraphs and the total insurance finance income or expenses for the period.
91 If an entity transfers a group of insurance contracts or derecognises an insurance contract applying paragraph 77:
- it shall reclassify to profit or loss as a reclassification adjustment (see IAS 1 Presentation of Financial Statements) any remaining amounts for the group (or contract) that were previously recognised in other comprehensive income because the entity chose the accounting policy set out in paragraph 88(b).
- it shall not reclassify to profit or loss as a reclassification adjustment (see IAS 1) any remaining amounts for the group (or contract) that were previously recognised in other comprehensive income because the entity chose the accounting policy set out in paragraph 89(b).
92 Paragraph 30 requires an entity to treat an insurance contract as a monetary item under IAS 21 for the purpose of translating foreign exchange items into the entity's functional currency. An entity includes exchange differences on changes in the carrying amount of groups of insurance contracts in the statement of profit or loss, unless they relate to changes in the carrying amount of groups of insurance contracts included in other comprehensive income applying paragraph 90, in which case they shall be included in other comprehensive income.
Disclosure
93 The objective of the disclosure requirements is for an entity to disclose information in the notes that, together with the information provided in the statement of financial position, statement(s) of financial performance and statement of cash flows, gives a basis for users of financial statements to assess the effect that contracts within the scope of IFRS 17 have on the entity's financial position, financial performance and cash flows. To achieve that objective, an entity shall disclose qualitative and quantitative information about:
- the amounts recognised in its financial statements for contracts within the scope of IFRS 17 (see paragraphs 97–116);
- the significant judgements, and changes in those judgements, made when applying IFRS 17 (see paragraphs 117–120); and
- the nature and extent of the risks from contracts within the scope of IFRS 17 (see paragraphs 121–132).
94 An entity shall consider the level of detail necessary to satisfy the disclosure objective and how much emphasis to place on each of the various requirements. If the disclosures provided, applying paragraphs 97–132, are not enough to meet the objective in paragraph 93, an entity shall disclose additional information necessary to meet that objective.
95 An entity shall aggregate or disaggregate information so that useful information is not obscured either by the inclusion of a large amount of insignificant detail or by the aggregation of items that have different characteristics.
96 Paragraphs 29–31 of IAS 1 set out requirements relating to materiality and aggregation of information. Examples of aggregation bases that might be appropriate for information disclosed about insurance contracts are:
- type of contract (for example, major product lines);
- geographical area (for example, country or region); or
- reportable segment, as defined in IFRS 8 Operating Segments.
Explanation of recognised amounts
97 Of the disclosures required by paragraphs 98–109A, only those in paragraphs 98–100, 102–103, 105–105B and 109A apply to contracts to which the premium allocation approach has been applied. If an entity uses the premium allocation approach, it shall also disclose:
- which of the criteria in paragraphs 53 and 69 it has satisfied;
- whether it makes an adjustment for the time value of money and the effect of financial risk applying paragraphs 56, 57(b) and 59(b); and
- the method it has chosen to recognise insurance acquisition cash flows applying paragraph 59(a).
98 An entity shall disclose reconciliations that show how the net carrying amounts of contracts within the scope of IFRS 17 changed during the period because of cash flows and income and expenses recognised in the statement(s) of financial performance. Separate reconciliations shall be disclosed for insurance contracts issued and reinsurance contracts held. An entity shall adapt the requirements of paragraphs 100–109 to reflect the features of reinsurance contracts held that differ from insurance contracts issued; for example, the generation of expenses or reduction in expenses rather than revenue.
99 An entity shall provide enough information in the reconciliations to enable users of financial statements to identify changes from cash flows and amounts that are recognised in the statement(s) of financial performance. To comply with this requirement, an entity shall:
- disclose, in a table, the reconciliations set out in paragraphs 100–105B; and
- for each reconciliation, present the net carrying amounts at the beginning and at the end of the period, disaggregated into a total for portfolios of contracts that are assets and a total for portfolios of contracts that are liabilities, that equal the amounts presented in the statement of financial position applying paragraph 78.
100 An entity shall disclose reconciliations from the opening to the closing balances separately for each of:
- the net liabilities (or assets) for the remaining coverage component, excluding any loss component.
- any loss component (see paragraphs 47–52 and 57–58).
- the liabilities for incurred claims. For insurance contracts to which the premium allocation approach described in paragraphs 53–59 or 69–70A has been applied, an entity shall disclose separate reconciliations for:
- the estimates of the present value of the future cash flows; and
- the risk adjustment for non-financial risk.
101 For insurance contracts other than those to which the premium allocation approach described in paragraphs 53–59 or 69–70A has been applied, an entity shall also disclose reconciliations from the opening to the closing balances separately for each of:
- the estimates of the present value of the future cash flows;
- the risk adjustment for non-financial risk; and
- the contractual service margin.
102 The objective of the reconciliations in paragraphs 100–101 is to provide different types of information about the insurance service result.
103 An entity shall separately disclose in the reconciliations required in paragraph 100 each of the following amounts related to services, if applicable:
- insurance revenue.
- insurance service expenses, showing separately:
- incurred claims (excluding investment components) and other incurred insurance service expenses;
- amortisation of insurance acquisition cash flows;
- changes that relate to past service, ie changes in fulfilment cash flows relating to the liability for incurred claims; and
- changes that relate to future service, ie losses on onerous groups of contracts and reversals of such losses.
- investment components excluded from insurance revenue and insurance service expenses (combined with refunds of premiums unless refunds of premiums are presented as part of the cash flows in the period described in paragraph 105(a)(i)).
104 An entity shall separately disclose in the reconciliations required in paragraph 101 each of the following amounts related to services, if applicable:
- changes that relate to future service, applying paragraphs B96–B118, showing separately:
- changes in estimates that adjust the contractual service margin;
- changes in estimates that do not adjust the contractual service margin, ie losses on groups of onerous contracts and reversals of such losses; and
- the effects of contracts initially recognised in the period.
- changes that relate to current service, ie:
- the amount of the contractual service margin recognised in profit or loss to reflect the transfer of services;
- the change in the risk adjustment for non-financial risk that does not relate to future service or past service; and
- experience adjustments (see paragraphs B97(c) and B113(a)), excluding amounts relating to the risk adjustment for non-financial risk included in (ii).
- changes that relate to past service, ie changes in fulfilment cash flows relating to incurred claims (see paragraphs B97(b) and B113(a)).
105 To complete the reconciliations in paragraphs 100–101, an entity shall also disclose separately each of the following amounts not related to services provided in the period, if applicable:
- cash flows in the period, including:
- premiums received for insurance contracts issued (or paid for reinsurance contracts held);
- insurance acquisition cash flows; and
- incurred claims paid and other insurance service expenses paid for insurance contracts issued (or recovered under reinsurance contracts held), excluding insurance acquisition cash flows.
- the effect of changes in the risk of non-performance by the issuer of reinsurance contracts held;
- insurance finance income or expenses; and
- any additional line items that may be necessary to understand the change in the net carrying amount of the insurance contracts.
105A An entity shall disclose a reconciliation from the opening to the closing balance of assets for insurance acquisition cash flows recognised applying paragraph 28B. An entity shall aggregate information for the reconciliation at a level that is consistent with that for the reconciliation of insurance contracts, applying paragraph 98.
105B An entity shall separately disclose in the reconciliation required by paragraph 105A any impairment losses and reversals of impairment losses recognised applying paragraph 28E–28F.
106 For insurance contracts issued other than those to which the premium allocation approach described in paragraphs 53–59 has been applied, an entity shall disclose an analysis of the insurance revenue recognised in the period comprising:
- the amounts relating to the changes in the liability for remaining coverage as specified in paragraph B124, separately disclosing:
- the insurance service expenses incurred during the period as specified in paragraph B124(a);
- the change in the risk adjustment for non-financial risk, as specified in paragraph B124(b);
- the amount of the contractual service margin recognised in profit or loss because of the transfer of insurance contract services in the period, as specified in paragraph B124(c); and
- other amounts, if any, for example, experience adjustments for premium receipts other than those that relate to future service as specified in paragraph B124(d).
- the allocation of the portion of the premiums that relate to the recovery of insurance acquisition cash flows (see paragraph B125).
107 For insurance contracts other than those to which the premium allocation approach described in paragraphs 53–59 or 69–70A has been applied, an entity shall disclose the effect on the statement of financial position separately for insurance contracts issued and reinsurance contracts held that are initially recognised in the period, showing their effect at initial recognition on:
- the estimates of the present value of future cash outflows, showing separately the amount of the insurance acquisition cash flows;
- the estimates of the present value of future cash inflows;
- the risk adjustment for non-financial risk; and
- the contractual service margin.
108 In the disclosures required by paragraph 107, an entity shall separately disclose amounts resulting from:
- contracts acquired from other entities in transfers of insurance contracts or business combinations; and
- groups of contracts that are onerous.
109 For insurance contracts other than those to which the premium allocation approach described in paragraphs 53–59 or 69–70A has been applied, an entity shall disclose when it expects to recognise the contractual service margin remaining at the end of the reporting period in profit or loss quantitatively, in appropriate time bands. Such information shall be provided separately for insurance contracts issued and reinsurance contracts held.
109A An entity shall disclose quantitatively, in appropriate time bands, when it expects to derecognise an asset for insurance acquisition cash flows applying paragraph 28C.
Insurance finance income or expenses
110 An entity shall disclose and explain the total amount of insurance finance income or expenses in the reporting period. In particular, an entity shall explain the relationship between insurance finance income or expenses and the investment return on its assets, to enable users of its financial statements to evaluate the sources of finance income or expenses recognised in profit or loss and other comprehensive income.
111 For contracts with direct participation features, the entity shall describe the composition of the underlying items and disclose their fair value.
112 For contracts with direct participation features, if an entity chooses not to adjust the contractual service margin for some changes in the fulfilment cash flows, applying paragraph B115, it shall disclose the effect of that choice on the adjustment to the contractual service margin in the current period.
113 For contracts with direct participation features, if an entity changes the basis of disaggregation of insurance finance income or expenses between profit or loss and other comprehensive income, applying paragraph B135, it shall disclose, in the period when the change in approach occurred:
- the reason why the entity was required to change the basis of disaggregation;
- the amount of any adjustment for each financial statement line item affected; and
- the carrying amount of the group of insurance contracts to which the change applied at the date of the change.
Transition amounts
114 An entity shall provide disclosures that enable users of financial statements to identify the effect of groups of insurance contracts measured at the transition date applying the modified retrospective approach (see paragraphs C6–C19A) or the fair value approach (see paragraphs C20–C24B) on the contractual service margin and insurance revenue in subsequent periods. Hence an entity shall disclose the reconciliation of the contractual service margin applying paragraph 101(c), and the amount of insurance revenue applying paragraph 103(a), separately for:
- insurance contracts that existed at the transition date to which the entity has applied the modified retrospective approach;
- insurance contracts that existed at the transition date to which the entity has applied the fair value approach; and
- all other insurance contracts.
115 For all periods in which disclosures are made applying paragraphs 114(a) or 114(b), to enable users of financial statements to understand the nature and significance of the methods used and judgements applied in determining the transition amounts, an entity shall explain how it determined the measurement of insurance contracts at the transition date.
116 An entity that chooses to disaggregate insurance finance income or expenses between profit or loss and other comprehensive income applies paragraphs C18(b), C19(b), C24(b) and C24(c) to determine the cumulative difference between the insurance finance income or expenses that would have been recognised in profit or loss and the total insurance finance income or expenses at the transition date for the groups of insurance contracts to which the disaggregation applies. For all periods in which amounts determined applying these paragraphs exist, the entity shall disclose a reconciliation from the opening to the closing balance of the cumulative amounts included in other comprehensive income for financial assets measured at fair value through other comprehensive income related to the groups of insurance contracts. The reconciliation shall include, for example, gains or losses recognised in other comprehensive income in the period and gains or losses previously recognised in other comprehensive income in previous periods reclassified in the period to profit or loss.
Significant judgements in applying IFRS 17
117 An entity shall disclose the significant judgements and changes in judgements made in applying IFRS 17. Specifically, an entity shall disclose the inputs, assumptions and estimation techniques used, including:
- the methods used to measure insurance contracts within the scope of IFRS 17 and the processes for estimating the inputs to those methods. Unless impracticable, an entity shall also provide quantitative information about those inputs.
- any changes in the methods and processes for estimating inputs used to measure contracts, the reason for each change, and the type of contracts affected.
- to the extent not covered in (a), the approach used:
- to distinguish changes in estimates of future cash flows arising from the exercise of discretion from other changes in estimates of future cash flows for contracts without direct participation features (see paragraph B98);
- to determine the risk adjustment for non-financial risk, including whether changes in the risk adjustment for non-financial risk are disaggregated into an insurance service component and an insurance finance component or are presented in full in the insurance service result;
- to determine discount rates;
- to determine investment components; and
- to determine the relative weighting of the benefits provided by insurance coverage and investment-return service or by insurance coverage and investment-related service (see paragraphs B119–B119B).
118 If, applying paragraph 88(b) or paragraph 89(b), an entity chooses to disaggregate insurance finance income or expenses into amounts presented in profit or loss and amounts presented in other comprehensive income, the entity shall disclose an explanation of the methods used to determine the insurance finance income or expenses recognised in profit or loss.
119 An entity shall disclose the confidence level used to determine the risk adjustment for non-financial risk. If the entity uses a technique other than the confidence level technique for determining the risk adjustment for non-financial risk, it shall disclose the technique used and the confidence level corresponding to the results of that technique.
120 An entity shall disclose the yield curve (or range of yield curves) used to discount cash flows that do not vary based on the returns on underlying items, applying paragraph 36. When an entity provides this disclosure in aggregate for a number of groups of insurance contracts, it shall provide such disclosures in the form of weighted averages, or relatively narrow ranges.
Nature and extent of risks that arise from contracts within the scope of IFRS 17
121 An entity shall disclose information that enables users of its financial statements to evaluate the nature, amount, timing and uncertainty of future cash flows that arise from contracts within the scope of IFRS 17. Paragraphs 122–132 contain requirements for disclosures that would normally be necessary to meet this requirement.
122 These disclosures focus on the insurance and financial risks that arise from insurance contracts and how they have been managed. Financial risks typically include, but are not limited to, credit risk, liquidity risk and market risk.
123 If the information disclosed about an entity's exposure to risk at the end of the reporting period is not representative of its exposure to risk during the period, the entity shall disclose that fact, the reason why the period-end exposure is not representative, and further information that is representative of its risk exposure during the period.
124 For each type of risk arising from contracts within the scope of IFRS 17, an entity shall disclose:
- the exposures to risks and how they arise;
- the entity's objectives, policies and processes for managing the risks and the methods used to measure the risks; and
- any changes in (a) or (b) from the previous period.
125 For each type of risk arising from contracts within the scope of IFRS 17, an entity shall disclose:
- summary quantitative information about its exposure to that risk at the end of the reporting period. This disclosure shall be based on the information provided internally to the entity's key management personnel.
- the disclosures required by paragraphs 127–132, to the extent not provided applying (a) of this paragraph.
126 An entity shall disclose information about the effect of the regulatory frameworks in which it operates; for example, minimum capital requirements or required interest-rate guarantees. If an entity applies paragraph 20 in determining the groups of insurance contracts to which it applies the recognition and measurement requirements of IFRS 17, it shall disclose that fact.
All types of risk—concentrations of risk
127 An entity shall disclose information about concentrations of risk arising from contracts within the scope of IFRS 17, including a description of how the entity determines the concentrations, and a description of the shared characteristic that identifies each concentration (for example, the type of insured event, industry, geographical area, or currency). Concentrations of financial risk might arise, for example, from interest-rate guarantees that come into effect at the same level for a large number of contracts. Concentrations of financial risk might also arise from concentrations of non-financial risk; for example, if an entity provides product liability protection to pharmaceutical companies and also holds investments in those companies.
Insurance and market risks—sensitivity analysis
128 An entity shall disclose information about sensitivities to changes in risk variables arising from contracts within the scope of IFRS 17. To comply with this requirement, an entity shall disclose:
- a sensitivity analysis that shows how profit or loss and equity would have been affected by changes in risk variables that were reasonably possible at the end of the reporting period:
- for insurance risk—showing the effect for insurance contracts issued, before and after risk mitigation by reinsurance contracts held; and
- for each type of market risk—in a way that explains the relationship between the sensitivities to changes in risk variables arising from insurance contracts and those arising from financial assets held by the entity.
- the methods and assumptions used in preparing the sensitivity analysis; and
- changes from the previous period in the methods and assumptions used in preparing the sensitivity analysis, and the reasons for such changes.
129 If an entity prepares a sensitivity analysis that shows how amounts different from those specified in paragraph 128(a) are affected by changes in risk variables and uses that sensitivity analysis to manage risks arising from contracts within the scope of IFRS 17, it may use that sensitivity analysis in place of the analysis specified in paragraph 128(a). The entity shall also disclose:
- an explanation of the method used in preparing such a sensitivity analysis and of the main parameters and assumptions underlying the information provided; and
- an explanation of the objective of the method used and of any limitations that may result in the information provided.
Insurance risk—claims development
130 An entity shall disclose actual claims compared with previous estimates of the undiscounted amount of the claims (ie claims development). The disclosure about claims development shall start with the period when the earliest material claim(s) arose and for which there is still uncertainty about the amount and timing of the claims payments at the end of the reporting period; but the disclosure is not required to start more than 10 years before the end of the reporting period. The entity is not required to disclose information about the development of claims for which uncertainty about the amount and timing of the claims payments is typically resolved within one year. An entity shall reconcile the disclosure about claims development with the aggregate carrying amount of the groups of insurance contracts, which the entity discloses applying paragraph 100(c).
Credit risk—other information
131 For credit risk that arises from contracts within the scope of IFRS 17, an entity shall disclose:
- the amount that best represents its maximum exposure to credit risk at the end of the reporting period, separately for insurance contracts issued and reinsurance contracts held; and
- information about the credit quality of reinsurance contracts held that are assets.
Liquidity risk—other information
132 For liquidity risk arising from contracts within the scope of IFRS 17, an entity shall disclose:
- a description of how it manages the liquidity risk.
- separate maturity analyses for portfolios of insurance contracts issued that are liabilities and portfolios of reinsurance contracts held that are liabilities that show, as a minimum, net cash flows of the portfolios for each of the first five years after the reporting date and in aggregate beyond the first five years. An entity is not required to include in these analyses liabilities for remaining coverage measured applying paragraphs 55–59 and paragraphs 69–70A. The analyses may take the form of:
- an analysis, by estimated timing, of the remaining contractual undiscounted net cash flows; or
- an analysis, by estimated timing, of the estimates of the present value of the future cash flows.
- the amounts that are payable on demand, explaining the relationship between such amounts and the carrying amount of the related portfolios of contracts, if not disclosed applying (b) of this paragraph.
Appendix A Defined terms
This appendix is an integral part of IFRS 17 Insurance Contracts.
contractual service margin A component of the carrying amount of the asset or liability for a group of insurance contracts representing the unearned profit the entity will recognise as it provides insurance contract services under the insurance contracts in the group.
coverage period The period during which the entity provides insurance contract services. This period includes the insurance contract services that relate to all premiums within the boundary of the insurance contract.
experience adjustment A difference between:
- for premium receipts (and any related cash flows such as insurance acquisition cash flows and insurance premium taxes)—the estimate at the beginning of the period of the amounts expected in the period and the actual cash flows in the period; or
- for insurance service expenses (excluding insurance acquisition expenses)—the estimate at the beginning of the period of the amounts expected to be incurred in the period and the actual amounts incurred in the period.
financial risk The risk of a possible future change in one or more of a specified interest rate, financial instrument price, commodity price, currency exchange rate, index of prices or rates, credit rating or credit index or other variable, provided in the case of a non-financial variable that the variable is not specific to a party to the contract.
fulfilment cash flows An explicit, unbiased and probability-weighted estimate (ie expected value) of the present value of the future cash outflows minus the present value of the future cash inflows that will arise as the entity fulfils insurance contracts, including a risk adjustment for non-financial risk.
group of insurance contracts A set of insurance contracts resulting from the division of a portfolio of insurance contracts into, at a minimum, contracts issued within a period of no longer than one year and that, at initial recognition:
- are onerous, if any;
- have no significant possibility of becoming onerous subsequently, if any; or
- do not fall into either (a) or (b), if any.
insurance acquisition cash flows Cash flows arising from the costs of selling, underwriting and starting a group of insurance contracts (issued or expected to be issued) that are directly attributable to the portfolio of insurance contracts to which the group belongs. Such cash flows include cash flows that are not directly attributable to individual contracts or groups of insurance contracts within the portfolio.
insurance contract A contract under which one party (the issuer) accepts significant insurance risk from another party (the policyholder) by agreeing to compensate the policyholder if a specified uncertain future event (the insured event) adversely affects the policyholder.
insurance contract services The following services that an entity provides to a policyholder of an insurance contract:
- coverage for an insured event (insurance coverage);
- for insurance contracts without direct participation features, the generation of an investment return for the policyholder, if applicable (investment-return service); and
- for insurance contracts with direct participation features, the management of underlying items on behalf of the policyholder (investment-related service).
insurance contract with direct participation features An insurance contract for which, at inception:
- the contractual terms specify that the policyholder participates in a share of a clearly identified pool of underlying items;
- the entity expects to pay to the policyholder an amount equal to a substantial share of the fair value returns on the underlying items; and
- the entity expects a substantial proportion of any change in the amounts to be paid to the policyholder to vary with the change in fair value of the underlying items.
insurance contract without direct participation features An insurance contract that is not an insurance contract with direct participation features.
insurance risk Risk, other than financial risk, transferred from the holder of a contract to the issuer.
insured event An uncertain future event covered by an insurance contract that creates insurance risk.
investment component The amounts that an insurance contract requires the entity to repay to a policyholder in all circumstances, regardless of whether an insured event occurs.
investment contract with discretionary participation features A financial instrument that provides a particular investor with the contractual right to receive, as a supplement to an amount not subject to the discretion of the issuer, additional amounts:
- that are expected to be a significant portion of the total contractual benefits;
- the timing or amount of which are contractually at the discretion of the issuer; and
- that are contractually based on:
- the returns on a specified pool of contracts or a specified type of contract;
- realised and/or unrealised investment returns on a specified pool of assets held by the issuer; or
- the profit or loss of the entity or fund that issues the contract.
liability for incurred claims An entity's obligation to:
- investigate and pay valid claims for insured events that have already occurred, including events that have occurred but for which claims have not been reported, and other incurred insurance expenses; and
- pay amounts that are not included in (a) and that relate to:
- insurance contract services that have already been provided; or
- any investment components or other amounts that are not related to the provision of insurance contract services and that are not in the liability for remaining coverage.
liability for remaining coverage An entity's obligation to:
- investigate and pay valid claims under existing insurance contracts for insured events that have not yet occurred (ie the obligation that relates to the unexpired portion of the insurance coverage); and
- pay amounts under existing insurance contracts that are not included in (a) and that relate to:
- insurance contract services not yet provided (ie the obligations that relate to future provision of insurance contract services); or
- any investment components or other amounts that are not related to the provision of insurance contract services and that have not been transferred to the liability for incurred claims.
policyholder A party that has a right to compensation under an insurance contract if an insured event occurs.
portfolio of insurance contracts Insurance contracts subject to similar risks and managed together.
reinsurance contract An insurance contract issued by one entity (the reinsurer) to compensate another entity for claims arising from one or more insurance contracts issued by that other entity (underlying contracts).
risk adjustment for non-financial risk The compensation an entity requires for bearing the uncertainty about the amount and timing of the cash flows that arises from non-financial risk as the entity fulfils insurance contracts.
underlying items Items that determine some of the amounts payable to a policyholder. Underlying items can comprise any items; for example, a reference portfolio of assets, the net assets of the entity, or a specified subset of the net assets of the entity.
Appendix B
Application guidance
This appendix is an integral part of IFRS 17 Insurance Contracts.
B1This appendix provides guidance on the following:
- definition of an insurance contract (see paragraphs B2-B30);
- separation of components from an insurance contract (see paragraphs B31-B35);
- asset for insurance acquisition cash flows (see paragraphs B35A-B35D);
- measurement (see paragraphs B36-B119F);
- insurance revenue (see paragraphs B120-B127);
- insurance finance income or expenses (see paragraphs B128-B136); and
- interim financial statements (see paragraph B137).
Definition of an insurance contract (Appendix A)
B2This section provides guidance on the definition of an insurance contract as specified in Appendix A. It addresses the following:
- uncertain future event (see paragraphs B3-B5);
- payments in kind (see paragraph B6);
- the distinction between insurance risk and other risks (see paragraphs B7-B16);
- significant insurance risk (see paragraphs B17-B23);
- changes in the level of insurance risk (see paragraphs B24-B25); and
- examples of insurance contracts (see paragraphs B26-B30).
Uncertain future event
B3Uncertainty (or risk) is the essence of an insurance contract. Accordingly, at least one of the following is uncertain at the inception of an insurance contract:
- the probability of an insured event occurring;
- when the insured event will occur; or
- how much the entity will need to pay if the insured event occurs.
B4In some insurance contracts, the insured event is the discovery of a loss during the term of the contract, even if that loss arises from an event that occurred before the inception of the contract. In other insurance contracts, the insured event is an event that occurs during the term of the contract, even if the resulting loss is discovered after the end of the contract term.
B5Some insurance contracts cover events that have already occurred but the financial effect of which is still uncertain. An example is an insurance contract that provides insurance coverage against an adverse development of an event that has already occurred. In such contracts, the insured event is the determination of the ultimate cost of those claims.
Payments in kind
B6Some insurance contracts require or permit payments to be made in kind. In such cases, the entity provides goods or services to the policyholder to settle the entity's obligation to compensate the policyholder for insured events. An example is when the entity replaces a stolen article instead of reimbursing the policyholder for the amount of its loss. Another example is when an entity uses its own hospitals and medical staff to provide medical services covered by the insurance contract. Such contracts are insurance contracts, even though the claims are settled in kind. Fixed-fee service contracts that meet the conditions specified in paragraph 8 are also insurance contracts, but applying paragraph 8, an entity may choose to account for them applying either IFRS 17 or IFRS 15 Revenue from Contracts with Customers.
The distinction between insurance risk and other risks
B7The definition of an insurance contract requires that one party accepts significant insurance risk from another party. IFRS 17 defines insurance risk as 'risk, other than financial risk, transferred from the holder of a contract to the issuer'. A contract that exposes the issuer to financial risk without significant insurance risk is not an insurance contract.
B8The definition of financial risk in Appendix A refers to financial and non-financial variables. Examples of non-financial variables not specific to a party to the contract include an index of earthquake losses in a particular region or temperatures in a particular city. Financial risk excludes risk from non-financial variables that are specific to a party to the contract, such as the occurrence or non-occurrence of a fire that damages or destroys an asset of that party. Furthermore, the risk of changes in the fair value of a non-financial asset is not a financial risk if the fair value reflects changes in the market prices for such assets (ie a financial variable) and the condition of a specific non-financial asset held by a party to a contract (ie a non-financial variable). For example, if a guarantee of the residual value of a specific car in which the policyholder has an insurable interest exposes the guarantor to the risk of changes in the car's physical condition, that risk is insurance risk, not financial risk.
B9Some contracts expose the issuer to financial risk in addition to significant insurance risk. For example, many life insurance contracts guarantee a minimum rate of return to policyholders, creating financial risk, and at the same time promise death benefits that may significantly exceed the policyholder's account balance, creating insurance risk in the form of mortality risk. Such contracts are insurance contracts.
B10Under some contracts, an insured event triggers the payment of an amount linked to a price index. Such contracts are insurance contracts, provided that the payment contingent on the insured event could be significant. For example, a life-contingent annuity linked to a cost-of-living index transfers insurance risk because the payment is triggered by an uncertain future event—the survival of the person who receives the annuity. The link to the price index is a derivative, but it also transfers insurance risk because the number of payments to which the index applies depends on the survival of the annuitant. If the resulting transfer of insurance risk is significant, the derivative meets the definition of an insurance contract, in which case it shall not be separated from the host contract (see paragraph 11(a)).
B11Insurance risk is the risk the entity accepts from the policyholder. This means the entity must accept, from the policyholder, a risk to which the policyholder was already exposed. Any new risk created by the contract for the entity or the policyholder is not insurance risk.
B12The definition of an insurance contract refers to an adverse effect on the policyholder. This definition does not limit the payment by the entity to an amount equal to the financial effect of the adverse event. For example, the definition includes 'new for old' insurance coverage that pays the policyholder an amount that permits the replacement of a used and damaged asset with a new one. Similarly, the definition does not limit the payment under a life insurance contract to the financial loss suffered by the deceased's dependants, nor does it exclude contracts that specify the payment of predetermined amounts to quantify the loss caused by death or an accident.
B13Some contracts require a payment if a specified uncertain future event occurs, but do not require an adverse effect on the policyholder as a precondition for the payment. This type of contract is not an insurance contract even if the holder uses it to mitigate an underlying risk exposure. For example, if the holder uses a derivative to hedge an underlying financial or non-financial variable correlated with the cash flows from an asset of the entity, the derivative is not an insurance contract because the payment is not conditional on whether the holder is adversely affected by a reduction in the cash flows from the asset. The definition of an insurance contract refers to an uncertain future event for which an adverse effect on the policyholder is a contractual precondition for payment. A contractual precondition does not require the entity to investigate whether the event actually caused an adverse effect, but it does permit the entity to deny the payment if it is not satisfied that the event did cause an adverse effect.
B14Lapse or persistency risk (the risk that the policyholder will cancel the contract earlier or later than the issuer had expected when pricing the contract) is not insurance risk because the resulting variability in the payment to the policyholder is not contingent on an uncertain future event that adversely affects the policyholder. Similarly, expense risk (ie the risk of unexpected increases in the administrative costs associated with the servicing of a contract, rather than in the costs associated with insured events) is not insurance risk because an unexpected increase in such expenses does not adversely affect the policyholder.
B15Consequently, a contract that exposes the entity to lapse risk, persistency risk or expense risk is not an insurance contract unless it also exposes the entity to significant insurance risk. However, if the entity mitigates its risk by using a second contract to transfer part of the non-insurance risk to another party, the second contract exposes the other party to insurance risk.
B16An entity can accept significant insurance risk from the policyholder only if the entity is separate from the policyholder. In the case of a mutual entity, the mutual entity accepts risk from each policyholder and pools that risk. Although policyholders bear that pooled risk collectively because they hold the residual interest in the entity, the mutual entity is a separate entity that has accepted the risk.
Significant insurance risk
B17A contract is an insurance contract only if it transfers significant insurance risk. Paragraphs B7-B16 discuss insurance risk. Paragraphs B18-B23 discuss the assessment of whether the insurance risk is significant.
B18Insurance risk is significant if, and only if, an insured event could cause the issuer to pay additional amounts that are significant in any single scenario, excluding scenarios that have no commercial substance (ie no discernible effect on the economics of the transaction). If an insured event could mean significant additional amounts would be payable in any scenario that has commercial substance, the condition in the previous sentence can be met even if the insured event is extremely unlikely, or even if the expected (ie probability-weighted) present value of the contingent cash flows is a small proportion of the expected present value of the remaining cash flows from the insurance contract.
B19In addition, a contract transfers significant insurance risk only if there is a scenario that has commercial substance in which the issuer has a possibility of a loss on a present value basis. However, even if a reinsurance contract does not expose the issuer to the possibility of a significant loss, that contract is deemed to transfer significant insurance risk if it transfers to the reinsurer substantially all the insurance risk relating to the reinsured portions of the underlying insurance contracts.
B20The additional amounts described in paragraph B18 are determined on a present-value basis. If an insurance contract requires payment when an event with uncertain timing occurs and if the payment is not adjusted for the time value of money, there may be scenarios in which the present value of the payment increases, even if its nominal value is fixed. An example is insurance that provides a fixed death benefit when the policyholder dies, with no expiry date for the cover (often referred to as whole-life insurance for a fixed amount). It is certain that the policyholder will die, but the date of death is uncertain. Payments may be made when an individual policyholder dies earlier than expected. Because those payments are not adjusted for the time value of money, significant insurance risk could exist even if there is no overall loss on the portfolio of contracts. Similarly, contractual terms that delay timely reimbursement to the policyholder can eliminate significant insurance risk. An entity shall use the discount rates required in paragraph 36 to determine the present value of the additional amounts.
B21The additional amounts described in paragraph B18 refer to the present value of amounts that exceed those that would be payable if no insured event had occurred (excluding scenarios that lack commercial substance). Those additional amounts include claims handling and assessment costs, but exclude:
- the loss of the ability to charge the policyholder for future service. For example, in an investment-linked life insurance contract, the death of the policyholder means that the entity can no longer perform investment management services and collect a fee for doing so. However, this economic loss for the entity does not result from insurance risk, just as a mutual fund manager does not take on insurance risk in relation to the possible death of a client. Consequently, the potential loss of future investment management fees is not relevant when assessing how much insurance risk is transferred by a contract.
- a waiver, on death, of charges that would be made on cancellation or surrender. Because the contract brought those charges into existence, their waiver does not compensate the policyholder for a pre-existing risk. Consequently, they are not relevant when assessing how much insurance risk is transferred by a contract.
- a payment conditional on an event that does not cause a significant loss to the holder of the contract. For example, consider a contract that requires the issuer to pay CU1 million¹ if an asset suffers physical damage that causes an insignificant economic loss of CU1 to the holder. In this contract, the holder transfers the insignificant risk of losing CU1 to the issuer. At the same time, the contract creates a non-insurance risk that the issuer will need to pay CU999,999 if the specified event occurs. Because there is no scenario in which an insured event causes a significant loss to the holder of the contract, the issuer does not accept significant insurance risk from the holder and this contract is not an insurance contract.
- possible reinsurance recoveries. The entity accounts for these separately.
B22An entity shall assess the significance of insurance risk contract by contract. Consequently, the insurance risk can be significant even if there is minimal probability of significant losses for a portfolio or group of contracts.
B23It follows from paragraphs B18-B22 that, if a contract pays a death benefit that exceeds the amount payable on survival, the contract is an insurance contract unless the additional death benefit is not significant (judged by reference to the contract itself rather than to an entire portfolio of contracts). As noted in paragraph B21(b), the waiver on death of cancellation or surrender charges is not included in this assessment if that waiver does not compensate the policyholder for a pre-existing risk. Similarly, an annuity contract that pays out regular sums for the rest of a policyholder's life is an insurance contract, unless the aggregate life-contingent payments are insignificant.
Changes in the level of insurance risk
B24For some contracts, the transfer of insurance risk to the issuer occurs after a period of time. For example, consider a contract that provides a specified investment return and includes an option for the policyholder to use the proceeds of the investment on maturity to buy a life-contingent annuity at the same rates the entity charges other new annuitants at the time the policyholder exercises that option. Such a contract transfers insurance risk to the issuer only after the option is exercised, because the entity remains free to price the annuity on a basis that reflects the insurance risk that will be transferred to the entity at that time. Consequently, the cash flows that would occur on the exercise of the option fall outside the boundary of the contract, and before exercise there are no insurance cash flows within the boundary of the contract. However, if the contract specifies the annuity rates (or a basis other than market rates for setting the annuity rates), the contract transfers insurance risk to the issuer because the issuer is exposed to the risk that the annuity rates will be unfavourable to the issuer when the policyholder exercises the option. In that case, the cash flows that would occur when the option is exercised are within the boundary of the contract.
B25A contract that meets the definition of an insurance contract remains an insurance contract until all rights and obligations are extinguished (ie discharged, cancelled or expired), unless the contract is derecognised applying paragraphs 74–77, because of a contract modification.
Examples of insurance contracts
B26The following are examples of contracts that are insurance contracts if the transfer of insurance risk is significant:
- insurance against theft or damage.
- insurance against product liability, professional liability, civil liability or legal expenses.
- life insurance and prepaid funeral plans (although death is certain, it is uncertain when death will occur or, for some types of life insurance, whether death will occur within the period covered by the insurance).
- life-contingent annuities and pensions, ie contracts that provide compensation for the uncertain future event—the survival of the annuitant or pensioner—to provide the annuitant or pensioner with a level of income that would otherwise be adversely affected by his or her survival. (Employers' liabilities that arise from employee benefit plans and retirement benefit obligations reported by defined benefit retirement plans are outside the scope of IFRS 17, applying paragraph 7(b)).
- insurance against disability and medical costs.
- surety bonds, fidelity bonds, performance bonds and bid bonds, ie contracts that compensate the holder if another party fails to perform a contractual obligation; for example, an obligation to construct a building.
- product warranties. Product warranties issued by another party for goods sold by a manufacturer, dealer or retailer are within the scope of IFRS 17. However, product warranties issued directly by a manufacturer, dealer or retailer are outside the scope of IFRS 17 applying paragraph 7(a), and are instead within the scope of IFRS 15 or IAS 37 Provisions, Contingent Liabilities and Contingent Assets.
B27The following are examples of items that are not insurance contracts:
- investment contracts that have the legal form of an insurance contract but do not transfer significant insurance risk to the issuer. For example, life insurance contracts in which the entity bears no significant mortality or morbidity risk are not insurance contracts; such contracts are financial instruments or service contracts—see paragraph B28. Investment contracts with discretionary participation features do not meet the definition of an insurance contract; however, they are within the scope of IFRS 17 provided they are issued by an entity that also issues insurance contracts, applying paragraph 3(c).
- contracts that have the legal form of insurance, but return all significant insurance risk to the policyholder through non-cancellable and enforceable mechanisms that adjust future payments by the policyholder to the issuer as a direct result of insured losses. For example, some financial reinsurance contracts or some group contracts return all significant insurance risk to the policyholders; such contracts are normally financial instruments or service contracts (see paragraph B28).
- self-insurance (ie retaining a risk that could have been covered by insurance). In such situations, there is no insurance contract because there is no agreement with another party. Thus, if an entity issues an insurance contract to its parent, subsidiary or fellow subsidiary, there is no insurance contract in the consolidated financial statements because there is no contract with another party. However, for the individual or separate financial statements of the issuer or holder, there is an insurance contract.
- contracts (such as gambling contracts) that require a payment if a specified uncertain future event occurs, but do not require, as a contractual precondition for payment, the event to adversely affect the policyholder. However, this does not exclude from the definition of an insurance contract contracts that specify a predetermined payout to quantify the loss caused by a specified event such as a death or an accident (see paragraph B12).
- derivatives that expose a party to financial risk but not insurance risk, because the derivatives require that party to make (or give them the right to receive) payment solely based on the changes in one or more of a specified interest rate, a financial instrument price, a commodity price, a foreign exchange rate, an index of prices or rates, a credit rating or a credit index or any other variable, provided that, in the case of a non-financial variable, the variable is not specific to a party to the contract.
- credit-related guarantees that require payments even if the holder has not incurred a loss on the failure of the debtor to make payments when due; such contracts are accounted for applying IFRS 9 Financial Instruments (see paragraph B29).
- contracts that require a payment that depends on a climatic, geological or any other physical variable not specific to a party to the contract (commonly described as weather derivatives).
- contracts that provide for reduced payments of principal, interest or both, that depend on a climatic, geological or any other physical variable, the effect of which is not specific to a party to the contract (commonly referred to as catastrophe bonds).
B28An entity shall apply other applicable Standards, such as IFRS 9 and IFRS 15, to the contracts described in paragraph B27.
B29The credit-related guarantees and credit insurance contracts discussed in paragraph B27(f) can have various legal forms, such as that of a guarantee, some types of letters of credit, a credit default contract or an insurance contract. Those contracts are insurance contracts if they require the issuer to make specified payments to reimburse the holder for a loss that the holder incurs because a specified debtor fails to make payment when due to the policyholder applying the original or modified terms of a debt instrument. However, such insurance contracts are excluded from the scope of IFRS 17 unless the issuer has previously asserted explicitly that it regards the contracts as insurance contracts and has used accounting applicable to insurance contracts (see paragraph 7(e)).
B30Credit-related guarantees and credit insurance contracts that require payment, even if the policyholder has not incurred a loss on the failure of the debtor to make payments when due, are outside the scope of IFRS 17 because they do not transfer significant insurance risk. Such contracts include those that require payment:
- regardless of whether the counterparty holds the underlying debt instrument; or
- on a change in the credit rating or the credit index, rather than on the failure of a specified debtor to make payments when due.
Separating components from an insurance contract (paragraphs 10–13)
Investment components (paragraph 11(b))
B31Paragraph 11(b) requires an entity to separate a distinct investment component from the host insurance contract. An investment component is distinct if, and only if, both the following conditions are met:
- the investment component and the insurance component are not highly interrelated.
- a contract with equivalent terms is sold, or could be sold, separately in the same market or the same jurisdiction, either by entities that issue insurance contracts or by other parties. The entity shall take into account all information reasonably available in making this determination. The entity is not required to undertake an exhaustive search to identify whether an investment component is sold separately.
B32An investment component and an insurance component are highly interrelated if, and only if:
- the entity is unable to measure one component without considering the other. Thus, if the value of one component varies according to the value of the other, an entity shall apply IFRS 17 to account for the combined investment and insurance component; or
- the policyholder is unable to benefit from one component unless the other is also present. Thus, if the lapse or maturity of one component in a contract causes the lapse or maturity of the other, the entity shall apply IFRS 17 to account for the combined investment component and insurance component.
Promises to transfer distinct goods or services other than insurance contract services (paragraph 12)
B33Paragraph 12 requires an entity to separate from an insurance contract a promise to transfer distinct goods or services other than insurance contract services to a policyholder. For the purpose of separation, an entity shall not consider activities that an entity must undertake to fulfil a contract unless the entity transfers a good or service other than insurance contract services to the policyholder as those activities occur. For example, an entity may need to perform various administrative tasks to set up a contract. The performance of those tasks does not transfer a service to the policyholder as the tasks are performed.
B34A good or service other than an insurance contract service promised to a policyholder is distinct if the policyholder can benefit from the good or service either on its own or together with other resources readily available to the policyholder. Readily available resources are goods or services that are sold separately (by the entity or by another entity), or resources that the policyholder has already got (from the entity or from other transactions or events).
B35A good or service other than an insurance contract service that is promised to the policyholder is not distinct if:
- the cash flows and risks associated with the good or service are highly interrelated with the cash flows and risks associated with the insurance components in the contract; and
- the entity provides a significant service in integrating the good or service with the insurance components.
Insurance acquisition cash flows (paragraphs 28A-28F)
B35ATo apply paragraph 28A, an entity shall use a systematic and rational method to allocate:
- insurance acquisition cash flows directly attributable to a group of insurance contracts:
- to that group; and
- to groups that will include insurance contracts that are expected to arise from renewals of the insurance contracts in that group.
- insurance acquisition cash flows directly attributable to a portfolio of insurance contracts, other than those in (a), to groups of contracts in the portfolio.
B35BAt the end of each reporting period, an entity shall revise amounts allocated as specified in paragraph B35A to reflect any changes in assumptions that determine the inputs to the method of allocation used. An entity shall not change amounts allocated to a group of insurance contracts after all contracts have been added to the group (see paragraph B35C).
B35CAn entity might add insurance contracts to a group of insurance contracts across more than one reporting period (see paragraph 28). In those circumstances, an entity shall derecognise the portion of an asset for insurance acquisition cash flows that relates to insurance contracts added to the group in that period and continue to recognise an asset for insurance acquisition cash flows to the extent that the asset relates to insurance contracts expected to be added to the group in a future reporting period.
B35DTo apply paragraph 28E:
- an entity shall recognise an impairment loss in profit or loss and reduce the carrying amount of an asset for insurance acquisition cash flows so that the carrying amount of the asset does not exceed the expected net cash inflow for the related group of insurance contracts, determined applying paragraph 32(a).
- when an entity allocates insurance acquisition cash flows to groups of insurance contracts applying paragraph B35A(a)(ii), the entity shall recognise an impairment loss in profit or loss and reduce the carrying amount of the related assets for insurance acquisition cash flows to the extent that:
- the entity expects those insurance acquisition cash flows to exceed the net cash inflow for the expected renewals, determined applying paragraph 32(a); and
- the excess determined applying (b)(i) has not already been recognised as an impairment loss applying (a).
Measurement (paragraphs 29–71)
Estimates of future cash flows (paragraphs 33–35)
B36This section addresses:
- unbiased use of all reasonable and supportable information available without undue cost or effort (see paragraphs B37-B41);
- market variables and non-market variables (see paragraphs B42-B53);
- using current estimates (see paragraphs B54-B60); and
- cash flows within the contract boundary (see paragraphs B61-B71).
Unbiased use of all reasonable and supportable information available without undue cost or effort (paragraph 33(a))
B37The objective of estimating future cash flows is to determine the expected value, or probability-weighted mean, of the full range of possible outcomes, considering all reasonable and supportable information available at the reporting date without undue cost or effort. Reasonable and supportable information available at the reporting date without undue cost or effort includes information about past events and current conditions, and forecasts of future conditions (see paragraph B41). Information available from an entity's own information systems is considered to be available without undue cost or effort.
B38The starting point for an estimate of the cash flows is a range of scenarios that reflects the full range of possible outcomes. Each scenario specifies the amount and timing of the cash flows for a particular outcome, and the estimated probability of that outcome. The cash flows from each scenario are discounted and weighted by the estimated probability of that outcome to derive an expected present value. Consequently, the objective is not to develop a most likely outcome, or a more-likely-than-not outcome, for future cash flows.
B39When considering the full range of possible outcomes, the objective is to incorporate all reasonable and supportable information available without undue cost or effort in an unbiased way, rather than to identify every possible scenario. In practice, developing explicit scenarios is unnecessary if the resulting estimate is consistent with the measurement objective of considering all reasonable and supportable information available without undue cost or effort when determining the mean. For example, if an entity estimates that the probability distribution of outcomes is broadly consistent with a probability distribution that can be described completely with a small number of parameters, it will be sufficient to estimate the smaller number of parameters. Similarly, in some cases, relatively simple modelling may give an answer within an acceptable range of precision, without the need for many detailed simulations. However, in some cases, the cash flows may be driven by complex underlying factors and may respond in a non-linear fashion to changes in economic conditions. This may happen if, for example, the cash flows reflect a series of interrelated options that are implicit or explicit. In such cases, more sophisticated stochastic modelling is likely to be necessary to satisfy the measurement objective.
B40The scenarios developed shall include unbiased estimates of the probability of catastrophic losses under existing contracts. Those scenarios exclude possible claims under possible future contracts.
B41An entity shall estimate the probabilities and amounts of future payments under existing contracts on the basis of information obtained including:
- information about claims already reported by policyholders.
- other information about the known or estimated characteristics of the insurance contracts.
- historical data about the entity's own experience, supplemented when necessary with historical data from other sources. Historical data is adjusted to reflect current conditions, for example, if:
- the characteristics of the insured population differ (or will differ, for example, because of adverse selection) from those of the population that has been used as a basis for the historical data;
- there are indications that historical trends will not continue, that new trends will emerge or that economic, demographic and other changes may affect the cash flows that arise from the existing insurance contracts; or
- there have been changes in items such as underwriting procedures and claims management procedures that may affect the relevance of historical data to the insurance contracts.
- current price information, if available, for reinsurance contracts and other financial instruments (if any) covering similar risks, such as catastrophe bonds and weather derivatives, and recent market prices for transfers of insurance contracts. This information shall be adjusted to reflect the differences between the cash flows that arise from those reinsurance contracts or other financial instruments, and the cash flows that would arise as the entity fulfils the underlying contracts with the policyholder.
Market variables and non-market variables
B42IFRS 17 identifies two types of variables:
- market variables—variables that can be observed in, or derived directly from, markets (for example, prices of publicly traded securities and interest rates); and
- non-market variables—all other variables (for example, the frequency and severity of insurance claims and mortality).
B43Market variables will generally give rise to financial risk (for example, observable interest rates) and non-market variables will generally give rise to non-financial risk (for example, mortality rates). However, this will not always be the case. For example, there may be assumptions that relate to financial risks for which variables cannot be observed in, or derived directly from, markets (for example, interest rates that cannot be observed in, or derived directly from, markets).
Market variables (paragraph 33(b))
B44Estimates of market variables shall be consistent with observable market prices at the measurement date. An entity shall maximise the use of observable inputs and shall not substitute its own estimates for observable market data except as described in paragraph 79 of IFRS 13 Fair Value Measurement. Consistent with IFRS 13, if variables need to be derived (for example, because no observable market variables exist) they shall be as consistent as possible with observable market variables.
B45Market prices blend a range of views about possible future outcomes and also reflect the risk preferences of market participants. Consequently, they are not a single-point forecast of the future outcome. If the actual outcome differs from the previous market price, this does not mean that the market price was 'wrong'.
B46An important application of market variables is the notion of a replicating asset or a replicating portfolio of assets. A replicating asset is one whose cash flows exactly match, in all scenarios, the contractual cash flows of a group of insurance contracts in amount, timing and uncertainty. In some cases, a replicating asset may exist for some of the cash flows that arise from a group of insurance contracts. The fair value of that asset reflects both the expected present value of the cash flows from the asset and the risk associated with those cash flows. If a replicating portfolio of assets exists for some of the cash flows that arise from a group of insurance contracts, the entity can use the fair value of those assets to measure the relevant fulfilment cash flows instead of explicitly estimating the cash flows and discount rate.
B47IFRS 17 does not require an entity to use a replicating portfolio technique. However, if a replicating asset or portfolio does exist for some of the cash flows that arise from insurance contracts and an entity chooses to use a different technique, the entity shall satisfy itself that a replicating portfolio technique would be unlikely to lead to a materially different measurement of those cash flows.
B48Techniques other than a replicating portfolio technique, such as stochastic modelling techniques, may be more robust or easier to implement if there are significant interdependencies between cash flows that vary based on returns on assets and other cash flows. Judgement is required to determine the technique that best meets the objective of consistency with observable market variables in specific circumstances. In particular, the technique used must result in the measurement of any options and guarantees included in the insurance contracts being consistent with observable market prices (if any) for such options and guarantees.
Non-market variables
B49Estimates of non-market variables shall reflect all reasonable and supportable evidence available without undue cost or effort, both external and internal.
B50Non-market external data (for example, national mortality statistics) may have more or less relevance than internal data (for example, internally developed mortality statistics), depending on the circumstances. For example, an entity that issues life insurance contracts shall not rely solely on national mortality statistics, but shall consider all other reasonable and supportable internal and external sources of information available without undue cost or effort when developing unbiased estimates of probabilities for mortality scenarios for its insurance contracts. In developing those probabilities, an entity shall give more weight to the more persuasive information. For example:
- internal mortality statistics may be more persuasive than national mortality data if national data is derived from a large population that is not representative of the insured population. This might be because, for example, the demographic characteristics of the insured population could significantly differ from those of the national population, meaning that an entity would need to place more weight on the internal data and less weight on the national statistics.
- conversely, if the internal statistics are derived from a small population with characteristics that are believed to be close to those of the national population, and the national statistics are current, an entity shall place more weight on the national statistics.
B51Estimated probabilities for non-market variables shall not contradict observable market variables. For example, estimated probabilities for future inflation rate scenarios shall be as consistent as possible with probabilities implied by market interest rates.
B52In some cases, an entity may conclude that market variables vary independently of non-market variables. If so, the entity shall consider scenarios that reflect the range of outcomes for the non-market variables, with each scenario using the same observed value of the market variable.
B53In other cases, market variables and non-market variables may be correlated. For example, there may be evidence that lapse rates (a non-market variable) are correlated with interest rates (a market variable). Similarly, there may be evidence that claim levels for house or car insurance are correlated with economic cycles and therefore with interest rates and expense amounts. The entity shall ensure that the probabilities for the scenarios and the risk adjustments for the non-financial risk that relates to the market variables are consistent with the observed market prices that depend on those market variables.
Using current estimates (paragraph 33(c))
B54In estimating each cash flow scenario and its probability, an entity shall use all reasonable and supportable information available without undue cost or effort. An entity shall review the estimates that it made at the end of the previous reporting period and update them. In doing so, an entity shall consider whether:
- the updated estimates faithfully represent the conditions at the end of the reporting period.
- the changes in estimates faithfully represent the changes in conditions during the period. For example, suppose that estimates were at one end of a reasonable range at the beginning of the period. If the conditions have not changed, shifting the estimates to the other end of the range at the end of the period would not faithfully represent what has happened during the period. If an entity's most recent estimates are different from its previous estimates, but conditions have not changed, it shall assess whether the new probabilities assigned to each scenario are justified. In updating its estimates of those probabilities, the entity shall consider both the evidence that supported its previous estimates and all newly available evidence, giving more weight to the more persuasive evidence.
B55The probability assigned to each scenario shall reflect the conditions at the end of the reporting period. Consequently, applying IAS 10 Events after the Reporting Period, an event occurring after the end of the reporting period that resolves an uncertainty that existed at the end of the reporting period does not provide evidence of the conditions that existed at that date. For example, there may be a 20 per cent probability at the end of the reporting period that a major storm will strike during the remaining six months of an insurance contract. After the end of the reporting period but before the financial statements are authorised for issue, a major storm strikes. The fulfilment cash flows under that contract shall not reflect the storm that, with hindsight, is known to have occurred. Instead, the cash flows included in the measurement include the 20 per cent probability apparent at the end of the reporting period (with disclosure applying IAS 10 that a non-adjusting event occurred after the end of the reporting period).
B56Current estimates of expected cash flows are not necessarily identical to the most recent actual experience. For example, suppose that mortality experience in the reporting period was 20 per cent worse than the previous mortality experience and previous expectations of mortality experience. Several factors could have caused the sudden change in experience, including:
- lasting changes in mortality;
- changes in the characteristics of the insured population (for example, changes in underwriting or distribution, or selective lapses by policyholders in unusually good health);
- random fluctuations; or
- identifiable non-recurring causes.
B57An entity shall investigate the reasons for the change in experience and develop new estimates of cash flows and probabilities in the light of the most recent experience, the earlier experience and other information. The result for the example in paragraph B56 would typically be that the expected present value of death benefits changes, but not by as much as 20 per cent. In the example in paragraph B56, if mortality rates continue to be significantly higher than the previous estimates for reasons that are expected to continue, the estimated probability assigned to the high-mortality scenarios will increase.
B58Estimates of non-market variables shall include information about the current level of insured events and information about trends. For example, mortality rates have consistently declined over long periods in many countries. The determination of the fulfilment cash flows reflects the probabilities that would be assigned to each possible trend scenario, taking account of all reasonable and supportable information available without undue cost or effort.
B59Similarly, if cash flows allocated to a group of insurance contracts are sensitive to inflation, the determination of the fulfilment cash flows shall reflect current estimates of possible future inflation rates. Because inflation rates are likely to be correlated with interest rates, the measurement of fulfilment cash flows shall reflect the probabilities for each inflation scenario in a way that is consistent with the probabilities implied by the market interest rates used in estimating the discount rate (see paragraph B51).
B60When estimating the cash flows, an entity shall take into account current expectations of future events that might affect those cash flows. The entity shall develop cash flow scenarios that reflect those future events, as well as unbiased estimates of the probability of each scenario. However, an entity shall not take into account current expectations of future changes in legislation that would change or discharge the present obligation or create new obligations under the existing insurance contract until the change in legislation is substantively enacted.
Cash flows within the contract boundary (paragraph 34)
B61Estimates of cash flows in a scenario shall include all cash flows within the boundary of an existing contract and no other cash flows. An entity shall apply paragraph 2 in determining the boundary of an existing contract.
B62Many insurance contracts have features that enable policyholders to take actions that change the amount, timing, nature or uncertainty of the amounts they will receive. Such features include renewal options, surrender options, conversion options and options to stop paying premiums while still receiving benefits under the contracts. The measurement of a group of insurance contracts shall reflect, on an expected value basis, the entity's current estimates of how the policyholders in the group will exercise the options available, and the risk adjustment for non-financial risk shall reflect the entity's current estimates of how the actual behaviour of the policyholders may differ from the expected behaviour. This requirement to determine the expected value applies regardless of the number of contracts in a group; for example it applies even if the group comprises a single contract. Thus, the measurement of a group of insurance contracts shall not assume a 100 per cent probability that policyholders will:
- surrender their contracts, if there is some probability that some of the policyholders will not; or
- continue their contracts, if there is some probability that some of the policyholders will not.
B63When an issuer of an insurance contract is required by the contract to renew or otherwise continue the contract, it shall apply paragraph 34 to assess whether premiums and related cash flows that arise from the renewed contract are within the boundary of the original contract.
B64Paragraph 34 refers to an entity's practical ability to set a price at a future date (a renewal date) that fully reflects the risks in the contract from that date. An entity has that practical ability in the absence of constraints that prevent the entity from setting the same price it would for a new contract with the same characteristics as the existing contract issued on that date, or if it can amend the benefits to be consistent with the price it will charge. Similarly, an entity has that practical ability to set a price when it can reprice an existing contract so that the price reflects overall changes in the risks in a portfolio of insurance contracts, even if the price set for each individual policyholder does not reflect the change in risk for that specific policyholder. When assessing whether the entity has the practical ability to set a price that fully reflects the risks in the contract or portfolio, it shall consider all the risks that it would consider when underwriting equivalent contracts on the renewal date for the remaining service. In determining the estimates of future cash flows at the end of a reporting period, an entity shall reassess the boundary of an insurance contract to include the effect of changes in circumstances on the entity's substantive rights and obligations.
B65Cash flows within the boundary of an insurance contract are those that relate directly to the fulfilment of the contract, including cash flows for which the entity has discretion over the amount or timing. The cash flows within the boundary include:
- premiums (including premium adjustments and instalment premiums) from a policyholder and any additional cash flows that result from those premiums.
- payments to (or on behalf of) a policyholder, including claims that have already been reported but have not yet been paid (ie reported claims), incurred claims for events that have occurred but for which claims have not been reported and all future claims for which the entity has a substantive obligation (see paragraph 34).
- payments to (or on behalf of) a policyholder that vary depending on returns on underlying items.
- payments to (or on behalf of) a policyholder resulting from derivatives, for example, options and guarantees embedded in the contract, to the extent that those options and guarantees are not separated from the insurance contract (see paragraph 11(a)).
- an allocation of insurance acquisition cash flows attributable to the portfolio to which the contract belongs.
- claim handling costs (ie the costs the entity will incur in investigating, processing and resolving claims under existing insurance contracts, including legal and loss-adjusters' fees and internal costs of investigating claims and processing claim payments).
- costs the entity will incur in providing contractual benefits paid in kind.
- policy administration and maintenance costs, such as costs of premium billing and handling policy changes (for example, conversions and reinstatements). Such costs also include recurring commissions that are expected to be paid to intermediaries if a particular policyholder continues to pay the premiums within the boundary of the insurance contract.
- transaction-based taxes (such as premium taxes, value added taxes and goods and services taxes) and levies (such as fire service levies and guarantee fund assessments) that arise directly from existing insurance contracts, or that can be attributed to them on a reasonable and consistent basis.
- payments by the insurer in a fiduciary capacity to meet tax obligations incurred by the policyholder, and related receipts.
- potential cash inflows from recoveries (such as salvage and subrogation) on future claims covered by existing insurance contracts and, to the extent that they do not qualify for recognition as separate assets, potential cash inflows from recoveries on past claims.
- costs the entity will incur:
- performing investment activity, to the extent the entity performs that activity to enhance benefits from insurance coverage for policyholders. Investment activities enhance benefits from insurance coverage if the entity performs those activities expecting to generate an investment return from which policyholders will benefit if an insured event occurs.
- providing investment-return service to policyholders of insurance contracts without direct participation features (see paragraph B119B).
- providing investment-related service to policyholders of insurance contracts with direct participation features.
- an allocation of fixed and variable overheads (such as the costs of accounting, human resources, information technology and support, building depreciation, rent, and maintenance and utilities) directly attributable to fulfilling insurance contracts. Such overheads are allocated to groups of contracts using methods that are systematic and rational, and are consistently applied to all costs that have similar characteristics.
- any other costs specifically chargeable to the policyholder under the terms of the contract.
B66The following cash flows shall not be included when estimating the cash flows that will arise as the entity fulfils an existing insurance contract:
- investment returns. Investments are recognised, measured and presented separately.
- cash flows (payments or receipts) that arise under reinsurance contracts held. Reinsurance contracts held are recognised, measured and presented separately.
- cash flows that may arise from future insurance contracts, ie cash flows outside the boundary of existing contracts (see paragraphs 34–35).
- cash flows relating to costs that cannot be directly attributed to the portfolio of insurance contracts that contain the contract, such as some product development and training costs. Such costs are recognised in profit or loss when incurred.
- cash flows that arise from abnormal amounts of wasted labour or other resources that are used to fulfil the contract. Such costs are recognised in profit or loss when incurred.
- income tax payments and receipts the insurer does not pay or receive in a fiduciary capacity or that are not specifically chargeable to the policyholder under the terms of the contract.
- cash flows between different components of the reporting entity, such as policyholder funds and shareholder funds, if those cash flows do not change the amount that will be paid to the policyholders.
- cash flows arising from components separated from the insurance contract and accounted for using other applicable Standards (see paragraphs 10–13).
B66ABefore the recognition of a group of insurance contracts, an entity might be required to recognise an asset or liability for cash flows related to the group of insurance contracts other than insurance acquisition cash flows either because of the occurrence of the cash flows or because of the requirements of another IFRS Standard. Cash flows are related to the group of insurance contracts if those cash flows would have been included in the fulfilment cash flows at the date of initial recognition of the group had they been paid or received after that date. To apply paragraph 38(c)(ii) an entity shall derecognise such an asset or liability to the extent that the asset or liability would not be recognised separately from the group of insurance contracts if the cash flow or the application of the IFRS Standard occurred at the date of initial recognition of the group of insurance contracts.
Contracts with cash flows that affect or are affected by cash flows to policyholders of other contracts
B67Some insurance contracts affect the cash flows to policyholders of other contracts by requiring:
- the policyholder to share with policyholders of other contracts the returns on the same specified pool of underlying items; and
- either:
- the policyholder to bear a reduction in their share of the returns on the underlying items because of payments to policyholders of other contracts that share in that pool, including payments arising under guarantees made to policyholders of those other contracts; or
- policyholders of other contracts to bear a reduction in their share of returns on the underlying items because of payments to the policyholder, including payments arising from guarantees made to the policyholder.
B68Sometimes, such contracts will affect the cash flows to policyholders of contracts in other groups. The fulfilment cash flows of each group reflect the extent to which the contracts in the group cause the entity to be affected by expected cash flows, whether to policyholders in that group or to policyholders in another group. Hence the fulfilment cash flows for a group:
- include payments arising from the terms of existing contracts to policyholders of contracts in other groups, regardless of whether those payments are expected to be made to current or future policyholders; and
- exclude payments to policyholders in the group that, applying (a), have been included in the fulfilment cash flows of another group.
B69For example, to the extent that payments to policyholders in one group are reduced from a share in the returns on underlying items of CU350 to CU250 because of payments of a guaranteed amount to policyholders in another group, the fulfilment cash flows of the first group would include the payments of CU100 (ie would be CU350) and the fulfilment cash flows of the second group would exclude CU100 of the guaranteed amount.
B70Different practical approaches can be used to determine the fulfilment cash flows of groups of contracts that affect or are affected by cash flows to policyholders of contracts in other groups. In some cases, an entity might be able to identify the change in the underlying items and resulting change in the cash flows only at a higher level of aggregation than the groups. In such cases, the entity shall allocate the effect of the change in the underlying items to each group on a systematic and rational basis.
B71After all insurance contract services have been provided to the contracts in a group, the fulfilment cash flows may still include payments expected to be made to current policyholders in other groups or future policyholders. An entity is not required to continue to allocate such fulfilment cash flows to specific groups but can instead recognise and measure a liability for such fulfilment cash flows arising from all groups.
Discount rates (paragraph 36)
B72An entity shall use the following discount rates in applying IFRS 17:
- to measure the fulfilment cash flows—current discount rates applying paragraph 36;
- to determine the interest to accrete on the contractual service margin applying paragraph 44(b) for insurance contracts without direct participation features—discount rates determined at the date of initial recognition of a group of contracts, applying paragraph 36 to nominal cash flows that do not vary based on the returns on any underlying items;
- to measure the changes to the contractual service margin applying paragraphs B96(a)–B96(b) and B96(d) for insurance contracts without direct participation features—discount rates applying paragraph 36 determined on initial recognition;
- for groups of contracts applying the premium allocation approach that have a significant financing component, to adjust the carrying amount of the liability for remaining coverage applying paragraph 56—discount rates applying paragraph 36 determined on initial recognition;
- if an entity chooses to disaggregate insurance finance income or expenses between profit or loss and other comprehensive income (see paragraph 88), to determine the amount of the insurance finance income or expenses included in profit or loss:
- for groups of insurance contracts for which changes in assumptions that relate to financial risk do not have a substantial effect on the amounts paid to policyholders, applying paragraph B131—discount rates determined at the date of initial recognition of a group of contracts, applying paragraph 36 to nominal cash flows that do not vary based on the returns on any underlying items;
- for groups of insurance contracts for which changes in assumptions that relate to financial risk have a substantial effect on the amounts paid to policyholders, applying paragraph B132(a)(i)—discount rates that allocate the remaining revised expected finance income or expenses over the remaining duration of the group of contracts at a constant rate; and
- for groups of contracts applying the premium allocation approach applying paragraphs 59(b) and B133—discount rates determined at the date of the incurred claim, applying paragraph 36 to nominal cash flows that do not vary based on the returns on any underlying items.
B73To determine the discount rates at the date of initial recognition of a group of contracts described in paragraphs B72(b)–B72(e), an entity may use weighted-average discount rates over the period that contracts in the group are issued, which applying paragraph 22 cannot exceed one year.
B74Estimates of discount rates shall be consistent with other estimates used to measure insurance contracts to avoid double counting or omissions; for example:
- cash flows that do not vary based on the returns on any underlying items shall be discounted at rates that do not reflect any such variability;
- cash flows that vary based on the returns on any financial underlying items shall be:
- discounted using rates that reflect that variability; or
- adjusted for the effect of that variability and discounted at a rate that reflects the adjustment made.
- nominal cash flows (ie those that include the effect of inflation) shall be discounted at rates that include the effect of inflation; and
- real cash flows (ie those that exclude the effect of inflation) shall be discounted at rates that exclude the effect of inflation.
B75Paragraph B74(b) requires cash flows that vary based on the returns on underlying items to be discounted using rates that reflect that variability, or to be adjusted for the effect of that variability and discounted at a rate that reflects the adjustment made. The variability is a relevant factor regardless of whether it arises because of contractual terms or because the entity exercises discretion, and regardless of whether the entity holds the underlying items.
B76Cash flows that vary with returns on underlying items with variable returns, but that are subject to a guarantee of a minimum return, do not vary solely based on the returns on the underlying items, even when the guaranteed amount is lower than the expected return on the underlying items. Hence, an entity shall adjust the rate that reflects the variability of the returns on the underlying items for the effect of the guarantee, even when the guaranteed amount is lower than the expected return on the underlying items.
B77IFRS 17 does not require an entity to divide estimated cash flows into those that vary based on the returns on underlying items and those that do not. If an entity does not divide the estimated cash flows in this way, the entity shall apply discount rates appropriate for the estimated cash flows as a whole; for example, using stochastic modelling techniques or risk-neutral measurement techniques.
B78Discount rates shall include only relevant factors, ie factors that arise from the time value of money, the characteristics of the cash flows and the liquidity characteristics of the insurance contracts. Such discount rates may not be directly observable in the market. Hence, when observable market rates for an instrument with the same characteristics are not available, or observable market rates for similar instruments are available but do not separately identify the factors that distinguish the instrument from the insurance contracts, an entity shall estimate the appropriate rates. IFRS 17 does not require a particular estimation technique for determining discount rates. In applying an estimation technique, an entity shall:
- maximise the use of observable inputs (see paragraph B44) and reflect all reasonable and supportable information on non-market variables available without undue cost or effort, both external and internal (see paragraph B49). In particular, the discount rates used shall not contradict any available and relevant market data, and any non-market variables used shall not contradict observable market variables.
- reflect current market conditions from the perspective of a market participant.
- exercise judgement to assess the degree of similarity between the features of the insurance contracts being measured and the features of the instrument for which observable market prices are available and adjust those prices to reflect the differences between them.
B79For cash flows of insurance contracts that do not vary based on the returns on underlying items, the discount rate reflects the yield curve in the appropriate currency for instruments that expose the holder to no or negligible credit risk, adjusted to reflect the liquidity characteristics of the group of insurance contracts. That adjustment shall reflect the difference between the liquidity characteristics of the group of insurance contracts and the liquidity characteristics of the assets used to determine the yield curve. Yield curves reflect assets traded in active markets that the holder can typically sell readily at any time without incurring significant costs. In contrast, under some insurance contracts the entity cannot be forced to make payments earlier than the occurrence of insured events, or dates specified in the contracts.
B80Hence, for cash flows of insurance contracts that do not vary based on the returns on underlying items, an entity may determine discount rates by adjusting a liquid risk-free yield curve to reflect the differences between the liquidity characteristics of the financial instruments that underlie the rates observed in the market and the liquidity characteristics of the insurance contracts (a bottom-up approach).
B81Alternatively, an entity may determine the appropriate discount rates for insurance contracts based on a yield curve that reflects the current market rates of return implicit in a fair value measurement of a reference portfolio of assets (a top-down approach). An entity shall adjust that yield curve to eliminate any factors that are not relevant to the insurance contracts, but is not required to adjust the yield curve for differences in liquidity characteristics of the insurance contracts and the reference portfolio.
B82In estimating the yield curve described in paragraph B81:
- if there are observable market prices in active markets for assets in the reference portfolio, an entity shall use those prices (consistent with paragraph 69 of IFRS 13).
- if a market is not active, an entity shall adjust observable market prices for similar assets to make them comparable to market prices for the assets being measured (consistent with paragraph 83 of IFRS 13).
- if there is no market for assets in the reference portfolio, an entity shall apply an estimation technique. For such assets (consistent with paragraph 89 of IFRS 13) an entity shall:
- develop unobservable inputs using the best information available in the circumstances. Such inputs might include the entity's own data and, in the context of IFRS 17, the entity might place more weight on long-term estimates than on short-term fluctuations; and
- adjust those data to reflect all information about market participant assumptions that is reasonably available.
B83In adjusting the yield curve, an entity shall adjust market rates observed in recent transactions in instruments with similar characteristics for movements in market factors since the transaction date, and shall adjust observed market rates to reflect the degree of dissimilarity between the instrument being measured and the instrument for which transaction prices are observable. For cash flows of insurance contracts that do not vary based on the returns on the assets in the reference portfolio, such adjustments include:
- adjusting for differences between the amount, timing and uncertainty of the cash flows of the assets in the portfolio and the amount, timing and uncertainty of the cash flows of the insurance contracts; and
- excluding market risk premiums for credit risk, which are relevant only to the assets included in the reference portfolio.
B84In principle, for cash flows of insurance contracts that do not vary based on the returns of the assets in the reference portfolio, there should be a single illiquid risk-free yield curve that eliminates all uncertainty about the amount and timing of cash flows. However, in practice the top-down approach and the bottom-up approach may result in different yield curves, even in the same currency. This is because of the inherent limitations in estimating the adjustments made under each approach, and the possible lack of an adjustment for different liquidity characteristics in the top-down approach. An entity is not required to reconcile the discount rate determined under its chosen approach with the discount rate that would have been determined under the other approach.
B85IFRS 17 does not specify restrictions on the reference portfolio of assets used in applying paragraph B81. However, fewer adjustments would be required to eliminate factors that are not relevant to the insurance contracts when the reference portfolio of assets has similar characteristics. For example, if the cash flows from the insurance contracts do not vary based on the returns on underlying items, fewer adjustments would be required if an entity used debt instruments as a starting point rather than equity instruments. For debt instruments, the objective would be to eliminate from the total bond yield the effect of credit risk and other factors that are not relevant to the insurance contracts. One way to estimate the effect of credit risk is to use the market price of a credit derivative as a reference point.
Risk adjustment for non-financial risk (paragraph 37)
B86The risk adjustment for non-financial risk relates to risk arising from insurance contracts other than financial risk. Financial risk is included in the estimates of the future cash flows or the discount rate used to adjust the cash flows. The risks covered by the risk adjustment for non-financial risk are insurance risk and other non-financial risks such as lapse risk and expense risk (see paragraph B14).
B87The risk adjustment for non-financial risk for insurance contracts measures the compensation that the entity would require to make the entity indifferent between:
- fulfilling a liability that has a range of possible outcomes arising from non-financial risk; and
- fulfilling a liability that will generate fixed cash flows with the same expected present value as the insurance contracts.
For example, the risk adjustment for non-financial risk would measure the compensation the entity would require to make it indifferent between fulfilling a liability that—because of non-financial risk—has a 50 per cent probability of being CU90 and a 50 per cent probability of being CU110, and fulfilling a liability that is fixed at CU100. As a result, the risk adjustment for non-financial risk conveys information to users of financial statements about the amount charged by the entity for the uncertainty arising from non-financial risk about the amount and timing of cash flows.
B88Because the risk adjustment for non-financial risk reflects the compensation the entity would require for bearing the non-financial risk arising from the uncertain amount and timing of the cash flows, the risk adjustment for non-financial risk also reflects:
- the degree of diversification benefit the entity includes when determining the compensation it requires for bearing that risk; and
- both favourable and unfavourable outcomes, in a way that reflects the entity's degree of risk aversion.
B89The purpose of the risk adjustment for non-financial risk is to measure the effect of uncertainty in the cash flows that arise from insurance contracts, other than uncertainty arising from financial risk. Consequently, the risk adjustment for non-financial risk shall reflect all non-financial risks associated with the insurance contracts. It shall not reflect the risks that do not arise from the insurance contracts, such as general operational risk.
B90The risk adjustment for non-financial risk shall be included in the measurement in an explicit way. The risk adjustment for non-financial risk is conceptually separate from the estimates of future cash flows and the discount rates that adjust those cash flows. The entity shall not double-count the risk adjustment for non-financial risk by, for example, also including the risk adjustment for non-financial risk implicitly when determining the estimates of future cash flows or the discount rates. The discount rates that are disclosed to comply with paragraph 120 shall not include any implicit adjustments for non-financial risk.
B91IFRS 17 does not specify the estimation technique(s) used to determine the risk adjustment for non-financial risk. However, to reflect the compensation the entity would require for bearing the non-financial risk, the risk adjustment for non-financial risk shall have the following characteristics:
- risks with low frequency and high severity will result in higher risk adjustments for non-financial risk than risks with high frequency and low severity;
- for similar risks, contracts with a longer duration will result in higher risk adjustments for non-financial risk than contracts with a shorter duration;
- risks with a wider probability distribution will result in higher risk adjustments for non-financial risk than risks with a narrower distribution;
- the less that is known about the current estimate and its trend, the higher will be the risk adjustment for non-financial risk; and
- to the extent that emerging experience reduces uncertainty about the amount and timing of cash flows, risk adjustments for non-financial risk will decrease and vice versa.
B92An entity shall apply judgement when determining an appropriate estimation technique for the risk adjustment for non-financial risk. When applying that judgement, an entity shall also consider whether the technique provides concise and informative disclosure so that users of financial statements can benchmark the entity's performance against the performance of other entities. Paragraph 119 requires an entity that uses a technique other than the confidence level technique for determining the risk adjustment for non-financial risk to disclose the technique used and the confidence level corresponding to the results of that technique.
Initial recognition of transfers of insurance contracts and business combinations (paragraph 39)
B93When an entity acquires insurance contracts issued or reinsurance contracts held in a transfer of insurance contracts that do not form a business or in a business combination within the scope of IFRS 3, the entity shall apply paragraphs 14–24 to identify the groups of contracts acquired, as if it had entered into the contracts on the date of the transaction.
B94An entity shall use the consideration received or paid for the contracts as a proxy for the premiums received. The consideration received or paid for the contracts excludes the consideration received or paid for any other assets and liabilities acquired in the same transaction. In a business combination within the scope of IFRS 3, the consideration received or paid is the fair value of the contracts at that date. In determining that fair value, an entity shall not apply paragraph 47 of IFRS 13 (relating to demand features).
B95Unless the premium allocation approach for the liability for remaining coverage in paragraphs 55–59 and 69–70A applies, on initial recognition the contractual service margin is calculated applying paragraph 38 for acquired insurance contracts issued and paragraph 65 for acquired reinsurance contracts held using the consideration received or paid for the contracts as a proxy for the premiums received or paid at the date of initial recognition.
B95AIf acquired insurance contracts issued are onerous, applying paragraph 47, the entity shall recognise the excess of the fulfilment cash flows over the consideration paid or received as part of goodwill or gain on a bargain purchase for contracts acquired in a business combination within the scope of IFRS 3, or as a loss in profit or loss for contracts acquired in a transfer. The entity shall establish a loss component of the liability for remaining coverage for that excess, and apply paragraphs 49–52 to allocate subsequent changes in fulfilment cash flows to that loss component.
B95BFor a group of reinsurance contracts held to which paragraphs 66A–66B apply, an entity shall determine the loss-recovery component of the asset for remaining coverage at the date of the transaction by multiplying:
- the loss component of the liability for remaining coverage of the underlying insurance contracts at the date of the transaction; and
- the percentage of claims on the underlying insurance contracts the entity expects at the date of the transaction to recover from the group of reinsurance contracts held.
B95CThe entity shall recognise the amount of the loss-recovery component determined applying paragraph B95B as part of goodwill or gain on a bargain purchase for reinsurance contracts held acquired in a business combination within the scope of IFRS 3, or as income in profit or loss for contracts acquired in a transfer.
B95DApplying paragraphs 14–22, at the date of the transaction an entity might include in an onerous group of insurance contracts both onerous insurance contracts covered by a group of reinsurance contracts held and onerous contracts not covered by the group of reinsurance contracts held. To apply paragraph B95B in such cases, an entity shall use a systematic and rational basis of allocation to determine the portion of the loss component of the group of insurance contracts that relates to insurance contracts covered by the group of reinsurance contracts held.
Asset for insurance acquisition cash flows
B95EWhen an entity acquires insurance contracts issued in a transfer of insurance contracts that do not form a business or in a business combination within the scope of IFRS 3, the entity shall recognise an asset for insurance acquisition cash flows at fair value at the date of the transaction for the rights to obtain:
- future insurance contracts that are renewals of insurance contracts recognised at the date of the transaction; and
- future insurance contracts, other than those in (a), after the date of the transaction without paying again insurance acquisition cash flows the acquiree has already paid that are directly attributable to the related portfolio of insurance contracts.
B95FAt the date of the transaction, the amount of any asset for insurance acquisition cash flows shall not be included in the measurement of the acquired group of insurance contracts applying paragraphs B93–B95A.
Changes in the carrying amount of the contractual service margin for insurance contracts without direct participation features (paragraph 44)
B96For insurance contracts without direct participation features, paragraph 44(c) requires an adjustment to the contractual service margin of a group of insurance contracts for changes in fulfilment cash flows that relate to future service. These changes comprise:
- experience adjustments arising from premiums received in the period that relate to future service, and related cash flows such as insurance acquisition cash flows and premium-based taxes, measured at the discount rates specified in paragraph B72(c).
- changes in estimates of the present value of the future cash flows in the liability for remaining coverage, except those described in paragraph B97(a), measured at the discount rates specified in paragraph B72(c).
- differences between any investment component expected to become payable in the period and the actual investment component that becomes payable in the period. Those differences are determined by comparing (i) the actual investment component that becomes payable in the period with (ii) the payment in the period that was expected at the start of the period plus any insurance finance income or expenses related to that expected payment before it becomes payable.
- differences between any loan to a policyholder expected to become repayable in the period and the actual loan to a policyholder that becomes repayable in the period. Those differences are determined by comparing (i) the actual loan to a policyholder that becomes repayable in the period with (ii) the repayment in the period that was expected at the start of the period plus any insurance finance income or expenses related to that expected repayment before it becomes repayable.
- changes in the risk adjustment for non-financial risk that relate to future service. An entity is not required to disaggregate the change in the risk adjustment for non-financial risk between (i) a change related to non-financial risk and (ii) the effect of the time value of money and changes in the time value of money. If an entity makes such a disaggregation, it shall adjust the contractual service margin for the change related to non-financial risk, measured at the discount rates specified in paragraph B72(c).
B97An entity shall not adjust the contractual service margin for a group of insurance contracts without direct participation features for the following changes in fulfilment cash flows because they do not relate to future service:
- the effect of the time value of money and changes in the time value of money and the effect of financial risk and changes in financial risk. These effects comprise:
B98The terms of some insurance contracts without direct participation features give an entity discretion over the cash flows to be paid to policyholders. A change in the discretionary cash flows is regarded as relating to future service, and accordingly adjusts the contractual service margin. To determine how to identify a change in discretionary cash flows, an entity shall specify at inception of the contract the basis on which it expects to determine its commitment under the contract; for example, based on a fixed interest rate, or on returns that vary based on specified asset returns.
B99An entity shall use that specification to distinguish between the effect of changes in assumptions that relate to financial risk on that commitment (which do not adjust the contractual service margin) and the effect of discretionary changes to that commitment (which adjust the contractual service margin).
B100If an entity cannot specify at inception of the contract what it regards as its commitment under the contract and what it regards as discretionary, it shall regard its commitment to be the return implicit in the estimate of the fulfilment cash flows at inception of the contract, updated to reflect current assumptions that relate to financial risk.
Changes in the carrying amount of the contractual service margin for insurance contracts with direct participation features (paragraph 45)
B101Insurance contracts with direct participation features are insurance contracts that are substantially investment-related service contracts under which an entity promises an investment return based on underlying items. Hence, they are defined as insurance contracts for which:
- the contractual terms specify that the policyholder participates in a share of a clearly identified pool of underlying items (see paragraphs B105–B106);
- the entity expects to pay to the policyholder an amount equal to a substantial share of the fair value returns on the underlying items (see paragraph B107); and
- the entity expects a substantial proportion of any change in the amounts to be paid to the policyholder to vary with the change in fair value of the underlying items (see paragraph B107).
B102An entity shall assess whether the conditions in paragraph B101 are met using its expectations at inception of the contract and shall not reassess the conditions afterwards, unless the contract is modified, applying paragraph 72.
B103To the extent that insurance contracts in a group affect the cash flows to policyholders of contracts in other groups (see paragraphs B67–B71), an entity shall assess whether the conditions in paragraph B101 are met by considering the cash flows that the entity expects to pay the policyholders determined applying paragraphs B68–B70.
B104The conditions in paragraph B101 ensure that insurance contracts with direct participation features are contracts under which the entity’s obligation to the policyholder is the net of:
- the obligation to pay the policyholder an amount equal to the fair value of the underlying items; and
- a variable fee (see paragraphs B110–B118) that the entity will deduct from (a) in exchange for the future service provided by the insurance contract, comprising:
- the amount of the entity’s share of the fair value of the underlying items; less
- fulfilment cash flows that do not vary based on the returns on underlying items.
B105A share referred to in paragraph B101(a) does not preclude the existence of the entity’s discretion to vary the amounts paid to the policyholder. However, the link to the underlying items must be enforceable (see paragraph 2).
B106The pool of underlying items referred to in paragraph B101(a) can comprise any items, for example a reference portfolio of assets, the net assets of the entity, or a specified subset of the net assets of the entity, as long as they are clearly identified by the contract. An entity need not hold the identified pool of underlying items. However, a clearly identified pool of underlying items does not exist when:
- an entity can change the underlying items that determine the amount of the entity’s obligation with retrospective effect; or
- there are no underlying items identified, even if the policyholder could be provided with a return that generally reflects the entity’s overall performance and expectations, or the performance and expectations of a subset of assets the entity holds. An example of such a return is a crediting rate or dividend payment set at the end of the period to which it relates. In this case, the obligation to the policyholder reflects the crediting rate or dividend amounts the entity has set, and does not reflect identified underlying items.
B107Paragraph B101(b) requires that the entity expects a substantial share of the fair value returns on the underlying items will be paid to the policyholder and paragraph B101(c) requires that the entity expects a substantial proportion of any change in the amounts to be paid to the policyholder to vary with the change in fair value of the underlying items. An entity shall:
- interpret the term ‘substantial’ in both paragraphs in the context of the objective of insurance contracts with direct participation features being contracts under which the entity provides investment-related services and is compensated for the services by a fee that is determined by reference to the underlying items; and
- assess the variability in the amounts in paragraphs B101(b) and B101(c):
- over the duration of the insurance contract; and
- on a present value probability-weighted average basis, not a best or worst outcome basis (see paragraphs B37–B38).
B108For example, if the entity expects to pay a substantial share of the fair value returns on underlying items, subject to a guarantee of a minimum return, there will be scenarios in which:
- the cash flows that the entity expects to pay to the policyholder vary with the changes in the fair value of the underlying items because the guaranteed return and other cash flows that do not vary based on the returns on underlying items do not exceed the fair value return on the underlying items; and
- the cash flows that the entity expects to pay to the policyholder do not vary with the changes in the fair value of the underlying items because the guaranteed return and other cash flows that do not vary based on the returns on underlying items exceed the fair value return on the underlying items.
The entity’s assessment of the variability in paragraph B101(c) for this example will reflect a present value probability-weighted average of all these scenarios.
B109Reinsurance contracts issued and reinsurance contracts held cannot be insurance contracts with direct participation features for the purposes of IFRS 17.
B110For insurance contracts with direct participation features, the contractual service margin is adjusted to reflect the variable nature of the fee. Hence, changes in the amounts set out in paragraph B104 are treated as set out in paragraphs B111–B114.
B111Changes in the obligation to pay the policyholder an amount equal to the fair value of the underlying items (paragraph B104(a)) do not relate to future service and do not adjust the contractual service margin.
B112Changes in the amount of the entity’s share of the fair value of the underlying items (paragraph B104(b)(i)) relate to future service and adjust the contractual service margin, applying paragraph 45(b).
B113Changes in the fulfilment cash flows that do not vary based on the returns on underlying items (paragraph B104(b)(ii)) comprise:
- changes in the fulfilment cash flows other than those specified in (b). An entity shall apply paragraphs B96–B97, consistent with insurance contracts without direct participation features, to determine to what extent they relate to future service and, applying paragraph 45(c), adjust the contractual service margin. All the adjustments are measured using current discount rates.
- the change in the effect of the time value of money and financial risks not arising from the underlying items; for example, the effect of financial guarantees. These relate to future service and, applying paragraph 45(c), adjust the contractual service margin, except to the extent that paragraph B115 applies.
B114An entity is not required to identify the adjustments to the contractual service margin required by paragraphs B112 and B113 separately. Instead, a combined amount may be determined for some or all of the adjustments.
Risk mitigation
B115To the extent that an entity meets the conditions in paragraph B116, it may choose not to recognise a change in the contractual service margin to reflect some or all of the changes in the effect of the time value of money and financial risk on:
- the amount of the entity’s share of the underlying items (see paragraph B112) if the entity mitigates the effect of financial risk on that amount using derivatives or reinsurance contracts held; and
- the fulfilment cash flows set out in paragraph B113(b) if the entity mitigates the effect of financial risk on those fulfilment cash flows using derivatives, non-derivative financial instruments measured at fair value through profit or loss, or reinsurance contracts held.
B116To apply paragraph B115, an entity must have a previously documented risk-management objective and strategy for mitigating financial risk as described in paragraph B115. In applying that objective and strategy:
- an economic offset exists between the insurance contracts and the derivative, non-derivative financial instrument measured at fair value through profit or loss, or reinsurance contract held (ie the values of the insurance contracts and those risk mitigating items generally move in opposite directions because they respond in a similar way to the changes in the risk being mitigated). An entity shall not consider accounting measurement differences in assessing the economic offset.
- credit risk does not dominate the economic offset.
B117The entity shall determine the fulfilment cash flows in a group to which paragraph B115 applies in a consistent manner in each reporting period.
B117AIf the entity mitigates the effect of financial risk using derivatives or non-derivative financial instruments measured at fair value through profit or loss, it shall include insurance finance income or expenses for the period arising from the application of paragraph B115 in profit or loss. If the entity mitigates the effect of financial risk using reinsurance contracts held, it shall apply the same accounting policy for the presentation of insurance finance income or expenses arising from the application of paragraph B115 as the entity applies to the reinsurance contracts held applying paragraphs 88 and 90.
B118If, and only if, any of the conditions in paragraph B116 cease to be met an entity shall cease to apply paragraph B115 from that date. An entity shall not make any adjustment for changes previously recognised in profit or loss.
Recognition of the contractual service margin in profit or loss
B119An amount of the contractual service margin for a group of insurance contracts is recognised in profit or loss in each period to reflect the insurance contract services provided under the group of insurance contracts in that period (see paragraphs 44(e), 45(e) and 66(e)). The amount is determined by:
- identifying the coverage units in the group. The number of coverage units in a group is the quantity of insurance contract services provided by the contracts in the group, determined by considering for each contract the quantity of the benefits provided under a contract and its expected coverage period.
- allocating the contractual service margin at the end of the period (before recognising any amounts in profit or loss to reflect the insurance contract services provided in the period) equally to each coverage unit provided in the current period and expected to be provided in the future.
- recognising in profit or loss the amount allocated to coverage units provided in the period.
B119ATo apply paragraph B119, the period of investment-return service or investment-related service ends at or before the date that all amounts due to current policyholders relating to those services have been paid, without considering payments to future policyholders included in the fulfilment cash flows applying paragraph B68.
B119BInsurance contracts without direct participation features may provide an investment-return service if, and only if:
- an investment component exists, or the policyholder has a right to withdraw an amount;
- the entity expects the investment component or amount the policyholder has a right to withdraw to include an investment return (an investment return could be below zero, for example, in a negative interest rate environment); and
- the entity expects to perform investment activity to generate that investment return.
Reinsurance contracts held—recognition of recovery of losses on underlying insurance contracts (paragraphs 66A–66B)
B119CParagraph 66A applies if, and only if, the reinsurance contract held is entered into before or at the same time as the onerous underlying insurance contracts are recognised.
B119DTo apply paragraph 66A, an entity shall determine the adjustment to the contractual service margin of a group of reinsurance contracts held and the resulting income by multiplying:
- the loss recognised on the underlying insurance contracts; and
- the percentage of claims on the underlying insurance contracts the entity expects to recover from the group of reinsurance contracts held.
B119EApplying paragraphs 14–22, an entity might include in an onerous group of insurance contracts both onerous insurance contracts covered by a group of reinsurance contracts held and onerous insurance contracts not covered by the group of reinsurance contracts held. To apply paragraphs 66(c)(i)–(ii) and paragraph 66A in such cases, the entity shall apply a systematic and rational method of allocation to determine the portion of losses recognised on the group of insurance contracts that relates to insurance contracts covered by the group of reinsurance contracts held.
B119FAfter an entity has established a loss-recovery component applying paragraph 66B, the entity shall adjust the loss-recovery component to reflect changes in the loss component of an onerous group of underlying insurance contracts (see paragraphs 50–52). The carrying amount of the loss-recovery component shall not exceed the portion of the carrying amount of the loss component of the onerous group of underlying insurance contracts that the entity expects to recover from the group of reinsurance contracts held.
Insurance revenue (paragraphs 83 and 85)
B120The total insurance revenue for a group of insurance contracts is the consideration for the contracts, ie the amount of premiums paid to the entity:
- adjusted for a financing effect; and
- excluding any investment components.
B121Paragraph 83 requires the amount of insurance revenue recognised in a period to depict the transfer of promised services at an amount that reflects the consideration to which the entity expects to be entitled in exchange for those services. The total consideration for a group of contracts covers the following amounts:
- amounts related to the provision of services, comprising:
- insurance service expenses, excluding any amounts relating to the risk adjustment for non-financial risk included in (ii) and any amounts allocated to the loss component of the liability for remaining coverage;
- amounts related to income tax that are specifically chargeable to the policyholder;
- the risk adjustment for non-financial risk, excluding any amounts allocated to the loss component of the liability for remaining coverage; and
- the contractual service margin.
- amounts related to insurance acquisition cash flows.
B122Insurance revenue for a period relating to the amounts described in paragraph B121(a) is determined as set out in paragraphs B123–B124. Insurance revenue for a period relating to the amounts described in paragraph B121(b) is determined as set out in paragraph B125.
B123Applying IFRS 15, when an entity provides services, it derecognises the performance obligation for those services and recognises revenue. Consistently, applying IFRS 17, when an entity provides services in a period, it reduces the liability for remaining coverage for the services provided and recognises insurance revenue. The reduction in the liability for remaining coverage that gives rise to insurance revenue excludes changes in the liability that do not relate to services expected to be covered by the consideration received by the entity. Those changes are:
- changes that do not relate to services provided in the period, for example:
- changes resulting from cash inflows from premiums received;
- changes that relate to investment components in the period;
- changes resulting from cash flows from loans to policyholders;
- changes that relate to transaction-based taxes collected on behalf of third parties (such as premium taxes, value added taxes and goods and services taxes) (see paragraph B65(i));
- insurance finance income or expenses;
- insurance acquisition cash flows (see paragraph B125); and
- derecognition of liabilities transferred to a third party.
- changes that relate to services, but for which the entity does not expect consideration, ie increases and decreases in the loss component of the liability for remaining coverage (see paragraphs 47–52).
B123ATo the extent that an entity derecognises an asset for cash flows other than insurance acquisition cash flows at the date of initial recognition of a group of insurance contracts (see paragraphs 38(c)(ii) and B66A), it shall recognise insurance revenue and expenses for the amount derecognised at that date.
B124Consequently, insurance revenue for the period can also be analysed as the total of the changes in the liability for remaining coverage in the period that relates to services for which the entity expects to receive consideration. Those changes are:
- insurance service expenses incurred in the period (measured at the amounts expected at the beginning of the period), excluding:
- amounts allocated to the loss component of the liability for remaining coverage applying paragraph 51(a);
- repayments of investment components;
- amounts that relate to transaction-based taxes collected on behalf of third parties (such as premium taxes, value added taxes and goods and services taxes) (see paragraph B65(i));
- insurance acquisition expenses (see paragraph B125); and
- the amount related to the risk adjustment for non-financial risk (see (b)).
- the change in the risk adjustment for non-financial risk, excluding:
- changes included in insurance finance income or expenses applying paragraph 87;
- changes that adjust the contractual service margin because they relate to future service applying paragraphs 44(c) and 45(c); and
- amounts allocated to the loss component of the liability for remaining coverage applying paragraph 51(b).
- the amount of the contractual service margin recognised in profit or loss in the period, applying paragraphs 44(e) and 45(e).
- other amounts, if any, for example, experience adjustments for premium receipts other than those that relate to future service (see paragraph B96(a)).
B125An entity shall determine insurance revenue related to insurance acquisition cash flows by allocating the portion of the premiums that relate to recovering those cash flows to each reporting period in a systematic way on the basis of the passage of time. An entity shall recognise the same amount as insurance service expenses.
B126When an entity applies the premium allocation approach in paragraphs 55–58, insurance revenue for the period is the amount of expected premium receipts (excluding any investment component and adjusted to reflect the time value of money and the effect of financial risk, if applicable, applying paragraph 56) allocated to the period. The entity shall allocate the expected premium receipts to each period of insurance contract services:
- on the basis of the passage of time; but
- if the expected pattern of release of risk during the coverage period differs significantly from the passage of time, then on the basis of the expected timing of incurred insurance service expenses.
B127An entity shall change the basis of allocation between paragraphs B126(a) and B126(b) as necessary if facts and circumstances change.
Insurance finance income or expenses (paragraphs 87–92)
B128Paragraph 87 requires an entity to include in insurance finance income or expenses the effect of the time value of money and financial risk and changes therein. For the purposes of IFRS 17:
- assumptions about inflation based on an index of prices or rates or on prices of assets with inflation-linked returns are assumptions that relate to financial risk;
- assumptions about inflation based on an entity’s expectation of specific price changes are not assumptions that relate to financial risk; and
- changes in the measurement of a group of insurance contracts caused by changes in the value of underlying items (excluding additions and withdrawals) are changes arising from the effect of the time value of money and financial risk and changes therein.
B129Paragraphs 88–89 require an entity to make an accounting policy choice as to whether to disaggregate insurance finance income or expenses for the period between profit or loss and other comprehensive income. An entity shall apply its choice of accounting policy to portfolios of insurance contracts. In assessing the appropriate accounting policy for a portfolio of insurance contracts, applying paragraph 13 of IAS 8 Accounting Policies, Changes in Accounting Estimates and Errors, the entity shall consider for each portfolio the assets that the entity holds and how it accounts for those assets.
B130If paragraph 88(b) applies, an entity shall include in profit or loss an amount determined by a systematic allocation of the expected total finance income or expenses over the duration of the group of insurance contracts. In this context, a systematic allocation is an allocation of the total expected finance income or expenses of a group of insurance contracts over the duration of the group that:
- is based on characteristics of the contracts, without reference to factors that do not affect the cash flows expected to arise under the contracts. For example, the allocation of the finance income or expenses shall not be based on expected recognised returns on assets if those expected recognised returns do not affect the cash flows of the contracts in the group.
- results in the amounts recognised in other comprehensive income over the duration of the group of contracts totalling zero. The cumulative amount recognised in other comprehensive income at any date is the difference between the carrying amount of the group of contracts and the amount that the group would be measured at when applying the systematic allocation.
B131For groups of insurance contracts for which changes in assumptions that relate to financial risk do not have a substantial effect on the amounts paid to the policyholder, the systematic allocation is determined using the discount rates specified in paragraph B72(e)(i).
B132For groups of insurance contracts for which changes in assumptions that relate to financial risk have a substantial effect on the amounts paid to the policyholders:
- a systematic allocation for the finance income or expenses arising from the estimates of future cash flows can be determined in one of the following ways:
- using a rate that allocates the remaining revised expected finance income or expenses over the remaining duration of the group of contracts at a constant rate; or
- for contracts that use a crediting rate to determine amounts due to the policyholders—using an allocation that is based on the amounts credited in the period and expected to be credited in future periods.
- a systematic allocation for the finance income or expenses arising from the risk adjustment for non-financial risk, if separately disaggregated from other changes in the risk adjustment for non-financial risk applying paragraph 81, is determined using an allocation consistent with that used for the allocation for the finance income or expenses arising from the future cash flows.
- a systematic allocation for the finance income or expenses arising from the contractual service margin is determined:
- for insurance contracts that do not have direct participation features, using the discount rates specified in paragraph B72(b); and
- for insurance contracts with direct participation features, using an allocation consistent with that used for the allocation for the finance income or expenses arising from the future cash flows.
B133In applying the premium allocation approach to insurance contracts described in paragraphs 53–59, an entity may be required, or may choose, to discount the liability for incurred claims. In such cases, it may choose to disaggregate the insurance finance income or expenses applying paragraph 88(b). If the entity makes this choice, it shall determine the insurance finance income or expenses in profit or loss using the discount rate specified in paragraph B72(e)(iii).
B134Paragraph 89 applies if an entity, either by choice or because it is required to, holds the underlying items for insurance contracts with direct participation features. If an entity chooses to disaggregate insurance finance income or expenses applying paragraph 89(b), it shall include in profit or loss expenses or income that exactly match the income or expenses included in profit or loss for the underlying items, resulting in the net of the separately presented items being nil.
B135An entity may qualify for the accounting policy choice in paragraph 89 in some periods but not in others because of a change in whether it holds the underlying items. If such a change occurs, the accounting policy choice available to the entity changes from that set out in paragraph 88 to that set out in paragraph 89, or vice versa. Hence, an entity might change its accounting policy between that set out in paragraph 88(b) and that set out in paragraph 89(b). In making such a change an entity shall:
- include the accumulated amount previously included in other comprehensive income by the date of the change as a reclassification adjustment in profit or loss in the period of change and in future periods, as follows:
- if the entity had previously applied paragraph 88(b)—the entity shall include in profit or loss the accumulated amount included in other comprehensive income before the change as if the entity were continuing the approach in paragraph 88(b) based on the assumptions that applied immediately before the change; and
- if the entity had previously applied paragraph 89(b)—the entity shall include in profit or loss the accumulated amount included in other comprehensive income before the change as if the entity were continuing the approach in paragraph 89(b) based on the assumptions that applied immediately before the change.
- not restate prior period comparative information.
B136When applying paragraph B135(a), an entity shall not recalculate the accumulated amount previously included in other comprehensive income as if the new disaggregation had always applied; and the assumptions used for the reclassification in future periods shall not be updated after the date of the change.
The effect of accounting estimates made in interim financial statements
B137If an entity prepares interim financial statements applying IAS 34 Interim Financial Reporting, the entity shall make an accounting policy choice as to whether to change the treatment of accounting estimates made in previous interim financial statements when applying IFRS 17 in subsequent interim financial statements and in the annual reporting period. The entity shall apply its choice of accounting policy to all groups of insurance contracts it issues and groups of reinsurance contracts it holds.
Appendix C
Effective date and transition
This appendix is an integral part of IFRS 17 Insurance Contracts.
Effective date
C1An entity shall apply IFRS 17 for annual reporting periods beginning on or after 1 January 2023. If an entity applies IFRS 17 earlier, it shall disclose that fact. Early application is permitted for entities that apply IFRS 9 Financial Instruments on or before the date of initial application of IFRS 17.
C2For the purposes of the transition requirements in paragraphs C1 and C3–C33:
- the date of initial application is the beginning of the annual reporting period in which an entity first applies IFRS 17; and
- the transition date is the beginning of the annual reporting period immediately preceding the date of initial application.
C2AInitial Application of IFRS 17 and IFRS 9—Comparative Information, issued in December 2021, added paragraphs C28A–C28E and C33A. An entity that chooses to apply paragraphs C28A–C28E and C33A shall apply them on initial application of IFRS 17.
Transition
C3Unless it is impracticable to do so, or paragraph C5A applies, an entity shall apply IFRS 17 retrospectively, except that:
- an entity is not required to present the quantitative information required by paragraph 28(f) of IAS 8 Accounting Policies, Changes in Accounting Estimates and Errors, and
- an entity shall not apply the option in paragraph B115 for periods before the transition date. An entity may apply the option in paragraph B115 prospectively on or after the transition date if, and only if, the entity designates risk mitigation relationships at or before the date it applies the option.
C4To apply IFRS 17 retrospectively, an entity shall at the transition date:
- identify, recognise and measure each group of insurance contracts as if IFRS 17 had always applied;
- identify, recognise and measure any assets for insurance acquisition cash flows as if IFRS 17 had always applied (except that an entity is not required to apply the recoverability assessment in paragraph 28E before the transition date);
- derecognise any existing balances that would not exist had IFRS 17 always applied; and
C5If, and only if, it is impracticable for an entity to apply paragraph C3 for a group of insurance contracts, an entity shall apply the following approaches instead of applying paragraph C4(a):
- the modified retrospective approach in paragraphs C6–C19A, subject to paragraph C6(a); or
- the fair value approach in paragraphs C20–C24B.
C5ANotwithstanding paragraph C5, an entity may choose to apply the fair value approach in paragraphs C20–C24B for a group of insurance contracts with direct participation features to which it could apply IFRS 17 retrospectively if, and only if:
- the entity chooses to apply the risk mitigation option in paragraph B115 to the group of insurance contracts prospectively from the transition date; and
- the entity has used derivatives, non-derivative financial instruments measured at fair value through profit or loss, or reinsurance contracts held to mitigate financial risk arising from the group of insurance contracts, as specified in paragraph B115, before the transition date.
C5BIf, and only if, it is impracticable for an entity to apply paragraph C4(aa) for an asset for insurance acquisition cash flows, the entity shall apply the following approaches to measure the asset for insurance acquisition cash flows:
- the modified retrospective approach in paragraphs C14B–C14D and C17A, subject to paragraph C6(a); or
- the fair value approach in paragraphs C24A–C24B.
Modified retrospective approach
C6The objective of the modified retrospective approach is to achieve the closest outcome to retrospective application possible using reasonable and supportable information available without undue cost or effort. Accordingly, in applying this approach, an entity shall:
- use reasonable and supportable information. If the entity cannot obtain reasonable and supportable information necessary to apply the modified retrospective approach, it shall apply the fair value approach.
- maximise the use of information that would have been used to apply a fully retrospective approach, but need only use information available without undue cost or effort.
C7Paragraphs C9–C19A set out permitted modifications to retrospective application in the following areas:
- assessments of insurance contracts or groups of insurance contracts that would have been made at the date of inception or initial recognition;
- amounts related to the contractual service margin or loss component for insurance contracts without direct participation features;
- amounts related to the contractual service margin or loss component for insurance contracts with direct participation features; and
- insurance finance income or expenses.
C8To achieve the objective of the modified retrospective approach, an entity is permitted to use each modification in paragraphs C9–C19A only to the extent that an entity does not have reasonable and supportable information to apply a retrospective approach.
Assessments at inception or initial recognition
C9To the extent permitted by paragraph C8, an entity shall determine the following matters using information available at the transition date:
- how to identify groups of insurance contracts, applying paragraphs 14–24;
- whether an insurance contract meets the definition of an insurance contract with direct participation features, applying paragraphs B101–B109;
- how to identify discretionary cash flows for insurance contracts without direct participation features, applying paragraphs B98–B100; and
- whether an investment contract meets the definition of an investment contract with discretionary participation features within the scope of IFRS 17, applying paragraph 71.
C9ATo the extent permitted by paragraph C8, an entity shall classify as a liability for incurred claims a liability for settlement of claims incurred before an insurance contract was acquired in a transfer of insurance contracts that do not form a business or in a business combination within the scope of IFRS 3.
C10To the extent permitted by paragraph C8, an entity shall not apply paragraph 22 to divide groups into those that do not include contracts issued more than one year apart.
Determining the contractual service margin or loss component for groups of insurance contracts without direct participation features
C11To the extent permitted by paragraph C8, for contracts without direct participation features, an entity shall determine the contractual service margin or loss component of the liability for remaining coverage (see paragraphs 49–52) at the transition date by applying paragraphs C12–C16C.
C12To the extent permitted by paragraph C8, an entity shall estimate the future cash flows at the date of initial recognition of a group of insurance contracts as the amount of the future cash flows at the transition date (or earlier date, if the future cash flows at that earlier date can be determined retrospectively, applying paragraph C4(a)), adjusted by the cash flows that are known to have occurred between the date of initial recognition of a group of insurance contracts and the transition date (or earlier date). The cash flows that are known to have occurred include cash flows resulting from contracts that ceased to exist before the transition date.
C13To the extent permitted by paragraph C8, an entity shall determine the discount rates that applied at the date of initial recognition of a group of insurance contracts (or subsequently):
- using an observable yield curve that, for at least three years immediately before the transition date, approximates the yield curve estimated applying paragraphs 36 and B72–B85, if such an observable yield curve exists.
- if the observable yield curve in paragraph (a) does not exist, estimate the discount rates that applied at the date of initial recognition (or subsequently) by determining an average spread between an observable yield curve and the yield curve estimated applying paragraphs 36 and B72–B85, and applying that spread to that observable yield curve. That spread shall be an average over at least three years immediately before the transition date.
C14To the extent permitted by paragraph C8, an entity shall determine the risk adjustment for non-financial risk at the date of initial recognition of a group of insurance contracts (or subsequently) by adjusting the risk adjustment for non-financial risk at the transition date by the expected release of risk before the transition date. The expected release of risk shall be determined by reference to the release of risk for similar insurance contracts that the entity issues at the transition date.
C14AApplying paragraph B137, an entity may choose not to change the treatment of accounting estimates made in previous interim financial statements. To the extent permitted by paragraph C8, such an entity shall determine the contractual service margin or loss component at the transition date as if the entity had not prepared interim financial statements before the transition date.
C14BTo the extent permitted by paragraph C8, an entity shall use the same systematic and rational method the entity expects to use after the transition date when applying paragraph 28A to allocate any insurance acquisition cash flows paid (or for which a liability has been recognised applying another IFRS Standard) before the transition date (excluding any amount relating to insurance contracts that ceased to exist before the transition date) to:
- groups of insurance contracts that are recognised at the transition date; and
- groups of insurance contracts that are expected to be recognised after the transition date.
C14CInsurance acquisition cash flows paid before the transition date that are allocated to a group of insurance contracts recognised at the transition date adjust the contractual service margin of that group, to the extent insurance contracts expected to be in the group have been recognised at that date (see paragraphs 28C and B35C). Other insurance acquisition cash flows paid before the transition date, including those allocated to a group of insurance contracts expected to be recognised after the transition date, are recognised as an asset, applying paragraph 28B.
C14DIf an entity does not have reasonable and supportable information to apply paragraph C14B, the entity shall determine the following amounts to be nil at the transition date:
- the adjustment to the contractual service margin of a group of insurance contracts recognised at the transition date and any asset for insurance acquisition cash flows relating to that group; and
- the asset for insurance acquisition cash flows for groups of insurance contracts expected to be recognised after the transition date.
C15If applying paragraphs C12–C14D results in a contractual service margin at the date of initial recognition, to determine the contractual service margin at the date of transition an entity shall:
- if the entity applies C13 to estimate the discount rates that apply on initial recognition, use those rates to accrete interest on the contractual service margin; and
- to the extent permitted by paragraph C8, determine the amount of the contractual service margin recognised in profit or loss because of the transfer of services before the transition date, by comparing the remaining coverage units at that date with the coverage units provided under the group of contracts before the transition date (see paragraph B119).
C16If applying paragraphs C12–C14D results in a loss component of the liability for remaining coverage at the date of initial recognition, an entity shall determine any amounts allocated to the loss component before the transition date applying paragraphs C12–C14D and using a systematic basis of allocation.
C16AFor a group of reinsurance contracts held that provides coverage for an onerous group of insurance contracts and was entered into before or at the same time that the insurance contracts were issued, an entity shall establish a loss-recovery component of the asset for remaining coverage at the transition date (see paragraphs 66A–66B). To the extent permitted by paragraph C8, an entity shall determine the loss-recovery component by multiplying:
- the loss component of the liability for remaining coverage for the underlying insurance contracts at the transition date (see paragraphs C16 and C20); and
- the percentage of claims for the underlying insurance contracts the entity expects to recover from the group of reinsurance contracts held.
C16BApplying paragraphs 14–22, at the transition date an entity might include in an onerous group of insurance contracts both onerous insurance contracts covered by a group of reinsurance contracts held and onerous insurance contracts not covered by the group of reinsurance contracts held. To apply paragraph C16A in such cases, an entity shall use a systematic and rational basis of allocation to determine the portion of the loss component of the group of insurance contracts that relates to insurance contracts covered by the group of reinsurance contracts held.
C16CIf an entity does not have reasonable and supportable information to apply paragraph C16A, the entity shall not identify a loss-recovery component for the group of reinsurance contracts held.
Determining the contractual service margin or loss component for groups of insurance contracts with direct participation features
C17To the extent permitted by paragraph C8, for contracts with direct participation features an entity shall determine the contractual service margin or loss component of the liability for remaining coverage at the transition date as:
- the total fair value of the underlying items at that date; minus
- the fulfilment cash flows at that date; plus or minus
- an adjustment for:
- amounts charged by the entity to the policyholders (including amounts deducted from the underlying items) before that date.
- amounts paid before that date that would not have varied based on the underlying items.
- the change in the risk adjustment for non-financial risk caused by the release from risk before that date. The entity shall estimate this amount by reference to the release of risk for similar insurance contracts that the entity issues at the transition date.
- insurance acquisition cash flows paid (or for which a liability has been recognised applying another IFRS Standard) before the transition date that are allocated to the group (see paragraph C17A).
- if (a)–(c) result in a contractual service margin—minus the amount of the contractual service margin that relates to services provided before that date. The total of (a)–(c) is a proxy for the total contractual service margin for all services to be provided under the group of contracts, ie before any amounts that would have been recognised in profit or loss for services provided. The entity shall estimate the amounts that would have been recognised in profit or loss for services provided by comparing the remaining coverage units at the transition date with the coverage units provided under the group of contracts before the transition date; or
- if (a)–(c) result in a loss component—adjust the loss component to nil and increase the liability for remaining coverage excluding the loss component by the same amount.
Insurance finance income or expenses
C18For groups of insurance contracts that, applying paragraph C10, include contracts issued more than one year apart:
- an entity is permitted to determine the discount rates at the date of initial recognition of a group specified in paragraphs B72(b)–B72(e)(ii) and the discount rates at the date of the incurred claim specified in paragraph B72(e)(iii) at the transition date instead of at the date of initial recognition or incurred claim.
- if an entity chooses to disaggregate insurance finance income or expenses between amounts included in profit or loss and amounts included in other comprehensive income applying paragraphs 88(b) or 89(b), the entity needs to determine the cumulative amount of insurance finance income or expenses recognised in other comprehensive income at the transition date to apply paragraph 91(a) in future periods. The entity is permitted to determine that cumulative amount either by applying paragraph C19(b) or:
- as nil, unless (ii) applies; and
- for insurance contracts with direct participation features to which paragraph B134 applies, as equal to the cumulative amount recognised in other comprehensive income on the underlying items.
- if an entity applies paragraph C13 to estimate the discount rates that applied at initial recognition (or subsequently), it shall also determine the discount rates specified in paragraphs B72(b)–B72(e) applying paragraph C13; and
- if an entity chooses to disaggregate insurance finance income or expenses between amounts included in profit or loss and amounts included in other comprehensive income, applying paragraphs 88(b) or 89(b), the entity needs to determine the cumulative amount of insurance finance income or expenses recognised in other comprehensive income at the transition date to apply paragraph 91(a) in future periods. The entity shall determine that cumulative amount:
- for insurance contracts for which an entity will apply the methods of systematic allocation set out in paragraph B131—if the entity applies paragraph C13 to estimate the discount rates at initial recognition—using the discount rates that applied at the date of initial recognition, also applying paragraph C13;
- for insurance contracts for which an entity will apply the methods of systematic allocation set out in paragraph B132—on the basis that the assumptions that relate to financial risk that applied at the date of initial recognition are those that apply on the transition date, ie as nil;
Fair value approach
C20To apply the fair value approach, an entity shall determine the contractual service margin or loss component of the liability for remaining coverage at the transition date as the difference between the fair value of a group of insurance contracts at that date and the fulfilment cash flows measured at that date. In determining that fair value, an entity shall not apply paragraph 47 of IFRS 13 Fair Value Measurement (relating to demand features).
C20AFor a group of reinsurance contracts held to which paragraphs 66A–66B apply (without the need to meet the condition set out in paragraph B119C), an entity shall determine the loss-recovery component of the asset for remaining coverage at the transition date by multiplying:
- the loss component of the liability for remaining coverage for the underlying insurance contracts at the transition date (see paragraphs C16 and C20); and
- the percentage of claims for the underlying insurance contracts the entity expects to recover from the group of reinsurance contracts held.
C20BApplying paragraphs 14–22, at the transition date an entity might include in an onerous group of insurance contracts both onerous insurance contracts covered by a group of reinsurance contracts held and onerous insurance contracts not covered by the group of reinsurance contracts held. To apply paragraph C20A in such cases, an entity shall use a systematic and rational basis of allocation to determine the portion of the loss component of the group of insurance contracts that relates to insurance contracts covered by the group of reinsurance contracts held.
C21In applying the fair value approach, an entity may apply paragraph C22 to determine:
- how to identify groups of insurance contracts, applying paragraphs 14–24;
- whether an insurance contract meets the definition of an insurance contract with direct participation features, applying paragraphs B101–B109;
- how to identify discretionary cash flows for insurance contracts without direct participation features, applying paragraphs B98–B100; and
- whether an investment contract meets the definition of an investment contract with discretionary participation features within the scope of IFRS 17, applying paragraph 71.
C22An entity may choose to determine the matters in paragraph C21 using:
- reasonable and supportable information for what the entity would have determined given the terms of the contract and the market conditions at the date of inception or initial recognition, as appropriate; or
- reasonable and supportable information available at the transition date.
C22AIn applying the fair value approach, an entity may choose to classify as a liability for incurred claims a liability for settlement of claims incurred before an insurance contract was acquired in a transfer of insurance contracts that do not form a business or in a business combination within the scope of IFRS 3.
C23In applying the fair value approach, an entity is not required to apply paragraph 22, and may include in a group contracts issued more than one year apart. An entity shall only divide groups into those including only contracts issued within a year (or less) if it has reasonable and supportable information to make the division. Whether or not an entity applies paragraph 22, it is permitted to determine the discount rates at the date of initial recognition of a group specified in paragraphs B72(b)–B72(e)(ii) and the discount rates at the date of the incurred claim specified in paragraph B72(e)(iii) at the transition date instead of at the date of initial recognition or incurred claim.
C24In applying the fair value approach, if an entity chooses to disaggregate insurance finance income or expenses between profit or loss and other comprehensive income, it is permitted to determine the cumulative amount of insurance finance income or expenses recognised in other comprehensive income at the transition date:
- retrospectively—but only if it has reasonable and supportable information to do so; or
- as nil—unless (c) applies; and
- for insurance contracts with direct participation features to which paragraph B134 applies—as equal to the cumulative amount recognised in other comprehensive income from the underlying items.
Asset for insurance acquisition cash flows
C24AIn applying the fair value approach for an asset for insurance acquisition cash flows (see paragraph C5B(b)), at the transition date, an entity shall determine an asset for insurance acquisition cash flows at an amount equal to the insurance acquisition cash flows the entity would incur at the transition date for the rights to obtain:
- recoveries of insurance acquisition cash flows from premiums of insurance contracts issued before the transition date but not recognised at the transition date;
- future insurance contracts that are renewals of insurance contracts recognised at the transition date and insurance contracts described in (a); and
- future insurance contracts, other than those in (b), after the transition date without paying again insurance acquisition cash flows the entity has already paid that are directly attributable to the related portfolio of insurance contracts.
C24BAt the transition date, the entity shall exclude from the measurement of any groups of insurance contracts the amount of any asset for insurance acquisition cash flows.
Comparative information
C25Notwithstanding the reference to the annual reporting period immediately preceding the date of initial application in paragraph C2(b), an entity may also present adjusted comparative information applying IFRS 17 for any earlier periods presented, but is not required to do so. If an entity does present adjusted comparative information for any earlier periods, the reference to ‘the beginning of the annual reporting period immediately preceding the date of initial application’ in paragraph C2(b) shall be read as ‘the beginning of the earliest adjusted comparative period presented’.
C26An entity is not required to provide the disclosures specified in paragraphs 93–132 for any period presented before the beginning of the annual reporting period immediately preceding the date of initial application.
C27If an entity presents unadjusted comparative information and disclosures for any earlier periods, it shall clearly identify the information that has not been adjusted, disclose that it has been prepared on a different basis, and explain that basis.
C28An entity need not disclose previously unpublished information about claims development that occurred earlier than five years before the end of the annual reporting period in which it first applies IFRS 17. However, if an entity does not disclose that information, it shall disclose that fact.
Entities that first apply IFRS 17 and IFRS 9 at the same time
C28AAn entity that first applies IFRS 17 and IFRS 9 at the same time is permitted to apply paragraphs C28B–C28E (classification overlay) for the purpose of presenting comparative information about a financial asset if the comparative information for that financial asset has not been restated for IFRS 9. Comparative information for a financial asset will not be restated for IFRS 9 if either the entity chooses not to restate prior periods (see paragraph 7.2.15 of IFRS 9), or the entity restates prior periods but the financial asset has been derecognised during those prior periods (see paragraph 7.2.1 of IFRS 9).
C28BAn entity applying the classification overlay to a financial asset shall present comparative information as if the classification and measurement requirements of IFRS 9 had been applied to that financial asset. The entity shall use reasonable and supportable information available at the transition date (see paragraph C2(b)) to determine how the entity expects the financial asset would be classified and measured on initial application of IFRS 9 (for example, an entity might use preliminary assessments performed to prepare for the initial application of IFRS 9).
C28CIn applying the classification overlay to a financial asset, an entity is not required to apply the impairment requirements in Section 5.5 of IFRS 9. If, based on the classification determined applying paragraph C28B, the financial asset would be subject to the impairment requirements in Section 5.5 of IFRS 9 but the entity does not apply those requirements in applying the classification overlay, the entity shall continue to present any amount recognised in respect of impairment in the prior period in accordance with IAS 39 Financial Instruments: Recognition and Measurement. Otherwise, any such amounts shall be reversed.
C28DAny difference between the previous carrying amount of a financial asset and the carrying amount at the transition date that results from applying paragraphs C28B–C28C shall be recognised in opening retained earnings (or other component of equity, as appropriate) at the transition date.
C28EAn entity that applies paragraphs C28B–C28D shall:
- disclose qualitative information that enables users of financial statements to understand:
- the extent to which the classification overlay has been applied (for example, whether it has been applied to all financial assets derecognised in the comparative period);
- whether and to what extent the impairment requirements in Section 5.5 of IFRS 9 have been applied (see paragraph C28C);
- only apply those paragraphs to comparative information for reporting periods between the transition date to IFRS 17 and the date of initial application of IFRS 17 (see paragraphs C2 and C25); and
- at the date of initial application of IFRS 9, apply the transition requirements in IFRS 9 (see Section 7.2 of IFRS 9).
Redesignation of financial assets
C29At the date of initial application of IFRS 17, an entity that had applied IFRS 9 to annual reporting periods before the initial application of IFRS 17:
- may reassess whether an eligible financial asset meets the condition in paragraph 4.1.2(a) or paragraph 4.1.2A(a) of IFRS 9. A financial asset is eligible only if the financial asset is not held in respect of an activity that is unconnected with contracts within the scope of IFRS 17. Examples of financial assets that would not be eligible for reassessment are financial assets held in respect of banking activities or financial assets held in funds relating to investment contracts that are outside the scope of IFRS 17.
- shall revoke its previous designation of a financial asset as measured at fair value through profit or loss if the condition in paragraph 4.1.5 of IFRS 9 is no longer met because of the application of IFRS 17.
- may designate a financial asset as measured at fair value through profit or loss if the condition in paragraph 4.1.5 of IFRS 9 is met.
- may designate an investment in an equity instrument as at fair value through other comprehensive income applying paragraph 5.7.5 of IFRS 9.
- may revoke its previous designation of an investment in an equity instrument as at fair value through other comprehensive income applying paragraph 5.7.5 of IFRS 9.
C30An entity shall apply paragraph C29 on the basis of the facts and circumstances that exist at the date of initial application of IFRS 17. An entity shall apply those designations and classifications retrospectively. In doing so, the entity shall apply the relevant transition requirements in IFRS 9. The date of initial application for that purpose shall be deemed to be the date of initial application of IFRS 17.
C31An entity that applies paragraph C29 is not required to restate prior periods to reflect such changes in designations or classifications. The entity may restate prior periods only if it is possible without the use of hindsight. If an entity restates prior periods, the restated financial statements must reflect all the requirements of IFRS 9 for those affected financial assets. If an entity does not restate prior periods, the entity shall recognise, in the opening retained earnings (or other component of equity, as appropriate) at the date of initial application, any difference between:
- the previous carrying amount of those financial assets; and
- the carrying amount of those financial assets at the date of initial application.
C32When an entity applies paragraph C29, it shall disclose in that annual reporting period for those financial assets by class:
- if paragraph C29(a) applies—its basis for determining eligible financial assets;
- if any of paragraphs C29(a)–C29(e) apply:
- the measurement category and carrying amount of the affected financial assets determined immediately before the date of initial application of IFRS 17; and
- the new measurement category and carrying amount of the affected financial assets determined after applying paragraph C29.
- if paragraph C29(b) applies—the carrying amount of financial assets in the statement of financial position that were previously designated as measured at fair value through profit or loss applying paragraph 4.1.5 of IFRS 9 that are no longer so designated.
- how it applied paragraph C29 to financial assets the classification of which has changed on initially applying IFRS 17;
- the reasons for any designation or de-designation of financial assets as measured at fair value through profit or loss applying paragraph 4.1.5 of IFRS 9; and
- why the entity came to any different conclusions in the new assessment applying paragraphs 4.1.2(a) or 4.1.2A(a) of IFRS 9.
C33AFor a financial asset derecognised between the transition date and date of initial application of IFRS 17, an entity may apply paragraphs C28B–C28E (classification overlay) for the purpose of presenting comparative information as if paragraph C29 had been applied to that asset. Such an entity shall adapt the requirements of paragraphs C28B–C28E so that the classification overlay is based on how the entity expects the financial asset would be designated applying paragraph C29 at the date of initial application of IFRS 17.
Withdrawal of other IFRS Standards
C34IFRS 17 supersedes IFRS 4 Insurance Contracts, as amended in 2020.
Footnotes
-
The EU completed the endorsement and adoption of IFRS 17 in November 2021. ↩
-
Section 5 requires a minimum quorum attendance of sixty percent of the appointed members (including the UKEB Chair as an appointed member) (ToR, paragraph 5.1) and an affirmative written vote of at least two-thirds of all of the appointed Board members (ToR, paragraph 5.2). ↩
-
SI 2019/685 regulation 5(a) – see footnote 3. ↩
-
IFRS 17 was issued in May 2017 and amended in June 2020 and December 2021. ↩
-
The UK's statutory requirements for adoption of international accounting standards are set out in The International Accounting Standards and European Public Limited-Liability Company (Amendment etc.) (EU Exit) Regulations 2019 no. 685 (the Regulations, or SI 2019/685). Link. ↩
-
In particular, the disclosure requirements of IAS 1 paragraph 17 (c) which requires "additional disclosures when compliance with the specific requirements in IFRSs is insufficient to enable users to understand the impact of particular transactions, other events and conditions on the entity's financial position and financial performance." ↩
-
In December 2021 the IASB issued Initial Application of IFRS 17 and IFRS 9 - Comparative Information (Amendment to IFRS 17). The Amendment is not expected to be widely used in the UK and feedback indicated that stakeholders agreed with the assessment that the Amendment was not likely to give rise to any issues that are significant for the purposes of the IFRS 17 adoption decision. The UKEB comment letter to the IASB can be found here. See Section 3 from paragraph 3.8 for an explanation of the identification of 'significant' issues. ↩
-
Sometimes also referred to as 'endorsement criteria'. While the relevant legislation uses only the term 'adoption' and does not refer to 'endorsement', for the purposes of this ECA the term 'endorsement' is generally used when referring to the assessment of IFRS 17 against the statutory adoption criteria, reflecting general usage. This is not intended to imply the existence of two distinct statutory functions or processes. ↩
-
Refer to Section 5, True and fair view assessment. ↩
-
In December 2021 the IASB issued Initial Application of IFRS 17 and IFRS 9 – Comparative Information (Amendment to IFRS 17). See also paragraph 1.1 and the related footnote above. ↩
-
The 2007 Discussion Paper (receiving 162 comment letters), the 2010 Exposure Draft (receiving 251 comment letters), the 2013 Exposure Draft (receiving 194 comment letters) and the 2019 Exposure Draft Amendments to IFRS 17 (receiving 123 comment letters). ↩
-
Including users and preparers of financial statements, actuaries, auditors, regulators and others. ↩
-
IFRS 17: B18-B23 provide application guidance on the assessment of whether the insurance risk is significant. ↩
-
IFRS Standards Effects Analysis - IFRS 17 Insurance Contracts (May 2017). See link: IFRS 17 Effects Analysis ↩
-
IFRS 17 defines 'investment contract with discretionary participation features' as a financial instrument that provides a particular investor with the contractual right to receive, as a supplement to an amount not subject to the discretion of the issuer, additional amounts: ↩
-
For a detailed assessment of the level of aggregation requirements refer to Section 3 priority issue C: Grouping insurance contracts: profitability buckets and annual cohorts. ↩
-
There are three measurement models in IFRS 17. These are discussed in more detail in paragraphs 2.42 – 2.77 below: 'Overview of accounting models'. ↩
-
IFRS 17 defines 'investment component' as the amounts that an insurance contract requires the entity to repay to a policyholder in all circumstances, regardless of whether an insured event occurs. ↩
-
For a detailed assessment of the Other comprehensive income option refer to Appendix B Assessment of remaining significant issues, pages 168-170. ↩
-
Or the loss component of the liability for remaining coverage, in the case of a group of onerous contracts. ↩
-
For a detailed assessment of the transition requirements refer to Appendix B Assessment of remaining significant issues, pages 171 - 173. ↩
-
For a detailed assessment of the recognition of income from reinsurance to match losses from onerous underlying contracts refer to Appendix B Assessment of remaining significant issues, pages 153-156. ↩
-
For a detailed assessment of the IFRS 17 requirements for contracts acquired in their settlement period refer to Appendix B Assessment of remaining significant issues, pages 157 - 159. ↩
-
For a detailed assessment of the requirements relating to discount rates refer to Section 3 priority issue B: 'Discount rates'. ↩
-
For a detailed assessment of the risk adjustment for non-financial risk refer to Appendix B Assessment of remaining significant issues, pages 147 - 149. ↩
-
For a detailed assessment of IFRS 17's requirements for the allocation of the contractual service margin refer to Section 3 priority issue A: 'Profit recognition – allocation of CSM for annuities'. ↩
-
For a detailed assessment of IFRS 17's requirements in respect of interest accretion at the locked-in rate under the GMM refer to Appendix B Assessment of remaining significant issues, pages 150 - 152. ↩
-
For a detailed assessment of Other VFA issues 'Eligibility for VFA when there are mutualised cash flows' refer to Appendix B Assessment of remaining significant issues, pages 179 - 181. ↩
-
For a detailed assessment of the ineligibility of reinsurance contracts for the VFA refer to Appendix B Assessment of remaining significant issues, pages 174-176. ↩
-
For a detailed assessment of the prohibition of retrospective application of the risk mitigation option refer to Appendix B Assessment of remaining significant issues, pages 177 - 178. ↩
-
For a detailed assessment of IFRS 17's requirements for the accounting of different aspects of with-profits contracts refer to: * Section 3 priority issue D: 'With-profits: inherited estates'. * Appendix B Assessment of remaining significant issues – Contracts that change nature over time. * Appendix B Assessment of remaining significant issues – Other VFA issues: (iv) Non-profit contracts written by a with-profits fund. ↩
-
This line item presents investment income arising from financial assets measured at Fair Value through Profit or Loss and interest income on assets measured at Amortised Cost and at Fair Value through Other Comprehensive Income. ↩
-
This line item presents investment income arising from financial assets measured at Fair Value through Other Comprehensive Income. ↩
-
https://www.endorsement-board.uk/endorsement-projects/ifrs-17/technical-advisory-group ↩
-
For example, see IASB Board Paper 2A from July 2017, summarising 35 discussions with 153 investors and analysts https://www.ifrs.org/content/dam/ifrs/meetings/2017/july/iasb/ap02a-insurance-contracts.pdf ↩
-
Information presented in the format [IFRS 17: BCXX] refers to IASB® IFRS 17 Basis for Conclusions. ↩
-
For insurance contracts with direct participation features, an entity provides an investment-related service by managing the underlying items on the behalf of the policyholder. ↩
-
In June 2020, in response to feedback that IFRS 17 did not appropriately reflect that many contracts combine insurance coverage and service relating to investment activities, and that the timing of provision of service relating to investment activities and insurance coverage might differ, the IASB amended IFRS 17 to permit entities to recognise CSM in profit or loss for the provision of investment-return services, in addition to insurance coverage service. ↩
-
The IASB Transition Resource Group (TRG) meeting in May 2018 discussed the determination of coverage units and acknowledged that it involves judgements and estimates. https://www.ifrs.org/content/dam/ifrs/meetings/2018/may/trg-for-ifrs-17/ap05-quantity-of-benefits-for-identifying-coverage-units.pdf ↩
-
See paragraphs 3.78 – 3.79 below for explanations of the bottom-up and top-down approach. ↩
-
For example, see IFRS 17: BC193. ↩
-
IFRS 17: BC196 "The Board expects a reference portfolio will typically have liquidity characteristics closer to the liquidity characteristics of the group of insurance contracts than highly liquid, high-quality bonds. Because of the difficulty in assessing liquidity premiums, the Board decided that in applying a top-down approach an entity need not make an adjustment for any remaining differences in liquidity characteristics between the reference portfolio and the insurance contracts." ↩
-
See for example the International Actuarial Association IAN 100 sections 3.15 – 3.18. See also guidance from the Australian Actuaries Institute section 4.2.4 ↩
-
"By pooling the risks arising from a large number of similar contracts, an insurer acquires a reasonable statistical basis for making a credible estimate of the amount, timing and uncertainty of the cash flows arising from the contracts. If the outcome of one contract is independent of the outcome on other contracts, pooling of risks also reduces the risk of random statistical fluctuations." Source: IASB 2007 Discussion Paper Preliminary Views on Insurance Contracts, para. 18(b) ↩
-
Cohorts can be for periods less than one year, e.g. quarterly cohorts ↩
-
We address the EU carve out for annual cohorts in Section 4 from paragraph 4.223 ↩
-
FCA (2017), Review of the fair treatment of with-profits customers: https://www.fca.org.uk/publication/thematic-reviews/tr19-03.pdf. ↩
-
Sometimes referred to as contracts with mutualisation ↩
-
See also IFRS 17: BC170: "The Board considered whether to provide specific guidance on amounts that have accumulated over many decades in participating funds and whose 'ownership' may not be attributable definitively between shareholders and policyholders. It concluded that it would not. In principle, IFRS 17 requires an entity to estimate the cash flows in each scenario. If that requires difficult judgements or involves unusual levels of uncertainty, an entity would consider those matters in deciding what disclosures it must provide to satisfy the disclosure objective in IFRS 17." ↩
-
IFRS 17: 93 - "The objective of the disclosure requirements is for an entity to disclose information in the notes that, together with the information provided in the statement of financial position, statement(s) of financial performance and statement of cash flows, gives a basis for users of financial statements to assess the effect that contracts within the scope of IFRS 17 have on the entity's financial position, financial performance and cash flows." ↩
-
The disclosures required by IFRS 12 paragraph 13 may also be relevant in this context: "An entity shall disclose (a) significant restrictions (eg statutory, contractual and regulatory restrictions) on its ability to access or use the assets and settle the liabilities of the group, ....." ↩
-
IAS 1 paragraphs 17(c) and 31 already require the provision of additional disclosures when compliance with the specific requirements in IFRS is insufficient to enable users of financial statements to understand the impact of particular transactions, other events and conditions on the entity's financial position and financial performance. ↩
-
The functions of the Secretary of State were delegated to the UK Endorsement Board in May 2021. http://www.legislation.gov.uk/id/uksi/2021/609. ↩
-
This refers to insurance contracts that function as long-term savings products (e.g. endowment policies and pensions savings products) ↩
-
OECD data: https://stats.oecd.org/Index.aspx?DataSetCode=PT5#. Estimates vary depending on the reporting organisation: as of 2019, according to Swiss RE, insurance business written in the United Kingdom amounted to about £285bn (Swiss RE Institute, Sigma Report N 3/2021, “World insurance: the recovery gains pace"); this figure is higher than one provided by EY (£253bn) and one provided by Insurance Europe (£223bn). The reason for the differences is not clear. ↩
-
As reported by the Bank of England: https://www.bankofengland.co.uk/prudential-regulation/publication/2020/insurance-data-release-information-and-format-a-call-for-feedback And EIOPA: https://www.eiopa.europa.eu/tools-and-data/insurance-statistics_en ↩
-
Credit Suisse Wealth Reports and Global Wealth Databooks can be found here: https://www.credit-suisse.com/about-us/en/reports-research/global-wealth-report.html ↩
-
According to UK law, an insurer must be separately authorised to write either life or non-life insurance business. While historically a few companies were authorised to write both (composite insurers), currently no new composite licences may be granted. See https://uk.practicallaw.thomsonreuters.com/0-501-2031?transitionType=Default&contextData=(sc.Default) ↩
-
Gross Written Premium Breakdown: Swiss RE Sigma Report 3/2021 AUM breakdown: EIOPA data ↩
-
See list published by the Bank of England: https://www.bankofengland.co.uk/-/media/boe/files/prudential-regulation/authorisations/which-firms-does-the-pra-regulate/2021/list-of-authorised-insurers/list-of-uk-insurers-july-2021.pdf ↩
-
The following are UK regulated markets: IPSX; The London Metal Exchange; ICE Futures Europe; London Stock Exchange; Euronext - Euronext London; NEX Exchange; Cboe Europe Equities Regulated Market. ↩
-
See FCA Handbook: 1.pdf (fca.org.uk) ↩
-
See AIM Rules: AIM Rules for Companies (01012021)_1.pdf (londonstockexchange.com) ↩
-
CA 2006: see section 395 for individual accounts and section 403 for group accounts ↩↩
-
UK SI 2019/707, regulations 67 and 68. Equivalent standards are: * IFRS Standards as adopted by the European Union. * Generally Accepted Accounting Principles of Japan. * Generally Accepted Accounting Principles of the United States of America. * Generally Accepted Accounting Principles of the People's Republic of China. * Generally Accepted Accounting Principles of Canada. * Generally Accepted Accounting Principles of Korea. ↩↩
-
Gross written premium amount presented in Prudential's Annual Report 2020 USD$42,521 translated to GBP using average exchange rate for the year to date (1 USD: 0.78 GBP) as disclosed in Prudential's Annual Report 2020 note A1 Exchange rates (page 215). ↩↩
-
Scottish Widows Limited is a subsidiary of Lloyds Banking Group ↩↩
-
Source RSA Annual Report as at 31 December 2020. RSA was acquired in June 2021 and has since been delisted from UK exchanges. ↩↩
-
This figure excludes the market capitalisation of financial and non-financial companies that have insurance businesses, such as Scottish Widows Limited, HSBC Life or Tesco Underwriting. The gross written premiums attributed to these businesses are, however, included in the figures displayed in the table. Source: Refinitiv Eikon. ↩
-
The Society of Lloyd's prepares its own financial statements using IFRS. ↩
-
https://www.fca.org.uk/brexit/temporary-permissions-regime-tpr ↩
-
https://www.dacbeachcroft.com/en/gb/articles/2021/january/life-after-passporting-the-insurance-sector/ ↩
-
As reported by the OECD: https://stats.oecd.org/Index.aspx?DatasetCode=INSIND ↩
-
A similar point is made in the Economic Report. ↩
-
IFRS 17:7 ↩
-
Further information on the impact of IFRS 17 on non-insurers is provided in an ICAEW Financial Reporting Faculty Factsheet. ↩
-
For the avoidance of doubt, insurance companies that are subsidiaries of non-insurance companies (e.g. banks) are included in the assessment. ↩
-
IFRS Standards Effects Analysis – IFRS 17 Insurance Contracts (May 2017). IFRS 17 Effects Analysis ↩
-
These terms were defined in The Financial Services and Markets Act 2000 (Regulated Activities) Order 2001 ↩
-
Requirements relating to insurance companies were set out in the Companies Act 1985 (Insurance Companies Accounts) Regulations 1993; this was superseded by the Companies Act 2006 and The Large and Medium-sized Companies and Groups (Accounts and Reports) Regulations 2008 (SI 2008/410) ↩
-
The relevant piece of regulation in 2005 was the Integrated Prudential Sourcebook 2004. This was superseded in 2007 and again in 2016 by Solvency II ↩
-
Major insurance and bancassurance groups, with the support of the ABI, entered into a Memorandum of Understanding with the ASB in December 2004 under which they undertook to apply the requirements of FRS 27 in their IFRS accounts ↩
-
The ABI SORP was last updated in 2006 and has subsequently been withdrawn ↩
-
https://www.frc.org.uk/getattachment/2757d651-1f05-4dd6-a1cf-79a648b8a540/Life_Assurance_Report_to_HM-Treasury-June-2005.pdf ↩
-
See in particular the discussion relating to with-profits inherited estates in Section 3 ↩
-
Now superseded by the IASB's Conceptual Framework (2018) ↩
-
IFRS 15 Revenue from Contracts with Customers ↩
-
IAS 37 Provisions, Contingent Liabilities and Contingent Assets ↩
-
IFRS 17:8 ↩
-
IFRS 17: 8A ↩
-
IFRS 17: 7(h) ↩
-
Except, optionally, in measuring the liability for incurred claims under the premium allocation approach, when cash flows are expected to be paid or received in one year or less. IFRS 17:59 ↩
-
See Section 2 and the more detailed discussion in Section 3 - Priority issue C ↩
-
For more detail see the discussions in paragraphs 4.153 - 4.180 below ↩
-
IFRS 17:83 ↩
-
IFRS 17: 80 – 82 et seq ↩
-
IFRS 17:98 - 105B ↩
-
IFRS 17: 101; 104 ↩
-
IFRS 17: 109 ↩
-
Refer to UKEB website for the IFRS 17 Preparer and User Survey Summaries ↩
-
Refer to UKEB website for the IFRS 17 User Roundtable Summary ↩
-
Refer to UKEB website for the IFRS 17 webinars ↩
-
KPMG - Can you see clearly now? Analysts' views on IFRS 17 and the insurance reporting landscape (December 2018) ↩
-
One survey participant chose not to disclose their implementation costs but noted that they were similar in nature to their Solvency II implementation cost. Their implementation cost was estimated by using a regression model based on their Gross Written Premium and was broadly in line with their Solvency II costs. ↩
-
Participants in the UKEB Preparers survey account for over £100 billion in gross written premiums, representing approximately 67% of the UK insurance sector. As the survey covered most, but not all the IFRS-adopting insurance companies in the UK, the information collected through the survey was extrapolated to estimate the total overall cost of compliance. The portion of costs attributable to non-surveyed insurance companies was estimated by a linear regression model based on the below equation: Cost of compliance _i= ẞ_0+ ẞ_1 Gross Written (Premiums) _i+ u_i Coefficients ẞ0 and ẞ1 were used to estimate the cost of compliance for insurance companies where we did not have costs but were able to identify gross written premiums. ↩
-
The Global Public Policy Committee (GPPC) is a global forum of the six largest accounting networks. The GPPC also noted in their paper 'Implementation of IFRS 17 Insurance Contracts - Considerations for those charged with governance' (2020) that there would be wide-ranging potential business impacts on insurance companies encompassing 'strategy, planning, equity and income patterns, pricing, products and distribution channels, taxation, KPIs used to measure management compensation and capital management.' ↩
-
It is not clear what the figures in the range column mean for the one UK participant that provided information on ongoing costs and cost savings ↩
-
The identities of the four UK participants in EFRAG's survey were not disclosed. The fact that estimates were made at different times may account for some of the apparent differences. ↩
-
Refer to the Sunk Costs section below. ↩
-
Refer to paragraph 4.107 for UK Preparer survey views on cost savings. ↩
-
SAS is a global analytics organisation that provides IFRS 17 consultancy and products. The SAS research was informed by a UK-based survey. The report can be accessed at: https://www.risklibrary.net/regulation/compliance/transformation-progress-perspectives-andapproaches-ifrs-17-29356 ↩
-
The Green Book is guidance issued by HM Treasury on how to appraise policies, programmes and projects. ↩
-
IASB Amendments to IFRS Insurance Contracts. These amendments were intended in part to reduce implementation costs by simplifying areas of the standard. ↩
-
At the AM Best webinar 'IFRS 17 What will users do?' held in April 2021, a panellist observed 'Now that the standard is set there has been a lot of automation of controls and analysis which frees up time. Better data provides more insight. Some concepts in IFRS 17 do link more closely to the commercial side and sales side of the business. Historically, it was driven more by regulatory requirements'. ↩
-
One user observed that the standard may encourage insurance companies to reconsider issuing products with fundamentally 'good economics' but that were currently too difficult to explain to investors. For example, investors struggled to support participating with-profits business as profitability was sometimes difficult to demonstrate. In this user's view, the enhanced transparency expected to be provided by IFRS 17 may potentially help revitalise certain products in the market. ↩
-
Similar time frames were also noted by PwC in their survey of global insurance companies' readiness for transition. They found that most insurance companies with stakeholder engagement plans were intending to disclose their opening balance sheet 'between 12 to 15 months after the transition date' and the majority of those would disclose comparative income statement information 'between 3 to 6 months after the effective date'. ↩
-
Further details of the relevant accounting requirements under IFRS 17 are included in Section 2 of this ECA ↩
-
Aon plc is a global professional services firm providing a broad range of risk, retirement and health solutions. Their report can be found here The Impact of IFRS 17 on Key Performance Indicators February 2020. ↩
-
Accountancy Europe informs accounting policy debate in Europe and represents 50 professional organisations from 35 countries that represent 1 million qualified accountants, auditors, and advisors. ↩
-
EFRAG Final Endorsement Advice: IFRS 17 Insurance Contracts Appendix III: para 617 ↩
-
EFRAG also noted that the audit profession had concluded that the 'standard is auditable'. EFRAG Final Endorsement Advice IFRS 17 Insurance Contracts Appendix III: para 619 ↩
-
Direct implementation costs are net of £0.5 billion sunk costs – NB this is likely to be an understatement (see paragraph 4.99) ↩
-
The Economic Report can be found here. ↩
-
Institute and Faculty of Actuaries, 2019, IFRS 17: Profit profiles under IFRS 4 and IFRS 17. Available at: https://www.actuaries.org.uk/system/files/field/document/IFRS%2017_Profit%20profiles%20under%20IFRS%204%20and%20IFRS%2017_20190717.pdf ↩
-
For example, such wider benefits could include: improvements in policy and claims data integrity, new insights from data manipulation, more efficient processes and effective controls, improvements in organisational culture and potential opportunities for innovation. ↩
-
The full text of the Regulation is set out in Section 1 of this [Draft] ECA ↩
-
Paragraph 15 of IAS 1 Presentation of Financial Statements. ↩
-
See paragraphs 2.69 - 2.71 in Section 2 above ↩
-
See 'Other Comprehensive Income option' in Appendix B ↩
-
This assessment is written on the assumption that contracts acquired in their settlement period meet the definition of insurance contract. ↩
-
The relief is available only to the extent that an entity does not have reasonable and supportable information to apply a fully retrospective approach [IFRS 17: C8] ↩
-
MRA = modified retrospective approach to transition; FVA = fair value approach to transition ↩
-
This assessment is written on the assumption that an RITC contract covering liabilities for incurred claims (as opposed to liabilities for remaining coverage) meets the definition of insurance contract. ↩
-
This arises due to the fact that the economics underlying the RITC are different from those underlying the original contracts – the RITC is entered into at a different time and potentially using different pricing assumptions. ↩
-
See also the analysis in respect of Contracts acquired in their settlement period (pages 157 to 159 above). ↩
-
When the obligation specified in the contract is discharged or cancelled or expires. [IFRS 9 3.3.1] ↩
-
A substantial modification of the terms of an existing financial liability, or a part of it, is accounted for as an extinguishment of the original financial liability and the recognition of a new financial liability. [IFRS 9 3.3.2] ↩
-
In accordance with IAS 32.42 a financial asset and a financial liability are offset when, and only when, an entity currently has a legally enforceable right to set off the recognised amounts and the entity intends either to settle on a net basis, or to realise the asset and settle the liability simultaneously. ↩
-
IFRS 17 paragraphs B115-B118 provide specific requirements to the presentation of IFIE arising from risk mitigation activities, which dictate the presentation in profit or loss depending on the type of instruments used for risk mitigation (i.e. derivatives, non-derivative financial instruments measured at fair value through profit or loss or reinsurance contracts held). However, this are not in the scope of this assessment. ↩
-
IAS 8, paragraph 13, states 'An entity shall select and apply its accounting policies consistently for similar transactions, other events and conditions, unless IFRS specifically requires or permits categorisation of items for which different policies may be appropriate. If an IFRS requires or permits such categorisation, an appropriate accounting policy shall be selected and applied consistently to each category'. ↩