7.0 PIR IFRS 9 – Classification & Measurement—Approve Final Comment Letter, Feedback Statement and Compliance Statement
Executive Summary
| Project Type | Influencing |
|---|---|
| Project Scope | Significant |
Purpose of the paper
This paper requests the Board's approval of the comment letter to the IASB and the related feedback statement.
Summary of the Issue
The IASB has commenced a PIR of IFRS 9 Financial Instruments, focused on the classification and measurement requirements. The PIR assesses whether the standard is meeting its objectives, can be applied consistently, provides useful information to users, and that implementation costs are as expected.
Stakeholder outreach has indicated that the IFRS 9 classification and measurement requirements are generally working as intended. The exceptions are: the cashflow characteristics assessments for some financial instruments; and the practical application of the effective interest calculation described at IFRS 9 B5.4.5 and B5.4.6. In addition, at the December 2021 meeting the Board agreed with stakeholder feedback that issues raised by the recent IFRIC tentative agenda decision Cash Received via Electronic Transfer as Settlement for a Financial Asset may be best resolved via the IFRS 9 PIR process. The comment letter reflects this position.
Decisions for the Board
The Board is asked for its:
- approval to issue the comment letter to IASB and publish on the UKEB website;
- approval to publish the feedback statement on the UKEB website; and
- approval of the Due Process Compliance Statement.
Recommendation
We recommend the Board approve the final comment letter and feedback statement for publication, and approve the Due Process Compliance Statement.
Appendices
| Appendix 1 | Draft final comment letter |
|---|---|
| Appendix 2 | Draft feedback statement |
| Appendix 3 | Due Process Compliance Statement |
Background
1In July 2014 the IASB issued IFRS 9 Financial Instruments. The Standard was effective for annual periods commencing on or after 1 January 2018. Insurers may defer the effective date until 1 January 2023 to align with implementation of IFRS 17 Insurance Contracts, providing certain conditions are met.
2IFRS 9 replaced IAS 39 Financial Instruments: Recognition and Measurement. IFRS 9 introduced changes to the IAS 39 accounting requirements in three main areas: classification and measurement, impairment (introduction of Expected Credit Losses) and hedge accounting.
3In accordance with its due process, the IASB is required to conduct a post implementation review (PIR) of each new IFRS standard and major amendment. The purpose of the PIR is to assess whether the standard or amendment is meeting its objectives, can be applied consistently, that information is useful to users of financial statements, and that implementation costs are as expected.
4The IASB's possible actions following the PIR are to:
- Produce educational materials;
- Conduct follow-up research work for possible standard setting; or
- Take no action.
5The IASB has commenced its review of IFRS 9 by considering the standard's classification and measurement requirements, together with the related disclosure requirements in IFRS 7 Financial Instruments: Disclosures. Separate RFIs addressing IFRS 9's impairment and hedge accounting requirements are expected in 2022.
UKEB draft comment letter - key themes
6The UKEB's draft comment letter was open for public consultation from 15 December 2021- 10 January 2022. In anticipation of this short comment period, stakeholder feedback was also obtained via roundtable events and stakeholder meetings with stakeholders prior to the publication of the draft comment letter. The draft comment letter (DCL) noted that:
- IFRS 9 classification and measurement requirements are for the most part working as intended.
- there are two significant exceptions to this - financial instruments with ESG[^1] features and contractually linked instruments. Stakeholders believe that the issue related to financial instruments with ESG features is urgent given the nature of the instruments and their expected rate of growth. They believe this issue should be removed from the PIR process and addressed in a more urgent manner by IASB.
- stakeholders also noted a lack of clarity in the application guidance on the use of the effective interest method. Specifically, the circumstances where paragraphs B5.4.5 and B5.4.6 should be applied. The UKEB DCL included a recommendation that IASB provided further guidance on key terms and additional examples.
- UKEB considered the recent IFRS Interpretations Committee (IFRIC) tentative agenda decision Cash Received via Electronic Transfer as Settlement for a Financial Asset, and recommended this matter should be addressed as part of the PIR of IFRS 9. This is an important issue for UK stakeholders given the widespread implications of the TAD. the UKEB DCL recommended IASB take an approach similar to that already taken for “regular way transactions” (IFRS 9 3.1.2), that is permitting a policy choice to determine the extinguishment of a financial payable (as per IFRS 9 3.3.1) or receivable (as per IFRS 9 3.2.3(a)) at either the commencement or conclusion of a market standard settlement mechanism. We believe that such a treatment could avoid many of the concerns that have been identified with the TAD.
7Stakeholder feedback highlighted a small number of other IFRS 9 classification and measurement areas that may benefit from improvement. However, they were considered to be less important and not needing the IASB's attention as (i) they might distract from the critical issues raised above and (ii) the likelihood that the action necessary to resolve the issue would be disproportionate to the significance of the issue. During the agenda consultation IASB made clear it had limited resources to accommodate further work, and this approach is consistent with ensuring that this limited resource is focused on the most critical issues. Accordingly, these additional items were not included in the comment letter and we do not believe this is necessary. However should the board wish to reference these matters in the comment letter example wording is provided below. This would be inserted into paragraph A1 of the comment letter.
Potential revised wording (modifications in bold).
8Subject to the issues associated with the cash flow characteristics assessment and effective interest method noted below, we have found that the IFRS 9 classification and measurement requirements generally work as intended and are an improvement to the previous rule-based requirements in IAS 39 Financial Instruments: Recognition and Measurement. Our response to the IASB's Request for Information (RFI) therefore focuses primarily on Question 3: Contractual Cash flow Characteristics and Question 7: Amortised Cost and the Effective Interest Method, where improvement, and potentially standard setting activity, are required. Individual responses to RFI questions for areas that, materially, work as intended are not provided. Stakeholders requested UKEB focus its response on the most serious of the topics raised so as not to distract from these critical messages. Examples of other areas for potential improvement raised by stakeholders included the application of the business model test, ability to recycle gains from equity instruments in OCI, the treatment of modifications to contractual cashflows, the boundary between IFRS 16 Leases and IFRS 9 Financial Instruments, and accounting for financial guarantees. However many stakeholders noted these were not priority topics to raise or noted the action necessary to resolve the issue would be disproportionate to the significance of the issue. We have not included these topics in this letter and do not recommend IASB undertake further work in these areas. We also provide comment on the IFRS Interpretations Committee (IFRIC) tentative agenda decision (TAD) Cash Received via Electronic Transfer as Settlement for a Financial Asset at Question 9: Other Matters.
Question for the Board
- Given stakeholder direction not to distract from the critical issues, do Board members agree that it is not necessary to include in our comment letter the issues identified by stakeholders as being lower priority, and that the modification to paragraph A1 above is not required?
Subsequent UK stakeholder feedback
9Subsequent to the December Board meeting, additional stakeholder outreach included a survey on IFRS 9 and an interview with a banking analyst. Including these activities, in total 31 stakeholders, representing 23 organisations, provided feedback via the different formats made available. No responses were received to the draft comment letter. This was not unexpected as many organisations expected to respond on this topic had participated in the earlier outreach events which helped identify the issues included in the draft comment letter.
10Two preparers, representing the banking and insurance sectors, responded to the IFRS 9 survey. Their feedback was consistent with previous stakeholders comment.
11The treatment of financial instruments with ESG features was the most significant area of concern, with concerns raised that fair value treatment of such instruments may reduce decision useful information, and that such an outcome could make green investment less attractive to investors.
12The responses noted that for ESG instruments the economic substance and risks inherent in these products continued to relate to credit and interest rate, making amortised cost the more appropriate methodology. A view expressed in the July 2021 IASB staff paper[^2] was also questioned. This had stated that it was not sufficient when assessing classification to note that an ESG interest rate adjustment is part of the lending profit margin, as “any contractual term that could give rise to variability in the contractual cashflows needs to be assessed to determine whether they are SPPI”. This was considered too strict and could result in fair value accounting treatment, and the likely loss of decision useful information, in too many cases. It noted further guidance was required and in doing so IASB should be mindful of creating a consistent model which would minimize structuring opportunities.
13The banking analyst we consulted felt strongly that lending products should use amortised cost accounting as this provided the most decision useful information and any move away from this would reduce the usefulness of that information. They considered that amortised cost provided transparent and relevant information, and facilitated reliable comparison both within and between organisations, for example on fundamental areas such as lending growth and provision coverage. By contrast, the valuations of lending products at fair value were considered to be opaque, and difficult to disaggregate to obtain decision useful information.
14This feedback is consistent with that previously received and included in the draft comment letter. Paragraph A6 has been expanded to include this additional feedback from the banking analyst, and a new paragraph added at A7c to reflect feedback from the survey responses, and the potential unintended consequences of moving away from principles based accounting requirements.
Questions for the Board
- Do Board members have any suggested amendments to the comment letter included at Appendix 1, or to the feedback statement at Appendix 2?
- Subject to any suggested amendments, does the Board approve the comment letter for issuance to the IASB?
- Subject to any suggested amendments, does the Board approve the feedback statement for publication on the UKEB website?
- Do Board members have any suggested amendments to the draft compliance statement included at Appendix 3?
- Subject to any suggested amendments, does the Board approve the compliance statement for publication on the UKEB website?
Next Steps
15The next project milestones are as follows:
| Date | Milestone | ---------- | ---------- | | P | UKEB Board Approval ------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------ ```
## Post Implementation Review: IFRS 9 Financial Instruments – Classification & Measurement: Final Comment Letter
Executive Summary
| Project Type | Influencing |
|---|---|
| Project Scope | Significant |
Purpose of the paper
This paper requests the Board's approval of the comment letter to the IASB and the related feedback statement.
Summary of the Issue
The IASB has commenced a PIR of IFRS 9 Financial Instruments, focused on the classification and measurement requirements. The PIR assesses whether the standard is meeting its objectives, can be applied consistently, provides useful information to users, and that implementation costs are as expected.
Stakeholder outreach has indicated that the IFRS 9 classification and measurement requirements are generally working as intended. The exceptions are: the cashflow characteristics assessments for some financial instruments; and the practical application of the effective interest calculation described at IFRS 9 B5.4.5 and B5.4.6. In addition, at the December 2021 meeting the Board agreed with stakeholder feedback that issues raised by the recent IFRIC tentative agenda decision Cash Received via Electronic Transfer as Settlement for a Financial Asset may be best resolved via the IFRS 9 PIR process. The comment letter reflects this position.
Decisions for the Board
The Board is asked for its:
- approval to issue the comment letter to IASB and publish on the UKEB website;
- approval to publish the feedback statement on the UKEB website; and
- approval of the Due Process Compliance Statement.
Recommendation
We recommend the Board approve the final comment letter and feedback statement for publication, and approve the Due Process Compliance Statement.
Appendices
| Appendix 1 | Draft final comment letter |
|---|---|
| Appendix 2 | Draft feedback statement |
| Appendix 3 | Due Process Compliance Statement |
Background
1 In July 2014 the IASB issued IFRS 9 Financial Instruments. The Standard was effective for annual periods commencing on or after 1 January 2018. Insurers may defer the effective date until 1 January 2023 to align with implementation of IFRS 17 Insurance Contracts, providing certain conditions are met.
2 IFRS 9 replaced IAS 39 Financial Instruments: Recognition and Measurement. IFRS 9 introduced changes to the IAS 39 accounting requirements in three main areas: classification and measurement, impairment (introduction of Expected Credit Losses) and hedge accounting.
3 In accordance with its due process, the IASB is required to conduct a post implementation review (PIR) of each new IFRS standard and major amendment. The purpose of the PIR is to assess whether the standard or amendment is meeting its objectives, can be applied consistently, that information is useful to users of financial statements, and that implementation costs are as expected.
4 The IASB's possible actions following the PIR are to:
- Produce educational materials;
- Conduct follow-up research work for possible standard setting; or
- Take no action.
5 The IASB has commenced its review of IFRS 9 by considering the standard's classification and measurement requirements, together with the related disclosure requirements in IFRS 7 Financial Instruments: Disclosures. Separate RFIs addressing IFRS 9's impairment and hedge accounting requirements are expected in 2022.
UKEB draft comment letter - key themes
6 The UKEB's draft comment letter was open for public consultation from 15 December 2021- 10 January 2022. In anticipation of this short comment period, stakeholder feedback was also obtained via roundtable events and stakeholder meetings with stakeholders prior to the publication of the draft comment letter. The draft comment letter (DCL) noted that:
- IFRS 9 classification and measurement requirements are for the most part working as intended.
- there are two significant exceptions to this – financial instruments with ESG[^1] features and contractually linked instruments. Stakeholders believe that the issue related to financial instruments with ESG features is urgent given the nature of the instruments and their expected rate of growth. They believe this issue should be removed from the PIR process and addressed in a more urgent manner by IASB.
- stakeholders also noted a lack of clarity in the application guidance on the use of the effective interest method. Specifically, the circumstances where paragraphs B5.4.5 and B5.4.6 should be applied. The UKEB DCL included a recommendation that IASB provided further guidance on key terms and additional examples.
- UKEB considered the recent IFRS Interpretations Committee (IFRIC) tentative agenda decision (TAD) Cash Received via Electronic Transfer as Settlement for a Financial Asset, and recommended this matter should be addressed as part of the PIR of IFRS 9. This is an important issue for UK stakeholders given the widespread implications of the TAD. the UKEB DCL recommended IASB take an approach similar to that already taken for “regular way transactions” (IFRS 9 3.1.2), that is permitting a policy choice to determine the extinguishment of a financial payable (as per IFRS 9 3.3.1) or receivable (as per IFRS 9 3.2.3(a)) at either the commencement or conclusion of a market standard settlement mechanism. We believe that such a treatment could avoid many of the concerns that have been identified with the TAD.
7 Stakeholder feedback highlighted a small number of other IFRS 9 classification and measurement areas that may benefit from improvement. However, they were considered to be less important and not needing the IASB's attention as (i) they might distract from the critical issues raised above and (ii) the likelihood that the action necessary to resolve the issue would be disproportionate to the significance of the issue. During the agenda consultation IASB made clear it had limited resources to accommodate further work, and this approach is consistent with ensuring that this limited resource is focused on the most critical issues. Accordingly, these additional items were not included in the comment letter and we do not believe this is necessary. However should the board wish to reference these matters in the comment letter example wording is provided below. This would be inserted into paragraph A1 of the comment letter.
Potential revised wording (modifications in bold).
8 Subject to the issues associated with the cash flow characteristics assessment and effective interest method noted below, we have found that the IFRS 9 classification and measurement requirements generally work as intended and are an improvement to the previous rule-based requirements in IAS 39 Financial Instruments: Recognition and Measurement. Our response to the IASB's Request for Information (RFI) therefore focuses primarily on Question 3: Contractual Cash flow Characteristics and Question 7: Amortised Cost and the Effective Interest Method, where improvement, and potentially standard setting activity, are required. Individual responses to RFI questions for areas that, materially, work as intended are not provided. Stakeholders requested UKEB focus its response on the most serious of the topics raised so as not to distract from these critical messages. Examples of other areas for potential improvement raised by stakeholders included the application of the business model test, ability to recycle gains from equity instruments in OCI, the treatment of modifications to contractual cashflows, the boundary between IFRS 16 Leases and IFRS 9 Financial Instruments, and accounting for financial guarantees. However many stakeholders noted these were not priority topics to raise or noted the action necessary to resolve the issue would be disproportionate to the significance of the issue. We have not included these topics in this letter and do not recommend IASB undertake further work in these areas. We also provide comment on the IFRS Interpretations Committee (IFRIC) tentative agenda decision (TAD) Cash Received via Electronic Transfer as Settlement for a Financial Asset at Question 9: Other Matters.
Question for the Board
- Given stakeholder direction not to distract from the critical issues, do Board members agree that it is not necessary to include in our comment letter the issues identified by stakeholders as being lower priority, and that the modification to paragraph A1 above is not required?
Subsequent UK stakeholder feedback
9 Subsequent to the December Board meeting, additional stakeholder outreach included a survey on IFRS 9 and an interview with a banking analyst. Including these activities, in total 31 stakeholders, representing 23 organisations, provided feedback via the different formats made available. No responses were received to the draft comment letter. This was not unexpected as many organisations expected to respond on this topic had participated in the earlier outreach events which helped identify the issues included in the draft comment letter.
10 Two preparers, representing the banking and insurance sectors, responded to the IFRS 9 survey. Their feedback was consistent with previous stakeholders comment.
11 The treatment of financial instruments with ESG features was the most significant area of concern, with concerns raised that fair value treatment of such instruments may reduce decision useful information, and that such an outcome could make green investment less attractive to investors.
12 The responses noted that for ESG instruments the economic substance and risks inherent in these products continued to relate to credit and interest rate, making amortised cost the more appropriate methodology. A view expressed in the July 2021 IASB staff paper[^2] was also questioned. This had stated that it was not sufficient when assessing classification to note that an ESG interest rate adjustment is part of the lending profit margin, as “any contractual term that could give rise to variability in the contractual cashflows needs to be assessed to determine whether they are SPPI”. This was considered too strict and could result in fair value accounting treatment, and the likely loss of decision useful information, in too many cases. It noted further guidance was required and in doing so IASB should be mindful of creating a consistent model which would minimize structuring opportunities.
13 The banking analyst we consulted felt strongly that lending products should use amortised cost accounting as this provided the most decision useful information and any move away from this would reduce the usefulness of that information. They considered that amortised cost provided transparent and relevant information, and facilitated reliable comparison both within and between organisations, for example on fundamental areas such as lending growth and provision coverage. By contrast, the valuations of lending products at fair value were considered to be opaque, and difficult to disaggregate to obtain decision useful information.
14 This feedback is consistent with that previously received and included in the draft comment letter. Paragraph A6 has been expanded to include this additional feedback from the banking analyst, and a new paragraph added at A7c to reflect feedback from the survey responses, and the potential unintended consequences of moving away from principles based accounting requirements.
Next Steps
15 The next project milestones are as follows:
| Date | Milestone | Complete |
|---|---|---|
| 30 September 2021 | IASB Publish RFI | ✔ |
| 15 November 2021 | Publish stakeholder survey. | ✔ |
| 18 November 2021 | Board Meeting | Approve PIP | ✔ |
| 09 December 2021 | Board Meeting | Approve Draft Comment Letter | ✔ |
| 15 December 2021 | Publish Draft Comment Letter. Deadline for responses 10 January 2022. | ✔ |
| 20 January 2022 | Board Meeting | Approve Final Comment Letter Approve Feedback Statement Approve Compliance Statement | |
| 28 January 2022 | Submit Comment Letter to IASB Publish Feedback Statement on website. | |
| 17 February 2022 | Board Meeting | Final Compliance Statement to board for noting. | |
| 18 February 2022 | Publish Compliance Statement on website. |
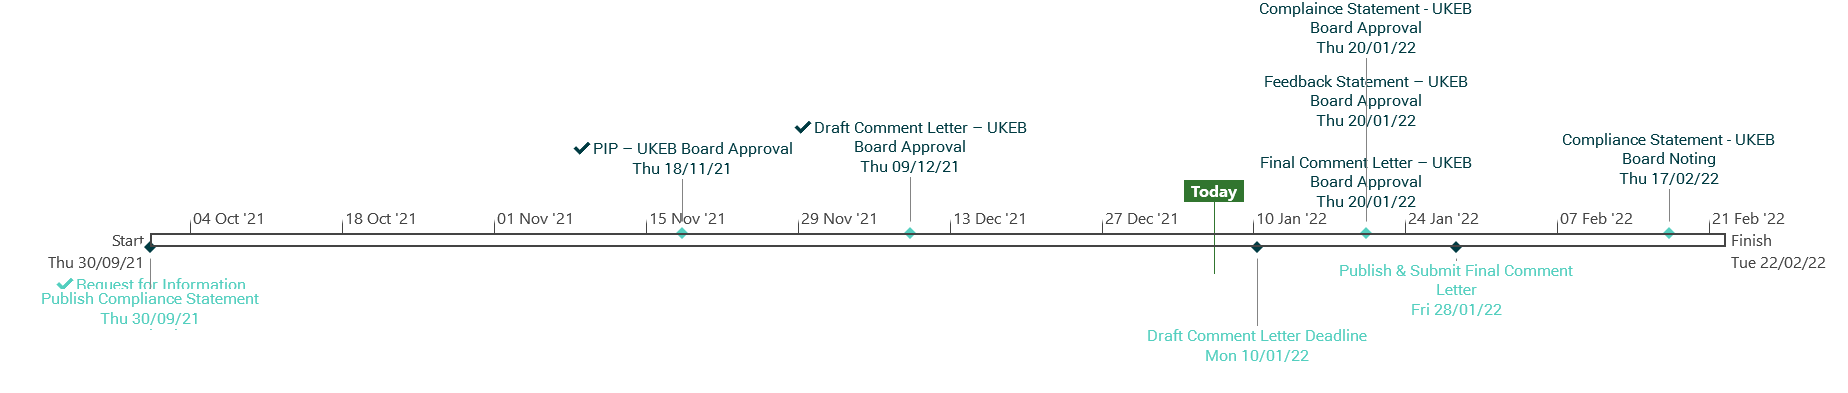
APPENDIX 1: INVITATION TO COMMENT - REQUEST FOR INFORMATION - POST-IMPLEMENTATION REVIEW: IFRS 9 FINANCIAL INSTRUMENTS CLASSIFICATION AND MEASUREMENT
Dr Andreas Barckow Chairman International Accounting Standards Board 7 Westferry Circus Canary Wharf London E14 4HD
28 January 2022
Dear Dr Barckow
The UK Endorsement Board (UKEB) is responsible for endorsement and adoption of IFRS for use in the UK and therefore is the UK's National Standard Setter for IFRS. The UKEB also leads the UK's engagement with the IFRS Foundation (Foundation) on the development of new standards, amendments and interpretations. This letter is intended to contribute to the Foundation's due process. The views expressed by the UKEB in this letter are separate from, and will not necessarily affect the conclusions in, any endorsement and adoption assessment on new or amended International Accounting Standards undertaken by the UKEB.
There are currently approximately 1,500 entities with equity listed on London Stock Exchange that prepare their financial statements in accordance with IFRS Standards[^A1-1]. In addition, UK law allows unlisted companies the option to use IFRS and approximately 14,000 such companies currently take up this option[^A1-2].
We welcome the opportunity to provide comment on the IASB's Request for Information – Post-implementation Review: IFRS 9 Financial Instruments Classification and Measurement (RFI). To develop our response our work has included in-house research, a stakeholder survey, and feedback received during stakeholder roundtables and interviews. Based upon this work we note the following:
1 Our stakeholder outreach has highlighted that the IFRS 9 classification and measurement requirements generally work as intended and represent an improvement to the previous rule-based requirements in IAS 39 Financial Instruments: Recognition and Measurement. Our response to the RFI will therefore focus on the three significant areas where we consider that improvement, and potentially standard setting activity, is required. Two areas of concern relate to the application of the contractual cash flow characteristics assessment for financial assets, while the third relates to the effective interest rate methodology.
Financial instruments with sustainability-linked features
2 The IFRS 9 classification and measurement requirements are designed to deal with all types of financial instruments. In recent years, instruments for which interest rates vary on the occurrence of one or more pre-determined events have become increasingly prevalent. Of these, financial instruments with ESG[^A1-3] features (“FIEF”) are the most common and are expected to grow significantly in future. FIEF come in a variety of forms, including sophisticated instruments which clearly qualify for fair value treatment under IFRS 9. Our concern lies with financial instruments that, but for the ESG feature, would be considered basic lending and qualify for amortised cost accounting.
3 There is a general concern that IFRS 9 currently does not adequately cater for such instruments. In the absence of clear guidance, there is a risk that inconsistent accounting practices will develop for such instruments. Furthermore, UK stakeholders have expressed concern that FIEF that are in substance basic lending may be required to be accounted for at fair value based on the current drafting of IFRS 9. In this respect, it is worth noting that the purpose of ESG features in such instruments is generally to change behaviour and not to lead to a change in the value of the loan. Where the product in substance represents basic lending, IFRS 9 is based on the premise that amortised cost provides users with more decision useful information: (i) the effective interest rate (EIR) interest flows are reported as interest income, often monitored as a key metric for such instruments; and (ii) the expected credit loss requirements of IFRS 9 are considered to provide comprehensive and transparent information on the performance of the product. Measuring such basic lending instruments at fair value would lose that decision useful information.
4 In Appendix 1 paragraph A7, we make a number of suggestions to clarify the IFRS 9 requirements in this regard. These include adding relevant examples to IFRS 9 and providing further guidance as to what can be considered covered by credit risk, profit margin, and "other basic lending risks". Guidance included previously for the treatment of items related to liquidity risk and administrative costs provides precedent for such an approach.
5 We believe resolution of this issue is needed as a matter of urgency. This product set is expected to experience significant and sustained growth in the near future. We concur with stakeholders that attempting to resolve this issue via the Post Implementation Review (PIR) process is unlikely to lead to a timely outcome. We urge the IASB to address it via a more urgent mechanism than the PIR process.
Amortised cost and the effective interest method
6 Stakeholder feedback indicates that the application guidance in IFRS 9 in relation to amortised cost and use of the effective interest method is not sufficiently clear. In particular, stakeholders raise the application of B5.4.5 and B5.4.6 and whether a revision of estimates should be reflected as a change in the effective interest rate or recognised as a 'catch-up adjustment'. We have therefore included recommendations on this issue in Appendix 1 paragraphs A12-A13. If, as expected, FIEF become more prevalent and the potential change in cash flows due to the ESG feature becomes greater, then this issue will become more significant. We consider this issue should be addressed alongside those described above relating to FIEF and with the same urgency. Accounting for basic lending instruments at fair value would lose decision useful information.
A7 The nature of basic lending products will evolve over time to meet the changing needs of society. A principle-based accounting standard should accommodate such changes in a way that provides decision useful information. To enable such products to pass the cash flow characteristics test, and hence achieve amortised cost accounting (to reflect the substance of the transaction), we recommend that IASB:
- Provide additional examples illustrating the application of the cash flow characteristics assessment to FIEF products;
- Provide further guidance as to permitted elements of credit risk and profit margin relevant to this debate. In doing so we recommend the IASB expands on Paragraph B4.1.7A of IFRS 9 which states that 'interest can also include consideration for other basic lending risks' and 'interest can include a profit margin that is consistent with a basic lending arrangement to clarify the nature of “other basic lending risks" and how ESG features may fit within this. B4.1.7A already specifies liquidity risk and administrative costs as examples of activities which meet these definitions, and this creates precedent to include other helpful examples such as those relevant to FEIF assessments.
- Be mindful when developing further guidance or interpretation that it does not cumulatively move the standard from a principles to a rules based approach or inadvertently creates bright lines e.g. creating examples to address individual issues ends up creating new redlines. This is considered particularly important when dealing with examples where there are likely to be further developments or ongoing changes, such as new product sets. In this respect, it is more helpful when guidance opens up or clarifies new possibilities rather than reduces possibilities. For example, one stakeholder expressed concern with the view expressed in the July 2021 IASB staff paper[^A1-6] that it was not sufficient when assessing classification to just note that an ESG interest rate adjustment is part of the lending profit margin (an acceptable element of SPPI at B4.1.7.A), as “any contractual term that could give rise to variability in the contractual cashflows needs to be assessed to determine whether they are SPPI". This was considered too narrow an interpretation, which by excluding consideration of broader factors or context was likely to lead an inappropriate number of loans then failing the SPPI test and moved to fair value accounting, in turn leading to less decision useful information.
A8 In addition, we believe resolution of this issue is needed as a matter of urgency. This product set is expected to experience significant and sustained growth in the near future. Attempting to resolve this issue via the PIR process is considered unlikely to lead to a timely outcome and may exacerbate the inconsistent accounting practices. We urge IASB to address it via a more urgent mechanism than the PIR process.
Contractually linked instruments and non-recourse finance
A9 Currently there is limited guidance on the contractual cash flow characteristics assessment in IFRS 9 in relation to the boundary between contractually linked instruments (CLI) and non-recourse finance (NRF) transactions. The boundary is not clear and, with the existing guidance, distinguishing between the two is challenging. As CLI requires the underlying portfolio to meet the cash flow characteristics test to achieve amortised cost accounting and NRF does not, outcomes can be very different. Outcomes can also be counterintuitive: instruments with relatively little asset risk may be treated as CLI and measured at fair value while other instruments with significantly more asset risk may be treated as NRF and measured at amortised cost. We are told the volume of analysis is onerous and costly, and the asset classes impacted diverse and widespread. Examples provided by stakeholders have, with permission, been shared with IASB staff.
A10 We strongly recommend the IASB clarifies the objective for contractually linked instruments in IFRS 9, to help enhance stakeholder understanding of the transactions intended to be in scope as well as improving the framework for assessment.
A11 Further work would be required to determine the most effective way to improve clarity, but aspects to consider could include:
- Providing definitions of key terms in B4.1.20 including “multiple” (we suggest this must be more than two), “tranche” and “issuer”, and clarify whether these must be contractual or can be implied (for example a legal vs implicit tranche, whether contractual linkage can be implied when lending to an entity with limited other assets).
- Assessing the most senior tranche as non-recourse finance, leaving the CLI guidance to only apply to tranches which apply credit protection to the structure. This would provide clarity and reduce the number of instruments that need to be assessed under the more onerous/costly CLI guidance.
- Clarifying that where lending is provided by a single lender (or multiple lenders acting pari-passu) this is not within the scope of CLI.
- Clarifying what is meant by concentrations of credit risk, particularly in structures with only two parties – a borrower and a single lender (or multiple lenders acting pari-passu).
Amortised cost and the effective interest method
Question 7: Amortised cost and the effective interest method
- Is the effective interest method working as the Board intended? Why or why not?
Please explain whether applying the requirements results in useful information for users of financial statements about the amount, timing and uncertainty of future cash flows of the financial instruments that are measured applying the effective interest method.
- Can the effective interest method be applied consistently? Why or why not?
Please explain the types of changes in contractual cash flows for which entities apply paragraph B5.4.5 of IFRS 9 or paragraph B5.4.6 of IFRS 9 (the 'catch-up adjustment') and whether there is diversity in practice in determining when those paragraphs apply. Please also explain the line item in profit or loss in which the catch-up adjustments are presented and how significant these adjustments typically are. If diversity in practice exists, please explain how pervasive the diversity is and its effect on entities' financial statements.
A12 It is not always clear how uncertain cash flows should best be reflected in the EIR calculation, and specifically in which circumstances paragraphs B5.4.5 or B5.4.6 should be applied. This was illustrated in the recent IFRS Interpretations Committee (IFRIC) TLTRO decision, which considered an instrument where the interest rate may vary on a pre-determined basis, on the occurrence of one or more pre-determined events. This is not an isolated example as such ratchet structures feature in other financial instruments, including many FIEF.
A13 We recommend the IASB provides further guidance on key terms such as “floating rate" and "market rate” to assist in understanding better the boundary between instruments to be accounted for under paragraph B5.4.5 and those to which B5.4.6 applies. Further examples, particularly those involving FIEF, would be helpful. In paragraph A8 we recommend removing the issue related to ESG instruments from the PIR and addressing it via a more urgent mechanism. We make the same recommendation in relation to this matter, as if (as expected) FIEF become more prevalent and the potential change in cash flows due to the ESG feature becomes greater, a clear understanding of the application of the EIR requirements to such instruments will be required.
Question 9: Other matters
- Are there any further matters that you think the Board should examine as part of the post-implementation review of the classification and measurement requirements in IFRS 9? If yes, what are those matters and why should they be examined? Please explain why those matters should be considered in the context of the purpose of the post-implementation review, and the pervasiveness of any matter raised. Please provide examples and supporting evidence when relevant.
A14 In its September 2021 update IFRIC published a tentative agenda decision (TAD) Cash Received via Electronic Transfer as Settlement for a Financial Asset. The IFRIC was asked whether an entity can derecognise a trade receivable and recognise cash on the date the cash transfer is initiated (its reporting date), rather than on the date the cash transfer is settled (after its reporting date). The IFRIC concluded that: an entity derecognises the trade receivable on the date on which its contractual rights to the cash flows from the trade receivable expire; and recognises the cash (or another financial asset) received as settlement for that trade receivable on the same date.
A15 Though we agree this approach complies with a literal reading of the IFRS 9 requirements, it appears to run counter to well established practice. While the TAD addresses only the specific transaction submitted to the Committee, it would appear to have far reaching implications. It is probable that as a direct result of this TAD, entities will have to reconsider their approaches for a wide range of payment systems that were not considered by the IFRIC when it issued its TAD. These include: payment settlement, including cheque payments in lieu of trade payables/ trade receivables; credit card receipts that can be cancelled before they are settled; payments made for a financial liability by electronic transfer; and intragroup cash transfers straddling a reporting period end. It would also appear that creditors paying accounts payable would also have to review the approach they take to accounting for those transactions.
A16 The TAD would potentially require significant analysis by preparers to determine the exact point at which cash is legally transferred. This would require detailed analysis of each transaction type as the timing of extinguishment may not be known without additional information and analysis (e.g. for international transfers legal extinguishment may arise sometime in the middle of the settlement cycle, rather than only at the end). As noted by one respondent to the TAD, both entities involved in a transaction would need to be able to answer questions such as “if the receiver's bank failed after the cash was received by the bank but before the receiver's bank account was credited with the funds, would the receiver have a claim on the payer, or would the payer's obligation be extinguished at this point and the receiver's claim be solely on its own bank?". Obtaining legal advice to establish when routine trade receivables (and trade payables) are extinguished for the different jurisdictions and settlement systems involved will be time consuming, costly and an unnecessary diversion from already established and understood norms in the market.
A17 Even if the legal rights can be established to the level required, new accounting will need to be established that addresses the potential mismatch between the timing of the settlement/payment of a receivable and the transfer of cash into/out of accounts. This may now happen earlier or later, which could be impacted by whether the counterparties are using the same paying /receiving bank or different institutions. Entities will be required to create a new class of financial asset/liability to “fill the gap” between, for example, a liability being extinguished and cash arriving to the bank account. This will require the creation of new subledgers and control systems.
A18 A significant number of respondents to the IFRIC noted similar concerns and recommended that instead of an IFRIC Agenda Decision being published, the matter should instead be considered as part of the IFRS 9 PIR. The UKEB agrees with this view. Specifically we recommend that the IASB consider (as part of the PIR) applying a similar approach to that already taken for "regular way transactions” (IFRS 9 3.1.2), that is permitting a policy choice to determine the extinguishment of a financial payable (as per IFRS 9 3.3.1) or receivable (as per IFRS 9 3.2.3(a)) at either the commencement or conclusion of a market standard settlement mechanism. We believe that such a treatment could avoid many of the concerns that have been identified with the TAD.
Yours sincerely
Pauline Wallace Chair UK Endorsement Board
UKEB FEEDBACK STATEMENT
IASB Post-implementation Review (PIR) IFRS 9 Financial Instruments: Classification and Measurement
[DRAFT FOR BOARD REVIEW]
January 2022
The UK Endorsement Board (UKEB) is responsible for endorsement and adoption of IFRS for use in the UK and therefore is the UK's National Standard Setter for IFRS. The UKEB also leads the UK's engagement with the IFRS Foundation (Foundation) on the development of new standards, amendments and interpretations.
The comment letter to which this feedback statement relates forms part of those influencing activities and is intended to contribute to the Foundation's due process. The views expressed by the UKEB in this letter are separate from, and will not necessarily affect the conclusions in, any endorsement and adoption assessment on new or amended International Accounting Standards undertaken by the UKEB.
CONTENTS
- Background
- UKEB draft comment letter - key themes
- Subsequent UK stakeholder feedback
- Next Steps
- Background
- UKEB draft comment letter - key themes
- Subsequent UK stakeholder feedback
- Next Steps
- APPENDIX 1: INVITATION TO COMMENT - REQUEST FOR INFORMATION - POST-IMPLEMENTATION REVIEW: IFRS 9 FINANCIAL INSTRUMENTS CLASSIFICATION AND MEASUREMENT
- UKEB FEEDBACK STATEMENT
- CONTENTS
- Purpose of this feedback statement
- The IASB's Post-implementation Review
- Outreach approach
- 1. Primary topics of concern to UK stakeholders: Contractual cashflow characteristics of financial assets.
- APPENDIX 1: QUESTIONS ON REQUEST FOR INFORMATION: POST IMPLEMENTATION REVIEW IFRS 9, CLASSIFICATION AND MEASUREMENT.
- APPENDIX 3: INFLUENCING PROCESS: PIR IFRS 9
Purpose of this feedback statement
This feedback statement presents the views of UK stakeholders received during the UKEB's outreach activities on the IASB's Post-implementation Review (PIR) of IFRS 9 Financial Instruments: Classification and Measurement and explains how the UKEB’s comment letter addressed those views.
The IASB's Post-implementation Review
The IASB has commenced its PIR of IFRS 9 Financial Instruments, focusing initially on the classification and measurement requirements.
The PIR assesses whether the standard is meeting its objectives, can be applied consistently, provides useful information to users, and that implementation costs are as expected. The IASB's possible actions following the PIR are to:
- Produce educational materials;
- Conduct follow-up research work for possible standard setting; or
- Take no action.
IASB's Request for Information identified nine areas of the classification and measurement requirements on which IASB were seeking feedback. The UKEB response was responsive to UK stakeholder feedback and focused only on those areas where UK stakeholders expressed particular concerns.
Outreach approach
The UKEB's outreach activities took place between October 2021 and January 2022.
The outreach approach was underpinned by the UKEB's guiding principles of thought leadership, transparency, independence and accountability.
The outreach activities with UK stakeholders revealed that the IFRS 9 classification and measurement requirements generally work as intended, except for a small number of concern. Stakeholders requested UKEB focus its response on the most serious of these topics (the "primary topics”) so as not to distract from these critical messages.
All comments and views were considered in reaching the UKEB final views on the questions raised.
Outreach activities included:
- Hosting a series of roundtables events with stakeholder groups which included preparers, auditors/accounting firms.
- Meetings with users, accounting firms and regulators;
- An online survey; and
- Public consultation on the UKEB's draft comment letter;
In total 31 stakeholders representing 23 organisations, and one professional body/committee engaged in outreach activities as follows.
| Stakeholder type | Stakeholders | Organisations represented |
|---|---|---|
| Preparers | 15 | 12 |
| Auditors & Accounting Firms | 12 | 7 |
| Regulators | 3 | 3 |
| Users | 1 | 1 |
| Professional bodies / committees* | 1 professional body/ committee |
* The professional bodies/committees have multiple members, often representing a variety of stakeholder types.
1. Primary topics of concern to UK stakeholders: Contractual cashflow characteristics of financial assets.
| Initial stakeholder views | Text | Status |
|---|---|---|
Diagram 1: Project timeline of the UKEB approval process for the Final Comment Letter to IASB on IFRS 9 PIR.
This timeline illustrates key UKEB Board approvals, comment letter deadlines, and publication dates from September 2021 to February 2022.
APPENDIX 1: QUESTIONS ON REQUEST FOR INFORMATION: POST IMPLEMENTATION REVIEW IFRS 9, CLASSIFICATION AND MEASUREMENT.
A1 Subject to the issues associated with the cash flow characteristics assessment and effective interest method noted below, we have found that the IFRS 9 classification and measurement requirements generally work as intended and are an improvement to the previous rule-based requirements in IAS 39 Financial Instruments: Recognition and Measurement. Our response to the IASB's Request For Information (RFI) therefore focuses primarily on Question 3: Contractual Cash flow Characteristics and Question 7: Amortised Cost and the Effective Interest Method, where improvement, and potentially standard setting activity, are required. Individual responses to RFI questions for areas that, materially, work as intended are not provided. We also provide comment on the IFRS Interpretations Committee (IFRIC) tentative agenda decision (TAD) Cash Received via Electronic Transfer as Settlement for a Financial Asset at Question 9: Other Matters.
Question 3: Contractual cash flow characteristics
- Is the cash flow characteristics assessment working as the Board intended? Why or why not? Please explain whether requiring entities to classify and measure a financial asset considering the asset's cash flow characteristics achieves the Board's objective of entities providing users of financial statements with useful information about the amount, timing and uncertainty of future cash flows. If, in your view, useful information could be provided about a financial asset with cash flows that are not SPPI applying IFRS 9 (that is, an asset that is required to be measured at fair value through profit or loss applying IFRS 9) by applying a different measurement approach (that is, using amortised cost or fair value through OCI) please explain:
- why the asset is required to be measured at fair value through profit or loss (that is, why, applying IFRS 9, the entity concludes that the asset has cash flows that are not SPPI).
- which measurement approach you think could provide useful information about the asset and why, including an explanation of how that approach would apply. For example, please explain how you would apply the amortised cost measurement requirements to the asset (in particular, if cash flows are subject to variability other than credit risk). (See Section 7 for more questions about applying the effective interest method.)
- Can the cash flow characteristics assessment be applied consistently? Why or why not? Please explain whether the requirements are clear and comprehensive enough to enable the assessment to be applied in a consistent manner to all financial assets within the scope of IFRS 9 (including financial assets with new product features such as sustainability-linked features). If diversity in practice exists, please explain how pervasive the diversity is and its effect on entities' financial statements.
- Are there any unexpected effects arising from the cash flow characteristics assessment? How significant are these effects? Please explain the costs and benefits of the contractual cash flow assessment, considering any financial reporting effects or operational effects for preparers of financial statements, users of financial statements, auditors or regulators. In responding to (a)-(c), please include information about financial instruments with sustainability-linked features (see Spotlight 3.1) and contractually linked instruments (see Spotlight 3.2).
Contractual cash flow characteristics of financial assets
A2 To develop our response our work has included in-house research, a stakeholder survey and feedback received during stakeholder roundtables and interviews. This has identified two significant areas where the cash flow characteristics test is not working as intended, leading to inconsistent application and counterintuitive results, and a third area of concern relating to the effective interest rate methodology. We believe improvement, and potentially standard setting activity, is required in these areas. These issues are described below.
Financial instruments with sustainability-linked features
A3 The IFRS 9 classification and measurement requirements are principles-based and therefore intended to deal with all types of financial instruments, including new financial instruments as they emerge.
A4 Subsequent to IFRS 9 being issued, financial instruments for which interest rates vary on the occurrence of one or more pre-determined events have become more prevalent. Of these, financial instruments with ESG[^A1-4] features (“FIEF”) are the most common and are expected to grow significantly in future. FIEF come in variety of forms, including sophisticated instruments which clearly qualify for fair value treatment under IFRS 9. The scope of this response and the discussion below relates to financial instruments that, but for the ESG[^A1-5] feature, would be considered basic lending and qualify for amortised cost accounting
A5 We understand that the IFRS 9 requirements do not provide adequate guidance to enable accounting for FIEF that is consistent with the substance of the transactions. Current practice varies, with some considering the ESG feature as part of credit risk, and others considering it a part of the profit margin. Many consider such features to meet the de-minimis criteria of IFRS 9 B4.1.18 but acknowledge this may not be a sustainable argument should these features become more prominent as this asset class continues to evolve and grow.
A6 UK stakeholders expressed overwhelming concern that, once ESG features are material, FIEF that in substance represent basic lending may be required to be accounted for at fair value based on current IFRS 9 requirements. In this respect it is important to note that the purpose of ESG features in such instruments is generally to change behaviour and it is not intended that they will lead to a change in the value of the loan. Where the product in substance represents basic lending, IFRS 9 is based on the premise that amortised cost provides users with more decision useful information. The EIR interest flows are reported as interest income, which in various forms is monitored as a key metric. The expected credit loss requirements of IFRS 9 are considered to provide comprehensive and transparent information on the performance of the product. Discussion with a banking analyst highlighted that the transparency of amortised cost accounting produces more relevant information, facilitates comparison within and between organisations, and allows critical information such as lending growth and provision coverage to be clearly identified. By contrast lending at fair value was considered opaque and difficult to disaggregate to obtain the desired information. Accounting for basic lending instruments at fair value would lose decision useful information.
A7 The nature of basic lending products will evolve over time to meet the changing needs of society. A principle-based accounting standard should accommodate such changes in a way that provides decision useful information. To enable such products to pass the cash flow characteristics test, and hence achieve amortised cost accounting (to reflect the substance of the transaction), we recommend that IASB:
- Provide additional examples illustrating the application of the cash flow characteristics assessment to FIEF products;
- Provide further guidance as to permitted elements of credit risk and profit margin relevant to this debate. In doing so we recommend the IASB expands on Paragraph B4.1.7A of IFRS 9 which states that 'interest can also include consideration for other basic lending risks' and 'interest can include a profit margin that is consistent with a basic lending arrangement to clarify the nature of “other basic lending risks" and how ESG features may fit within this. B4.1.7A already specifies liquidity risk and administrative costs as examples of activities which meet these definitions, and this creates precedent to include other helpful examples such as those relevant to FEIF assessments.
- Be mindful when developing further guidance or interpretation that it does not cumulatively move the standard from a principles to a rules based approach or inadvertently creates bright lines e.g. creating examples to address individual issues ends up creating new redlines. This is considered particularly important when dealing with examples where there are likely to be further developments or ongoing changes, such as new product sets. In this respect, it is more helpful when guidance opens up or clarifies new possibilities rather than reduces possibilities. For example, one stakeholder expressed concern with the view expressed in the July 2021 IASB staff paper[^A1-6] that it was not sufficient when assessing classification to just note that an ESG interest rate adjustment is part of the lending profit margin (an acceptable element of SPPI at B4.1.7.A), as “any contractual term that could give rise to variability in the contractual cashflows needs to be assessed to determine whether they are SPPI". This was considered too narrow an interpretation, which by excluding consideration of broader factors or context was likely to lead an inappropriate number of loans then failing the SPPI test and moved to fair value accounting, in turn leading to less decision useful information.
A8 In addition, we believe resolution of this issue is needed as a matter of urgency. This product set is expected to experience significant and sustained growth in the near future. Attempting to resolve this issue via the PIR process is considered unlikely to lead to a timely outcome and may exacerbate the inconsistent accounting practices. We urge IASB to address it via a more urgent mechanism than the PIR process.
Contractually linked instruments and non-recourse finance
A9 Currently there is limited guidance on the contractual cash flow characteristics assessment in IFRS 9 in relation to the boundary between contractually linked instruments (CLI) and non-recourse finance (NRF) transactions. The boundary is not clear and, with the existing guidance, distinguishing between the two is challenging. As CLI requires the underlying portfolio to meet the cash flow characteristics test to achieve amortised cost accounting and NRF does not, outcomes can be very different. Outcomes can also be counterintuitive: instruments with relatively little asset risk may be treated as CLI and measured at fair value while other instruments with significantly more asset risk may be treated as NRF and measured at amortised cost. We are told the volume of analysis is onerous and costly, and the asset classes impacted diverse and widespread. Examples provided by stakeholders have, with permission, been shared with IASB staff.
A10 We strongly recommend the IASB clarifies the objective for contractually linked instruments in IFRS 9, to help enhance stakeholder understanding of the transactions intended to be in scope as well as improving the framework for assessment.
A11 Further work would be required to determine the most effective way to improve clarity, but aspects to consider could include:
- Providing definitions of key terms in B4.1.20 including “multiple” (we suggest this must be more than two), “tranche” and “issuer”, and clarify whether these must be contractual or can be implied (for example a legal vs implicit tranche, whether contractual linkage can be implied when lending to an entity with limited other assets).
- Assessing the most senior tranche as non-recourse finance, leaving the CLI guidance to only apply to tranches which apply credit protection to the structure. This would provide clarity and reduce the number of instruments that need to be assessed under the more onerous/costly CLI guidance.
- Clarifying that where lending is provided by a single lender (or multiple lenders acting pari-passu) this is not within the scope of CLI.
- Clarifying what is meant by concentrations of credit risk, particularly in structures with only two parties – a borrower and a single lender (or multiple lenders acting pari-passu).
Amortised cost and the effective interest method
Question 7: Amortised cost and the effective interest method
- Is the effective interest method working as the Board intended? Why or why not?
Please explain whether applying the requirements results in useful information for users of financial statements about the amount, timing and uncertainty of future cash flows of the financial instruments that are measured applying the effective interest method.
- Can the effective interest method be applied consistently? Why or why not?
Please explain the types of changes in contractual cash flows for which entities apply paragraph B5.4.5 of IFRS 9 or paragraph B5.4.6 of IFRS 9 (the 'catch-up adjustment') and whether there is diversity in practice in determining when those paragraphs apply. Please also explain the line item in profit or loss in which the catch-up adjustments are presented and how significant these adjustments typically are. If diversity in practice exists, please explain how pervasive the diversity is and its effect on entities' financial statements.
A12 It is not always clear how uncertain cash flows should best be reflected in the EIR calculation, and specifically in which circumstances paragraphs B5.4.5 or B5.4.6 should be applied. This was illustrated in the recent IFRS Interpretations Committee (IFRIC) TLTRO decision, which considered an instrument where the interest rate may vary on a pre-determined basis, on the occurrence of one or more pre-determined events. This is not an isolated example as such ratchet structures feature in other financial instruments, including many FIEF.
A13 We recommend the IASB provides further guidance on key terms such as “floating rate" and "market rate” to assist in understanding better the boundary between instruments to be accounted for under paragraph B5.4.5 and those to which B5.4.6 applies. Further examples, particularly those involving FIEF, would be helpful. In paragraph A8 we recommend removing the issue related to ESG instruments from the PIR and addressing it via a more urgent mechanism. We make the same recommendation in relation to this matter, as if (as expected) FIEF become more prevalent and the potential change in cash flows due to the ESG feature becomes greater, a clear understanding of the application of the EIR requirements to such instruments will be required.
Question 9: Other matters
- Are there any further matters that you think the Board should examine as part of the post-implementation review of the classification and measurement requirements in IFRS 9? If yes, what are those matters and why should they be examined? Please explain why those matters should be considered in the context of the purpose of the post-implementation review, and the pervasiveness of any matter raised. Please provide examples and supporting evidence when relevant.
A14 In its September 2021 update IFRIC published a tentative agenda decision (TAD) Cash Received via Electronic Transfer as Settlement for a Financial Asset. The IFRIC was asked whether an entity can derecognise a trade receivable and recognise cash on the date the cash transfer is initiated (its reporting date), rather than on the date the cash transfer is settled (after its reporting date). The IFRIC concluded that: an entity derecognises the trade receivable on the date on which its contractual rights to the cash flows from the trade receivable expire; and recognises the cash (or another financial asset) received as settlement for that trade receivable on the same date.
A15 Though we agree this approach complies with a literal reading of the IFRS 9 requirements, it appears to run counter to well established practice. While the TAD addresses only the specific transaction submitted to the Committee, it would appear to have far reaching implications. It is probable that as a direct result of this TAD, entities will have to reconsider their approaches for a wide range of payment systems that were not considered by the IFRIC when it issued its TAD. These include: payment settlement, including cheque payments in lieu of trade payables/ trade receivables; credit card receipts that can be cancelled before they are settled; payments made for a financial liability by electronic transfer; and intragroup cash transfers straddling a reporting period end. It would also appear that creditors paying accounts payable would also have to review the approach they take to accounting for those transactions.
A16 The TAD would potentially require significant analysis by preparers to determine the exact point at which cash is legally transferred. This would require detailed analysis of each transaction type as the timing of extinguishment may not be known without additional information and analysis (e.g. for international transfers legal extinguishment may arise sometime in the middle of the settlement cycle, rather than only at the end). As noted by one respondent to the TAD, both entities involved in a transaction would need to be able to answer questions such as “if the receiver's bank failed after the cash was received by the bank but before the receiver's bank account was credited with the funds, would the receiver have a claim on the payer, or would the payer's obligation be extinguished at this point and the receiver's claim be solely on its own bank?". Obtaining legal advice to establish when routine trade receivables (and trade payables) are extinguished for the different jurisdictions and settlement systems involved will be time consuming, costly and an unnecessary diversion from already established and understood norms in the market.
A17 Even if the legal rights can be established to the level required, new accounting will need to be established that addresses the potential mismatch between the timing of the settlement/payment of a receivable and the transfer of cash into/out of accounts. This may now happen earlier or later, which could be impacted by whether the counterparties are using the same paying /receiving bank or different institutions. Entities will be required to create a new class of financial asset/liability to “fill the gap” between, for example, a liability being extinguished and cash arriving to the bank account. This will require the creation of new subledgers and control systems.
A18 A significant number of respondents to the IFRIC noted similar concerns and recommended that instead of an IFRIC Agenda Decision being published, the matter should instead be considered as part of the IFRS 9 PIR. The UKEB agrees with this view. Specifically we recommend that the IASB consider (as part of the PIR) applying a similar approach to that already taken for "regular way transactions” (IFRS 9 3.1.2), that is permitting a policy choice to determine the extinguishment of a financial payable (as per IFRS 9 3.3.1) or receivable (as per IFRS 9 3.2.3(a)) at either the commencement or conclusion of a market standard settlement mechanism. We believe that such a treatment could avoid many of the concerns that have been identified with the TAD.
APPENDIX 3: INFLUENCING PROCESS: PIR IFRS 9
| Step | Required / Optional | Metrics or evidence