5.0 Non-Current Liabilities with Covenants (IAS 1) – Approve PIP and Draft Comment Letter
Project Type: Influencing Project Scope: Limited (Narrow Scope Amendment)
Executive Summary
Purpose of the paper
This paper presents a draft Project Initiation Plan (PIP) and Draft Comment Letter (DCL) in respect of the IASB's Exposure Draft (ED) Non-current Liabilities with Covenants.
Summary of the Issue
The IASB proposes to amend IAS 1 to specify that specific conditions (covenants) with which a company must comply after the reporting date do not affect the classification of a liability as current or non-current at that date. Instead, a company would be required to:
- present non-current liabilities with covenants as a separate component of non-current liabilities, on the face of its balance sheet; and
- disclose information in the notes about the covenants with which it must comply within 12 months after the reporting date.
The IASB ED was published in November 2021 with a 21 March 2022 comment deadline.
Decisions for the Board
The Board is asked to approve the draft PIP and publication of the DCL for stakeholder comment.
Recommendation
We recommend the Board approves the draft PIP and DCL.
Appendices
- Appendix 1 Draft Project initiation Plan
- Appendix 2 Draft Comment Letter
APPENDIX 1 - Project Initiation Plan
IASB Exposure Draft Non-current Liabilities with Covenants
| Project Type | Influencing |
| Project Scope | Limited (Narrow Scope Amendment) |
Background
1SI/2019/685(5)(b) requires the UKEB to be responsible for “participating in and contributing to the development of a single set of international accounting standards.” The proposed project contributes to this work.
2In January 2020, the International Accounting Standards Board (IASB) issued an amendment to IAS 1 Presentation of Financial Statements (IAS 1) on Classification of Liabilities as Current or Non-current (2020 amendments). It was aimed at clarifying how to classify debt and other financial liabilities as current or non-current in particular circumstances.
3In 2021, stakeholder concerns led to consideration by the IFRS Interpretations Committee (IFRIC) of the application of the 2020 amendments. Specifically, this was centred on classification when a company's right to defer settlement is subject to compliance with covenants within 12 months of the reporting date and the company is not compliant with such covenants at the reporting date. This led to an IFRIC tentative agenda decision (TAD) which stated that as the company would not have a right to defer settlement of the liability and it would present the related liability as a current liability in its balance sheet. Respondents to the TAD were critical of the conclusion and highlighted unintended consequences arising from the 2020 amendment and the TAD which had not been considered when developing the amendments.
4The IASB's response was a tentative decision to amend IAS 1 with respect to classification (as current or non-current), presentation and disclosures of liabilities where an entity's right to defer settlement for at least 12 months is subject to the entity complying with conditions after the reporting period. This was subsequently published as IASB Exposure Draft (ED) Non-current Liabilities with Covenants in November 2021 with a comment deadline of 21 March 2022.
5In the ED, the IASB proposes to amend IAS 1 to specify that “specific conditions”, with which a company must comply after the reporting date, do not affect the classification of a liability as current or non-current at that date. Instead, a company would be required to:
- present non-current liabilities with covenants separately on the face of its balance sheet; and
- disclose information in the notes about the covenants with which it must comply within 12 months of the reporting date.
6Two IASB Board Members have provided an “alternative view” to the ED. Specifically they disagree with the proposal to require an entity to present separately, in its statement of financial position, non-current liabilities subject to such conditions. They also disagree with some of the additional note disclosures proposed in the ED.
Initial identification of issues
7Our initial desk-based review of the standard and feedback from stakeholder discussions have identified a number of concerns with the proposals. We believe that the exposure draft, though narrow in scope, could have a significant impact on financial reporting in the UK. We also spoke with the IASB project team to ensure that our concerns did not arise from any misunderstanding of the requirements of the proposals.
8We have also undertaken some preliminary outreach, having spoken informally to representatives of a number of accounting firms, all of whom appear to reinforce our initial views on the IASB proposals. These are outlined in our Draft Comment Letter (see Appendix 2 of this paper).
9We have discussed the EFRAG draft response with their project team. Their letter raises similar concerns to our own.
Key planning assumptions, constraints and timeline
Comment deadline and resource capacity
10As noted, the IASB's ED was published in November 2021, with a 21 March 2022 comment deadline.
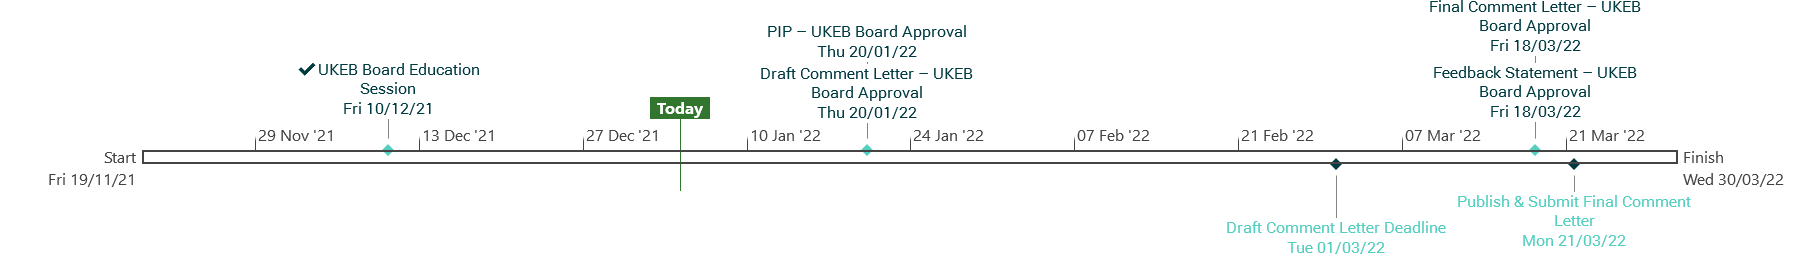
11Given the short deadline, we have included a Draft Comment Letter for Board consideration at this meeting. Subject to Board approval, we plan to publish the draft comment letter in the week following the Board meeting and it will be open for stakeholder comment until about 1 March 2022, ensuring that the comment period is no shorter than 28 days.
12The Final Comment Letter will be circulated to the Board for the 18 March Board Meeting, followed by submission to the IASB on 21 March, subject to Board approval.
13As outlined below we believe that time should be invested in undertaking active outreach with potentially affected stakeholders, including prepares and users. We estimate that 20% of a Project Director's time will be required to obtain the stakeholder feedback and reflect it in the final comment letter.
Assumptions
14We have made the following assumptions in developing this project plan:
- the impact of the amendments is expected to be widespread.
- It is likely that many stakeholders have not identified the impact of these changes, and given the short timeline, which has run over the Christmas holiday period, it is probable they have not fully engaged with the proposals.
- We would invest some time into raising awareness and actively reaching out to stakeholders to solicit feedback on the Draft Comment Letter.
Outreach
15Staff believe that given this is a narrow scope amendment, albeit with the potential for significant impact on the financial statements, a proportionate response is to raise general awareness of the IASB proposals and our Draft Comment Letter as well as undertaking additional targeted outreach with potentially affected stakeholders, including preparers and users.
UK stakeholders
16We have already reached out to a number of accounting firms and have either spoken to, or expect to speak with, most in the coming weeks.
17We have also reached out to potentially affected stakeholders, including preparers and users, who we believe could have an interest in this topic.
18We believe that the publication of the draft comment letter will provide an opportunity to raise specific concerns with stakeholders directly.
International stakeholders
19As noted, we are already in touch with the IASB's project team but we do not propose any joint outreach as it would be disproportionate to the size of the amendment itself.
20Also as noted, we are already discussing this issue with the EFRAG's project team and plan to continue sharing views.
21Once the Draft Comment Letter is published, we will reach out to staff of the Accounting Standards Board of Canada (AcSB), Australian Accounting Standards Board (AASB), and Malaysian Accounting Standards Board (MASB). This will allow us to understand their view of the requirements proposed in the ED and whether there are overlaps with issues we identify for UK entities.
Project closure
22It is intended that the Feedback Statement and Due Process Compliance Statement will be provided to the UKEB at the same meeting as the Final Comment Letter.
Project timeline
23The proposed high-level project timeline is as follows:
| Date | Milestones | |
|---|---|---|
| 21 Jan | Board meeting | Approve PIP and draft comment letter |
| 25 Jan | Publish draft comment letter | |
| 1 March | Deadline for responses to draft comment letter (more than 28 Days from publishing) | |
| 11 March | Circulate Final Comment Letter, Feedback Statement and Due Process Compliance Statement for Board Approval | |
| 18 March | Board meeting | Board Approval meeting for Final Comment Letter, Feedback Statement and Due Process Compliance Statement |
| 21 March | Submit Final Comment Letter to IASB |
APPENDIX 2 Draft Comment Letter
Dr Andreas Barckow Chairman International Accounting Standards Board 7 Westferry Circus Canary Wharf London E14 4HD
XX XXX 2022
Dear Dr Barckow
Invitation to Comment: Exposure Draft – Non-current Liabilities with Covenants
The UK Endorsement Board (UKEB) is responsible for endorsement and adoption of IFRS Accounting Standards for use in the UK and therefore is the UK's National Standard Setter for IFRS Accounting Standards. The UKEB also leads the UK's engagement with the IFRS Foundation (Foundation) on the development of new standards, amendments and interpretations. This letter is intended to contribute to the Foundation's due process. The views expressed by the UKEB in this letter are separate from, and will not necessarily affect the conclusions in, any endorsement and adoption assessment on new or amended International Accounting Standards undertaken by the UKEB.
There are currently approximately 1,500 entities with equity listed on the London Stock Exchange that prepare their financial statements in accordance with IFRS Accounting Standards 1. In addition, UK law allows unlisted companies the option to use IFRS Accounting Standards and approximately 14,000 such companies currently take up this option 2.
We welcome the opportunity to provide comment on the IASB's Exposure Draft Non-current Liabilities with Covenants (ED). To develop our draft response our work to-date has included in-house research and feedback received during stakeholder outreach. [Stakeholder consultation is ongoing and will be concluded before this draft comment letter is finalised.]
We agree that it is important that users of financial statements can clearly understand the potential for liabilities categorised as non-current to become current and additional information on this may be useful. We agree that the current requirement in IAS 1 Paragraph 72A regarding compliance with future specific conditions, introduced by the Classification of Liabilities as Current or Non-current (2020) Amendments, needs to be addressed. However, as you will note below, we have significant concerns about other elements of the ED proposals as they risk introducing new uncertainty and diversity in practice.
We also largely support the alternative view provided in the ED by IASB Board Members Mr Mackenzie and Dr Scott with regard to disclosure of non-current debt with covenants on the face of the financial statements. Particularly when they state that "this proposal contradicts the principle-based nature of IFRS Standards”. As they note Paragraph 55 of IAS 1 Presentation of Financial Statements already requires further disaggregation in the statement of financial position when it is relevant to an understanding of an entity's financial position. The proposed blanket approach risks simply introducing clutter.
We believe it is particularly important that any narrow scope amendments to the existing standard are clear and fit within the wider context of the standard itself. The ED proposals are intended to amend a previous amendment that had been referred to IFRIC before it was implemented. These proposals touch on a fundamental element of financial reporting, the distinction between current and non-current liabilities. We therefore recommend a more wholistic review of the underlying concerns to ensure the requirements achieve their intended outcome.
Pending that wholistic review, we suggest the IASB should make limited amendments at this stage specifically to redress the unintended consequences of the 2020 Amendments and introduce enhanced disclosure for significant conditions in loans. The IASB should then undertake the more wholistic approach to the question of current/non-current classification in the financial statements only if there is evidence that the current requirements are clearly failing to address concerns around classification.
If you have any questions about this response, please contact the project team at [email protected]
For signature
[Appendix]: Overarching concerns and Responses to Detailed Questions
Overarching Concerns
A1Before addressing the questions as asked in the “questions for respondents” we believe it is important to highlight some specific concerns with the wording of the proposed amendments. We are taking this unusual step as we believe it is important that these amendments clearly address the underlying issue and will not raise further unintended consequences.
Paragraph 72A
A2The original amendment to IAS 1 that introduced Paragraph 72A must be changed as indicated. The tentative IFRIC Agenda Decision took a view of the words that had the potential to create significant problems for preparers, and confusion for users of financial statements as was clearly outlined by many respondents to that decision. We agree that the elimination of the final two sentences of the paragraph must occur.
Paragraph 72B
A3The term “covenants”, is not a term defined in the accounting standards. In fact, the amendments, in Paragraph 72B, refer to “specified conditions” (another undefined term), and then note that these are “often referred to as 'covenants”. It is possible that the IASB may have intended that these requirements apply to some limited set of terms in a loan agreement, however without further definition it is difficult to infer this limit. In English common law, as applied to contracts generally, the term covenant appears to simply mean any condition in a contract.
A4It is common for loan agreements to include a range of terms (including those specifically identified as covenants) that could cause it to become payable at shorter notice. This could include failure to meet certain financial metrics, changes in circumstances (ownership say), or missing a scheduled repayment.
A5This could lead to the “scope” of paragraph 72B (and subsequently 76ZA) capturing any condition in a loan that could cause it to become repayable within 12 months. A direct consequence of this could be that few non-current financial liabilities would not require presentation and disclosure in accordance with paragraph 76ZA.
A6We are not sure that this wide “scope” was expected by the users of financial statements, nor will it lead to a particularly useful outcome if the majority of non-current financial liabilities fall within this new presentation and require additional disclosure.
Paragraph 72B(a)
A7We agree that if an entity fails to comply with a specified condition at the end of the reporting period, which are only assessed after the reporting period (say once audited financial statements are produced) it should still be treated as being in breach at the end of that reporting period. However, we suggest that this fits better into Paragraph 74.
Paragraph 72B(b)
A8This paragraph seems to suggest that specific conditions that relate to future circumstances will never cause a liability to be classified as current (subject to Paragraph 72C(b) discussed below). The statement that “specified conditions with which an entity must comply within twelve months after the reporting period ... have no effect on the classification of a liability as current or non-current” appears too prescriptive and may imply that even conditions that are inevitably going to be breached would not cause a liability to be classified as current.
A9We disagree with this position and believe that there must be a threshold where the likelihood of breaching a specific condition in the next 12 months becomes so high and obvious that a liability should be recognised as current in anticipation of the breach. We think that this interpretation is consistent with the intent of the amended paragraph 72A that "An entity's right to defer settlement of a liability for at least twelve months after the reporting period must have substance” (emphasis added).
A10While we understand that determining and articulating an appropriate threshold is difficult, we must conclude either:
- The intention is that the expected breach of a future specific condition could never lead to a liability being classified as current, we do not support this view.
- The intention is that there are circumstances where the expected breach of a future specific condition could lead to the liability being classified as current, then some guidance on the threshold should be articulated.
Paragraph 72C(b)
A11We believe that this paragraph has significant potential to introduce unintended consequences and diversity in practice. The paragraph effectively states that a liability should be classified as current if its repayment could be triggered by the occurrence, or non-occurrence, of uncertain future events or outcomes that “are unaffected by the entities future actions”. (emphasis added)
A12Conditions that are outside of the ability of the borrower to affect do not convey a right to defer settlement and are therefore classified as current. While we agree with the concept, the construction of the sentence, coupled with the use of the term “unaffected” seem to create a high hurdle for what would be recognised as a current liability.
A13There are few outcomes that cannot in some way be affected (and hence would be not “unaffected”) by the entity's future actions. Take the example provided in the paragraph itself, a financial guarantee. There are a range of things an entity could presumably do to "affect” the outcome of a guarantee, including providing funds to enhance the other party's liquidity position, taking legal action, etc. Each may affect the outcome of the guarantee.
A14We do not believe the intention of the IASB is to create such a high hurdle for recognition as a current liability.
Paragraph 76ZA
A15We are supportive of the alternative view provided by IASB Board Members Mr Mackenzie and Dr Scott with regard to presentation and disclosure.
A16Primarily, we agree with Mr Mackenzie and Dr Scott when they state that “this proposal contradicts the principle-based nature of IFRS Standards... The proposed presentation requirement does not represent a compelling case to forgo a principle-based approach. Under a principle-based approach, to provide the most relevant information to users of financial statements, an entity would apply principles to prioritise the information presented in the statement of financial position relative to disclosure in the notes”.
A17As they note Paragraph 55 of IAS 1 Presentation of Financial Statements already requires further disaggregation in the statement of financial position when it is relevant to an understanding of an entity's financial position. The aggregation and disaggregation of information in the statement of financial position that is most relevant to users of financial statements will inevitably vary across entities. The current principles for disaggregation in IAS 1, and the expected improved principles for disaggregation proposed in the Primary Financial Statements project, should govern disaggregation in all of the financial statements.
A18We also believe, as the requirements are currently worded, few non-current financial liabilities would be deemed to be outside this presentation requirement, adding clutter to the statement of financial position.
Responses to Detailed Questions
Question 1 - Classification and disclosure (paragraphs 72B and 76ZA(b))
The Board proposes to require that, for the purposes of applying paragraph 69(d) of IAS 1, specified conditions with which an entity must comply within twelve months after the reporting period have no effect on whether an entity has, at the end of the reporting period, a right to defer settlement of a liability for at least twelve months after the reporting period. Such conditions would therefore have no effect on the classification of a liability as current or non-current. Instead, when an entity classifies a liability subject to such conditions as non-current, it would be required to disclose information in the notes that enables users of financial statements to assess the risk that the liability could become repayable within twelve months, including:
- the conditions (including, for example, their nature and the date on which the entity must comply with them);
- whether the entity would have complied with the conditions based on its circumstances at the end of the reporting period; and
- whether and how the entity expects to comply with the conditions after the end of the reporting period.
Paragraphs BC15–BC17 and BC23–BC26 of the Basis for Conclusions explain the Board's rationale for this proposal.
Do you agree with this proposal? Why or why not? If you disagree with the proposal, please explain what you suggest instead and why.
A19As noted at paragraphs A3 – A6 we believe that paragraph 72B may capture conditions that were not intended by the amendments.
A20As noted at paragraph A7 we agree 72B(a) is useful, but suggest it fits better into paragraph 74.
A21As noted at paragraphs A8 – A9 we are concerned that 72B(b) appears too prescriptive and may imply that even conditions that are inevitably going to be breached would not cause a liability to be classified as current.
A22That being said, we support additional disclosure which “enables users of financial statements to assess the risk that [a non-current liability subject to specific conditions] could become repayable within twelve months”. We believe that the disclosures at 76ZA(b) are appropriate and could be introduced on a standalone basis.
Question 2 Presentation (paragraph 76ZA(a))
The Board proposes to require an entity to present separately, in its statement of financial position, liabilities classified as non-current for which the entity's right to defer settlement for at least twelve months after the reporting period is subject to compliance with specified conditions within twelve months after the reporting period.
Paragraphs BC21–BC22 of the Basis for Conclusions explain the Board's rationale for this proposal.
Do you agree with this proposal? Why or why not? If you disagree with the proposal, do you agree with either alternative considered by the Board (see paragraph BC22)? Please explain what you suggest instead and why.
A23As noted at paragraphs A14 – A17 we do not support separate presentation on the face of the statement of financial position. Though we agree that it would be useful for users to be able to understand that some liabilities classified as non-current could, in certain circumstances, be required to be paid earlier, we do not believe that the amendments as proposed are clear enough to allow for a meaningful distinction to be made and understood.
A24First, as already noted, we believe the current requirements of IAS 1 Paragraph 72B throw such a wide net that few items would not be captured by this new classification. Meaning that the distinction may well be meaningless.
A25Second, we support the alternative view provided in the ED that a blanket requirement for separate disclosure on the face of the financial statements is not consistent with a principle-based approach to financial accounting.
Question 3 - Other aspects of the proposals
The Board proposes to:
- clarify circumstances in which an entity does not have a right to defer settlement of a liability for at least twelve months after the reporting period for the purposes of applying paragraph 69(d) of IAS 1 (paragraph 72C);
- require an entity to apply the amendments retrospectively in accordance with IAS 8 Accounting Policies, Changes in Accounting Estimates and Errors, with earlier application permitted (paragraph 139V); and
- defer the effective date of the amendments to IAS 1, Classification of Liabilities as Current or Non-current, to annual reporting periods beginning on or after a date to be decided after exposure, but no earlier than 1 January 2024 (paragraph 139U). Paragraphs BC18–BC20 and BC30–BC32 of the Basis for Conclusions explain the Board's rationale for these proposals.
Do you agree with these proposals? Why or why not? If you disagree with any of the proposals, please explain what you suggest instead and why.
A26As noted at paragraphs A10 – A13 we have significant concerns about the application of 72C(b).
A27We believe that retrospective application of any amendments would be appropriate.
A28We agree that the effective date of IAS 1, Classification of Liabilities as Current or Non-current should be deferred to no earlier than 1 January 2024, and subject to finalisation of these proposals, particularly with regard to paragraph 72A.
[Annex 1]: Questions for the Invitation to Comment
1Do you agree with the views expressed in this draft comment letter? If not please explain why.
2Can you provide further examples of the issues discussed in this letter that we may share with IASB?
A link to the Exposure Draft can be found here.