3.0 Due Process Handbook
Project Type: UKEB Set-up Project Scope: N/A
Executive Summary
Purpose of the paper
This paper presents a revised draft of the consolidated version of UKEB's Due Process Handbook (the “Handbook”) for Board approval to issue it for stakeholder consultation (subject to amendments suggested by the Board at this meeting). A timeline for the publication and finalisation of the Handbook is included.
Summary of the Issue
The Handbook will set out the due process requirements the Board will apply to its activities to enable it to uphold its guiding principles of accountability, independence, transparency and thought leadership when fulfilling its statutory functions. A clearly set out due process ensures that the UKEB's views are based on the evidence gathered over the course of its activities. It also contributes to maintaining accountability and transparency to stakeholders throughout.
The appendices to this paper include: a current draft of the Handbook (clean version) (Agenda paper 3 Appendix 1); a tracked version (Agenda paper 3 Appendix 2); a summary of comments from Board members and responses (Agenda paper 3 Appendix 3); and the proposed questions for public consultation (Agenda Paper 3 Appendix 4).
Decisions for the Board
Board members are asked:
- For comments on the form and content of the consolidated draft of the Handbook; and
- Subject to any comments made at the meeting, whether they are content for the Handbook to be issued for public consultation.
Recommendation
We recommend that, subject to the amendments or additions, the Board approves the Handbook for public consultation.
Appendices
Appendix 1 [Draft] Due Process Handbook—full consolidated (clean) version Appendix 2 [Draft] Due Process Handbook—full consolidated (tracked) version Appendix 3 Summary of comments from Board members and responses Appendix 4 Proposed questions for public consultation
Purpose
1At the November 2021 Board meeting, the Board reviewed and provided comments on a consolidated version of the draft of the UKEB's Due Process Handbook (the "draft Handbook"). At the December 2021 meeting, the Board provided comments on four sweep issues derived from the comments received. The Secretariat addressed these comments in the revised draft version of the Handbook (see Appendix 1).
2This paper asks for approval to issue the revised draft Handbook for public consultation. For this purpose, we are providing separate papers for:
- A [Draft] Due Process Handbook—clean version (Agenda paper 3: Appendix 1);
- A [Draft] Due Process Handbook—tracked version (Agenda paper 3: Appendix 2);
- A Summary of comments from Board members at the December 2021 meeting and responses (Agenda paper 3: Appendix 3); and
- Proposed questions for public consultation (Agenda paper 3: Appendix 4).
Next steps and timeline
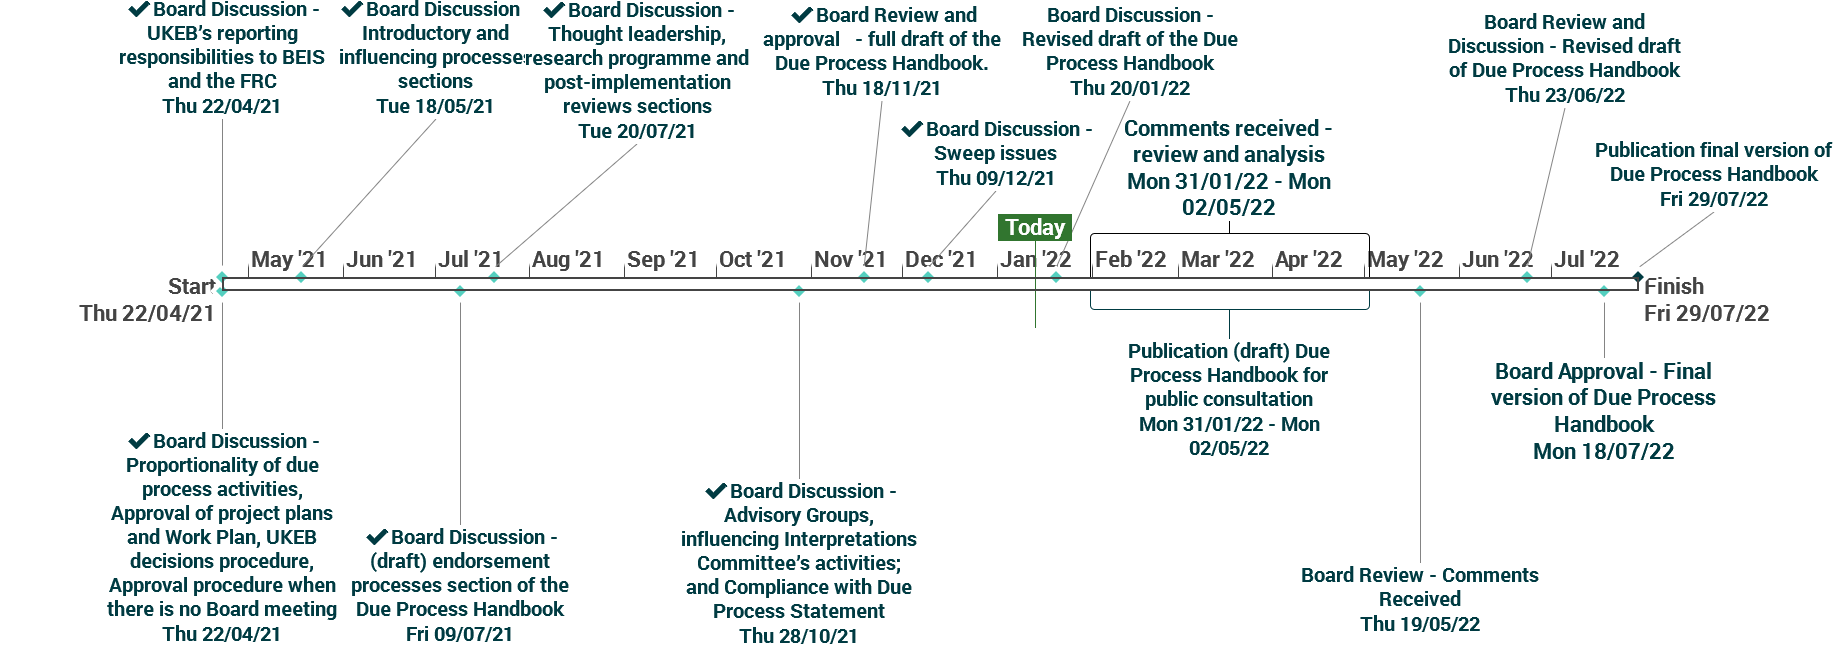
3Subject to amendments or additions required by the Board, our plan for the publication of the draft Handbook for public consultation and subsequent finalisation is set out in the table below and diagram in the next page.
| Date | At a public Board meeting: |
|---|---|
| 20 January 2022 | Board discussion of revised draft of the Handbook (this meeting) |
| Public consultation period | 31 January 2022–02 May 2022 [~90 days] |
| January–May 2022 | Comments received – review and analysis (UKEB Secretariat) |
| 19 May 2022 | Board review of comments received |
| 23 June 2022 | Board review and discussion of revised draft of Due Process Handbook |
| 18 July 2022 | Board approval of final version of Due Process Handbook |
| 29 July 2022 | Publication of final Due Process Handbook |
Question for the Board
Does the Board agree that, subject to suggestions by the Board at this meeting, the [draft] Due Process Handbook can be published for consultation?
Due Process Handbook Plan - Upcoming Tasks
High Level Plan
UK Endorsement Board
[Draft] Due Process Handbook
January 2022
- Executive Summary
- Purpose
- Next steps and timeline
- Due Process Handbook Plan - Upcoming Tasks
- [Draft] Due Process Handbook
- Appendices
- 1. Introduction
- 2. Statutory functions of the UKEB
- 3. Terms of Reference and Guiding Principles
- 4. Governance Activities
- 5. Influencing process
- 6. Endorsement process
- 7. Thought leadership and research programme
- Objectives of thought leadership
- Leading the UK debate
- Participating proactively in the development of global standards
- Representing UK views in international fora or in media with the aim of influencing debate
- Engaging with other bodies in other jurisdictions
- Research programme
- Milestones
- Identification of issues for research
- Project Initiation Plan (mandatory)
- Desk-based research
- Outreach activities
- Approval of a research document (mandatory)
- Publication (mandatory)
- Project closure
- 8. Post-implementation reviews
- 9. Advisory Groups
- 10. Influencing the work of the IFRS Interpretations Committee
- II Due Process Compliance Statement
- II Due Process Compliance Statement
- Appendix A—Relationship between Statutory Instruments (SI) and other governance documents for the Endorsement Board
- Appendix B—[Draft] Terms of Reference outline for advisory groups
- 1 Introduction
- 2 Statutory functions of the UKEB
- 3 Terms of Reference and Guiding Principles
- 4 Governance Mandatory Due Process-Activities
- Quorum of attendance and decision-making
- Voting process for endorsement decisions
- Voting process for non-endorsement decisions
- Transparency of meetings and stakeholder observers
- Minutes from Board Meetings
- UKEB Secretariat papers
- Consultation with stakeholders
- Keeping stakeholders informed
- Keeping stakeholders informed
- 5 Influencing process
- 6 Endorsement process
- 7. Thought leadership and research programme
- Research programme
- Objective
- Main outputs
- Milestones
- Identification of issues for research
- Project Initiation Plan (mandatory)
- Desk-based research
- Outreach activities
- Approval of a research document (mandatory)
- Publication (mandatory)
- Discussion Papers
- Research Papers and Requests for Information
- Project closure
- Feedback Statement (mandatory required when issuing a Discussion Paper)
- Comment Letter Summary required when issuing a Research Paper or a Request for Information
- Due Process Compliance Statement (mandatory required for a Discussion paper)
- 8. Post-implementation reviews
- Introduction
- Influencing IASB Post-implementation reviews
- Processes for a UKEB Post-implementation Review
- Desk-based research
- Initial consultation
- Publication of a Request for Information (mandatory)
- Second phase of a UKEB post-implementation review
- Publication of a Request for Information (mandatory)
- Second phase of a UKEB post-implementation review
- Outreach activities
- Project closure for a UKEB Post-implementation review
- Due Process Compliance Statement (mandatory)
- 9 Advisory Groups
- 10 Influencing the work of the IFRS Interpretations Committee
- Introduction
- Supporting the work of the IFRS Interpretations Committee
- Monitoring IFRS Interpretations Committee work
- Influencing proposals for amendments or for Draft IFRIC Interpretations
- Considering whether to respond to a tentative agenda decision
- Project milestones for tentative agenda decisions
- Informing the IFRS Interpretations Committee of significant issues raised by UK stakeholders
- II Due Process Compliance Statement
- Appendix A—Relationship between Statutory Instruments (SI) and other governance documents for the Endorsement Board
- Appendix B—IASB’s and IFRS Interpretations Committee’s consultation documents
- Appendix B [Draft] Terms of Reference outline for advisory groups
- [Draft] Due Process Handbook—
- Proposed questions for public consultation
Appendices
Appendix A Relationship between Statutory Instruments and other governance documents for the UK Endorsement Board Appendix B: Terms of Reference outline for advisory groups
1. Introduction
1.1The Due Process Handbook (Handbook) sets out the due process that the UK Endorsement Board (UKEB) 1 follows in assessing the appropriateness of international accounting standards 2 for use in the UK. International accounting standards are developed and issued by the International Accounting Standards Board (IASB). In doing so, it describes the due process that the UKEB follows in:
- influencing the development of international accounting standards and the other activities of the IASB and the IFRS Interpretations Committee; and
- endorsing and adopting international accounting standards.
1.2This Handbook also describes additional due process steps that the UKEB follows for:
- carrying out its thought leadership activities and developing its own research programme;
- performing its own post-implementation reviews;
- setting up and operation of advisory groups; and
- making sure it complies with the required due process steps in this Handbook.
1.3This Handbook guides the UKEB on performing the required due process steps and explains how stakeholders can participate in this process. These steps:
- specify the mandatory milestones to be achieved and other milestones (not labelled as "mandatory") that may be considered for most projects. These milestones build on the UKEB's statutory functions (as described in Chapter 2), its Terms of Reference and its guiding principles (as described in Chapter 3) and its Governance Activities (as described in Chapter 4); and
- identify other activities that can be undertaken to achieve the milestones set out in this Handbook. These activities should be proportionate to the technical issue(s) being addressed, including consideration of the project's significance for UK stakeholders and its complexity (i.e. nature or scope).
1.4The Secretary of State for the Department of Business, Energy and Industrial Strategy (BEIS) delegated the functions relating to influencing, endorsing and adopting international accounting standards for application in the UK to the UKEB in May 2021 3 . The Secretary of State maintains a regular review of the performance of the UKEB in exercising those functions. The UK Financial Reporting Council (FRC) oversees the effective governance of the UKEB and its adherence to the due processes set out in this Handbook. It also provides operational support. The FRC does not have the power to direct the UKEB in relation to the determination of its programme of work or the outcome of its technical decision-making 4 .
1.5This Handbook forms one of the key documents of the UKEB. A diagram of the relationship between these documents can be found in Appendix A.
2. Statutory functions of the UKEB
2.1The following statutory functions were delegated to the UKEB 5 , as follows:
Regulation 5 of SI 2019/685:
"(a) the adoption of international accounting standards for use within the United Kingdom, with a view to harmonising the financial information presented by the companies required by section 403(1) of the Companies Act 2006 to prepare their accounts in accordance with UK-adopted international accounting standards, in order to ensure-
- a high degree of transparency and international comparability of financial statements; and
- the efficient allocation of capital, including the smooth functioning of capital markets in the United Kingdom; and
(b) participating in and contributing to the development of a single set of international accounting standards."
2.2Regulation 8 of SI 2019/685 also requires consultation:
"Before adopting an international accounting standard under regulation 6, the Secretary of State must consult such persons as the Secretary of State considers to be representative of those with an interest in the quality and availability of accounts, including users and preparers of accounts.”
2.3Regulation 17 of SI 2019/685 also requires that the Board report to the Secretary of State on its activities:
"(1) The body must, at least once in each calendar year for which the delegation regulations are in force, make a report to the Secretary of State on-
- the discharge of the functions transferred to it, and
- such other matters as the Secretary of State may by regulations require.”
3. Terms of Reference and Guiding Principles
Terms of Reference
3.1The Terms of Reference (ToR) further elaborate on the UKEB's role and responsibilities as they relate to the statutory functions. The UKEB's key responsibilities include:
- Considering and deciding whether to endorse and adopt 7 new or amended international accounting standard for application in the UK 8 . This includes a formal endorsement criteria assessment which assesses the impact on UK entities.
- Influencing the development of IFRS. The UKEB will follow and contribute to debates on IASB's projects (as appropriate 9 ), consult with UK stakeholders to obtain their views, highlight any concerns to the IASB at different stages of their projects, including the development of the IASB's agenda, responding to its draft proposals and consultations and to its post-implementation reviews 10 .
- Deciding on the work plan for research and thought leadership activities and developing those activities to contribute to the development of financial reporting internationally, after public consultation on possible projects to be included 11 .
- Ensuring that there is an open and transparent due process including a public consultation process (as appropriate 12 ) with stakeholders on draft comment letters to the IASB, draft endorsement criteria assessments and other documents such as research discussion papers. This includes providing timely feedback to stakeholders on their contributions.
- Reporting to the FRC Board, in relation to the UKEB's effective operation, governance and adherence to the Due Process Handbook.
- Reporting to BEIS in relation to the performance of the UKEB's statutory functions.
3.2The ToR are set by the BEIS Secretary of State and adopted by the UK Endorsement Board.
Guiding Principles
3.3Paragraphs 4.1–4.5 in Section 4 of the ToR require the UKEB to act at all times in accordance with the guiding principles of:
- Accountability—includes consulting with UK stakeholders that are affected by financial reporting, undertaking activities and due process procedures in a timely manner and providing a rationale for the decisions it makes. The UKEB is accountable to:
- its stakeholders (i.e. users, preparers, academics, accounting firms, accounting bodies and regulators);
- its oversight body (the FRC) in relation to its effective operation, governance and adherence to the Due Process Handbook; and
- the Secretary of State for BEIS in relation to the performance of its statutory functions.
- Independence—to ensure that it acts in the UK's long term public good and that it is independent from other organisations or stakeholder groups, including the FRC and BEIS, in respect of its technical decision making.
- Transparency—to determine its technical decisions after having assessed the relevant evidence received and having followed its Due Process Handbook. To undertake its activities in a transparent manner so that stakeholders are aware of current projects and understand how decisions have been made (i.e. by making comment letters received publicly available on a timely basis).
- Thought leadership—to:
- lead and represent the UK on international accounting standards and reporting;
- represent UK views in international fora with the aim of influencing debate;
- engage with accounting and reporting and endorsement and adoption bodies in other jurisdictions, in order to improve influence and understand best practice; and
- pro-actively participate in the development of new global accounting standards for example by undertaking research.
3.4These guiding principles are embedded into the processes described in this Handbook.
4. Governance Activities
Quorum of attendance and decision-making
4.1Section 5 of the UKEB's ToR sets out, amongst other requirements, the quorum for the UKEB Board (thereafter 'Board') meetings. This requires that a minimum of sixty percent of the appointed members (including the UKEB Chair as an appointed member) must attend a meeting of the Board (ToR, paragraph 5.1).
Voting process for endorsement decisions
4.2A decision to adopt a standard or amendment to a standard or an IFRS Interpretations Committee's interpretation must be made at an UKEB public Board meeting by at least two-thirds of the Members, including the Chair as an appointed member (ToR, paragraph 5.2). However, decisions made at an UKEB public Board meeting are indicative only. These decisions must be formalised by circulation outside the meeting by a written vote (in paper or electronic form) and the vote constitutes proper evidence of the decisions of members of the Board (including the UKEB Chair as an appointed member). Each member of the Board has one vote.
4.3Following the conclusion of a final written vote, in relation to the decision in paragraph 4.2, the UKEB Chair shall make public the outcome of that vote within 3 working days. Publication of the results of the vote on a standard or part standard will, where the result is to adopt a standard in whole or in part, constitute the adoption of that standard by the UK Endorsement Board, on a date specified by the UK Endorsement Board (ToR, paragraph 5.3).
4.4Where the vote to adopt a standard or amendment or interpretation does not reach the required majority, the UKEB Chair may, after consultation with external parties including BEIS, choose to ask the Board to return to the vote. This may include asking the Board to vote on part of the standard, amendment or interpretation if it appears that this will have the required support. A subsequent decision to adopt the part standard or part amendment to a standard or part interpretation must be made by at least two-thirds of the Members (ToR, paragraph 5.4).
4.5Where a vote by the Board to adopt a standard, amendment, or interpretation, in whole or in part, has failed to reach the required majority and, in the opinion of the UKEB Chair, there is no prospect of such majority being reached, the UKEB Chair must provide a written explanation of circumstances to the Secretary of State within 10 working days of the failure to adopt. The Secretary of State may require further evidence. The Chair must inform members of the Board of any recommendations by the Secretary of State (ToR, paragraph 5.5).
Voting process for non-endorsement decisions
4.6Non-endorsement decisions such as approving a comment letter to be submitted to the IASB or a decision to approve the publication of a UKEB research outputs do not require a formal written vote by the Board. They require the support of a simple majority of the Board members present at the meeting, with approval given in a public meeting.
Transparency of meetings and stakeholder observers
4.7The UKEB's ToR set out the operating procedures that the UKEB applies in carrying out its responsibilities. Those procedures include the frequency and form of Board meetings (in Section 6 of the ToR), as well as rules for observers attending these meetings (in Section 7 of the ToR).
4.8The Board may hold meetings in person, by webcast, or by telephone or other similar means. In deciding the format of meeting, the UKEB Chair should take into consideration public access and attendance (ToR paragraph 6.2).
4.9Regular meetings of the Board are planned as far in advance as is practicable to help the UKEB Secretariat (thereafter 'Secretariat'), members of the Board, official observers (with speaking rights) of the Board, and stakeholders, prepare for those meetings. The meetings calendar is published on the UKEB website and is updated regularly.
4.10Meetings will usually be held in public and open to attendance by members of the public (as non-speaking observers). However, the Board may hold certain discussions in private or in the presence of invited observers with speaking rights only. For instance:
- Meetings held to discuss administrative issues and other non-technical matters (ToR paragraph 5.6); or,
- Education sessions held before public Board meetings, for example, to enable Board members to improve their understanding of new or complex proposals or standards or seek clarification about technical matters in staff papers.
4.11Only Board members and observers with speaking rights will have the right to speak at Board meetings. The UKEB Chair may invite others to attend meetings as advisors when specialised input is required. Such persons may be invited to speak at all or part of any meeting, as and when appropriate. (ToR, paragraph 7.2).
4.12Only public meetings are recorded and, whenever practicable, webcast live. Recordings of public meetings are made available on the UKEB website.
Minutes from Board Meetings
4.13Section 9 of the UKEB's ToR sets out the requirement to minute the meetings and any resolutions decided by the UKEB to keep stakeholders informed about the UKEB's activities. Minutes are a summary of the main tentative decisions reached at a Board meeting and/or main areas of Board discussion.
4.14The Secretary to the UKEB (i.e. the Operations Director, or their nominee) minutes the meetings and resolutions of the UKEB, including recording the names of those present and in attendance. (ToR paragraph 9.2)..
4.15The minutes for each Board meeting are circulated to all UKEB Members for approval and once approved are published and made available on the UKEB website as soon after the meeting as practicable and usually within 10 working days following the meeting (ToR paragraphs 9.2-9.3). The Secretariat is responsible for ensuring that the minutes reflect the Board's decisions at each meeting. The minutes serve also to inform interested parties about the progress made on technical projects in a timely manner.
UKEB Secretariat papers
4.16Section 8 of the UKEB's ToR sets out requirements for the notice of meetings and Secretariat papers.
4.17The Secretariat is responsible for developing papers with recommendations and supporting analysis of technical issues for consideration by the members of the Board.
4.18The objective of the papers is to provide enough information for members of the Board to make informed decisions on technical matters. In developing these papers, the Secretariat is expected to conduct research and to seek advice from members of the Board. However, recommendations ultimately reflect Secretariat's views, after consideration of the information obtained.
4.19The Board agenda and Secretariat papers for each public meeting are usually made available on the UKEB website no later than 5 working days, before they are scheduled for discussion at a Board meeting (ToR, paragraph 8.3). This is to allow Board members enough time to consider and assess the Secretariat's recommendations. It is the responsibility of the UKEB members to assess whether they have sufficient information and time to be able to make decisions based on Secretariat's recommendations. Secretariat papers may have to be distributed closer to the meeting date, in exceptional circumstances only, and with the prior approval of the UKEB Chair. For example, if an urgent issue has arisen.
4.20Also, only in exceptional circumstances, and taking into consideration the Guiding Principles, the UKEB Chair may, at their absolute discretion, decide that all or part of certain Secretariat papers used for discussion by the Board at public meetings should not be made publicly available (ToR, paragraph 8.4). This may be, for example, if releasing that information could breach UK law, commercial confidentiality or prejudice the conduct of public affairs. However, such circumstances are expected to be rare.
4.21Secretariat papers used for discussion by the Board at private Board meetings are not made publicly available.
4.22The Secretariat may supplement papers orally at a Board meeting, for example, to provide an update on recent events.
Consultation with stakeholders
4.23The UKEB operates transparently and gives fair consideration to the issues raised by UK stakeholders, and influences early in the development of international accounting standards by conducting timely outreach activities and regular consultations with stakeholders (ToR paragraph 3.2(d)(ii)). This ensures stakeholders' concerns are heard and builds robust and evidence-based recommendations in line with the UKEB's influencing strategy. It also undertakes consultation with stakeholders relating to the endorsement and adoption of IASB standards or amendments and for its thought leadership and research programme.
4.24The UKEB consults with stakeholders that represent different communities, (i.e. users, preparers, academics, accounting firms, accounting bodies and regulators) to gather their inputs, views, opinions and feedback on specific projects or technical matters.
4.25The UKEB consults stakeholders:
- on IASB's proposals for comment on proposals for new or amended international accounting standards (refer to Section 5—Influencing process) or on the IASB's research work (i.e. Discussion papers, Research papers or Requests for Information);
- before endorsing and adopting a new or amended international accounting standard in the UK 13 (refer to Section 6 – Endorsement process);
- on UKEB's research work in line with its guiding principle of accountability and thought leadership (refer to Section 7—Thought Leadership and the Research programme);
- on IASB's requests for information: for example, those issued for post-implementation reviews (refer to Section 8—Post-implementation reviews);
- on UKEB's post-implementation review work (refer to Section 8—sub-section on "Processes for a UKEB Post-implementation review"); and
- on tentative agenda decisions or Draft IFRIC Interpretations issued by the IFRS Interpretations Committee (refer to Section 10—Influencing the IFRS Interpretations Committee's activities).
Keeping stakeholders informed
4.26As a part of the guiding principle of transparency (ToR paragraph 4.4), the UKEB is committed to keeping its stakeholders and the general public informed about its activities. The principal means of communication between the UKEB and its stakeholders is through public meetings on technical issues, and the posting of relevant information and documents on the UKEB website.
4.27In particular, the UKEB publishes on its website:
- its work plan, its meeting schedules and agenda;
- its progress on individual projects or Board's deliberations and compliance with due process by posting:
- public Secretariat papers discussed at public Board meetings;
- minutes of the Board's main decisions at its meetings after approval by the Board (see ToR, paragraph 9.2); and
- recordings of public Board meetings; and
- media and information releases relating to its activities;
4.28All public materials, including those related to the UKEB due process, are freely available on the website.
5. Influencing process
5.1Technical work plan The UKEB's due process influencing process begins with a technical work plan. This plan comprises the set of technical projects the UKEB manages.
5.2The UKEB's technical work plan includes:
- technical issues identified by the IASB and by its IFRS Interpretations Committee 14 ; and
- other technical issues (refer to Section 7—Thought Leadership and the Research programme).
5.3Technical issues identified by the IASB are added to the UKEB's technical work plan. As a starting point, the UKEB assumes that where a technical issue is significant enough to be added to the IASB's technical work plan, similar issues exist in the UK.
5.4The UKEB's technical work plan is updated regularly to reflect estimated project timelines based on recent Board's decisions. It is presented for approval at the Board private meetings and once approved, is uploaded onto the UKEB website.
Prioritising technical projects
5.5In prioritising individual projects and allocating resources to them, the level of activities should be proportionate to the issue being addressed. To help assess the issue, the Board considers various factors, including:
- the importance of the issue to UK stakeholders (i.e. users, preparers, academics, accounting firms, accounting bodies and regulators, and others interested in financial reporting);
- the effect an issue has or is expected to have on UK entities using UK-adopted international accounting standards, including both the number of entities affected and the size of the effect;
- interactions with other current or proposed projects on the work plan;
- the urgency of the issue; and
- the availability of staff resources.
5.6The assessment is not limited to using the IASB's assessment of the potential impact of a project as the UKEB's remit is different. The IASB considers the potential impact on many jurisdictions whereas the UKEB is assessing the potential impact from a UK perspective. This may mean that in the UK we allocate a different significance for a project when compared with the IASB. For example, where UK entities do not undertake the types of transactions addressed in an IASB project, the project would be allocated a lower significance and a reduced number of outreach activities would be planned.
Overview of the influencing process
5.7The milestones expected to be achieved for influencing projects are:
- Project initiation plan (mandatory).
- Desk-based research.
- Outreach activities (including reduced mandatory outreach activities in exceptional circumstances).
- Draft comment letter.
- Final comment letter (mandatory).
- Project closure, including Feedback Statement (mandatory) and Due Process Compliance Statement (mandatory).
5.8The mandatory milestones will ensure that the UKEB adheres to its guiding principles of accountability, independence and transparency. Other milestones (those not labelled as "mandatory") may be considered for most projects and included in the project plan proportionate to the nature of the issue and the expected timeline.
5.9The activities undertaken to achieve the milestones in paragraph 5.7 should be proportionate to the technical issue(s) being addressed and will depend on its significance for UK stakeholders and on its complexity (i.e. nature or scope). Examples where the proportionate approach could apply are:
- it is expected that for 'major' projects or for complex projects with major amendments, the activities undertaken would be far more extensive than for other 'minor' projects (i.e. amendments that meet the IASB's criteria for annual improvements or for narrow-scope amendments 15 ), where some activities such as desk-based research or outreach activities may be somewhat more limited.
Footnotes
- interactions with other current or proposed projects on the work plan;
- the urgency of the issue; and
- the availability of staff resources.
5.6 The assessment is not limited to using the IASB's assessment of the potential impact of a project as the UKEB's remit is different. The IASB considers the potential impact on many jurisdictions whereas the UKEB is assessing the potential impact from a UK perspective. This may mean that in the UK we allocate a different significance for a project when compared with the IASB. For example, where UK entities do not undertake the types of transactions addressed in an IASB project, the project would be allocated a lower significance and a reduced number of outreach activities would be planned.
Overview of the influencing process
5.7 The milestones expected to be achieved for influencing projects are:
- Project initiation plan (mandatory).
- Desk-based research.
- Outreach activities (including reduced mandatory outreach activities in exceptional circumstances).
- Draft comment letter.
- Final comment letter (mandatory).
- Project closure, including Feedback Statement (mandatory) and Due Process Compliance Statement (mandatory).
5.8 The mandatory milestones will ensure that the UKEB adheres to its guiding principles of accountability, independence and transparency. Other milestones (those not labelled as "mandatory") may be considered for most projects and included in the project plan proportionate to the nature of the issue and the expected timeline.
5.9 The activities undertaken to achieve the milestones in paragraph 5.7 should be proportionate to the technical issue(s) being addressed and will depend on its significance for UK stakeholders and on its complexity (i.e. nature or scope). Examples where the proportionate approach could apply are:
- it is expected that for 'major' projects or for complex projects with major amendments, the activities undertaken would be far more extensive than for other 'minor' projects (i.e. amendments that meet the IASB's criteria for annual improvements or for narrow-scope amendments15), where some activities such as desk-based research or outreach activities may be somewhat more limited.
- The public consultation for proposed annual improvements or for a narrow-scope amendment may be limited to an issues paper on the UKEB website, with an associated news alert.
- The consultation for a tentative agenda decision, may be undertaken only with a selected group or number of stakeholders.
Project Initiation Plan (mandatory)
5.10 For a technical project to be incorporated into the UKEB's work plan, a “Project Initiation Plan" (PIP) is prepared for approval by the Board.
5.11 The objective of the PIP is to assess the potential impact and scale of the proposals being addressed as part of the project and, consequently, the level of analysis and outreach that should be undertaken.
5.12 The PIP outlines the approach to the project, including:
- a description of the project objective and proposed timeline;
- a description of mandatory milestones and planned activities that will be undertaken to achieve those milestones;
- available and required resources for the project (including whether those resources are already allowed for in the annual plan or budget);
- expected output (i.e. draft/final comment letter to the IASB); and
- if applicable, the factors considered to justify departing from the standard consultation period for a Draft comment letter (refer to paragraph 5.27 below).
5.13 A PIP must be prepared for each project and discussed, revised as directed and approved by the Board in a public meeting. For projects that meet the IASB's criteria for annual improvements or for narrow-scope amendments, a PIP is prepared but is tabled for noting, thereby giving Board members the opportunity to discuss it. The Board can then determine whether any individual annual improvement or narrow-scope amendment included in a group being considered together should be discussed as a separate agenda item.
5.14 If changes arise subsequent to commencement of a project, for example, as a result of the input received from outreach activities, the project PIP can be updated to address those changes.
5.15 The project plan included in the PIP forms the basis for compliance with the due process steps set out in this Handbook (refer to paragraph 11.2(c) in this Handbook).
Desk-based research
5.16 Desk-based research is undertaken to assist with the assessment of proportionality and to gather evidence on the issue. This will usually include a review of the IASB's previous work on this issue. It may also include, for example, a review of literature, academic papers, financial statements or of past papers or reports (by other national standard-setters or by other stakeholders (i.e. users, preparers, academics, accounting firms, accounting bodies and regulators). Additionally, the UKEB could liaise with national standard-setters who have carried out influencing activities or are in the process of performing such activities on the same (or related) project.
Narrow-scope amendments do not meet the criteria for annual improvements but meet the criteria in paragraph 5.16 in the same Handbook and are considered 'narrow' in scope.
Outreach activities
5.17 The UKEB promotes awareness and generally responds to all IASB projects that are relevant to the UK.
5.18 Outreach activities will be proportionate to the significance and complexity (i.e. nature or scope) of the project (i.e. relevant standard or amendment).
5.19 The amount of outreach to be undertaken, together with the rationale, will be highlighted in the PIP.
Reduced mandatory outreach activities in exceptional circumstances
5.20 In exceptional circumstances, e.g. for an urgent narrow-scope amendment issued by the IASB where it shortens the comment period for an Exposure Draft from its usual 120 days, the UKEB will have limited time to consult.
5.21 Therefore, the Board may decide against issuing a draft comment letter or issue a draft comment letter with a comment period shorter than 30 days, and/or determine that the minimum outreach it undertakes will be to directly consult with a representative group of stakeholders. This will usually be with members of the UKEB's standing and/or ad-hoc advisory groups.
Outreach activities in normal circumstances
5.22 In normal circumstances the outreach that the UKEB undertakes might include:
- convening and obtaining input from standing advisory groups and/or ad-hoc advisory groups16;
- meetings and/or interviews with stakeholders (i.e. users, preparers, academics, accounting firms, accounting bodies and regulators);
- undertaking fieldwork (see below);
- consultation on draft comment letter (see below);
- the commissioning of external economic studies (i.e. data gathering and analysis conducted by external consultants to assess aspects of the economic impact of a standard on the UK); and
- arranging informal meetings with IASB members and/or staff and their participation in UK outreach events.
5.23 Liaison with the IASB when undertaking outreach on an IASB due process document, e.g. an Exposure Draft, can enhance the efficiency and effectiveness of the UKEB's work. Examples of benefits could include:
- enhanced credibility and attraction of outreach events if conducted jointly with the IASB; and
- greater insight into technical issues.
5.24 The UKEB will maintain full transparency about its interaction with the IASB and other stakeholders. Steps will include:
- maintaining a public register of meetings between senior staff and Board members of the IASB and of the UKEB; and
- being transparent about the sources of information used in UKEB material.
Fieldwork
5.25 Fieldwork can be undertaken in a variety of ways and could include, but is not limited to:
- Surveys—organised to gather data, information, and facts on a specific subject;
- Field tests—include testing the application of technical proposals as if they were already in effect, in order to assess the understandability of the requirements and/or the resulting implementation issues. Field tests can be based on, for example:
- the completion of case studies;
- asking participants to assess how a technical proposal would apply to actual transactions;
- asking users how they process information; or
- assessing how accounting systems may be affected;
- Workshops or interviews—bring interested parties together and allow for in-depth analysis (for example to assess how technical proposals might be interpreted or applied) or to ensure the correct understanding of the results of a survey or field test.
- Public events—meetings with a larger number of interested stakeholders and organisations to listen to, and exchange views on, specific topics. These could take the form of roundtables, discussion forums, webinars and webcasts. These public events provide stakeholders with the opportunity to better understand and present their views on developing proposals.
Draft comment letter
5.27 A draft comment letter, explaining the UKEB's preliminary response to an IASB's or an IFRS Interpretations Committee's consultation document is made available for public consultation on the UKEB website once approved by the Board. This letter is normally preceded or accompanied by an Invitation to Comment that sets out the matters on which feedback is sought. The standard consultation period for a Draft Comment letter is not less than 30 days unless there are exceptional circumstances (see paragraphs 5.20–5.21).
Final comment letter (mandatory)
5.28 The UKEB considers the stakeholder feedback received on the draft comment letter or from other outreach undertaken and uses this input to issue a final version of the comment letter to the IASB. The final comment letter is submitted to the IASB and posted on the UKEB website. The comment letters submitted to the UKEB (where the respondent has not requested confidentiality) are also posted on the UKEB website.
Project closure
Feedback statements (mandatory)
5.29 Input and feedback received on a draft comment letter (and any other input and feedback derived from other outreach activities) is recorded, assessed, the evidence evaluated, and reported in a Feedback Statement.
5.30 The purpose of a Feedback Statement is to inform stakeholders how the UKEB has responded to, or has addressed, the main comments or views received from stakeholders who participated in outreach events or submitted comment letters on a specific project.
5.31 A Feedback Statement demonstrates the UKEB's adherence to its overarching guiding principles as follows:
- Accountability to stakeholders who submitted comment letters and/or participated in outreach, to the FRC as oversight body, and others, that the UKEB is taking account of stakeholders' views and fulfilling its due process obligations.
- Transparency about how the main comments or views have been addressed.
- Independence in that the UKEB acts in the UK's long term public good and is independent in its assessment of comments or views received from stakeholders and in determining the content of its final comment letter to the IASB.
5.32 Although the objective of all Feedback Statements is the same, the form and content will be proportionate to the objective of the underlying document, e.g. Discussion Papers have different objectives from Exposure Drafts. In general, a Feedback Statement includes the following content:
- an objective;
- a brief description of technical IASB's proposal(s), i.e. summary background;
- an explanation of the main feedback received through comment letters or other fieldwork or outreach activities;
- a description of the UKEB's response (i.e. how comments or views received from stakeholders have been addressed); and
- a summary of the sources of stakeholder comments, e.g. from individual stakeholder meetings, formal responses to draft comment letters or via other outreach events.
5.33 The Board discusses and provides comments on a draft Feedback Statement and approves the final Feedback Statement for publication.
5.34 A Feedback Statement is published on the UKEB website, usually at the same time as the final comment letter is submitted to the IASB. In exceptional circumstances, e.g. to meet a curtailed comment deadline for an urgent project, it may not be possible to present a Feedback Statement at the same meeting as the approval of the final comment letter. In this situation, it is presented for Board approval as soon as practicable.
Due Process Compliance Statement (mandatory)
5.35 The Secretariat summarises the due process activities undertaken in a closing control report called “Due Process Compliance Statement". For a description and content of this Statement refer to paragraph 11.2 in Section 11 of this Handbook.
6. Endorsement process
UK Statutory requirements for endorsement and adoption
6.1 New or amended international accounting standards issued by the International Accounting Standards Board (IASB) are not part of UK-adopted international accounting standards until the UKEB has endorsed and adopted those standards17.
6.2 The primary objective of endorsing and adopting international accounting standards for use in the UK as set out in SI 2019/68518 is to harmonise the financial information presented by relevant companies to ensure:
- a high degree of transparency and international comparability of financial statements; and
- the efficient allocation of capital, including the smooth functioning of capital markets in the United Kingdom.
6.3 The regulatory power embodied in the UKEB's endorsement and adoption function lends weight and authority to the UKEB's influencing activity.
6.4 The UKEB adopts international accounting standards for use within the UK, in accordance with regulations 6–9 in SI 2019/685 (these Regulations are described below).
6.5 Regulation 7—requires that an international accounting standard only be adopted if:
- "the standard is not contrary to either of the following principles—
- an undertaking's accounts must give a true and fair view of the undertaking's assets, liabilities, financial position and profit or loss;
- consolidated accounts must give a true and fair view of the assets, liabilities, financial position and profit or loss of the undertakings included in the accounts taken as a whole, so far as concerns members of the undertaking;
- the use of the standard is likely to be conducive to the long term public good in the United Kingdom; and
- the standard meets the criteria of understandability, relevance, reliability and comparability required of the financial information needed for making economic decisions and assessing the stewardship of management.”
6.7 Regulation 6—permits the adoption of a standard in part only and/or to extend an option available as part of a standard. The Regulation states that this may occur "in exceptional circumstances”. Regulation 6(3)(b) indicates that the amended standard (i.e. the part-adopted standard) would need to meet the endorsement criteria set out in Regulation 7.
6.8 Regulation 9—sets out the requirement to publish a final decision on adopting a new or amended international accounting standard.
Overview of UKEB endorsement and adoption process
6.9 The UKEB applies its own process before it decides to endorse and adopt a new or amended international accounting standard. This process is to ensure the Board fulfils its statutory responsibility relating to endorsement and adoption of international accounting standards (described in paragraphs 6.2–6.8) for the endorsement and adoption of an IASB standard or amendment into UK-adopted international accounting standards. This process takes place after a new or amended standard has been issued by the IASB and before the standard is effective. This process is described below.
6.10 The milestones expected to be undertaken for endorsement and adoption projects are:
- Project initiation plan (mandatory).
- Desk-based research.
- Public consultation on a draft Endorsement Criteria Assessment (DECA) (mandatory).
- Outreach activities (including reduced mandatory outreach activities in exceptional circumstances).
- Project closure, including vote on adoption, including the following documents:
- Final Endorsement Criteria Assessment (ECA) (mandatory).
- Feedback Statement (mandatory).
- Due Process Compliance Statement (mandatory).
- Adoption Statement (mandatory).
- Publication of the documents set out in (e) (mandatory).
6.12 The activities undertaken to achieve the milestones in paragraph 6.10 should be proportionate to the technical issue(s) being addressed and will depend on its significance for UK stakeholders and on its complexity (i.e. nature or scope). For example, it is expected that for 'major' projects or for complex projects with major amendments, the activities undertaken would be far more extensive than for other 'minor' projects (i.e. amendments that meet the IASB's criteria for annual improvements or for narrow-scope amendments), for which some activities (i.e. outreach activities) may be limited.
Project Initiation Plan (mandatory)
6.13 For a new or amended international accounting standard to be endorsed and adopted by the UKEB, a “Project Initiation Plan" (PIP) is prepared for approval by the Board.
6.14 The objective of the PIP is to assess the potential impact and scale of the new or amended standard and, consequently, the level of analysis and outreach that should be undertaken.
6.15 The PIP outlines the approach to the project, including:
- a description of the project objective and proposed timeline;
- a description of mandatory milestones and planned activities that will be undertaken to achieve those milestones;
- available and required resources for the project (including whether those resources are already allowed for in the annual plan or budget);
- expected output (i.e. draft/final Endorsement Criteria Assessment); and
- If applicable, the factors considered to justify departing from the standard consultation period for a draft Endorsement Criteria Assessment (refer to paragraph 6.24 below).
6.16 A PIP must be prepared for each project and discussed, revised as directed and approved by the Board in a public meeting. For projects that meet the IASB's criteria for annual improvements or for narrow scope amendments, a PIP is prepared but is tabled for noting, thereby giving Board members the opportunity to discuss it. The Board can then determine whether any individual annual improvement or narrow-scope amendment included in a group being considered together should be discussed as a separate agenda item.
6.17 If changes arise subsequent to commencement of a project, for example, as a result of the input received from outreach activities, the project PIP can be updated to address those changes
6.18 The project plan included in the PIP forms the basis for compliance with the due process steps set out in this Handbook (refer to paragraph 11.2(c) in this Handbook).
Desk-based research
6.19 Desk-based research is undertaken to assist with the assessment of proportionality and to gather evidence on the issue. This will usually include a review of the UKEB's earlier work on influencing activities and responses received, as well as IASB's previous work on this issue. It may also include, for example, a review of literature, academic papers, financial statements or of past papers or reports (by other national standard-setters or by other stakeholders (i.e. users, preparers, academics, accounting firms, accounting bodies and regulators) as well as liaising with national standard-setters who have endorsed or are in the process of endorsing the same new or amended standard.
Draft endorsement criteria assessment (DECA) (mandatory)
Content
6.20 The UKEB endorsement criteria is set out in paragraph 6.5 of this Handbook.
6.21 In general, a DECA considers and addresses the following:
- Introduction: legislative framework and approach to the assessment:
- Purpose of the DECA;
- Summary and explanation of legislative background to endorsement criteria; and
- Description of endorsement criteria (including text of criteria from SI 2019/685) and what is meant by each criterion;
- Rationale for the new or amended international accounting standard, i.e. summary background, context and objectives and main accounting requirements;
- Technical criteria assessment:
- whether the standard meets the criteria of relevance, reliability, comparability and understandability required of the financial information needed for making economic decisions and assessing the stewardship of management (SI 2019/685 Regulation 7(1)(c)); and
- whether the standard is not contrary to the principle that an entity's accounts must give a true and fair view (SI 2019/685 Regulation 7(1)(a)).
- Whether use of the new or amended standard is likely to be conducive to the long term public good in the UK (SI 2019/685 Regulation 7(1)(b)), including:
- whether the use of the standard is likely to improve the quality of financial reporting;
- the costs and benefits that are likely to result from the use of the standard; and
- whether the use of the standard is likely to have an adverse effect on the economy of the UK, including on economic growth.
6.23 A DECA is made available for public consultation on the UKEB website.
6.24 The standard consultation period is not less than 90 days unless there are exceptional circumstances (see paragraph 6.27). During this period, the Secretariat conduct outreach activities to gather input and feedback.
Outreach activities
6.25 Outreach activities will be proportionate to the significance and complexity (i.e. nature or scope) of the project (i.e. relevant standard or amendment) and may be undertaken throughout the endorsement assessment period.
6.26 The amount of outreach to be undertaken, together with the rationale, will be highlighted in the PIP.
Reduced mandatory outreach activities in exceptional circumstances
6.27 In exceptional circumstances, e.g. for an urgent narrow-scope amendment issued by the IASB where it shortens the period between publication date and effective date of the Amendment19 and the amendment is urgently required to be adopted by entities, the UKEB will have limited time to consult on whether it is suitable for endorsement and adoption in the UK. Therefore, the minimum outreach it undertakes is to ensure that the DECA is available for public consultation (on the UKEB website) for a minimum of 14 days.
Outreach activities in normal circumstances
6.28 In normal circumstances, for more complex projects that include major amendments, the UKEB may need or decide to conduct a larger number of outreach activities due to the nature and/or size of the amendment or standard to be endorsed and adopted and/or the response to consultation at the influencing stage. This is, for example, when:
- an amendment or standard changes an area of accounting that affects most UK entities applying UK-adopted international accounting standard; or
- an amendment or standard changes an area of accounting that affects a small number of UK entities applying UK-adopted international accounting standards but it is a major change.
6.29 The outreach activities that could be undertaken to gather input, views, opinions or feedback are the same as those described in section 5 of this Handbook (paragraphs 5.20–5.28). The level and content of the responses received during the influencing phase may also be relevant to deciding the level of outreach.
6.30 For 'minor' amendments that meet the IASB's criteria for annual improvements or for narrow-scope amendments the outreach activity may be focused solely on obtaining responses on the Draft Endorsement criteria Assessment (DECA).
Project closure
Voting on the adoption of a new or amended international accounting standard (mandatory)
6.31 The formal voting process by which Board members make a decision on the adoption of a new or amended international accounting standard are set out in the UKEB's Terms of Reference (Section 5, paragraphs 5.1–5.2).
6.32 Decisions on the endorsement and adoption of a standard or amendment are made at public Board meetings and follow the requirements of the UKEB's Terms of Reference as follows:
- Quorum attendance—a minimum of sixty percent of the appointed members20 are required to attend a meeting of the Board (ToR, paragraph 5.1).
- Decision-making—an affirmative written vote of at least two-thirds of all of the appointed Board members (ToR, paragraph 5.2), is required for the decision to be passed. Each member of the Board has one vote. A situation where the two-thirds majority cannot be obtained, may restart the endorsement and adoption process.
6.33 A "tentative” vote on the adoption of a new or amended international accounting standard is made at a public Board meeting and is indicative only. A formal written vote is required to endorse and adopt a new or amended international accounting standard. This vote is formalised by circulation outside the meeting by a written vote (in paper or electronic form), and the vote constitutes proper evidence of the decision of the members of the Board.
6.34 Where a Board member does not support the endorsement and adoption of a new or amended standard, that is reflected in their vote. If they wish, the reason for this view may be recorded in the minutes.
6.35 Publication of the outcome of an affirmative formal written vote on UKEB website21 is accompanied by the following documents:
- a copy of the new or amended international accounting standard;
- a copy of the 'Adoption package' that includes:
- A final Endorsement Criteria Assessment (ECA);
- A Feedback statement;
- A Due Process Compliance Statement; and
- An Adoption statement.
Adoption package
6.36 The following paragraphs set out a description of the content of the individual documents included in the 'Adoption package'.
Final Endorsement Criteria Assessment (ECA) (mandatory)
6.37 The UKEB considers the stakeholder feedback received on the DECA and uses this input to issue a final version of the Endorsement Criteria Assessment (final ECA).
Feedback statement (mandatory)
6.38 Consultation feedback received on the DECA (and any other input and feedback derived from other outreach activities) is recorded, assessed, the evidence evaluated, and reported to the UKEB in a Feedback Statement.
6.39 The purpose of a Feedback Statement is to inform stakeholders how the UKEB has responded to, or addressed, the main comments or views received from stakeholders. It also demonstrates the UKEB's adherence to its overarching guiding principles (accountability, transparency, independence and thought leadership).
6.40 The form and content of the Feedback Statement will be proportionate to the objective of the underlying subject matter and would generally include the following content:
- an objective;
- summary background of the new or amended standard;
- an explanation of the main feedback received on the DECA, through comment letters or other outreach activities;
- a description of the UKEB's response (i.e. how comments or views received from stakeholders have been addressed in the final ECA); and
- a summary of the sources of stakeholder comments, e.g. from individual stakeholder meetings, formal responses to the DECA or via other outreach events.
6.41 The Board discusses and provides comments on a draft Feedback Statement and approves the final Feedback Statement for publication.
6.42 A Feedback Statement is published on the UKEB website, usually at the same time as the final ECA is finalised.
Due Process Compliance Statement (mandatory)
6.43 The Secretariat summarises the due process activities undertaken in a closing control report called “Due Process Compliance Statement". For a description and content of this Statement refer to paragraph 11.2 in Section 11 of this Handbook.
Adoption statement (mandatory)
6.44 The Adoption statement includes:
- a statement that the new or amended standard has been:
- adopted for use within the UK, in compliance with the requirements in Regulations 7 and 8 of SI 2019/685 and reasons for this decision; or
- been partially adopted in accordance with paragraph (3) of Regulation 6 of SI 2019/685 and any reasons for this decision;
- when applicable, reasons for extending the scope of undertakings eligible to use an option in the standard in accordance with paragraph (4) of Regulation 6, setting out the full details;
- a description of the financial years in respect of which that standard must be used; and
- the wording of the adopted standard (in a separate document).
Next step after the adoption of a new or amended standard
6.46 The UKEB website should provide an indication about whether the recently adopted (new or amended) standard meets the criteria for a post-implementation review and, if so, the timing of that review (refer to Chapter 8 of this Handbook).
7. Thought leadership and research programme
Objectives of thought leadership
7.1 As part of the guiding principle of thought leadership, paragraph 4.5 of the UKEB's ToR states that the UKEB is committed to:
- lead the UK debate on international accounting standards and reporting;
- participate pro-actively in the development of new global standards, for example by undertaking research;
- represent UK views in international fora with the aim of influencing debate; and
- engage with accounting, reporting, endorsement and adoption bodies in other jurisdictions, in order to improve influence and understand best practice.
Leading the UK debate
7.2 The UKEB ensures that the views from UK stakeholders are heard and their needs understood during the development of new or amended international accounting standards.
7.3 The UKEB achieves this by:
- identifying key stakeholder groups, preparing outreach plans, and taking suitable approaches to each stakeholder group;
- giving UK stakeholders a platform to provide specialist input on areas of concern through roundtables, forums, workshops, panel discussions or education sessions organised by the UKEB or through the UKEB's advisory groups;
- soliciting UK stakeholders' comment on public consultation documents and/or UKEB's draft comment letters;
- arranging, where appropriate, for IASB Board members and/or for IASB staff to participate in UKEB's outreach events to enable first-hand understanding of any concerns or views expressed by UK stakeholders; and
- acting as a conduit for UK feedback on IASB consultations.
Participating proactively in the development of global standards
7.4 The UKEB proactively participates in the development of new global accounting standards by:
- engaging with UK stakeholders and collecting evidence on relevant technical issues (that may not be considered by the IASB or other national standard-setters);
- developing potential ways to improve or remedy deficiencies in international accounting standards; and
- working closely with others on long-term proactive work to stimulate debate on financial reporting matters on the IASB agenda at an early stage in the standard-setting process.
Representing UK views in international fora or in media with the aim of influencing debate
7.5 The UKEB directly influences the IASB Board and maintains a global presence on the international financial stage by:
- developing and presenting the UKEB's own thought leadership material to promote UK views and lead on the accounting debate at relevant international fora;
- identifying and promoting the appointment of UK representatives to IASB's consultative groups, subject to available UKEB resources. For example, to the IASB's Accounting Standards Advisory Forum (ASAF) to ensure that UK input on major technical issues related to the IASB's standard-setting activities is discussed and considered in this forum;
- maintaining effective relationships, communication and presence with the IASB and other national standard-setters subject to available UKEB resources. For example, by:
- participating in the World Standard-Setters conference organised by the IASB to share international accounting standards implementation and application experiences with other standard-setters around the world;
- participating in other international accounting forums organised by other parties independently (e.g. International Forum of Accounting Standard-Setters (IFASS));
- regularly attending (in person or remotely) key meetings and conferences of international financial reporting bodies to ensure adequate analysis and input, including expressing UK views;
- communicating outcomes from international engagements to UK stakeholders, to assist in identifying concerns with international proposals; and
- issuing articles, podcasts or videos, to stimulate debate on a particular matter or technical issue. The Board does not express any opinion or tentative views on the matters presented in such papers or reports.
Engaging with other bodies in other jurisdictions
7.6 Regular contact between the UKEB and other national standard-setters in other jurisdictions can help increase the understanding, awareness and support for UK views, thereby, allowing the UKEB to lead on the accounting debate.
7.7 The UKEB and other national standard-setters can interact in a range of ways including developing joint thought leadership and research documents, regular and ad-hoc emails, conferences and roundtables, blogs, articles, regional forums or telephone exchanges.
Research programme
Objective
7.8 Research is generally directed to identify specific issues associated with projects that are on the UKEB's technical agenda. As such, research may be expected to have a problem-solving orientation by collecting evidence on the nature and extent of the perceived shortcomings of, and assessing potential ways, to improve or to remedy a deficiency in international accounting standards.
7.9 This type of research helps the UKEB:
- identify a new project that could potentially be included in the UKEB's work plan;
- assist the IASB in the identification of a new technical issue (for example, in response to the IASB's five-yearly agenda consultation request) and in the analysis of potential solutions; or
- provide effective technical input into IASB proposals forming part of IASB's current agenda.
7.10 Where resources are available, other more explorative research may also be performed by the UKEB to include the consideration of broader financial reporting matters, such as how financial reporting is evolving, and to encourage international debate on financial reporting matters. This type of research may be formally added to the UKEB's technical agenda.
7.11 Research may be undertaken by the UKEB on its own or collectively with others (i.e. national standard-setters, regulators, academics and other interested parties); the latter when there are topics of mutual interest.
Main outputs
7.12 The common categories of research outputs derived from the UKEB's research programme are explained below:
- Discussion Papers, as documents that include an overview of specified technical issues, possible approaches to addressing these issues and preliminary/final views from the Board and an Invitation to Comment;
- Requests for Information or feedback on a matter related to technical projects or broader consultations. For example, seeking comments on the UKEB's technical work plan, post-implementation reviews, or help in assessing the practical implications of a potential financial reporting requirement;
- Research Papers, to contribute to wider discussions on cross-cutting issues in financial reporting;
- Bulletins, to promote and stimulate debate within the UK on specific accounting matters; or
- Quantitative studies.
Milestones
7.13 The milestones expected to be achieved for research projects are:
- Identification of issues for research;
- Project initiation plan (mandatory);
- Desk-based research;
- Outreach activities;
- Approval of research document (mandatory);
- Publication of research document (mandatory); and
- Project closure for research documents that invite stakeholder comments includes:
- Feedback Statement (mandatory); and
- Due Process Compliance Statement (mandatory).
7.14 The mandatory milestones will ensure that the UKEB adheres to its guiding principles of accountability, independence and transparency. Other milestones (those not labelled as "mandatory”) may be considered for most projects and included in the project plan proportionate to the nature of the issue and the expected timeline.
7.15 The activities undertaken to achieve the milestones in paragraph 7.13 should be proportionate to the issue(s) that are part of the UKEB's research and will depend on its significance for UK stakeholders and on its complexity (i.e. nature or scope). For example, it is expected that for 'major' research projects the activities undertaken would be far more extensive than for other 'minor' research projects where some activities such as desk-based research or outreach activities may be somewhat more limited.
Identification of issues for research
7.16 The Secretariat may identify or may receive proposals to research an issue and submit research proposals to the UKEB Chair for consideration. Proposals may arise from the Secretariat's own research, from a Board member, from consulting with the UKEB's advisory groups or from comments and information gained from public hearings, fieldwork (refer to paragraphs 5.21–5.22 of this Handbook) as well as stakeholder comment letters.
Project Initiation Plan (mandatory)
7.17 For a research project to be incorporated into the UKEB’s work plan, a “Project Initiation Plan" (PIP) is prepared for approval by the Board.
7.18 The objective of the PIP is to assess the potential impact and scale of the research project and, consequently, the level of analysis and outreach that should be undertaken.
7.19 The PIP outlines the approach to the project, including:
- a description of the project objective and proposed timeline;
- a description of mandatory milestones and planned activities that will be undertaken to achieve those milestones.
- available and required resources for the project (including whether those resources are already allowed for in the annual plan or budget);
- expected research output (i.e. Research Paper, Discussion Paper, Request for Information, bulletin, quantitative study, etc); and
- if applicable, the factors considered to justify departing from the standard consultation period for a research document (refer to paragraph 7.28 below).
7.20 If the research is carried out collectively with other parties (i.e. national standard-setters, regulators, academics or others) then agreement on the following will be achieved before commencement of work:
- the responsibilities and expectations of each party involved, including expectations about use of the project output;
- whether the project will present only an analysis of the facts or whether it will contain views or recommendations; and
- the expected output (i.e. Research Paper, Discussion Paper or Request for Information), copyright and publication rights over the output.
7.21 If changes arise subsequent to commencement of a research project, for example, as a result of the input received from outreach activities, the project PIP can be updated to address those changes.
7.22 The project plan included in the PIP forms the basis for compliance with the due process steps set out in this Handbook (refer to paragraph 11.2(c) in this Handbook).
Desk-based research
7.23 Desk-based research is undertaken to assist with the assessment of proportionality and to gather evidence on the issue. This will usually include a review of the IASB's previous work on this issue. It may also include, for example, a review of literature, academic papers, financial statements or of past papers or reports (by other national standard-setters or by other stakeholders (i.e. users, preparers, academics, accounting firms, accounting bodies, regulators or others), as well as liaising with national standard-setters who have who have performed or are in the process of performing research on the same (or related) project.
Outreach activities
7.24 Outreach is conducted with stakeholders that represent different stakeholder communities, (i.e. users, preparers, academics, accounting firms, accounting bodies and regulators) to gather their input, views, opinions or feedback on specific projects or technical matters.
7.25 The outreach activities that could be undertaken to gather input, views, opinions or feedback are the same as those described in section 5 of this Handbook (paragraphs 5.20–5.28).
Approval of a research document (mandatory)
7.26 The Board approves a research document for publication. It does not require a formal written vote by the Board. It requires the support of a simple majority of the Board members present at the meeting, with approval given in a public meeting.
Publication (mandatory)
7.27 A research document may not include an Invitation to Comment, e.g. a Bulletin explaining a specific accounting topic or a summary of outreach undertaken on a specific accounting topic.
7.28 Where a research document includes an Invitation to Comment, the standard consultation period is 90 days.
7.29 In exceptional circumstances, where the research document is on a topic that is narrow in scope and/or urgent the Board may set a shorter period. The rationale for a shorter comment period will be given in the PIP.
Project closure
7.30 This section applies only to a research document that invites stakeholder comments.
Feedback Statement (mandatory)
7.31 Input and feedback received on a research document is recorded, assessed, the evidence evaluated, and then incorporated into the analysis and discussion of the technical issues in a "Feedback Statement". For the objectives and content of this statement refer to paragraphs 5.29–5.34 in this Handbook.
Due Process Compliance Statement (mandatory)
7.32 For a research project that involves issuing a research document that invites stakeholder comments, the Secretariat summarises the due process activities undertaken in a closing control report called “Due Process Compliance Statement". For a description and content of this Statement refer to paragraph 11.2 in Section 11 of this Handbook.
8. Post-implementation reviews
Introduction
8.1 A post-implementation review (PIR) assesses the effect of a new international accounting standard or of a major amendment to an international accounting standard and determines whether:
- the requirements in international accounting standards result in entities providing financial information that is useful in making informed economic decisions;
- there are any significant unexpected changes to financial reporting or operating practices resulting from the application of the international accounting standard;
- there are unexpected costs or challenges in applying the international accounting standard;
- there are any areas of the international accounting standard that represent interpretation challenges and, as a result, impair the consistent application of the international accounting standard; and
- the international accounting standard is understandable and it is being applied as intended, and whether preparers are able to report the information reliably.
Influencing IASB Post-implementation reviews
8.2 The UKEB's work on influencing the development of international accounting standards includes monitoring and responding to IASB post-implementation reviews of international accounting standards.
8.3 The IASB is required to conduct a post-implementation review of each new IFRS Standard or major amendment. This review normally begins after the new requirements have been applied internationally for two years23. The IASB commences its post-implementation review with a Request for Information which sets out the initial identification and assessment of the matters to be examined.
8.4 The UKEB follows the influencing processes in Section 5 of this Handbook to respond to an IASB Request for Information.
8.5 In addition, the UKEB promotes awareness of IASB post-implementation reviews in the UK, and consults stakeholders and its advisory committees, asking them for input.
Processes for a UKEB Post-implementation Review
Objectives
8.6 Paragraph 3 in Regulation 11 in SI 2019/68524 contains a requirement to:
- "carry out a review of the impact of the adoption of the standard" where the standard is likely to lead to a "significant change in accounting practice"; and
- publish a report setting out the conclusions of the review no later than 5 years after the date on which the standard takes effect (being the first day of the first financial year in respect of which it must be used)".
8.7 Paragraph 4 in Regulation 11 in SI 2019/685 contains a requirement to:
- carry out subsequent reviews from time to time; and
- publish a report setting out the conclusions of any review conducted.
8.8 A "significant change in accounting practice” usually occurs when a new accounting standard is issued by the IASB. A new standard meets a “significant change in accounting practice" as it will usually have a widespread effect on many entities or a material effect on a few entities.
8.9 The IASB undertakes a post-implementation review of each new standard. As a result, the obligations in Regulation 11 in SI 2019/685 can be fulfilled for most international accounting standards by influencing and responding to IASB's post-implementation reviews (refer to paragraphs 8.2–8.5 in this Handbook).
8.10 When the IASB decides not to undertake a post-implementation review on a new international accounting standard and it is a significant change in accounting practice, the UKEB must perform its own post-implementation review of the standard to test its continuing relevance in line with the requirements in Regulation 11 in SI 2019/685. This should be completed no later than 5 years after the date on which the international accounting standard takes effect, in accordance with paragraph (3)(b) of this Regulation.
8.11 Each post-implementation review that the UKEB carries out has two phases as described below.
First phase of a UKEB post-implementation review
8.12 In the first phase of a post-implementation review, the UKEB sets out the scope of the review, on the basis of targeted consultation with stakeholders that represent different stakeholder communities, (e.g. users, preparers, academics, accounting firms, accounting bodies and regulators25) to gather their input, views, opinions or feedback on specific projects or technical matters. These initial consultations help the UKEB establish the questions to ask in the public request for information.
8.13 The milestones for the first phase are:
- Project initiation plan (PIP) (mandatory);
- Desk-based research;
- Initial consultation; and
- Publication of a Request for Information (mandatory).
Project Initiation Plan (mandatory)
8.14 The objective of the PIP is to assess the need to undertake a post-implementation review of an international accounting standard.
8.15 The PIP outlines the approach to the project, including:
- a description of the project objective and proposed timeline;
- any initial assessment of the international accounting standard, the reasons why the UKEB should seek feedback and the process followed in establishing the scope of the review;
- a description of mandatory milestones and planned activities that will be undertaken to achieve those milestones.
- available and required resources for the project (including whether those resources are already allowed for in the annual plan or budget);
- expected output (i.e. a Request For Information); and
- if applicable, the factors considered to justify departing from the standard consultation period for a Request For Information (refer to paragraph 8.23 below).
Desk-based research
8.16 Desk-based research is undertaken to assist with the assessment of proportionality and to gather evidence on the need for a PIR. This will usually include review of:
- the IASB's and the UKEB's previous work on the issue to identify the issues that were important or contentious during the development of the international accounting standard, which should be identifiable from the Basis for Conclusions, project summary, Feedback Statement and Effect Analysis, of the relevant Standard;
- any relevant research, including that performed by the Secretariat and academics; and
- any issues brought to the UKEB's attention prior to the commencement of the PIR.
8.17 It may also include, for example, a review of literature, academic papers, financial statements or of past papers or reports (by other national standard-setters or by other stakeholders (i.e. users, preparers, academics, accounting firms, accounting bodies and regulators), as well as liaising with national standard-setters who have carried out influencing activities or are in the process of performing such activities on the same (or related) project.
Initial consultation
8.18 The Board and its Secretariat may also consult with stakeholders to help identify areas where unexpected costs or implementation problems were encountered.
8.19 This initial review should draw on the broad network of UKEB related bodies and interested parties, such as the UKEB's advisory groups, and other outside groups of, for example, preparers, auditors or users. The purpose of these consultations is to inform the UKEB so that it can establish an appropriate scope for the review. The extent of consultation needed for this phase will depend on the Standard being reviewed and pre-existing information about the implementation of that Standard.
Publication of a Request for Information (mandatory)
8.20 When the UKEB is satisfied that it has sufficient information to establish the scope of the review it issues a request for information on the Post-implementation review of the international accounting standard.
8.21 A Request for Information sets out the matters for which the UKEB is seeking feedback together with a rationale for the information being sought and any initial assessment by the UKEB of the impact of the international accounting standard. It also describes the reasons for undertaking such review (in line with Regulation 11 in SI 2019/685).
8.22 Publication of a Request for Information does not require a formal written vote by the Board. It requires the support of a simple majority of the Board members present at the meeting, with approval given in a public meeting.
8.23 The standard comment period is 90 days.
8.24 In exceptional circumstances, where the Request for Information is on a topic that is narrow in scope and/or urgent the Board may set a shorter period. The rationale for a shorter comment period will be given in the PIP.
Second phase of a UKEB post-implementation review
8.25 In the second phase the UKEB collects information, via the Request for Information issued during the first phase, to help it assess the international accounting standard being reviewed. During this evidence-gathering phase of the post-implementation review the UKEB also conducts outreach activities to engage with different stakeholders
8.26 The milestones for the second phase are:
- Outreach activities; and
- Project closure: issue of a Final report (mandatory) and a Due Process Compliance Statement (mandatory).
Outreach activities
8.27 The UKEB's outreach activities will be focused on seeking implementation issues.
8.28 The amount of outreach to be undertaken, together with the rationale, will be highlighted in the PIP.
8.29 The outreach activities that could be undertaken to gather input, views, opinions or feedback are the same as those described in section 5 of this Handbook (paragraphs 5.20–5.28).
Project closure for a UKEB Post-implementation review
Final report (mandatory)
8.30 Input and feedback received on the request for information is recorded, assessed, the evidence evaluated, and then incorporated into the analysis and discussion of the technical issues.
8.31 When the UKEB has completed its deliberations, it presents its findings in a Final report that includes:
- an overview of the UKEB post-implementation review process and its timeline;
- background information to the international accounting standard under review;
- a summary of findings and next steps, including the areas for potential improvement and amendment;
- UKEB's conclusions of the review;
- recommendations or steps it plans to take, if any, as a result of the review; and
- a summary of the sources of stakeholder comments, e.g. from individual stakeholder meetings, formal responses to the Request for Information or via other outreach events.
Due Process Compliance Statement (mandatory)
8.32 For a UKEB post-implementation review, the Secretariat summarises the due process activities undertaken in a closing control report called "Due Process Compliance Statement". For a description and content of this Statement refer to paragraph 11.2 in Section 11 of this Handbook.
9. Advisory Groups
Introduction
9.1 The UKEB undertakes targeted consultation by appointing its own standing and ad-hoc advisory groups with the purpose of gathering technical advice, and other input on its projects or other technical matters (e.g. UK-specific implementation issues).
9.2 Members of advisory groups comprise experts that:
- provide advice and recommendations on specific agenda projects for example by sharing:
- knowledge and understanding of financial reporting issues and/or concerns raised by UK stakeholders; and
- up-to-date insight into developments and market sentiment on financial reporting matters, helping develop a timely understanding of any concern areas;
- deliver best practice, practical experience, and expertise as well as potential solutions that can improve the quality of information; and
- help amplify the UKEB's views across the UK reporting community and drive the debate of contemporary issues in the international community.
9.3 In carrying out their work, advisory groups have regard to the UKEB's Terms of Reference and Guiding Principles (refer to Chapter 3 in this Handbook).
Composition of advisory groups
Types of advisory groups
9.4 Advisory groups are not decision-making bodies, but advisory in nature and can be standing or ad-hoc. Their characteristics are described in the table below:
| Type | Standing | Ad hoc |
|---|---|---|
| Duration | Advisory group with an indefinite life. Intended to be long-lived. | Intended to be short-lived for a pre-defined time or set duration and is project-based. |
| Description | Provides regular and focused input on a wide range of strategic and technical issues. | Provides focused input on a specific technical issues. May support the implementation and/or transition to a new international accounting standard26 |
| Members- stakeholder type | Usually includes stakeholders from a particular industry, sector or stakeholder type (i.e. preparers, auditors or users). It can also include a 'mix' of stakeholders with shared interests27. | Usually includes a 'mix' of senior professionals from different stakeholder groups but with a specialist knowledge of the specific issue or technical area relevant to the group. It can also include a narrower (even single) stakeholder group when appropriate to a particular project (eg users or academics only for particular project, eg research project). |
Types of participants
9.5 Participants in a UKEB's advisory group (standing or ad-hoc) may originate from the following stakeholder groups:
- Users – those with practical experience in analysing and using financial information as users of financial reporting information. Users include "buy-side” fund managers, institutional investors and retail investors as well as participants from "sell-side” investment banks and ratings agencies.
- Preparers – those with considerable practical experience of financial reporting and provide knowledge and understanding of the financial reporting issues faced by IFRS reporters. Preparers have backgrounds in large or small, listed or unlisted UK-based companies applying international accounting standards.
- Aademics – researchers with expertise and experience in the use of accounting by individuals, organisations and government. This group could include researchers with interests in accounting policy, governance and environmental issues, quantitative analysis, wider corporate reporting and economics.
- Accounting firms – those with a close interest in the use and implementation of international accounting standards. Accounting firms have insights to share on a range of different sectors' use of international accounting standards and on any concerns arising from that use. They include large and medium-sized professional services firms in the UK.
- Accounting Bodies – those with a close interest in the use and implementation of international accounting standards and providing insights on current and emerging issues.
- Regulators – those that regulate or supervise a particular industry or business activity. Regulators have insights to share on the use of international accounting standards by different sectors and on any concerns arising from that use.
Operating procedures
Approval for the creation of an advisory group
9.6 The establishment of an advisory group is subject to Board approval by a majority of Board members.
Terms of reference
9.7 Each advisory group has its own Terms of Reference, setting out:
- the advisory group's purpose and responsibilities;
- membership rules;
- meetings and administrative arrangements;
- remuneration for members (if applicable); and
- date of approval of the Terms of Reference and process for making changes.
9.8 An outline of the content of the Terms of Reference applicable to each advisory group (i.e. standing or ad-hoc) is included in Appendix B of this Handbook.
Recruitment
9.9 Consistent with the UKEB's guiding principles of accountability and transparency, all recruitment for advisory groups should be via a public advertisement, inviting applications. Appointments should be based on interviews with Board members and members of the Secretariat. The Board may wish to retain the option to make the occasional direct appointment, however, this would need to be in exceptional circumstances, for example where there are few experts in a particular area or no other expert is forthcoming.
Appointments and membership
9.10 In appointing members, the UKEB Chair seeks to ensure that the membership in the advisory groups is diverse in terms of skills experience, background, race and other characteristics, and achieves a gender balance.
9.11 Members of advisory groups are appointed in their personal capacity. Alternates are not permitted.
9.12 Membership to an advisory body is approved by the Board at a private meeting. Once approved, the members of an advisory group are listed on the UKEB's website.
9.13 Depending on the advisory group's nature and purpose, the UKEB Chair may appoint a chair for the advisory group who may be either: an advisory group member, a Board member or a Secretariat member.
9.14 Members of advisory groups are appointed for an initial term of up to three years renewable for a second term of up to three additional years, or for the length of the project (e.g. for ad-hoc groups). The length of term may be shortened or lengthened if circumstances warrant. Staggered rotation of members to ensure continuity on the advisory group. Changes to appointments arising from such reviews are approved by the Board at a private meeting. The membership of the advisory group is then updated on the UKEB's website.
Meetings
9.15 Administrative support to the advisory group will be provided by the Secretariat as necessary, including organising meetings and updating members about the project's progress.
9.16 Technical papers for meetings of advisory groups will generally be prepared by Secretariat or members of the advisory group, as appropriate. All advisory groups' papers to the advisory groups and UKEB are confidential unless all members of the group agree to share them more widely or to issue papers which are presented at a public Board session.
9.17 Meetings of advisory groups are attended by some Board members as approved by the UKEB Chair.
9.18 Meetings of advisory groups are closed and held in private. The Secretariat will report a summary of the output from the group to the Board at a public meeting.
9.19 Meetings of advisory groups may be held in the presence of invited observers with speaking rights only if the chair deems it beneficial to the work of the group.
9.20 Members of advisory groups will be expected to:
- review all relevant material before the meeting;
- provide specialist knowledge and technical advice in line with the purpose and responsibilities of the group's Terms of Reference.;
- make evidence-based and objective contributions, to the extent possible;
- aim for consensus-building wherever possible and, to that end, should be prepared to be challenged on their views and open to consideration of other members' perspectives;
- remain respectful and professional in all interactions with other members of the group and with the Secretariat; and
- attend all meetings.
Frequency for ad hoc advisory groups
9.21 Once work on a project commences, the Board and/or the Secretariat may consult advisory groups when it is beneficial to the project to do so.
Effectiveness review
9.22 The Board will evaluate the purpose and effectiveness of each advisory group every three years (or more frequently, if circumstances warrant), to assess each group as to whether:
- It is continuing to serve the function for which it was established. The Board revises the Terms of Reference applicable to each advisory group as necessary.
- The composition continues to be appropriate. This will include appointments and re-appointments of members. Any changes to membership are approved by the Board at a private meeting. The membership of the advisory group is then updated on the UKEB's website.
10. Influencing the work of the IFRS Interpretations Committee
Introduction
10.1 The IFRS Interpretations Committee is the IASB's interpretative body that “assists the [IASB] Board in improving financial reporting through timely assessment, discussion and resolution of financial reporting issues identified to it within the IFRS framework”28. It does so by, amongst other things:
- recommending to the IASB to add a standard-setting project to its work plan when certain criteria in the IFRS Due Process Handbook29 are met. This is done in the form of a proposal for a narrow-scope amendment or an annual improvement, i.e. amendments that meet the IASB's criteria for annual improvements or for narrow-scope amendments;30
- developing a proposal for a Draft IFRIC Interpretation (that is later ratified by the IASB); and
- recommending that the IASB does not add a standard-setting project to its work plan, instead publishing an agenda decision31 to address application questions.
Supporting the work of the IFRS Interpretations Committee
10.2 The UKEB supports the IASB's and the IFRS Interpretations Committee's work by ensuring that UK views are considered during the development and improvement of international accounting standards (including IFRIC Interpretations). This is achieved by:
- monitoring the work of the IFRS Interpretations Committee;
- influencing proposals for annual improvements, narrow-scope amendments and/or Draft IFRIC Interpretations;
- considering whether to contribute comment letters on tentative agenda decisions issued by the IFRS Interpretations Committee; and
- informing the IFRS Interpretations Committee and/or the IASB of significant issues raised or identified by UK stakeholders for potential inclusion in their work programme.
(a) Monitoring IFRS Interpretations Committee work
10.3 The Secretariat monitors projects developed by (or with the assistance of) the Interpretations Committee and reports them to the Board on a regular basis (i.e. proposals for amendments, IFRIC Interpretations or tentative agenda decisions).
10.4 The Secretariat may consider:
- undertaking outreach activities ahead of the IFRS Interpretations Committee issuing proposals before a due process document is published; and
- delivering an update on matters discussed at Interpretations Committee meetings at Board meetings, with the objective of raising awareness at Board meetings on the issues being discussed; whether the Board would like to respond and possible interactions with the UKEB's other activities and projects.
(b) Influencing proposals for amendments or for Draft IFRIC Interpretations
10.5 The UKEB follows the requirements in Section 5 of this Handbook for influencing proposals for annual improvements, narrow-scope amendments and/or Draft IFRIC Interpretations.
(c) Considering whether to respond to a tentative agenda decision
10.6 The UKEB expects to respond to a limited number of tentative agenda decisions published by the IFRS Interpretations Committee. Some factors to consider when deciding whether to respond may be:
- The degree of impact of the IFRS Interpretations Committee tentative agenda decision on UK companies (for example, in cases where the tentative agenda decision is expected to affect a significant number of UK companies);
- Disagreement with the analysis performed by the IFRS Interpretations Committee; or
- Usefulness of the explanations and clarifications included in the tentative agenda decision.
10.7 The Board might also choose to respond to a tentative agenda decision even if it agrees with the analysis performed by the IFRS Interpretations Committee, to provide public support of the tentative agenda decision. For example, this may apply in cases where others have expressed disagreement with the analysis in the tentative agenda decision.
10.8 When the Board reviews the update on the IFRS Interpretations Committee's activities it decides whether to respond to a tentative agenda decision.
10.9 If an issue discussed by the IFRS Interpretations Committee arises outside the usual Board meeting cycle, the UKEB Chair can approve initiation of work on the tentative agenda decision.
Project milestones for tentative agenda decisions
10.10 The UKEB will broadly follow the milestones in paragraph 5.7 in Section 5 of this Handbook to influence tentative agenda decisions issued by the IFRS Interpretations Committee that the UKEB considers have relevance for the UK. However, these milestones will only be followed to the extent they are appropriate or possible. For example, given that the comment period for a tentative agenda decision is usually shorter than for other IASB's due process documents, it may be more appropriate to consult with a representative group of stakeholders and/or with members of the UKEB's standing and/or ad-hoc advisory groups, rather than making a Draft Comment Letter available for comment on the UKEB website.
10.11 The activities undertaken to achieve these milestones should be proportionate to the technical issue(s) being addressed and will depend on its significance for UK stakeholders and on its complexity. The Project Initiation Plan will outline the approach to the technical issue(s) being addressed and describe how the approach taken meets due process requirements.
10.12 After considering comments from UK stakeholders on tentative agenda decisions, the UKEB may decide to recommend that the IFRS Interpretations Committee:
- confirms the IFRS Interpretations Committee's decision to publish an agenda decision;
- revises (or abandons) the IFRS Interpretations Committee's tentative agenda decision; or
- refers the matter to the IASB to consider adding a standard-setting project to the IASB's work plan.
(d) Informing the IFRS Interpretations Committee of significant issues raised by UK stakeholders
10.13 The UKEB may decide to inform the IFRS Interpretations Committee of issues raised or identified by UK stakeholders as potential agenda items (i.e. for potential inclusion on the IASB's and/or on the IFRS Interpretations Committee's work programme). In doing so, the UKEB follows the procedures for the 'Identification of Matters' in the IFRS Due Process Handbook32.
II Due Process Compliance Statement
Introduction and objective
11.1 For each project, the Secretariat assesses whether it has complied with the UKEB's due process activities as set out in Section 4 (Governance activities), Section 5 (Influencing
10.9If an issue discussed by the IFRS Interpretations Committee arises outside the usual Board meeting cycle, the UKEB Chair can approve initiation of work on the tentative agenda decision.
Project milestones for tentative agenda decisions
10.10The UKEB will broadly follow the milestones in paragraph 5.7 in Section 5 of this Handbook to influence tentative agenda decisions issued by the IFRS Interpretations Committee that the UKEB considers have relevance for the UK. However, these milestones will only be followed to the extent they are appropriate or possible. For example, given that the comment period for a tentative agenda decision is usually shorter than for other IASB's due process documents, it may be more appropriate to consult with a representative group of stakeholders and/or with members of the UKEB's standing and/or ad-hoc advisory groups, rather than making a Draft Comment Letter available for comment on the UKEB website.
10.11The activities undertaken to achieve these milestones should be proportionate to the technical issue(s) being addressed and will depend on its significance for UK stakeholders and on its complexity. The Project Initiation Plan will outline the approach to the technical issue(s) being addressed and describe how the approach taken meets due process requirements.
10.12After considering comments from UK stakeholders on tentative agenda decisions, the UKEB may decide to recommend that the IFRS Interpretations Committee:
- confirms the IFRS Interpretations Committee's decision to publish an agenda decision;
- revises (or abandons) the IFRS Interpretations Committee's tentative agenda decision; or
- refers the matter to the IASB to consider adding a standard-setting project to the IASB's work plan.
(d) Informing the IFRS Interpretations Committee of significant issues raised by UK stakeholders
10.13The UKEB may decide to inform the IFRS Interpretations Committee of issues raised or identified by UK stakeholders as potential agenda items (i.e. for potential inclusion on the IASB's and/or on the IFRS Interpretations Committee's work programme). In doing so, the UKEB follows the procedures for the 'Identification of Matters' in the IFRS Due Process Handbook32.
II Due Process Compliance Statement
Introduction and objective
11.1For each project, the Secretariat assesses whether it has complied with the UKEB's due process activities as set out in Section 4 (Governance activities), Section 5 (Influencing Process), Section 6 (Endorsement Process), Section 7 (Thought leadership and research programme33) and Section 8 (i.e. the sub-section on “UKEB Post-implementation review”) of this Handbook, as applicable to the subject matter of the project.
11.2The Secretariat summarises the due process activities undertaken in a closing control report called “Due Process Compliance Statement". This report fulfils the following objectives:
- provides a record of the activities undertaken by the Secretariat to comply with the UKEB's due process activities;
- provides a basis for holding the Secretariat accountable to the Board for the due process procedures that it follows in practice; and
- informs the Board about the work undertaken compared with that agreed in the Project Initiation Plan (PIP). The Due Process Compliance Statement retrospectively validates that the process undertaken complied with the PIP (or not). If discrepancies are identified this report provides an explanation as to why, and how the activities still meet due process requirements.
Content
11.3The Due Process Compliance Statement includes the following sections:
- Project details:
- If influencing an IASB's due process document: title, date of publication and comment letter deadline;
- If a UKEB's thought leadership/research project: project title, date of publication, comment letter deadline (if applicable); or
- If endorsing an IASB standard or amendment: title, date of publication and the IASB's effective date.
- A description of due process steps undertaken covering the following areas:
- Project preparation (i.e. the Project Initiation Plan (PIP) and/or a revised version of the PIP and desk-based research);
- Communications (e.g. public meetings, documents posted on the UKEB website);
- Outreach activities (e.g. advisory groups, fieldwork undertaken);
- Preparation of documents for public comment (e.g. draft comment letter for influencing activities);
- Project finalisation and project closure (e.g. final comment letter, feedback statement for influencing activities);
- Metrics or evidence to demonstrate that the process was undertaken as agreed in the Project Initiation Plan (e.g. number of meetings held);
- An explanation of why the Secretariat decided not to undertake a due process step for a given project, if relevant (i.e. why an outreach activity specified in the PIP was not undertaken); and
- A conclusion as to whether, in the Secretariat's opinion, applicable due process steps have been complied with.
11.4The Board discusses and provides comments on a (draft) Due Process Compliance Statement and approves the final version of this Statement at a public Board meeting.
11.5A Due Process Compliance Statement is published on the UKEB website, usually at the same time as the Feedback Statement34.
Appendix A—Relationship between Statutory Instruments (SI) and other governance documents for the Endorsement Board
Relationship between SI and documents for the Endorsement Board
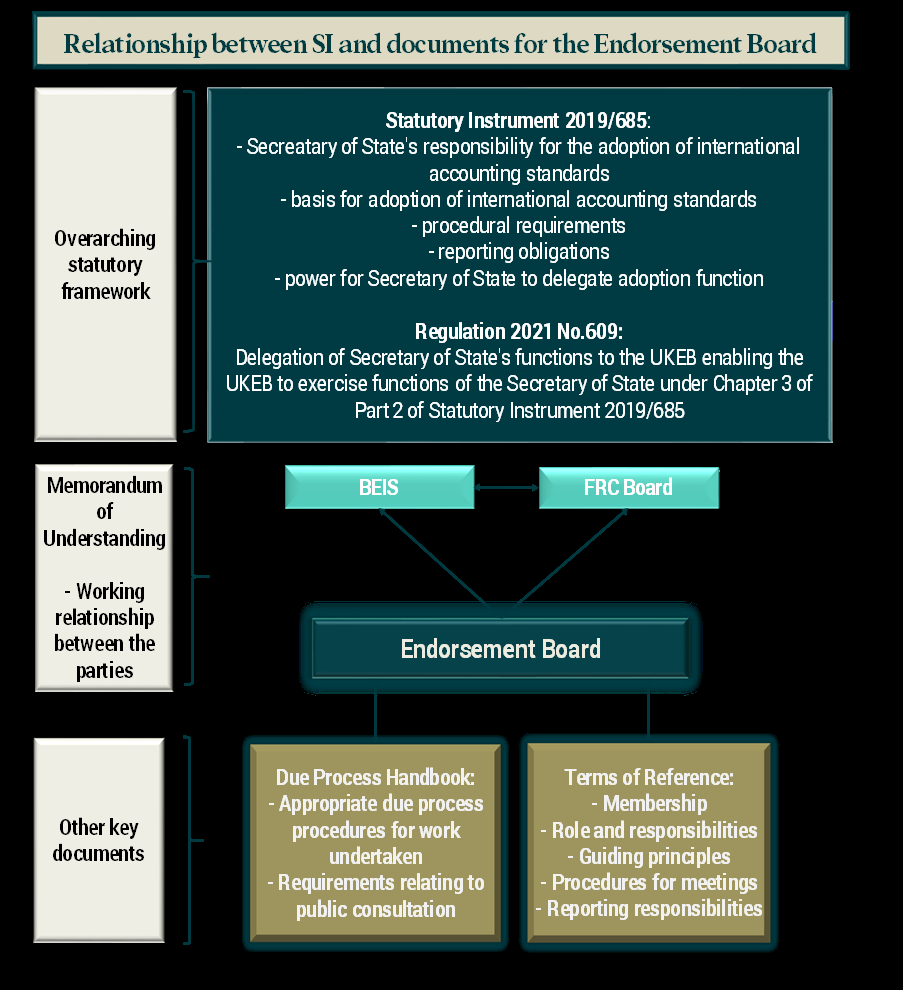
Appendix B—[Draft] Terms of Reference outline for advisory groups
Terms of Reference
1 Name, purpose and responsibilities
1.1Name [of advisory group], purpose and responsibilities to the Board and/or to the Secretariat.
1.2Guiding principles and compliance with legislative framework.
2 Membership
2.1Composition and membership length. The membership of an advisory group is reviewed on a regular basis with the possibility that members may be appointable for consecutive terms. Members of advisory groups are appointed for an initial term of up to three years renewable for a second term of up to three additional years. The length of term may be shortened to allow for a staggered rotation of members to ensure continuity on the advisory group. Changes to appointments arising from such reviews are approved by the Board.
2.2Size: minimum and maximum number of members.
2.3What the Board and/or the Secretariat expect from the members of the advisory group and consequences of failing to meet the expectations set out in the terms of reference (for example dismissal after non-attendance at a certain number of meetings, etc).
3 Meetings and administrative arrangements
3.1Process for holding meetings:
- Indication of whether meetings are:
- closed and/or open to the public; if meetings are public, an indication of whether observers can attend meetings and/or if they have speaking rights;
- held virtually and/or physically;
- Requirements for attendance and an indication of whether alternates are permitted;
- Location, duration (i.e. number of hours), and frequency (i.e. number of meetings per month and/or per year); and
- Indication of who will act as the chair of the advisory group;
3.2Notice of meetings and agendas: State obligation to:
- make available meeting agendas and papers for the members of the advisory groups before the meeting; and
- publish the agendas and a summary of the output from the group (without attribution to members) on the UKEB website.
3.3If meetings are public, also state obligation to broadcast (and/or record) meetings and to publish agenda papers on the UKEB website.
4 Remuneration for members
4.1Indication of whether members are (or not) remunerated.
4.2Indication of whether members are reimbursed for reasonable travel and other costs incurred in participating in the group's activities.
5 Approval of Terms of Reference and changes
5.1Date of approval of the Terms of Reference and process for making changes to these terms.
January 2022
- Executive Summary
- Purpose
- Next steps and timeline
- Due Process Handbook Plan - Upcoming Tasks
- [Draft] Due Process Handbook
- Appendices
- 1. Introduction
- 2. Statutory functions of the UKEB
- 3. Terms of Reference and Guiding Principles
- 4. Governance Activities
- 5. Influencing process
- 6. Endorsement process
- 7. Thought leadership and research programme
- Objectives of thought leadership
- Leading the UK debate
- Participating proactively in the development of global standards
- Representing UK views in international fora or in media with the aim of influencing debate
- Engaging with other bodies in other jurisdictions
- Research programme
- Milestones
- Identification of issues for research
- Project Initiation Plan (mandatory)
- Desk-based research
- Outreach activities
- Approval of a research document (mandatory)
- Publication (mandatory)
- Project closure
- 8. Post-implementation reviews
- 9. Advisory Groups
- 10. Influencing the work of the IFRS Interpretations Committee
- II Due Process Compliance Statement
- II Due Process Compliance Statement
- Appendix A—Relationship between Statutory Instruments (SI) and other governance documents for the Endorsement Board
- Appendix B—[Draft] Terms of Reference outline for advisory groups
- 1 Introduction
- 2 Statutory functions of the UKEB
- 3 Terms of Reference and Guiding Principles
- 4 Governance Mandatory Due Process-Activities
- Quorum of attendance and decision-making
- Voting process for endorsement decisions
- Voting process for non-endorsement decisions
- Transparency of meetings and stakeholder observers
- Minutes from Board Meetings
- UKEB Secretariat papers
- Consultation with stakeholders
- Keeping stakeholders informed
- Keeping stakeholders informed
- 5 Influencing process
- 6 Endorsement process
- 7. Thought leadership and research programme
- Research programme
- Objective
- Main outputs
- Milestones
- Identification of issues for research
- Project Initiation Plan (mandatory)
- Desk-based research
- Outreach activities
- Approval of a research document (mandatory)
- Publication (mandatory)
- Discussion Papers
- Research Papers and Requests for Information
- Project closure
- Feedback Statement (mandatory required when issuing a Discussion Paper)
- Comment Letter Summary required when issuing a Research Paper or a Request for Information
- Due Process Compliance Statement (mandatory required for a Discussion paper)
- 8. Post-implementation reviews
- Introduction
- Influencing IASB Post-implementation reviews
- Processes for a UKEB Post-implementation Review
- Desk-based research
- Initial consultation
- Publication of a Request for Information (mandatory)
- Second phase of a UKEB post-implementation review
- Publication of a Request for Information (mandatory)
- Second phase of a UKEB post-implementation review
- Outreach activities
- Project closure for a UKEB Post-implementation review
- Due Process Compliance Statement (mandatory)
- 9 Advisory Groups
- 10 Influencing the work of the IFRS Interpretations Committee
- Introduction
- Supporting the work of the IFRS Interpretations Committee
- Monitoring IFRS Interpretations Committee work
- Influencing proposals for amendments or for Draft IFRIC Interpretations
- Considering whether to respond to a tentative agenda decision
- Project milestones for tentative agenda decisions
- Informing the IFRS Interpretations Committee of significant issues raised by UK stakeholders
- II Due Process Compliance Statement
- Appendix A—Relationship between Statutory Instruments (SI) and other governance documents for the Endorsement Board
- Appendix B—IASB’s and IFRS Interpretations Committee’s consultation documents
- Appendix B [Draft] Terms of Reference outline for advisory groups
- [Draft] Due Process Handbook—
- Proposed questions for public consultation
1 Introduction
1.1The Due Process Handbook (Handbook) sets out the due process that how the UK Endorsement Board (UKEB)1 follows in will assessing the appropriateness of international accounting standards2 for use in the UK. International accounting standards are developed and issued by the International Accounting Standards Board (IASB). In doing so, it This Handbook describes the due process that the UKEB follows in:
- influencing the development of international accounting standards (including influencing the IASB's post-implementation reviews and the
and theother activities of the IASB and the IFRS Interpretations Committee's activities); and - endorsing and adopting international accounting standards.
1.2This Handbook also describes additional due process steps that the UKEB follows for:
- carrying out its thought leadership activities and developing its own research programme;
- performing its own post-implementation reviews;
- setting up and operation of advisory groups; and
- making sure it complies with the required due process steps in this Handbook.
1.3This Handbook guides the UKEB on performing the required due process steps and explains how stakeholders can participate in this process. These steps:
- specify the mandatory milestones to be achieved and other milestones (not labelled as “mandatory") that may be considered for most projects. These milestones build on the UKEB's statutory functions (as described in Chapter 2), its Terms of Reference and its guiding principles (as described in Chapter 3) and its Governance Activities (as described in Chapter 4); and
(e)(b) identify other activities that can be undertaken to achieve the milestones set out in this Handbook. These activities should be proportionate to the technical issue(s) being addressed, including consideration of the project's significance for UK stakeholders and its complexity (i.e. nature or scope).
1.41.31.4The Secretary of State for the Department of Business, Energy and Industrial Strategy (BEIS) delegated the functions relating to influencing, endorsing and adopting international accounting standards for application in the UK to the UKEB in May 20213. The Secretary of State maintains a regular review of the performance of the UKEB in exercising those functions. The UK Financial Reporting Council (FRC) oversees the effective governance of the UKEB and its adherence to the due processes set out in this Handbook. It also provides operational support. The FRC does not have the power to direct the UKEB in relation to the determination of its programme of work or the outcome of its technical decision-making4.
1.51.41.5This Handbook forms one of the key documents of the UKEB. A diagram of the relationship between these documents can be found in Appendix A.
2 Statutory functions of the UKEB
2.1The following Regulation 5 of SI 2019/685 sets out the UKEB's statutory functions were delegated to the UKEB⁵, as follows:
Regulation 5 of SI 2019/685:
- the adoption of international accounting standards for use within the United Kingdom, with a view to harmonising the financial information presented by the companies required by section 403(1) of the Companies Act 2006 to prepare their accounts in accordance with UK-adopted international accounting standards, in order to ensure-
- a high degree of transparency and international comparability of financial statements; and
- the efficient allocation of capital, including the smooth functioning of capital markets in the United Kingdom; and
- participating in and contributing to the development of a single set of international accounting standards."
2.2Regulation 8 of SI 2019/685 also requires consultation:
"Before adopting an international accounting standard under regulation 6, the Secretary of State must consult such persons as the Secretary of State considers to be representative of those with an interest in the quality and availability of accounts, including users and preparers of accounts.”
2.3Regulation 17 of SI 2019/685 also requires that the Board report to the Secretary of State on its activities:
"(1) The body must, at least once in each calendar year for which the delegation regulations are in force, make a report to the Secretary of State on-
- the discharge of the functions transferred to it, and
- such other matters as the Secretary of State may by regulations require.”
3 Terms of Reference and Guiding Principles
Terms of Reference
3.1The Terms of Reference (ToR)6 further elaborate on the UKEB's role and responsibilities as they relate to the statutory functions7. The UKEB's key responsibilities include:
- Considering and deciding whether to endorse and adopt8 new or amended international accounting standard for application in the UK. This includes a formal endorsement criteria assessment which assesses the impact on UK entities. Whilst the FRC will provide operational infrastructure and other support to it, the UKEB's technical decision-making shall be independent.
- Influencing the development of IFRS. The UKEB will follow and contribute to debates on
allthe IASB's projects (as appropriate)9, consult with UK stakeholders to obtain their views, highlight any concerns to the IASB at every different stages of their projects, including the development ofitsthe IASB's agenda, responding to its draft proposals and consultations and to its post-implementation reviews10. - Deciding on the work plan for research and thought leadership activities and developing those activities to contribute to the development of financial reporting internationally, after public consultation on possible projects to be included11.
- Ensuring that there is an open and transparent due process including a public consultation process (as appropriate12) with stakeholders on draft comment letters to the IASB, draft endorsement criteria assessments and other documents such as research discussion papers. This includes providing timely feedback to stakeholders on their contributions.
- Reporting to the FRC Board, in relation to the UKEB's effective operation, governance and adherence to the Due Process Handbook setting out the extent to which it has complied with the procedures set out in the Due Process Handbook.
(e)(f) Reporting to BEIS in relation to the performance of the UKEB's statutory functions.
3.2The ToR are set by the BEIS Secretary of State and adopted by the UK Endorsement Board.
Guiding Principles
3.3Paragraphs 4.1–4.5 in Section 4 of the ToR require the UKEB to act at all times in accordance with the guiding principles of:
- Accountability—includes consulting with UK stakeholders that are affected by financial reporting, undertaking activities and due process procedures in a timely manner and providing a rationale for the decisions it makes. The UKEB
istois to be accountable to:- its stakeholders (i.e. users, preparers, academics, accounting firms, accounting bodies and regulators);,
- its oversight body (the FRC) in relation to its effective operation, governance and adherence to the Due Process Handbook; and
andthe Secretary of State for BEIS in undertakingitsrelationits relation to the performance of its statutory functions.This.
- Independence—to ensure that it acts in the UK's long term public good and that it is independent from other organisations or stakeholder groups, including the FRC and BEIS, in respect of its technical decision making.
- Transparency—to determine its technical decisions after having assessed the relevant evidence received and having followed its Due Process Handbook. To undertake its activities in a transparent manner so that stakeholders are aware of current projects and understand how decisions have been made (i.e. by making comment letters received publicly available on a timely basis).
- Thought leadership—to
- lead and represent the UK on international accounting standards and reporting;
- represent UK views in international fora with the aim of influencing debate;
- engage with accounting and reporting and endorsement and adoption bodies in other jurisdictions, in order to improve influence and understand best practice; and
(i)(iv) pro-actively participate in the development of new global accounting standards for example by undertaking research.
3.4These guiding principles are embedded into the processes described in this Handbook.
4 Governance Mandatory Due Process-Activities
Quorum of attendance and decision-making
4.1Section 5 of the UKEB's ToR sets out, amongst other requirements, the quorum for the UKEB Board (thereafter 'Board') meetings. This requires that a minimum of sixty percent of the appointed members (including the UKEB Chair as an appointed member) must attend a meeting of the Board (ToR, paragraph 5.1).
Voting process for endorsement decisions
4.2A decision to adopt a standard or amendment to a standard or an IFRS Interpretations Committee's interpretation must be made at an UKEB public Board meeting by at least two-thirds of the Members, including the Chair as an appointed member (ToR, paragraph 5.2). However, decisions made at an UKEB public Board meeting are indicative only. These decisions must be formalised by circulation outside the meeting by a written vote (in paper or electronic form) and the vote constitutes proper evidence of the decisions of members of the Board (including the UKEB Chair as an appointed member). Each member of the Board has one vote.
4.3Following the conclusion of a final written vote, in relation to the decision in paragraph 4.2, the UKEB Chair shall make public the outcome of that vote within 3 working days. Publication of the results of the vote on a standard or part standard will, where the result is to adopt a standard in whole or in part, constitute the adoption of that standard by the UK Endorsement Board, on a date specified by the UK Endorsement Board: (ToR, paragraph 5.3).
4.4Where the vote to adopt a standard or amendment or interpretation does not reach the required majority, the UKEB Chair may, after consultation with external parties including BEIS, choose to ask the Board to return to the vote. This may include asking the Board to vote on part of the standard, amendment or interpretation if it appears that this will have the required support. A subsequent decision to adopt the part standard or part amendment to a standard or part interpretation must be made by at least two-thirds of the Members (ToR, paragraph 5.4).
4.5Where a vote by the Board to adopt a standard, amendment, or interpretation, in whole or in part, has failed to reach the required majority and, in the opinion of the UKEB Chair, there is no prospect of such majority being reached, the UKEB Chair must provide a written explanation of circumstances to the Secretary of State within 10 working days of the failure to adopt. The Secretary of State may require further evidence. The Chair must inform members of the Board of any recommendations by the Secretary of State (ToR, paragraph 5.5).
Voting process for non-endorsement decisions
4.6Non-endorsement decisions such as approving a comment letter to be submitted to the IASB or a decision to approve the publication of a UKEB research outputs do not require a formal written vote by the Board. They require the support of a simple majority of the Board members present at the meeting, with approval given in a public meeting.
Transparency of meetings and stakeholder observers
4.74.34.7The UKEB's ToR set out the operating procedures that the UKEB applies in carrying out its responsibilities. Those procedures include the frequency and form of Board meetings (in Section 6 of the ToR), as well as rules for observers attending these meetings (in Section 7 of the ToR).
4.84.44.8The Board may hold meetings in person, by webcast, or by telephone or other similar means. In deciding the format of meeting, the UKEB Chair should take into consideration public access and attendance (ToR paragraph 6.2).
4.94.54.9Regular meetings of the Board are planned as far in advance as is practicable to help the UKEB Secretariat (thereafter ‘Secretariat'), members of the Board, official observers (with speaking rights) of the Board, and stakeholders, prepare for those meetings. The meetings calendar is published on the UKEB website and is updated regularly.
4.104.64.10 Meetings will usually be held in public and open to attendance by members of the public (as non-speaking observers). However, the Board may hold certain discussions in private or in the presence of invited observers with speaking rights only. For instance:
- Meetings held to discuss administrative issues and other non-technical matters (ToR paragraph 5.6); or,
- Education sessions held before public Board meetings, for example, to enable Board members to improve their understanding of new or complex proposals or standards or seek clarification about technical matters in staff papers.
4.114.74.11 Only Board members and observers with speaking rights will have the right to speak at Board meetings. The UKEB Chair may invite others to attend meetings as advisors when specialised input is required. Such personsand may be invited to speak at all or part of any meeting, as and when appropriate. (ToR, paragraph 7.2).
4.124.84.12 Only public meetings are recorded and, whenever practicable, webcast live. Recordings of public meetings are made available on the UKEB website.
Minutes from Board Meetings
4.134.94.13 Section 9 of the UKEB's ToR sets out the requirement to minute the meetings and any resolutions decided by the UKEB to keep stakeholders informed about the UKEB's activities. Minutes are a summary of the main tentative decisions reached at a Board meeting and/or main areas of Board discussion.
4.144.104.14 The Secretary to the UKEB (i.e. the Operations Director, or their nominee) minutes the meetings and resolutions of the UKEB, including recording the names of those present and in attendance. (ToR paragraph 9.2).Minutes from the public and private Board meetings are approved by Board Members.
4.154.114.15 The minutes for each Board meeting are circulated to all UKEB Members for approval and once approved Minutes for each Board meeting are published and made available on the UKEB website as soon after the meeting as practicable and usually within 10 working days following the meeting (ToR paragraphs 9.2–9.3). The Secretariat is responsible for ensuring that the minutes reflect the Board's decisions at each meeting. The minutes serve also to inform interested parties about the progress made on technical projects in a timely manner.
UKEB Secretariat papers
4.164.124.16 Section 8 of the UKEB's ToR sets out requirements for the notice of meetings and Secretariat papers.
4.174.134.17 The Secretariat is responsible for developing papers with recommendations and supporting analysis of technical issues for consideration by the members of the Board.
4.184.144.18The objective of the papers is to provide enough information for members of the Board to make informed decisions on technical matters. In developing these papers, the Secretariat is expected to conduct research and to seek advice from members of the Board. However, recommendations ultimately reflect Secretariat's views, after consideration of the information obtained.
4.194.154.19The Board agenda and Secretariat papers for each public meeting are usually made available on the UKEB website no later than 5 working days, before they are scheduled for discussion at a Board meeting (ToR, paragraph 8.3). This is to allow Board members enough time to consider and assess the Secretariat's recommendations. It is the responsibility of the UKEB members to assess whether they have sufficient information and time to be able to make decisions based on Secretariat's recommendations. Secretariat papers may have to be distributed closer to the meeting date, in exceptional circumstances only, and with the prior approval of the UKEB Chair. For example, if an urgent issue has arisen.
4.20Also, only in exceptional circumstances, and taking into consideration the Guiding Principles, the UKEB Chair may, at their absolute discretion, decide that all or part of certain Secretariat papers used for discussion by the Board at public meetings should not be made publicly available (ToR, paragraph 8.4). This may be, for example, if releasing that information could breach UK law, commercial confidentiality or prejudice the conduct of public affairs. However, such circumstances are expected to be rare.
4.214.164.21 Secretariat papers used for discussion by the Board at private Board meetings are not made publicly available.
4.224.174.22 The Secretariat may supplement papers orally at a Board meeting, for example, to provide an update on recent events.
Consultation with stakeholders
4.234.184.23The UKEB operates transparently and gives fair consideration to the issues raised by UK stakeholders, and influences early in the development of international accounting standards by conducting timely outreach activities and regular consultations with stakeholders (ToR paragraph 3.2(d)(ii)). This ensures stakeholders' concerns are heard and addressed and builds robust and evidence-based recommendations in line with the UKEB's influencing strategy. It also undertakes consultation with stakeholders relating to the endorsement and adoption of IASB standards or amendments and for its thought leadership and research programme.
4.244.194.24The UKEB consults with stakeholders that represent different communities, (i.e. users, preparers, academics, accounting firms, accounting bodies and regulators) to gather their inputs, views, opinions and feedback on specific projects or technical matters.
4.254.204.25 The UKEB consults stakeholders:
- on IASB's proposals for comment on proposals for new or amended international accounting standards (refer to Section 5—Influencing process) or on the IASB's research work (i.e. Discussion papers, Research papers or Requests for Information);
- before endorsing and adopting a new or amended international accounting standard in the UK13 (refer to Section 6 – Endorsement process);
- on UKEB's research work in line with its guiding principle of accountability and thought leadership (refer to Section 7—Thought Leadership and the Research programme);
- on IASB's requests for information: for example, those issued for post-implementation reviews (refer to Section 8—Post-implementation reviews);
- on UKEB's post-implementation review work (refer to Section 8—sub-section on “Processes for a UKEB Post-implementation review"); and
- on tentative agenda decisions or Draft IFRIC Interpretations issued by the IFRS Interpretations Committee (refer to Section 10—Influencing the IFRS Interpretations Committee's activities).
Keeping stakeholders informed
4.264.214.26 As a part of the guiding principle of transparency (ToR paragraph 4.4), the UKEB is committed to keeping its stakeholders and the general public informed about its activities. The principal means of communication between the UKEB and its stakeholders is through public meetings on technical issues, and the posting of relevant information and documents on the UKEB website.
4.274.224.27 In particular, the UKEB publishes on its website:
- its work plan, its meeting schedules and agenda;
- its progress on individual projects or Board's deliberations and compliance with due process by posting:
- public Secretariat papers discussed at public Board meetings;
4.194.24 The UKEB consults with stakeholders that represent different communities, (i.e. users, preparers, academics, accounting firms, accounting bodies and regulators) to gather their inputs, views, opinions and feedback on specific projects or technical matters.
4.204.25 The UKEB consults stakeholders:
- on IASB's proposals for comment on proposals for new or amended international accounting standards (refer to Section 5–Influencing process) or on the IASB's research work (i.e. Discussion papers, Research papers or Requests for Information);
- before endorsing and adopting a new or amended international accounting standard in the UK13 (refer to Section 6 – Endorsement process);
- on UKEB's research work in line with its guiding principle of accountability and thought leadership (refer to Section 7–Thought Leadership and the Research programme);
- on IASB's requests for information: for example, those issued for post-implementation reviews (refer to Section 8–Post-implementation reviews);
- on UKEB's post-implementation review work (refer to Section 8–sub-section on “Processes for a UKEB Post-implementation review"); and
- on tentative agenda decisions or Draft IFRIC Interpretations issued by the IFRS Interpretations Committee (refer to Section 10–Influencing the IFRS Interpretations Committee's activities).
Keeping stakeholders informed
4.214.26 As a part of the guiding principle of transparency (ToR paragraph 4.4), the UKEB is committed to keeping its stakeholders and the general public informed about its activities. The principal means of communication between the UKEB and its stakeholders is through public meetings on technical issues, and the posting of relevant information and documents on the UKEB website.
4.224.27 In particular, the UKEB publishes on its website:
- its work plan, its meeting schedules and agenda;
- its progress on individual projects or Board's deliberations and compliance with due process by posting:
- public Secretariat papers discussed at public Board meetings;
minutes of the Board's main decisions at its meetings after approval by the Board (see ToR, paragraph 9.2); each public and private meetings-and- recordings of public Board meetings; and
materials relating to advisory group meetings and other project-related information.- media and information releases relating to its activities;
- any IASB consultation documents open for comment by providing links to these documents on the IASB's website;
- the formal comment letters submitted to the UKEB where the respondent has not requested confidentiality; and
- access to educational materials or webinars.
5 Influencing process
Setting up a Technical work plan
5.1 The UKEB's due process influencing process begins with a technical work plan. This plan comprises the set of technical projects the UKEB manages.
5.2 The UKEB's technical work plan includes:
- technical issues identified by the IASB and by its IFRS Interpretations Committee (hereafter, Interpretations Committee)14; and
- other technical issues (refer to Section 7–Thought Leadership and the Research programme).
5.3 Technical issues identified by the IASB are added to the UKEB's technical work plan. As a starting point, the UKEB assumes that where a technical issue is significant enough to be added to the IASB's technical work plan, similar issues exist in the UK.
5.4 The UKEB's technical work plan is updated regularly to reflect estimated project timelines based on recent Board's decisions. It is presented for approval at the Board to approve at each-private meetings and. Once approved, it is uploaded onto the UKEB website. The UKEB's technical work plan is updated regularly to reflect estimated project timelines based on recent Board's decisions and made available on the UKEB website.
The technical work plan is presented for the Board to approve at each private meeting. Once approved, it is uploaded onto the UKEB website. The work plan is regularly updated to reflect any changes made based on Board decisions.
Prioritising technical projects
5.5 In prioritising individual projects and allocating resources to them, the level of activities should be proportionate to the issue being addressed. To help assess the issue, the Board considers various factors, including:
- the importance of the issue to UK stakeholders (i.e. users, preparers, academics, accounting firms, accounting bodies and regulators, and others interested in financial reporting);
- the effect an issue has or is expected to have on UK entities using UK-adopted international accounting standards, including both the number of entities affected and the size of the effect—
whether the issue has or is expected to have a minoranan effect on a large number of UK entities or a significant effect on a small number of UK entities using UK-adopted international accounting standards; - interactions with other current or proposed projects on the work plan;
- the urgency of the issue; and
- the availability of staff resources.
5.6 The assessment is not limited to using the IASB's assessment of the potential impact of a project as the UKEB's remit is different. The IASB considers the potential impact on many jurisdictions whereas the UKEB is assessing the potential impact from a UK perspective. This may mean that in the UK we allocate a different significance for a project when compared with the IASB. For example, where UK entities do not undertake the types of transactions addressed in an IASB project, the project would be allocated a lower significance and a reduced number of outreach activities would be planned.
Overview of the influencing process
5.7 The mandatory milestones expected to be achieved for most influencing projects (except for the situations explained in paragraph 5.10) are:
- Project initiation plan (mandatory).
- Desk-based research.
- Outreach activities (including reduced mandatory outreach activities in exceptional circumstances).
- Draft comment letter.
- Final comment letter (mandatory).
- Project closure, including Feedback Statement (mandatory) and Due Process Compliance Statement (mandatory).
5.8 The mandatory milestones will ensure the UKEB adheres to its guiding principles of accountability, independence and transparency. Other milestones (those not labelled as “mandatory”) may be considered for most projects and included in the project plan proportionate to the nature of the issue and the expected timeline.
5.9 Other stepsmilestones are not mandatory. It is expected that they will be undertaken for most projects dependent on the nature of the issue being addressed and the expected timeline. The activities undertaken to achieve the milestones in paragraph 5.75.8 should be proportionate to the technical issue(s) being addressed and will depend on its significance for UK stakeholders and on its complexity (i.e. nature or scope). Examples where the proportionate approach could apply are:For example:
- it is expected that for 'major' projects or for complex projects with major amendments, the activities undertaken would be far more extensive than for other 'minor' projects (i.e. amendments that meet the IASB's criteria for annual improvements or for narrow-scope amendments15), where some activities such as desk-based research or outreach activities may be somewhat more limited.
- The public consultation for proposed annual improvements or for a narrow-scope amendment may be limited to an issues paper on the UKEB website, with an associated news alert.
- Whereas, The consultation for a tentative agenda decision, may be undertaken only with a selected group or number of stakeholders.
For 'urgent' amendments and for tentative agenda decisions issued by the Interpretations Committee the milestones in paragraph 5.8 are not mandatory due process steps because achieving those milestones may not always be possible. For example, making a draft comment letter available for consultation may not be possible and instead, consultation with a representative group of stakeholders and/or consulting with members of the UKEB's standing and/or ad-hoc advisory groups may be appropriate. However, the Secretariat should explain what steps will be undertaken and why some steps are being omitted, for Board approval.
Project Initiation Plan (mandatory)
5.85.10 For a technical project to be incorporated into the UKEB's work plan, a “Project Initiation Plan" (PIP) is prepared for approval by the Board.
5.11 The objective of the PIP is to assess the potential impact and scale of the proposals being addressed as part of the project and, consequently, the level of analysis and outreach that should be undertaken.
5.12 The PIP outlines the approach to the project, including
- a description of the project objective and proposed timeline;
- a description of mandatory milestones and planned activities that will be undertaken to achieve those milestones;
- the amount of desk-based research, outreach, key milestones, proposed timeline, available and required resources for the project (including whether those resources are already allowed for in the annual plan or budget);
resources, objectives, and - expected output (i.e. draft/final comment letter to the IASB); and
- if applicable, the factors considered to justify departing from the standard consultation period for a Draft comment letter (refer to paragraph 5.27 below).
- For a draft comment letter the PIP should state very clearly the factors considered to justify departing from "standard" consultation periods (refer to paragraph 5.27 below). The activities described in the PIP planned to be undertaken to achieve milestones should be described in the PIP and be proportionate to the issue being addressed. This approach should help ensure an appropriate level of resource is allocated to each project. Examples of where the proportionate approach could apply are:
- The public consultation for a proposed annual improvements or for a narrow-scope amendment may be limited to the publication of a draft comment letter or an issues paper on the UKEB website, with an associated news alert.
- The public consultation for a tentative agenda decision, may be undertaken only with a selected group or number of stakeholders, rather
due to the time constraint.
5.13 A PIP must be prepared for each project and discussed, revised as directed and approved by the Board in a public meeting. For projects that meet the IASB's criteria for annual improvements or for a project that is not categorised by the IASB as an annual improvement or as a narrow-scope amendment is discussed, revised as directed and approved by the Board in a public meeting as a separate agenda item. For an IASB project that is a narrow-scope amendments, a PIP is prepared but is tabled for noting, thereby giving Board members the opportunity to discuss it. The Board can then determine whether any individual annual improvement and/or narrow-scope amendment included in a group being considered together-included in the PIPit should be discussed as a separate agenda item. For all other projects approval of the PIP is tabled as a separate agenda item.
5.14 If changes arise subsequent to commencement of a project, for example, as a result of the input received from outreach activities, the project PIP can be updated to address those changes.
5.95.15 The project plan included in the PIP forms the basis for compliance with the due process steps set out in this Handbook (refer to paragraph 11.2(c) in this Handbook).
Desk-based research
5.105.16 Desk-based research is undertaken to assist with the assessment of proportionality and to gather evidence on the issue. This will usually include a review of the IASB's previous work on this issue. It may also include, for example, a review of literature, academic papers, financial statements or of past papers or reports (by other national standard-setters or by other stakeholders (i.e. users, preparers, academics, accounting firms, accounting bodies and regulators). Additionally, the UKEB could liaise with national standard-setters who have carried out influencing activities or are in the process of performing such activities on the same (or related) project.
Outreach activities
5.115.17 The UKEB promotes awareness and generally responds to all IASB projects that are relevant to the UK.
5.18 Outreach activities will be proportionate to the significance and complexity (i.e. nature or scope) of the project (i.e. relevant standard or amendment).
5.125.19 The amount of outreach to be undertaken, together with the rationale, will be highlighted in the PIP.
Reduced mandatory outreach activities in exceptional circumstances
5.20 In exceptional circumstances, e.g. for an urgent narrow-scope amendment issued by the IASB where it shortens the comment period for an Exposure Draft from its usual 120 days, the UKEB will have limited time to consult.
5.21 Therefore, the Board may decide against issuing a draft comment letter or issue a draft comment letter with a comment period shorter than 30 days, and/or determine that the minimum outreach it undertakes will be to directly consult with a representative group of stakeholders. This will usually be with members of the UKEB's standing and/or ad-hoc advisory groups.
Another situation where there is a limited time to consult would be for tentative agenda decisions issued by the IFRS Interpretations Committee. This is because the usualstandard standard consultation period is 60 days, giving the UKEB very limited time in which to consult. In this situation, the minimum outreach is consulting with a representative group of stakeholders.
Outreach activities in normal circumstances
5.135.22 In normal circumstances the The outreach that the UKEB undertakes might include:
- convening and obtaining input from standing advisory groups and/or ad-hoc advisory groups 16;
- meetings and/or interviews with stakeholders (i.e. including users, preparers, academics, accounting firms, accounting bodies and regulators);
- undertaking fieldwork (see below);
- consultation on draft comment letter (see below);
the commissioning of external economic studies (i.e. data gathering and analysis conducted by external consultants to assess aspects of the economic impact of a standard on the UK); and- arranging informal meetings with IASB members and/or staff and their participation in UK outreach events.
5.145.23 Liaison with the IASB when undertaking outreach on an IASB due process document, e.g. an Exposure Draft, can enhance the efficiency and effectiveness of the UKEB's work. Examples of benefits could include:
- enhanced credibility and attraction of outreach events if conducted jointly with the IASB; and
- greater insight into technical issues.
5.155.24 The UKEB will maintain full transparency about its interaction with the IASB and other stakeholders. Steps will include:
- maintaining a public register of meetings between senior staff and Board members of the IASB and of the UKEB; and
- being transparent about the sources of information used in UKEB material.
Fieldwork
5.165.25 Fieldwork can be undertaken in a variety of ways and could include, but is not limited to:
- Surveys—organised to gather data, information, and facts on a specific subject;
- Field tests—include testing the application of technical proposals as if they were already in effect, in order to assess the understandability of the requirements and/or the resulting implementation issues. Field tests can be based on, for example:
- the completion of case studies;
- asking participants to assess how a technical proposal would apply to actual transactions;
- asking users how they process information; or
- assessing how accounting systems may be affected;
- Workshops or interviews—bring interested parties together and allow for in-depth analysis (for example to assess how technical proposals might be interpreted or applied) or to ensure the correct understanding of the results of a survey or field test.
- Public events—meetings with a larger number of interested stakeholders and organisations to listen to, and exchange views on, specific topics. These could take the form of roundtables, discussion forums, webinars and webcasts. These public events provide stakeholders with the opportunity to better understand and present their views on developing proposals.
Draft comment letter
5.185.27 A draft comment letter, explaining the UKEB's preliminary response to an IASB's or an IFRS Interpretations Committee's consultation document (refer to Appendix B in this Handbook) is made available for public consultation on the UKEB website once approved by the Board. This letter is normally preceded or accompanied by an Invitation to Comment that sets out the matters on which feedback is sought. The minimum-standard standard consultation period for a Draft Comment letter is not less than 30 days 4 weeks 30 days (four weeks) unless there are exceptional circumstances (see paragraphs 5.20–5.21).
5.19 For 'urgent' amendments making a draft comment letter available for consultation may not be possible and instead, consultation with a representative group of stakeholders and/or consulting with members of the UKEB's standing and/or ad-hoc advisory groups may be appropriate.
Final comment letter (mandatory)
5.205.28 The UKEB considers the stakeholder feedback received on the draft comment letter or from other outreach undertaken and uses this input to issue a final version of the comment letter to the IASB. The final comment letter is submitted to the IASB and posted on the UKEB website, along with tThe the formal comment letters submitted to the UKEB (where the respondent has not requested confidentiality) are also posted on the UKEB websiteand the Feedback Statement (see section below).
Project closure
Feedback statements (mandatory)
5.215.29 Input and feedback received on a draft comment letter (and any other input and feedback derived from other outreach activities) is recorded, assessed, the evidence evaluated, and reported in a Feedback Statement.
5.225.30 The purpose of a Feedback Statement is to inform stakeholders how the UKEB has responded to, or has addressed, the main comments or views received from stakeholders who participated in a specific outreach events or submitted comment letters on a specific project.
5.235.31 A Feedback Statement demonstrates the UKEB's adherence to its overarching guiding principles as follows:
- Accountability to stakeholders who submitted comment letters and/or participated in outreach, to the FRC as oversight body, and others, that the UKEB is taking account of stakeholders' views and fulfilling its due process obligations.
- Transparency about how the main comments or views have been addressed.
- Independence in that the UKEB acts in the UK's long term public good and is independent in its assessment of comments or views received from stakeholders and in determining the content of its final comment letter to the IASB.
5.245.32 Although the objective of all Feedback Statements is the same, the form and content will be proportionate to the objective of the underlying document, e.g. Discussion Papers have different objectives from Exposure Drafts. In general, a Feedback Statement includes the following content:
- an objective;
- a brief description of technical IASB's proposal(s), i.e. summary background;
- an explanation of the main feedback received through comment letters or other fieldwork or outreach activities;
- a description of the UKEB's response (i.e. how comments or views received from stakeholders have been addressed); and
- a summary of the sources of stakeholder comments, e.g. from individual stakeholder meetings, formal responses to draft comment letters or via other outreach events.
5.255.33 The Board discusses and provides comments on a draft Feedback Statement and approves the final Feedback Statement for publication.
5.265.34 A Feedback Statement is published on the UKEB website, usually at the same time as the final comment letter is submitted to the IASB is submitted. In exceptional circumstances, e.g. to meet a curtailed comment deadline for an urgent project, it may not be possible to for the Secretariat to present a Feedback Statement at the same meeting as the approval of the final comment letter. In this situation, it is presented for Board approval as soon as practicable.
Due Process Compliance Statement (mandatory)
5.275.35 The Secretariat summarises the due process activities undertaken in a closing control report called “Due Process Compliance Statement". For a description and content of this Statement refer to paragraph 11.2 in Section 11 of this Handbook.
6 Endorsement process
UK Statutory requirements for endorsement and adoption
6.1 New or amended international accounting standards issued by the International Accounting Standards Board (IASB) are not part of UK-adopted international accounting standards until the UKEB has endorsed and adopted those standards17.
6.2 The primary objective of endorsing and adopting international accounting standards for use in the UK as set out in SI 2019/68518 is to harmonise the financial information presented by relevant companies to ensure:
- a high degree of transparency and international comparability of financial statements; and
- the efficient allocation of capital, including the smooth functioning of capital markets in the United Kingdom.
6.3 The regulatory power embodied in the UKEB's endorsement and adoption function lends weight and authority to the UKEB's influencing activity.
6.4 The UKEB adopts international accounting standards for use within the UK, in accordance with regulations 6–9 in SI 2019/685 (these Regulations are described below).
6.5 Regulation 7—requires that an international accounting standard only be adopted if:
- "the standard is not contrary to either of the following principles—
- an undertaking's accounts must give a true and fair view of the undertaking's assets, liabilities, financial position and profit or loss;
- consolidated accounts must give a true and fair view of the assets, liabilities, financial position and profit or loss of the undertakings included in the accounts taken as a whole, so far as concerns members of the undertaking;
- the use of the standard is likely to be conducive to the long term public good in the United Kingdom; and
- the standard meets the criteria of understandability, relevance, reliability and comparability required of the financial information needed for making economic decisions and assessing the stewardship of management.”
6.7 Regulation 6—permits the adoption of a standard in part only and/or to extend an option available as part of a standard. The Regulation states that this may occur “in exceptional circumstances”. Regulation 6(3)(b) indicates that the amended standard (i.e. the part-adopted standard) would need to meet the endorsement criteria set out in Regulation 7.
6.8 Regulation 9—sets out the requirement to publish a final decision on adopting a new or amended international accounting standard.
Overview of UKEB endorsement and adoption process
6.9 The UKEB applies its own process before it decides to endorse and adopt a new or amended international accounting standard. This process is to ensure the Board fulfils its statutory responsibilityies responsibilities relating to endorsement and adoption of international accounting standards (described set out in paragraphs 6.2-6.86.2–6.8) for the endorsement and adoption of an IASB standard or amendment into UK-adopted international accounting standards. This process takes place after a new or amended standard has been issued by the IASB and before the standard is effective. This process is described below.
6.10 The mandatory milestones expected to be undertaken for most endorsement and adoption projects (except for the situations explained in paragraph 6.12) are:
- Project initiation plan (mandatory).
- Desk-based research.
- Public consultation on a draft Endorsement Criteria Assessment (DECA) (mandatory).
- Outreach activities (including reduced mandatory outreach activities in exceptional circumstances).
- Project closure, including vote on adoption, including with the following documents:
- Final Endorsement Criteria Assessment (ECA) (mandatory).
- Feedback Statement (mandatory).
- Due Process Compliance Statement (mandatory).
- Adoption Statement (mandatory).
- Publication of the documents set out in (e) (mandatory).
6.12 Other steps are not mandatory. It is expected that they will be undertaken for most projects dependent on the nature of the issue being addressed and the expected timeline. The activities undertaken to achieve the milestones in paragraph 6.10 should be proportionate to the technical issue(s) being addressed and will depend on its significance for UK stakeholders and on its complexity (i.e. nature or scope). For example, it is expected that for 'major' projects or for complex projects with major amendments, the activities undertaken would be far more extensive than for other 'minor' projects (i.e. amendments that meet the IASB's criteria for annual improvements or for narrow-scope amendments), whereas for which some activities (i.e. desk-based research or outreach activities) may be more limited.
6.11 For 'urgent' amendments or 'minor' amendments that meet the IASB's criteria for annual improvements or for narrow-scope amendments the milestones in paragraph 6.10 are not mandatory due process steps. This is because for 'minor' amendments the outreach activities may be mainly focused on obtaining responses on the Draft Endorsement criteria Assessment (DECA). For urgent amendments, making a DECA publicly available on the UKEB website for consultation may not be possible, and instead, consultation with a representative group of stakeholders and/or consulting with members of the UKEB's standing and/or ad-hoc advisory groups may be appropriate19. However, the Secretariat should explain what steps will be undertaken and why some steps are being omitted, for Board approval.
Project Initiation Plan (mandatory)
6.126.13 For a new or amended international accounting standard to be endorsed and adopted by the UKEB, a “Project Initiation Plan” (PIP) is prepared for approval by the Board.
6.14 The objective of the PIP is to assess the potential impact and scale of the new or amended standard and, consequently, the level of analysis and outreach that should be undertaken.
6.15 The PIP outlines the approach to the project, including:
- a description of the project objective and proposed timeline;
- a description of mandatory milestones and planned activities that will be undertaken to achieve those milestones;
- available and required resources for the project (including whether those resources are already allowed for in the annual plan or budget);
- expected output (i.e. draft/final Endorsement Criteria Assessment); and
- If applicable, the factors considered to justify departing from the standard consultation period for a draft Endorsement Criteria Assessment (refer to paragraph 6.24 below).
~~
- the amount of desk-based research, outreach, key milestones, proposed timeline, available and required resources for the project (and whether those resources are already allowed for in the annual plan or budget), objectives and
expected output (i.e. draft/final Endorsement Criteria Assessment). The activities described in the PIP planned to be undertaken to achieve milestones should be proportionate to the standard or amendment under consideration for adoption. This approach should help ensure an appropriate level of resource is allocated to each project.
6.16 A PIP must be prepared for each project and discussed, revised as directed and approved by the Board in a public meeting. For projects that meet the IASB's criteria for annual improvements or for narrow scope amendments, a PIP is prepared but is tabled for noting, thereby giving Board members the opportunity to discuss it. The Board can then determine whether any individual annual improvement or narrow-scope amendment included in a group being considered together should be discussed as a separate agenda item. for a project that is not categorised by the IASB as a narrow-scope amendment (or as an annual improvement) is discussed, revised as directed and approved by the Board in a public meeting as a separate agenda item. For an IASB project that is a narrow-scope amendment (or an annual improvement), a PIP is tabled for noting, thereby giving Board members the opportunity to discuss it. The Board can then determine whether it should be discussed as a separate agenda item
6.17 If changes arise subsequent to commencement of a project, for example, as a result of the input received from outreach activities, the project PIP can be updated to address those changes.
6.18 The project plan included in the PIP forms the basis for compliance with the due process steps set out in this Handbook (refer to paragraph 11.2(c) in this Handbook).
Desk-based research
6.136.19 Desk-based research is undertaken to assist with the assessment of proportionality and to gather evidence on the issue. This will usually include a review of the UKEB's earlier work on influencing activities and responses received, as well as IASB's previous work on this issue. It may also include, for example, a review of literature, academic papers, financial statements or of past papers or reports (by other national standard-setters or by other stakeholders (i.e. users, preparers, academics, accounting firms, accounting bodies and regulators) as well as liaising with national standard-setters who have endorsed or are in the process of endorsing the same new or amended standard.
Draft endorsement criteria assessment (DECA) (mandatory)
6.146.20 The UKEB endorsement criteria is set out in paragraph 6.5 of this Handbook.
Content
6.156.21 In general, a DECA considers and addresses the following:
- Introduction: legislative framework and approach to the assessment:
- Purpose of the DECA;
- Summary and explanation of legislative background to endorsement criteria; and
- Description of endorsement criteria (including text of criteria from SI 2019/685) and what is meant by each criterion;
- Rationale for the new or amended international accounting standard, i.e. summary background, context and objectives and main accounting requirements;
- Technical criteria assessment:
- whether the standard meets the criteria of relevance, reliability, comparability and understandability required of the financial information needed for making economic decisions and assessing the stewardship of management (SI 2019/685 Regulation 7(1)(c)); and
- whether the standard is not contrary to the principle that an entity's accounts must give a true and fair view (SI 2019/685 Regulation 7(1)(a)).
- Whether use of the new or amended standard is likely to be conducive to the long term public good in the UK (SI 2019/685 Regulation 7(1)(b)), including:
- whether the use of the standard is likely to improve the quality of financial reporting;
- the costs and benefits that are likely to result from the use of the standard; and
- whether the use of the standard is likely to have an adverse effect on the economy of the UK, including on economic growth.
6.166.23 A DECA is made available for public consultation on the UKEB website. In exceptional circumstances for an urgent amendment this may not be possible and instead, consultation with a representative group of stakeholders, and/or consulting with members of the UKEB's standing and/or ad-hoc advisory groups may be appropriate. However, the Secretariat should explain what steps will be undertaken and why some steps are being omitted, for Board approval.
6.176.24 The minimum-standard standard consultation period is not less than 90 days 4 weeks 90 days (four weeks) unless there are exceptional circumstances (see paragraph 6.27). During this period, technical staff conductsthe Secretariat conducts outreach activities to gather input and feedback. In exceptional circumstance, for example, where an amendment is urgently required to be adopted by entities, the Board may approve a shorter comment period.
Outreach activities
6.186.25 Outreach activities will be proportionate to the significance and complexity (i.e. nature or scope) of the project (i.e. relevant standard or amendment) and may be undertaken throughout the endorsement assessment period.
6.19 For example, in the case of the endorsement of annual improvements or narrow-scope amendments, outreach activities are targeted to obtain sufficient responses on the DECA.
6.26 The amount of outreach to be undertaken, together with the rationale, will be highlighted in the PIP.
Reduced mandatory outreach activities in exceptional circumstances
6.27 In exceptional circumstances, e.g. for an urgent narrow-scope amendment issued by the IASB where it shortens the period between publication date and effective date of the Amendment20 and the amendment is urgently required to be adopted by entities, the UKEB will have limited time to consult on whether it is suitable for endorsement and adoption in the UK. Therefore, the minimum outreach it undertakes is to ensure that the DECA is available for public consultation (on the UKEB website) for a minimum of 14 days.
Outreach activities in normal circumstances
6.20 In exceptional circumstances, for urgent amendments, making a DECA available for consultation may not be possible, and instead, consultation with a representative group of stakeholders and/or consulting with members of the UKEB's standing and/or ad-hoc advisory groups may be appropriate.
6.216.28 In normal circumstances, For more complex projects that include major amendments, the UKEB may need or decide to conduct a larger number of additional outreach activities due to the nature and/or size of the amendment or standard to be endorsed and adopted and/or the response to consultation at the influencing stage. This is, for example, when:
- an amendment or standard changes an area of accounting that affects most UK entities applying UK-adopted international accounting standard; or
- an amendment or standard changes an area of accounting that affects a small number of UK entities applying UK-adopted international accounting standards but it is a major change.
6.29 The outreach activities that could be undertaken to gather input, views, opinions or feedback are the same as those described in section 5 of this Handbook (paragraphs 5.205.18–5.225.28). The level and content of the responses received during the influencing phase may also be relevant to deciding the level of outreach.
6.30 For 'minor' amendments that meet the IASB's criteria for annual improvements or for narrow-scope amendments the outreach activity may be focused solely on obtaining responses on the Draft Endorsement criteria Assessment (DECA).
Project closure
Voting on the adoption of a new or amended international accounting standard (mandatory)
6.226.31 The formal voting process by which Board members make a decision on the adoption of a new or amended international accounting standard are set out in the UKEB's Terms of Reference (Section 5, paragraphs 5.1–5.2).
6.236.32 Decisions on the endorsement and adoption of a standard or amendment are made at public Board meetings and follow the requirements of the UKEB's Terms of Reference as follows:
- Quorum attendance—a minimum of sixty percent of the appointed members21 are required to attend a meeting of the Board (ToR, paragraph 5.1).
- Decision-making—an affirmative written vote of at least two-thirds of all of the appointed Board members (ToR, paragraph 5.2), is required for the decision to be passed. Each member of the Board has one vote. A situation where the two-thirds majority cannot be obtained, may restart the endorsement and adoption process.
6.246.33 A “tentative” vote on the adoption of a new or amended international accounting standard is made at a public Board meeting and is indicative only. A formal written vote is required to endorse and adopt a new or amended international accounting standard. This vote is formalised by circulation outside the meeting by a written vote (in paper or electronic form), and the vote constitutes proper evidence of the decision of the members of the Board.
6.34 Where a Board member does not support the endorsement and adoption of a new or amended standard, that is reflected in their vote. If they wish, the reason for this view may be recorded in the minutes.
6.256.35 Publication of the outcome of the an affirmative formal written vote on UKEB website22 is accompanied by the following documents:
- a copy of the new or amended international accounting standard;
- a copy of the 'Adoption package' that includes:
- A final Endorsement Criteria Assessment (ECA);
- A Feedback statement;
- A Due Process Compliance Statement; and
- An Adoption statement.
Project closure
Voting on the adoption of a new or amended international accounting standard (mandatory)
6.226.31 The formal voting process by which Board members make a decision on the adoption of a new or amended international accounting standard are set out in the UKEB's Terms of Reference (Section 5, paragraphs 5.1-5.2).
6.236.32 Decisions on the endorsement and adoption of a standard or amendment are made at public Board meetings and follow the requirements of the UKEB's Terms of Reference as follows:
- Quorum attendance—a minimum of sixty percent of the appointed members21 are required to attend a meeting of the Board (ToR, paragraph 5.1).
- Decision-making—an affirmative written vote of at least two-thirds of all of the appointed Board members (ToR, paragraph 5.2), is required for the decision to be passed. Each member of the Board has one vote. A situation where the two-thirds majority cannot be obtained, may restart the endorsement and adoption process.
6.246.33 A “tentative” vote on the adoption of a new or amended international accounting standard is made at a public Board meeting and is indicative only. A formal written vote is required to endorse and adopt a new or amended international accounting standard. This vote is formalised by circulation outside the meeting by a written vote (in paper or electronic form), and the vote constitutes proper evidence of the decision of the members of the Board.
6.34 Where a Board member does not support the endorsement and adoption of a new or amended standard, that is reflected in their vote. If they wish, the reason for this view may be recorded in the minutes.
6.256.35 Publication of the outcome of the A an an affirmative formal written vote on UKEB website22 is accompanied by the following documents:
- a copy of the new or amended international accounting standard;
- a copy of the 'Adoption package' that includes:
- A final Endorsement Criteria Assessment (ECA);
- A Feedback statement;
- A Due Process Compliance Statement; and
- An Adoption statement.
Adoption package
6.276.36 The following paragraphs set out a description of the content of the individual documents included in the 'Adoption package'.
Final Endorsement Criteria Assessment (ECA) (mandatory)
6.286.37 The UKEB considers the stakeholder feedback received on the DECA and uses this input to issue a final version of the Endorsement Criteria Assessment (final ECA).
Feedback statement (mandatory)
6.296.38 Consultation feedback received on the DECA (and any other input and feedback derived from other outreach activities) is recorded, assessed, the evidence evaluated, and reported to the UKEB in a Feedback Statement.
6.306.39 The purpose of a Feedback Statement is to inform stakeholders how the UKEB has responded to, or addressed, the main comments or views received from stakeholders. It also demonstrates the UKEB's adherence to its overarching guiding principles (accountability, transparency, independence and thought leadership).
6.316.40 The form and content of the Feedback Statement will be proportionate to the objective of the underlying document-subject matter and would generally include the following content:
- an objective;
- summary background of the new or amended standard;
- an explanation of the main feedback received on the DECA, through comment letters or other outreach activities;
- a description of the UKEB's response (i.e. how comments or views received from stakeholders have been addressed in the final ECA); and
- a summary of the sources of stakeholder comments, e.g. from individual stakeholder meetings, formal responses to the DECA or via other outreach events.
6.326.41 The Board discusses and provides comments on a draft Feedback Statement and approves the final Feedback Statement for publication.
6.336.42 A Feedback Statement is published on the UKEB website, usually at the same time as the final ECA is finalised.
Due Process Compliance Statement (mandatory)
6.346.43 The Secretariat summarises the due process activities undertaken in a closing control report called “Due Process Compliance Statement". For a description and content of this Statement refer to paragraph 11.2 in Section 11 of this Handbook.
Adoption statement (mandatory)
6.356.44 The Adoption statement includes:
- a statement that the new or amended standard has been:
- adopted for use within the UK, in compliance with the requirements in Regulations 7 and 8 of SI 2019/685 and reasons for this decision; or
- been partially adopted in accordance with paragraph (3) of Regulation 6 of SI 2019/685 and any reasons for this decision;
- when applicable, reasons for extending the scope of undertakings eligible to use an option in the standard in accordance with paragraph (4) of Regulation 6, setting out the full details;
- a description of the financial years in respect of which that standard must be used; and
- the wording of the adopted standard (in a separate document).
Next step after the adoption of a new or amended standard
6.46 The UKEB website should provide an indication about whether the recently adopted (new or amended) standard meets the criteria for a post-implementation review and, if so, the timing of that review (refer to Chapter 8 of this Handbook).
7. Thought leadership and research programme
Objectives of thought leadership
7.1 As part of the guiding principle of thought leadership, paragraph 4.5 of the UKEB's ToR states that the UKEB is committed to:
- lead the UK debate on international accounting standards and reporting;
- participate pro-actively in the development of new global standards, for example by undertaking research;
- represent UK views in international fora with the aim of influencing debate; and
- engage with accounting, reporting, endorsement and adoption bodies in other jurisdictions, in order to improve influence and understand best practice.
Leading the UK debate
7.2 The UKEB ensures leads the UK debate on international accounting standards and reporting by ensuring that the views from UK stakeholders are heard and their needs understood during the development of new or amended international accounting standards.
7.3 The UKEB achieves this by:
- identifying key stakeholder groups, preparing outreach plans, and taking suitable approaches to each stakeholder group;
- giving UK stakeholders a platform to provide specialist input on areas of concern through roundtables, forums, workshops, panel discussions or education sessions organised by the UKEB or through the UKEB's advisory groups;
- soliciting UK stakeholders' comment on public consultation documents and/or UKEB's draft comment letters; and
- arranging, where appropriate, for IASB Board members and/or for IASB staff to participate in UKEB's outreach events to enable first-hand understanding of any concerns or views expressed by UK stakeholders; and
(d)(e) acting as a conduit for UK feedback on IASB consultations.
Participating proactively in the development of global standards
7.4 The UKEB proactively participates in the development of new global accounting standards by:
- engaging with UK stakeholders and collecting evidence on relevant technical issues (that may not be considered by the IASB or other national standard-setters);
- developing potential ways to improve or remedy deficiencies in international accounting standards; and
- working closely with others on long-term proactive work to stimulate debate on financial reporting matters on the IASB agenda at an early stage in the standard-setting process.
Representing UK views in international fora or in media with the aim of influencing debate
7.5 The UKEB directly influences the IASB Board and maintains a global presence on the international financial stage by:
- developing and presenting the UKEB's own thought leadership material to promote UK views and lead on the accounting debate at relevant international fora;
(a)(b) identifying and promoting the appointment of UK representatives to the IASB's consultative groups, subject to available UKEB resources. For example, to the IASB's Accounting Standards Advisory Forum (ASAF) to ensure that UK input on major technical issues related to the IASB's standard-setting activities is discussed and considered in this forum;
(b)(c) maintaining effective relationships, communication and presence with the IASB and other national standard-setters, subject to available UKEB resources. For example, by:- participating in the World Standard-Setters conference organised by the IASB to share international accounting standards implementation and application experiences with other standard-setters around the world;
- participating in other international accounting forums organised by other parties independently (e.g. International Forum of Accounting Standard-Setters (IFASS));
- regularly attending (in person or remotely) key meetings and conferences of international financial reporting bodies to ensure adequate analysis and input, including expressing UK views;
(c) developing and presenting the UKEB's own thought leadership material to promote UK views and lead on the accounting debate at relevant international fora;- communicating outcomes from international engagements to UK stakeholders, to assist in identifying concerns with international proposals; and
- issuing articles, podcasts or videos, to stimulate debate on a particular matter or technical issue. The Board does not express any opinion or tentative views on the matters presented in such papers or reports.
Engaging with other bodies in other jurisdictions
7.6 Regular contact between the UKEB and other national standard-setters in other jurisdictions can help increase the understanding, awareness and support for UK views, thereby, allowing the UKEB to lead on the accounting debate.
7.7 The UKEB and other national standard-setters can interact in a range of ways including developing joint thought leadership and research documents, regular and ad-hoc emails, conferences and roundtables, blogs, articles, regional forums or telephone exchanges.
Research programme
Objective
7.8 Research is generally directed to identify specific issues associated with projects that are on the UKEB's technical agenda. As such, research may be expected to have a problem-solving orientation by collecting evidence on the nature and extent of the perceived shortcomings of, and assessing potential ways to improve or to remedy a deficiency in international accounting standards.
7.9 This type of research helps the UKEB:
- identify a new research project that could potentially be included in the UKEB's work plan; er
- assist the IASB in the identification of a new technical issue (for example, in response to the IASB's five-yearly agenda consultation request) and in the analysis of potential solutions; or
(b)(c) provide effective technical input into IASB proposals forming part of IASB's current agenda.
7.10 Where resources are available, oOther more explorative research may also be performed by the UKEB to include the consideration of broader financial reporting matters, such as how financial reporting is evolving, and to encourage international debate on financial reporting matters. This type of research may be formally added to the UKEB's technical agenda.
7.11 Research may be undertaken by the UKEB on its own or collectively with others (i.e. national standard-setters, regulators, academics and other interested parties); the latter when there are topics of mutual interest.
Main outputs
7.12 The common categories of research primary outputs derived from the UKEB's research programme are explained in the table below:
- Discussion Papers, as documents that include an overview of specified technical issues, possible approaches to addressing these issues and preliminary/final views from the Board and an Invitation to Comment;
- Requests for Information or feedback on a matter related to technical projects or broader consultations. For example, seeking comments on the UKEB's technical work plan, post-implementation reviews, or help in assessing the practical implications of a potential financial reporting requirement;
- Research Papers, to contribute to wider discussions on cross-cutting issues in financial reporting;
- Bulletins, to promote and stimulate debate within the UK on specific accounting matters; or
(a)(e) Quantitative studies.
| Type | Discussion Paper | Research Paper | Request for Information |
|---|---|---|---|
| Issued by | The Board. | The Secretariat | The Board. |
| Description | A Discussion Paper includes a comprehensive overview of technical issues, possible approaches to addressing these issues and preliminary views from the Board | A Research Paper includes a comprehensive overview of technical issues. It may include possible approaches to addressing these | A Request for Information is a formal request for information or feedback on a matter related to technical projects or broader consultations. This includes seeking comments on the |
| Type | Discussion Paper | Research Paper | Request for Information |
|---|---|---|---|
| and an Invitation to Comment. | issues and preliminary views from the Secretariat and an invitation to comment. It is prepared by the Secretariat on its own. It may include collaborations from other national standard-setters or bodies. | UKEB's technical work plan, post-implementation reviews24, or help in assessing the practical implications of a potential financial reporting requirement. | |
| Reflects Board members' views? | Yes—Reflects the Board's analysis and collective view on a particular topic, although the discussion will reflect and convey any significant differences in Board members' views. | No—Reflects views from the Secretariat. | No—It is a request for information and does not reflect views from the Board or from the Secretariat. |
| Discussed at a public Board meeting? | Yes—The matters included in a Discussion Paper are discussed at public Board meetings. | Can be discussed at a public Board meeting to provide some input to the Secretariat. However, a Research Paper will not include any formal or preliminary views from the Board. | Yes—The matters included in a Request for Information are discussed at public Board meetings. However, a Request for Information will not include any formal or preliminary views from the Board. |
| Approval by the Board | To be published a Discussion Paper requires the affirmative vote of at least two-thirds of the members of the Board. The voting is made at a public Board meeting and is indicative only. The vote is formalised by circulation outside the meeting by a written vote (in paper or electronic form), and the vote constitutes proper evidence of the decision of the Board. | To be published a Research Paper requires the support of a simple majority of the full Board members, with approval given in a public meeting. | To be published a Request for Information requires the support of a simple majority of the full Board members, with approval given in a public meeting. |
Milestones
7.127.13 The mandatory milestones expected to be achieved for most research projects (except for the situation explained in paragraph 7.15) are:
- Identification of issues for research;
- Project initiation plan (mandatory);
- Desk-based research;
- Outreach activities;
- Approval of research document (mandatory);
(e)(f) Publication of research document (mandatory)a Discussion Paper, a Research Paper or a Request for Information; and- Project closure for research documents that invite stakeholder comments includes:
- 1) a Feedback Statement (mandatory); and
- Due Process Compliance Statement (mandatory). (for a Discussion Paper) a comment letter summary (for a Research Paper and for a Request for Information) and 2) a Due Process Compliance Statement (only required when issuing a Discussion Paper).
7.137.15 Other steps are not mandatory. It is expected that they will be undertaken for most projects dependent on the nature of the issue being addressed and the expected timeline. The activities undertaken to achieve the milestones in paragraph 7.13 should be proportionate to the issue(s) that are part of the UKEB's research and will depend on its significance for UK stakeholders and on its complexity (i.e. nature or scope). For example, it is expected that for 'major' research projects the activities undertaken would be far more extensive than for other 'minor' research projects where some activities such as desk-based research or outreach activities may be somewhat more limited.
7.14 For a Research Paper that is not requesting views or input from the public, the milestone in paragraph 7.13(f) is not a mandatory due process step.
Identification of issues for research
7.157.16 The Secretariat may identify or may receive proposals to research an issue (for example from academics) and submit research proposals to the UKEB Chair for consideration. Proposals may arise from the Secretariat's own research, from a Board member, from consulting with the UKEB's advisory groups or from comments and information gained from public hearings, fieldwork (refer to paragraphs 5.21-5.22 of this Handbook) as well as stakeholder comment letters.
Project Initiation Plan (mandatory)
7.167.17 For a research project to be incorporated into the UKEB's work plan, a “Project Initiation Plan" (PIP) is prepared for approval by the Board.
7.18 The objective of the PIP is to assess the potential impact and scale of the research project and, consequently, the level of analysis and outreach that should be undertaken.
7.19 The PIP outlines the approach to the project, including:
- a description of the project objective and proposed timeline;
- a description of mandatory milestones and planned activities that will be undertaken to achieve those milestones.
- the amount of desk-based research, outreach, key milestones, proposed timeline, available and required resources for the project (including whether those resources are already allowed for in the annual plan or budget);
- objectives, and expected research output (i.e. Research Paper, Discussion Paper, Request for Information, bulletin, quantitative study, etc); and
- if applicable, the factors considered to justify departing from the standard consultation period for a research document (refer to paragraph 7.28 below).
7.17 The activities described in the PIP should be proportionate to the issue being addressed. This approach should help ensure an appropriate level of resource is allocated to each project.
7.187.20 If the research is carried out collectively with other parties (i.e. national standard-setters, regulators, academics or others) then agreement on the following will be achieved before commencement of work:
- the responsibilities and expectations of each party involved, including expectations about use of the project output;
- whether the project will present only an analysis of the facts or whether it will contain views or recommendations; and
- the expected output (i.e. Research Paper, Discussion Paper or Request for Information), copyright and publication rights over the output.
7.21 If changes arise subsequent to commencement of a research project, for example, as a result of the input received from outreach activities, the project PIP can be updated to address those changes.
7.22 The project plan included in the PIP forms the basis for compliance with the due process steps set out in this Handbook (refer to paragraph 11.2(c) in this Handbook.
7.19 The UKEB usually allows a minimum of 90 days for comment on such a consultation. If the information request is narrow in scope and/or urgent the UKEB may set a shorter period.
Desk-based research
7.207.23 Desk-based research is undertaken to assist with the assessment of proportionality and to gather evidence on the issue. This will usually include a review of the IASB's previous work on this issue. It may also include, for example, a review of literature, academic papers, financial statements or of past papers or reports (by other national standard-setters or by other stakeholders (i.e. users, preparers, academics, accounting firms, accounting bodies, regulators or others), as well as liaising with national standard-setters who have who have performed or are in the process of performing research on the same (or related) project.
Outreach activities
7.217.24 Outreach is conducted with stakeholders that represent different stakeholder communities, (i.e. users, preparers, academics, accounting firms, accounting bodies and regulators) to gather their input, views, opinions or feedback on specific projects or technical matters.
7.227.25 The outreach activities that could be undertaken to gather input, views, opinions or feedback are the same as those described in section 5 of this Handbook (paragraphs 5.2018-5.2228).
Approval of a research document (mandatory)
7.26 The Board approves a research document for publication. It does not require a formal written vote by the Board. It requires the support of a simple majority of the Board members present at the meeting, with approval given in a public meeting.
Publication (mandatory)
7.27 A research document may not include an Invitation to Comment, e.g. a Bulletin explaining a specific accounting topic or a summary of outreach undertaken on a specific accounting topic.
7.28 Where a research document includes an Invitation to Comment, the minimumstandard consultation period is 90 days.
7.237.29 In exceptional circumstances, where the research document is on a topic that is narrow in scope and/or urgent the Board may set a shorter period. The rationale for a shorter comment period will be given in the PIP.
Discussion Papers
7.24 Board members make a decision at a public meeting about the publication of a Discussion Paper.
7.25 Decisions made at public Board meetings follow the requirements of the UKEB's Terms of Reference (Section 5, paragraphs 5.1-5.2 of the ToR):
- Quorum attendance—a minimum of sixty percent of the appointed members25 are required to attend a Board meeting. (ToR, paragraph 5.1).
- Decision-making—an affirmative vote of at least two-thirds of the appointed Board members (ToR, paragraph 5.2), is required for the decision to be passed. Each Board member has one vote.
7.26 A "tentative" vote on the publication of a Discussion Paper is made at a public Board meeting and is indicative only. A formal vote is required to approve the publication of a Discussion Paper. This vote is formalised by circulation outside the meeting by a written vote (in paper or electronic form), and the vote constitutes proper evidence of the decision of the members of the Board.
7.27 A formal written vote is accompanied by a copy of the Discussion Paper.
Research Papers and Requests for Information
7.28 Research Papers and Requests for Information do not require a formal written vote by the Board and only require the support of a simple majority of the full Board, with approval given in a public meeting.
Project closure
7.30 This section applies only to a research document that invites stakeholder comments.
Feedback Statement (mandatory required when issuing a Discussion Paper)
7.297.31 Input and feedback received on a research document Discussion Paper is recorded, assessed, the evidence evaluated, and then incorporated into the analysis and discussion of the technical issues in a “Feedback Statement”. For the objectives and content of this statement refer to paragraphs 5.29-5.34 in this Handbook.
Comment Letter Summary required when issuing a Research Paper or a Request for Information
7.30 Input and feedback received on a Research Paper or on a Request for Information is summarised in a "Comment Letter Summary".
7.31 In general, a Comment Letter Summary includes the following content:
- a brief description of the research project, i.e. summary background;
- an explanation of the main feedback received through comment letters or other fieldwork or outreach activities; and
- a summary of the sources of stakeholder comments, e.g. from individual stakeholder meetings, formal responses to research papers and/or requests for information or via other outreach events.
7.32 A Comment Letter Summary on a Research Project or on a Request for Information is discussed at a Board meeting and published on the UKEB website.
Due Process Compliance Statement (mandatory required for a Discussion paper)
7.337.32 For a research project that involves issuing a research document that invites stakeholder comments, Discussion Paper the Secretariat summarises the due process activities undertaken in a closing control report called “Due Process Compliance Statement". For a description and content of this Statement refer to paragraph 11.2 in Section 11 of this Handbook.
8. Post-implementation reviews
Introduction
8.1 A post-implementation review (PIR) assesses the effect of a new or amended international accounting standard or of a major amendment to an international accounting standard and determines whether:
- the requirements in international accounting standards result in reporting entities providing financial information that is useful in making informed economic decisions;
- there are any significant unexpected changes to financial reporting or operating practices resulting from the application of the international accounting standard;
- there are unexpected costs or challenges in applying the international accounting standard;
- there are any areas of the international accounting standard that represent interpretation challenges and, as a result, impair the consistent application of the international accounting standard; and
- the international accounting standard is understandable and it is being applied as intended, and whether preparers are able to report the information reliably.
Influencing IASB Post-implementation reviews
8.2 The UKEB's work on influencing the development of international accounting standards includes monitoring and responding to IASB post-implementation reviews of international accounting standards.
8.3 The IASB is required to conduct a post-implementation review of each new IFRS Standard or major amendment. This review normally begins after the new requirements
have been applied internationally for two years26. The IASB commences its post-implementation review with a Request for Information which sets out the initial identification and assessment of the matters to be examined.
8.4 The UKEB follows the influencing processes in Section 5 of this Handbook to respond to an IASB Request for Information.
8.5 In addition, the UKEB promotes awareness of IASB post-implementation reviews in the UK, and consults stakeholders and its advisory committees, asking them for input.
Processes for a UKEB Post-implementation Review
Objectives
8.6 Paragraph 3 in Regulation 11 in SI 2019/68527 contains a requirement to:
- "carry out a review of the impact of the adoption of the standard" where the standard is likely to lead to a “significant change in accounting practice"; and
- publish a report setting out the conclusions of the review no later than 5 years after the date on which the standard takes effect (being the first day of the first financial year in respect of which it must be used)".
8.7 Paragraph 4 in Regulation 11 in SI 2019/685 contains a requirement to:
- carry out subsequent reviews from time to time; and
- publish a report setting out the conclusions of any review conducted.
8.8 A “significant change in accounting practice” usually occurs when a new accounting standard is issued by the IASB. A new standard meets a “significant change in accounting practice” as it will usually have a widespread effect on many entities or a material effect on a few entities.
8.88.9 The IASB undertakes a post-implementation review of each new standard. As a result, the obligations in Regulation 11 in SI 2019/685 can be fulfilled for most international accounting standards by influencing and responding to IASB's post-implementation reviews (refer to paragraphs 8.2-8.5 in this Handbook).
8.98.10 When the IASB decides not to undertake a post-implementation review on a new international accounting standard and it is a significant change in accounting practice, However, the UKEB must may consider performing its own post-implementation review of international accounting-the standards to test its their continuing relevance in line with the requirements in Regulation 11 in SI 2019/685. This should be completed done no later than 5 years after the date on which the international accounting standard takes effect, in accordance with paragraph (3)(b) of this Regulation.
8.10 The UKEB may decide to perform its own post-implementation review of an international accounting standard when for example:
- the IASB decides not to undertake a detailed post-implementation review on an international accounting standard that has significance in the UK; or
- a change in a (revised) international accounting standard is so significant that a review is needed.
8.11 If the UKEB decides not to undertake a post-implementation review of a particular international accounting standard it may decide to start, instead, a research project following the processes set out in Chapter 7 of this Handbook.
8.128.11 Each post-implementation review that the UKEB carries out has two phases as described below.
First phase of a UKEB post-implementation review
8.138.12 In the first phase of a post-implementation review, the UKEB sets out the scope of the review, on the basis of targeted consultation with stakeholders that represent different stakeholder communities, (e.g.i.e. users, preparers, academics, accounting firms, accounting bodies and regulators28) to gather their input, views, opinions or feedback on specific projects or technical matters. These initial consultations help the UKEB establish the questions to ask in the public request for information.
8.14 Based on an initial assessment, the UKEB may determine that it would be premature to undertake a review at that time and decide not to conduct a post-implementation review.
8.158.13 The expected milestones for the first phase are:
- Project initiation plan (PIP) (mandatory);
- Desk-based research;
- Initial consultation; and
- Publication of a Request for Information (mandatory).; and
(d)Project closure: issue of a Final report and of a Due Process Compliance Statement for a UKEB Post-implementation review.
Project Initiation Plan (mandatory)
8.14 The objective of the PIP is to assess the need to undertake a post-implementation review of an international accounting standard. If and if it is determined that the post-implementation review should go ahead
8.168.15 The PIP outlines the approach to the project, including:
- a description of the project objective and proposed timeline;
(a)(b) any initial assessment of the international accounting standard, the reasons why the UKEB should seek feedback and the process followed in establishing the scope of the review;- a description of mandatory milestones and planned activities that will be undertaken to achieve those milestones.
- available and required resources for the project (including whether those resources are already allowed for in the annual plan or budget);
(b)(e) expected output (i.e. a Request For Information); and- if applicable, the factors considered to justify departing from the standard consultation period for a Request For Information (refer to paragraph 8.23 below).
8.17 includes the level of analysis and outreach that should be undertaken. 8.18 The PIP outlines a proportionate approach for the review (i.e. the matters for which feedback is needed), including the amount of desk-based research, outreach, and the proposed timeline. It further The activities described in the PIP should be proportionate to the standard or amendment under consideration for adoption. This approach should help ensure an appropriate level of resource is allocated to each projectexplains why the UKEB should seek feedback on the matters specified and includes any initial assessment of the international accounting standard. The PIP will also set out the process that the UKEB followed in establishing the scope of the review.
Desk-based research
8.198.16 Desk-based research is undertaken to assist with the assessment of proportionality and to gather evidence on the need for a PIR. This will usually include review of:
- the IASB's and the UKEB's previous work on the issue to identify the issues that were important or contentious during the development of the international accounting standard, which should be identifiable from the Basis for Conclusions, project summary, Feedback Statement and Effect Analysis, of the relevant Standard;
- any relevant research, including that performed by the Secretariat and academics; and
- any issues brought to the UKEB's attention prior to the commencement of the PIR.
8.208.17 It may also include, for example, a review of literature, academic papers, financial statements or of past papers or reports (by other national standard-setters or by other stakeholders (i.e. users, preparers, academics, accounting firms, accounting bodies and regulators), as well as liaising with national standard-setters who have carried out influencing activities or are in the process of performing such activities on the same (or related) project.
Initial consultation
8.218.18 The Board and its Secretariat may also will consult with stakeholders to help identify areas where unexpected costs or implementation problems were encountered.
8.228.19 This initial review should draw on the broad network of UKEB related bodies and interested parties, such as the UKEB's advisory groups, and other outside groups of, for example, preparers, auditors or users. The purpose of these consultations is to inform the UKEB so that it can establish an appropriate scope for the review. The extent of consultation needed for this phase will depend on the Standard being reviewed and pre-existing information about the implementation of that Standard.
Publication of a Request for Information (mandatory)
8.238.20 When the UKEB is satisfied that it has sufficient information to establish the scope of the review it issues a request for information on the Post-implementation review of the international accounting standard.
8.248.21 A Request for Information sets out the matters for which the UKEB is seeking feedback together with a rationale for the information being sought and any initial assessment by the UKEB of the impact of the international accounting standard. It also describes the reasons for undertaking such review (in line with Regulation 11 in SI 2019/685).
8.258.22 Publication of a Requests for Information does not require a formal written vote by the Board, and only It requires the support of a simple majority of the Board members present at the meeting, with approval given in a public meeting.
8.23 The UKEB usually allows a minimum standard comment period is of 90 days-for comment on such a consultation.
8.24 In exceptional circumstances, where the Request for Information is on a topic that is narrow in scope and/or urgent the Board may set a shorter period. The rationale for a shorter comment period will be given in the PIP.
Second phase of a UKEB post-implementation review
8.25 In the second phase the UKEB collects information, via the Request for Information issued during the first phase and a review of existing research, to help it assess the international accounting standard being reviewed. During this evidence-gathering phase of the post-implementation review the UKEB also conducts outreach activities to engage with different stakeholders
8.26 The milestones for the second phase are:
- Outreach activities; and
- Project closure: issue of a Final report (mandatory) and a Due Process Compliance Statement (mandatory).
8.18 The Board and its Secretariat may also willwill consult with stakeholders to help identify areas where unexpected costs or implementation problems were encountered.
8.19 This initial review should draw on the broad network of UKEB related bodies and interested parties, such as the UKEB's advisory groups, and other outside groups of, for example, preparers, auditors or users. The purpose of these consultations is to inform the UKEB so that it can establish an appropriate scope for the review. The extent of consultation needed for this phase will depend on the Standard being reviewed and pre-existing information about the implementation of that Standard.
Publication of a Request for Information (mandatory)
8.20 When the UKEB is satisfied that it has sufficient information to establish the scope of the review it issues a request for information on the Post-implementation review of the international accounting standard.
8.21 A Request for Information sets out the matters for which the UKEB is seeking feedback together with a rationale for the information being sought and any initial assessment by the UKEB of the impact of the international accounting standard. It also describes the reasons for undertaking such review (in line with Regulation 11 in SI 2019/685).
8.22 Publication of a Requests for Information does not require a formal written vote by the Board, and only It requiresrequires the support of a simple majority of the Board members present at the meeting, with approval given in a public meeting.
8.23 The UKEB usually allows a minimum standard comment period is of 90 days- for comment on such a consultation.
8.24 In exceptional circumstances, where the Request for Information is on a topic that is narrow in scope and/or urgent the Board may set a shorter period. The rationale for a shorter comment period will be given in the PIP.
Second phase of a UKEB post-implementation review
8.25 In the second phase the UKEB collects information, via the Request for Information issued during the first phase and a review of existing research, to help it assess the international accounting standard being reviewed. During this evidence-gathering phase of the post-implementation review the UKEB also conducts outreach activities to engage with different stakeholders 8.26 The milestones for the second phase are:
- Outreach activities; and
- Project closure: issue of a Final report (mandatory) and a Due Process Compliance Statement (mandatory).
Outreach activities
8.27 The UKEB's outreach activities will be focused on seeking implementation issues. 8.28 The amount of outreach to be undertaken, together with the rationale, will be highlighted in the PIP. 8.29 The outreach activities that could be undertaken to gather input, views, opinions or feedback are the same as those described in section 5 of this Handbook (paragraphs 5.20-5.28).
Project closure for a UKEB Post-implementation review
Final report (mandatory)
8.30 Input and feedback received on the request for information is recorded, assessed, the evidence evaluated, and then incorporated into the analysis and discussion of the technical issues. 8.31 When the UKEB has completed its deliberations, it presents its findings in a Final report that includes:
- an overview of the UKEB post-implementation review process and its timeline;
- background information to the international accounting standard under review;
- a summary of findings and next steps, including the areas for potential improvement and amendment;
- UKEB's tentative conclusions of the review;
- recommendations or steps it plans to take, if any, as a result of the review; and
- a summary of the sources of stakeholder comments, e.g. from individual stakeholder meetings, formal responses to the Request for Information or via other outreach events.
Due Process Compliance Statement (mandatory)
8.32 For a UKEB post-implementation review, the Secretariat summarises the due process activities undertaken in a closing control report called "Due Process Compliance Statement". For a description and content of this Statement refer to paragraph 11.2 in Section 11 of this Handbook.
9 Advisory Groups
Introduction
9.1 The UKEB undertakes targeted consultation by appointing its own standing and ad-hoc advisory groups with the purpose of gathering technical advice, and other input on its projects or other technical matters (e.g. UK-specific implementation issues). 9.2 Members of advisory groups comprise experts that:
- provide advice and recommendations on specific agenda projects for example by sharing:
- knowledge and understanding of financial reporting issues and/or concerns raised by UK stakeholders; and
- up-to-date insight into developments and market sentiment on financial reporting matters, helping develop a timely understanding of any concern areas;
- deliver best practice, practical experience, and expertise as well as potential solutions that can improve the quality of information; and
- help amplify the UKEB's views across the UK reporting community and drive the debate of contemporary issues in the international community.
9.3 In carrying out their work, advisory groups have regard to the UKEB's Terms of Reference and Guiding Principles (refer to Chapter 3 in this Handbook).
Composition of advisory groups
Types of advisory groups
9.4 Advisory groups are not decision-making bodies, but advisory in nature and can be standing or ad-hoc. Their characteristics are described in the table below:
| Type | Standing | Ad-hoc |
|---|---|---|
| Duration | Advisory group with an indefinite life. Intended to be long-lived. | Intended to be short-lived for a pre-defined time or set duration and is project-based. |
| Description | Provides regular and focused input on a wide range of strategic and technical issues. | Provides focused input on a wide-range |
| Members– stakeholder type | Usually includes stakeholders from a particular industry, sector or stakeholder type (i.e. preparers, auditors or users). It can also include a 'mix' of stakeholders with shared interests 30. | Usually includes a 'mix' of senior professionals from different stakeholder groups but with a specialist knowledge of the specific issue or technical area relevant to the group. It can also include a narrower (even single) stakeholder group when appropriate to a particular project (eg users or academics only for particular project, eg research project). |
| Benefits | Benefits are the same as for both standing and ad-hoc advisory groups. Enables the Board to access regular and timely advice on areas of specialist knowledge and receive a real-world view of the impact of proposals, generally on major projects. |
Types of participants
9.5 Participants in a UKEB's advisory group (standing or ad-hoc) may originate form- from the following stakeholder groups:
- Users – those with practical experience in analysing and using financial information as users of financial reporting information. Users include “buy-side”
fund managers, institutional investors and retail investors as well as participants from "sell-side” investment banks and ratings agencies.
- Preparers – those with considerable practical experience of financial reporting and provide knowledge and understanding of the financial reporting issues faced by IFRS reporters. Preparers have backgrounds in large or small, listed or unlisted UK-based companies applying international accounting standards.
- Academics – researchers with expertise and experience in the use of accounting by individuals, organisations and government. This group could include researchers with interests in accounting policy, governance and environmental issues, quantitative analysis, wider corporate reporting and economics.
- Accounting firms – those with a close interest in the use and implementation of international accounting standards. Accounting firms have insights to share on a range of different sectors' use of international accounting standards and on any concerns arising from that use. They include large and medium-sized professional services firms in the UK.
- Accounting Bodies – those with a close interest in the use and implementation of international accounting standards and providing insights on current and emerging issues.
- Regulators – those that regulate or supervise a particular industry or business activity. Regulators have insights to share on the use of international accounting standards by different sectors and on any concerns arising from that use.
Operating procedures
Approval for the creation of an advisory group
9.6 The establishment of an advisory group is subject to Board approval by a majority of Board members.
Terms of reference
9.7 Each advisory group has its own Terms of Reference, setting out:
- the advisory group's purpose and responsibilities;
- membership rules;
- meetings and administrative arrangements;
- remuneration for members (if applicable); and
- date of approval of the Terms of Reference and process for making changes.
9.8 An outline of the content of the Terms of Reference applicable to each advisory group (i.e. standing or ad-hoc) is included in Appendix B of this Handbook.
Recruitment
9.9 Consistent with the UKEB's guiding principles of accountability and transparency, all recruitment for advisory groups should be via a public advertisement, inviting applications. Appointments should be based on interviews with Board members and members of the Secretariat. The Board may wish to retain the option to make the occasional direct appointment, however, this would need to be in exceptional circumstances, for example where there are few experts in a particular area or no other expert is forthcoming.
Appointments and membership
9.10 In appointing members, the UKEB Chair seeks to ensure that the membership in the advisory groups is diverse in terms of skills experience, background, race, gender and other characteristics, and achieves a gender balance.
9.11 Members of advisory groups are appointed in their personal capacity, and only in exceptional circumstances, and at the discretion of the advisory group's chair, may they be represented by an alternateAlternates are not permitted.
9.12 Membership to an advisory body is approved subject to ratification by the Board at a private meeting. Once approved, the members of an advisory group are listed on the UKEB's website.
9.13 Depending on the advisory group's nature and purpose, the UKEB Chair may appoint a chair for the advisory group who may be either: an advisory group member, a Board member or a Secretariat member.
9.14 The membership of an advisory group is reviewed on a regular basis with the possibility that members may be appointable for consecutive terms. Members of advisory groups are appointed for an initial term of up to three years renewable for a second term of up to three additional years, or for the length of the project (e.g. for ad-hoc groups). The length of term may be shortened or lengthened if circumstances warrant. to allow for a Staggered rotation of members to ensure continuity on the advisory group. Changes to appointments arising from such reviews are approved by the Board at a private meeting. The membership of the advisory group is then updated on the UKEB's website.
Meetings
9.15 Administrative support to the advisory group will be provided by the Secretariat as necessary, including organising meetings and updating members about the project's progress.
9.16 Technical papers for meetings of advisory groups will generally be prepared by Secretariat or members of the advisory group, as appropriate. All advisory groups' papers to the advisory groups and UKEB are confidential unless all members of the group agree to share them more widely or to issue papers which are presented at a public Board session.
9.17 Meetings of advisory groups may beare attended by some Board members as approved by the UKEB Chair.
9.18 Meetings of advisory groups are usually closed and held in private. However, consistent with the UKEB guiding principles of accountability and transparency, the agendas and a summary of the discussions held by advisory groups (without attribution to members) are made available on the UKEB website. Members will be required to treat as confidential all information acquired in the exercise of their function as members. Advice may also sometimes be sought between meeting dates via email, telephone, video conference or other electronic means. The Secretariat will report a summary of the output from the group to the Board at a public meeting. 9.19 Where the Secretariat meets in private with an advisory group, it will report a summary of the output from the group to the Board at a public meeting. 9.20 Meetings of advisory groups may be held in the presence of invited observers with speaking rights only sometimes be opened to the public and if this is the case, meetings are webcast live (if possible), recorded and the papers discussed made available on the UKEB website. Representatives of other interested organisations that attend as observers may have speaking rights if the chair deems it beneficial to the work of the group. An advisory group can also, through its chair, invite other specialists to its meetings for specific agenda items. 9.21 Members of advisory groups will be expected to:
- review all relevant material before the meeting;
- provide specialist knowledge and technical advice in line with the purpose and responsibilities of the group's Terms of Reference. Standing advisory groups provide advice to the Board whereas ad-hoc advisory groups provide advice the Secretariat;
- make evidence-based and objective contributions, to the extent possible;
- aim for consensus-building wherever possible and, to that end, should be prepared to be challenged on their views and open to consideration of other members' perspectives;
- remain respectful and professional in all interactions with other members of the group and with the Secretariat; and
- attend all meetings.
Frequency for ad hoc advisory groups
9.22 Once work on a project commences, the Board and/or the Secretariat may consult advisory groups when it is beneficial to the project to do so.
Effectiveness review
9.23 The Board will evaluate the purpose, composition, and effectiveness of each advisory group every three years (or more frequently, if circumstances warrant), to assess each group as to whether
- It each group is continuing to serve the function for which it was established. The Board revises the Terms of Reference applicable to each advisory group as necessary.
- The composition continues to be appropriate. This will include appointments and re-appointments of members. Any changes to membership are approved by the Board at a private meeting. The membership of the advisory group is then updated on the UKEB's website.
10 Influencing the work of the IFRS Interpretations Committee
Introduction
10.1 The IFRS Interpretations Committee (Interpretations Committee) is the IASB's interpretative body that "assists the [IASB] Board in improving financial reporting through timely assessment, discussion and resolution of financial reporting issues identified to it within the IFRS framework"31. It does so by, amongst other things:
- recommending to the IASB to add a standard-setting project to its work plan when certain criteria in the IFRS Due Process Handbook32 are met. This is done in the form of a proposal for a narrow-scope amendment or an annual improvement, i.e. amendments that meet the IASB's criteria for annual improvements or for narrow-scope amendments;33
- developing a proposal for a Draft IFRIC Interpretation (that is later ratified by the IASB); and
- recommending that the IASB does not add a standard-setting project to its work plan, instead publishing an agenda decision34 to address application questions.
Supporting the work of the IFRS Interpretations Committee
10.2 The UKEB supports the IASB's and the IFRS Interpretations Committee's work by ensuring that UK views are considered during the development and improvement of international accounting standards (including IFRIC Interpretations). This is achieved by:
- monitoring the work of the IFRS Interpretations Committee;
- influencing proposals for annual improvements, narrow-scope amendments and/or Draft IFRIC Interpretations;
- considering whether to contribute comment letters on tentative agenda decisions issued by the IFRS Interpretations Committee; and
- informing the IFRS Interpretations Committee and/or the IASB of significant issues raised or identified by UK stakeholders for potential inclusion in their work programme.
Monitoring IFRS Interpretations Committee work
10.3 The Secretariat monitors projects developed by (or with the assistance of) the Interpretations Committee and reports them to the Board on a regular basis (i.e. proposals for amendments, IFRIC Interpretations or tentative agenda decisions). 10.4 The Secretariat may consider:
- undertaking outreach activities ahead of the IFRS Interpretations Committee issuing proposals before a due process document is published; and
- delivering an update on matters discussed at Interpretations Committee meetings at Board meetings, with the objective of raising awareness at Board meetings on the issues being discussed; whether the Board would like to respond and possible interactions with the UKEB's other activities and projects.
Influencing proposals for amendments or for Draft IFRIC Interpretations
10.5 The UKEB follows the requirements in Section 5 of this Handbook for influencing proposals for annual improvements, narrow-scope amendments and/or Draft IFRIC Interpretations.
Considering whether to respond to a tentative agenda decision
10.6 The UKEB expects to respond to a limited number of tentative agenda decisions published by the IFRS Interpretations Committee. Some factors to consider when deciding whether to respond may be:
- The degree of impact of the IASB-IFRS Interpretations Committee_tentative agenda decision on UK companies (for example, in cases where the tentative agenda decision is expected to affect a significant number of UK companies)
- Disagreement with the analysis performed by the IFRS Interpretations Committee; or
- Usefulness of the explanations and clarifications included in the tentative agenda decision.
10.7 The Board might also choose to respond to a tentative agenda decision even if it agrees with the analysis performed by the IFRS Interpretations Committee, to provide public
support of the tentative agenda decision. For example, this may apply in cases where others have expressed disagreement with the analysis in the tentative agenda decision. 10.8 When the Board reviews the update on the IFRS Interpretations Committee's activities it decides whether to respond to a tentative agenda decision. 10.9 If an issue discussed by the IFRS Interpretations Committee arises outside the usual Board meeting cycle, the UKEB Chair can approve initiation of work on the tentative agenda decision.
Project milestones for tentative agenda decisions
10.10 The UKEB will broadly follow the milestones in paragraph 5.8-7 in Section 5 of this Handbook to influence tentative agenda decisions issued by the IFRS Interpretations Committee that the UKEB considers have relevance for the UK. However, these milestones will only be followed to the extent they are appropriate or possible. For example, given that the comment period for a tentative agenda decision is usually shorter than for other IASB's due process documents, it is more appropriate to consult with a representative group of stakeholders and/or with members of the UKEB's standing and/or ad-hoc advisory groups, rather than making a Draft Comment Letter available for comment on the UKEB website. 10.11 The activities undertaken to achieve these milestones should be proportionate to the technical issue(s) being addressed and will depend on its significance for UK stakeholders and on its complexity. The Project Initiation Plan will outline the approach to the technical issue(s) being addressed and describe how the approach taken meets due process requirements. 10.12 After considering comments from UK stakeholders on tentative agenda decisions, the UKEB may decide to recommend that the IFRS Interpretations Committee:
- confirms the IFRS Interpretations Committee's decision to publish an agenda decision;
- revises (or abandons) the IFRS Interpretations Committee's tentative agenda decision; or
- refers the matter to the IASB to consider adding a standard-setting project to the IASB's work plan.
Informing the IFRS Interpretations Committee of significant issues raised by UK stakeholders
10.13 The UKEB may decide to inform the IFRS Interpretations Committee of issues raised or identified by UK stakeholders as potential agenda items (i.e. for potential inclusion on the IASB's and/or on the IFRS Interpretations Committee's work programme). In doing so, the UKEB follows the procedures for the 'Identification of Matters' in the IFRS Due Process Handbook35.
II Due Process Compliance Statement
Introduction and objective
11.1 For each project, the Secretariat assesses whether it has complied with the UKEB's due process activities as set out in Section 4 (Governance mandatory activities), Section 5 (Influencing Process), Section 6 (Endorsement Process), Section 7 (Thought leadership and research programme)36 and Section 8 (i.e. the sub-section on "UKEB Post-implementation review") of this Handbook, as applicable to the subject matter of the project. 11.2 The Secretariat summarises the due process activities undertaken in a closing control report called "Due Process Compliance Statement". This report fulfils the following objectives:
- provides a record of the activities undertaken by the Secretariat to comply with the UKEB's due process activities;
- provides a basis for holding the Secretariat accountable to the Board for the due process procedures that it follows in practice; and
- informs the Board about the work undertaken compared with that agreed in the Project Initiation Plan (PIP). The Due Process Compliance Statement retrospectively validates that the process undertaken complied with the PIP (or not). If discrepancies are identified this report provides an explanation as to why, and how the activities still meet due process requirements.
Content
11.3 The Due Process Compliance Statement includes the following sections:
- Project details:
- If influencing an IASB's due process document: title, date of publication and comment letter deadline;
- If a UKEB's thought leadership/research project: project title, date of publication, comment letter deadline (if applicable); or
- If endorsing an IASB standard or amendment: title, date of publication and the IASB's effective date.
- A description of due process steps undertaken covering the following areas:
- Project preparation (i.e. the Project Initiation Plan (PIP) and/or a revised version of the PIP and desk-based research);
-
- Communications (e.g. public meetings, documents posted on the UKEB website);
- Outreach activities (e.g. advisory groups, fieldwork undertaken);
- Preparation of documents for public comment (e.g. draft comment letter for influencing activities);
- Project finalisation and project closure (e.g. final comment letter, feedback statement for influencing activities);
- Metrics or evidence to demonstrate that the process was undertaken as agreed in the Project Initiation Plan (e.g. number of meetings held);
- An explanation of why the Secretariat decided not to undertake a due process step for a given project, if relevant (i.e. why an outreach activity specified in the PIP was not undertaken); and
- A conclusion as to whether, in the Secretariat's opinion, applicable due process steps have been complied with.
11.4 The Board discusses and provides comments on a (draft) Due Process Compliance Statement and approves the final version of this Statement at a public Board meeting. 11.5 A Due Process Compliance Statement is published on the UKEB website, usually at the same time as the Feedback Statement37.
Appendix A—Relationship between Statutory Instruments (SI) and other governance documents for the Endorsement Board
Appendix B—IASB’s and IFRS Interpretations Committee’s consultation documents
This Appendix has been included for information only.
| Consultation document | Description | Comment period |
|---|---|---|
| Discussion Paper (DP)/Research Paper | One of the main outputs of the IASB's Research programme is a Discussion Paper or a Research Paper. These documents:
|
Generally, the IASB gives a 120-day comment period. |
| Request for Information (RFI)/IASB Agenda Consultation | Requests for Information are formal requests by the IASB for information or feedback on a matter related to technical projects or broader consultations. This includes seeking comment on the IASB's technical work plan every five years, post-implementation reviews, or help in | Generally, the IASB gives a 120-day comment period for an RFI on the technical work plan. Other RFI's |
| Consultation document | Description | Comment period |
|---|---|---|
| assessing the practical implications of a potential financial reporting requirement. | generally allow a minimum of 60 days. | |
| Exposure Draft (ED) | An Exposure Draft is a mandatory step in the IASB due process before a new IFRS Standard can be. An Exposure Draft includes a specific proposal, a basis for conclusions that explains the rationale for the proposal and, if relevant, alternative views. It is developed at public meetings and includes an invitation to comment describing the issues that the IASB has identified as being of particular interest. | Normally, the IASB gives a 120-day comment period. For issues that are narrow in scope and urgent the period can be reduced to at least 30 days. Only in exceptional circumstances is less than 30 days permitted. |
| Annual Improvements (ED) | Annual Improvements contain a group of proposed amendments to IFRS Standards that are sufficiently minor or narrow in scope that can be packed together and exposed in a single document, even if the amendments are unrelated. Limited to changes that clarify the wording in the standards, or correct relatively minor unintended consequences, oversights or conflicts between existing requirements. Annual improvements are normally, but not always, issued on an annual basis. The IFRS Interpretations Committee can assist the IASB in developing these amendments. | Normally, the IASB gives a minimum of 90 days comment period. |
| Narrow-Scope Amendment (ED) | Narrow Scope Amendments are proposed |
A minimum period of 120 days for comments on exposure drafts but if the matter is narrow in scope and urgent the IASB may set a comment period of less than 120 days but no less than 30 days |
| Draft IFRIC Interpretation (DI) | A Draft IFRIC Interpretation is a mandatory step before issuing an IFRIC Interpretation. It is a draft of a proposed Interpretation of a Standard and is the equivalent of an ED for a Standard. It is developed in public meetings of the IFRS | The minimum comment period is normally 90 days. If the matter is narrow in scope |
| Consultation document | Description | Comment period |
|---|---|---|
| Interpretations Committee and is ratified by the IASB (Board). It sets out a specific proposal in the form of a proposed Interpretation. It includes an invitation to comment and a basis for conclusions which explains the rationale for the specific proposal. | and urgent the comment period can be reduced, down to a minimum of 30 days. | |
| Tentative Agenda Decisions (TAD) | Tentative Agenda Decisions are issued by the IFRS Interpretations Committee. These decisions explain why a standard-setting project should not be added to the IASB's technical work plan to address a submitted question and, in many cases, includes examples and other explanatory material that provides new or clarifying information. After considering the comments, the IFRS Interpretations Committee will confirm its decision and publish an Agenda Decision (subject to the IASB not objecting to this decisions) or decide that a standard-setting project should be added to the IASB work plan. | The IFRS IC requests comments on TADs within 60 days. |
| Post-implementation reviews (PIR) | The IASB conducts a post-implementation review of each new IFRS Standard or major amendment. A post-implementation review normally begins after the new requirements have been applied internationally for two years (generally about 30-36 months after the effective commencement date). The PIR is accompanied by a Request for Information (RFI) which sets out the initial identification and assessment of the matters to be examined. | The IASB gives a 120-day comment period. |
| Consultation document | Description | | --- | --- | --- | | (IASB_IASB_Board)_Board). It sets out a specific proposal in the form of a proposed Interpretation.It includes an invitation to comment and a basis for conclusions which explains the rationale for the specific proposal. | Interpretations Committee and is ratified by the | and urgent the comment period can be reduced, down to a minimum of 30 days. | | Tentative Agenda Decisions (TAD) | Tentative Agenda Decisions are issued by the IFRS Interpretations Committee. These decisions explain why a standard-setting project should not be added to the IASB’s technical work plan to address a submitted question and, in many cases, includes examples and other explanatory material that provides new or clarifying information.After considering the comments, the IFRS Interpretations Committee will confirm its decision and publish an Agenda Decision (subject to the IASB not objecting to this decisions) or decide that a standard-setting project should be added to the IASB work plan. | The IFRS IC requests comments on TADs within 60 days. | | Post-implementation reviews (PIR) | The IASB conducts a post-implementation review of each new IFRS Standard or major amendment. A post-implementation review normally begins after the new requirements have been applied internationally for two years (generally about 30–36 months after the effective commencement date). The PIR is accompanied by a Request for Information (RFI) which sets out the initial identification and assessment of the matters to be examined. | The IASB gives a 120-day comment period. |
Appendix B [Draft] Terms of Reference outline for advisory groups
Terms of Reference
1 Name, purpose and responsibilities
1.1Name [of advisory group], purpose and responsibilities to the Board and/or to the Secretariat.
1.2Guiding principles and compliance with legislative framework.
2 Membership
2.1Composition and membership length. The membership of an advisory group is reviewed on a regular basis with the possibility that members may be appointable for consecutive terms. Members of advisory groups are appointed for an initial term of up to three years renewable for a second term of up to three additional years. The length of term may be shortened to allow for a staggered rotation of members to ensure continuity on the advisory group. Changes to appointments arising from such reviews are approved by the Board.
2.2Size: minimum and maximum number of members.
2.3What the Board and/or the Secretariat expect from the members of the advisory group and consequences of failing to meet the expectations set out in the terms of reference (for example dismissal after non-attendance at a certain number of meetings, etc).
3 Meetings and administrative arrangements
3.1Process for holding meetings:
- Indication of whether meetings are:
- closed and/or open to the public; if meetings are public, an indication of whether observers can attend meetings and/or if they have speaking rights;
- held virtually and/or physically;
- Requirements for attendance and an indication of whether alternates are permitted;
- Location, duration (i.e. number of hours), and frequency (i.e. number of meetings per month and/or per year); and
- Indication of who will act as the chair of the advisory group;
3.2Notice of meetings and agendas: State obligation to:
- make available meeting agendas and papers for the members of the advisory groups before the meeting; and
- publish the agendas and a summary of the output from the group (without attribution to members) on the UKEB website.
3.3If meetings are public, also state obligation to broadcast (and/or record) meetings and to publish agenda papers on the UKEB website.
4 Remuneration for members
4.1Indication of whether members are (or not) remunerated.
4.2Indication of whether members are reimbursed for reasonable travel and other costs incurred in participating in the group's activities.
5 Approval of Terms of Reference and changes
5.1Date of approval of the Terms of Reference and process for making changes to these terms.
[Draft] Due Process Handbook—
Summary of comments (from the December 2021 meeting) and responses
| Issue raised 1 | Reference 2 | 3 | Commentator | Suggestion made 4 | | --- | --- | --- | --- | --- | --- | | Section 1: Introduction | | | | | | | 1 | General-footnotes | Section 1 | E | Liz Murrall | Update footnotes | Checked. | | 2 | Introduction | 1.1(a) | E | Mike Wells | I suggest rewording as follows 'Influencing the development of international accounting standards and the other activities of the IASB and the IFRS Interpretations Committee.' | Done. | | 3 | Introduction | 1.1(b) | E | Mike Wells | Holds true if paragraph 1.1(a) redrafted as above. | Ok noted and paragraph 1.1(a) amended. | | 4 | Introduction | 1.2(b) | E | Sandra Thompson | Suggests 'the setting up and operation of advisory groups' | Done. | | Section 2: Statutory functions of the UKEB | | | | | | | 5 | Statutory functions | Section 2 | S | Liz Murrall | We do refer to Regulation 5 in the SI, however we also need to refer to the delegation by the Secretary of State. Similarly, regulation 8. Then regulation 17 – reporting by the Board. | Done. Addressed in paragraphs 1.5 and 2.1, and links to these Regulations were included in footnotes 3 and 5. | | 6 | Statutory functions | 2.1 | E | Katherine Coates | Suggest explaining that item in a) referred to in Handbook as Endorsement Activities and items in b) referred to as Influencing activities and Research activities so that we have identified what the subsequent sections relate to. | Addressed in paragraph 3.1(a)-(b). We have added footnotes 7-10. | | 7 | Statutory functions | 2.2 | E | Katherine Coates | Delete "and" in first line | We cannot modify this paragraph as we are quoting it directly from Regulation 8. |
| Issue raised 1 | Reference 2 | 3 | Commentator | Suggestion made 4 | | --- | --- | --- | --- | --- | --- | --- | | 1 | General-footnotes | Section 1 | E | Liz Murrall | Update footnotes | Checked. | | 2 | Introduction | 1.1(a) | E | Mike Wells | I suggest rewording as follows 'Influencing the development of international accounting standards and the other activities of the IASB and the IFRS Interpretations Committee.' | Done. | | 3 | Introduction | 1.1(b) | E | Mike Wells | Holds true if paragraph 1.1(a) redrafted as above. | Ok noted and paragraph 1.1(a) amended. | | 4 | Introduction | 1.2(b) | E | Sandra Thompson | Suggests 'the setting up and operation of advisory groups' | Done. | | Section 2: Statutory functions of the UKEB | | | | | | | 5 | Statutory functions | Section 2 | S | Liz Murrall | We do refer to Regulation 5 in the SI, however we also need to refer to the delegation by the Secretary of State. Similarly, regulation 8. Then regulation 17 – reporting by the Board. | Done. Addressed in paragraphs 1.5 and 2.1, and links to these Regulations were included in footnotes 3 and 5. | | 6 | Statutory functions | 2.1 | E | Katherine Coates | Suggest explaining that item in a) referred to in Handbook as Endorsement Activities and items in b) referred to as Influencing activities and Research activities so that we have identified what the subsequent sections relate to. | Addressed in paragraph 3.1(a)–(b). We have added footnotes 7-10. | | 7 | Statutory functions | 2.2 | E | Katherine Coates | Delete "and" in first line | We cannot modify this paragraph as we are quoting it directly from Regulation 8. | | Section 3: Terms of Reference and Guiding Principles | | | | | | | 8 | Terms of Reference | 3.1 | E | Katherine Coates | Suggest reordering so b) follows d). Also reorder it: what is b) comes after a, c and d as b) is more a process In a) suggest deletion of last sentence as already in 1.5. In c) suggest adding after agenda in last line responding to draft proposals and consultations. [Pauline Wallace] Agreed. | Done. Paragraphs re-ordered and paragraph 3.1 amended. | | 9 | Terms of Reference | 3.1(a) | E | Mike Ashley | In the draft DECA (IFRS 17) we explain how we were using the terms "endorse" and "adopt" and I did wonder whether that it made sense to put something similar in here so that we are clear about what we are talking about as we do tend to use those terms a bit so that I would not say arbitrarily but in different places for different purposes | Done. We have added in footnote 7: "While the relevant legislation uses only the term 'adoption' and does not refer to 'endorsement', for the purposes of this (draft) Handbook the term 'endorsement' is generally used when referring to the assessment of international accounting standards against the statutory adoption criteria, reflecting general usage. This is not intended to imply the existence of two distinct statutory functions or processes". | | 10 | Terms of Reference | 3.1(b) | E | Mike Ashley | In 3.1(b) I just wondered how this paragraph (which states that we will look at all IASB's projects) vectors with things like tentative agenda decisions where we take a proportional approach. I would make it less absolutist. | Paragraph 3.1(b) has been amended following the suggestion made. | | | | | E | Pauline Wallace | Agree–I also suggest that we go back to our terms of reference and make sure that we didn't put something in there that was a challenge. | | | 11 | Terms of Reference | 3.1(f) | E | Katherine Coates | Should we mention reporting to BEIS in this section? [Pauline Wallace: agree). | Done. Added paragraph 3.1 (f) "Reporting to BEIS in relation to the performance of its statutory functions". |
| Issue raised 1 | Reference 2 | 3 | Commentator | Suggestion made 4 |
| Issue raised 1 | Reference 2 | 3 | Commentator | Suggestion made 4 | UKEB Secretariat response |
|---|---|---|---|---|---|
| 58 | Project closure-voting | Old paragraph 6.31 | E | Katherine Coates | Old paragraph 6.31 can be deleted if the first sentence is added to paragraph 6.35. |
| 59 | Project closure-voting | 6.35 | E | Katherine Coates | Add "publication of the outcome of the" formal written vote "on UKEB website" is accompanied.... In (a) add "if adopted at the end". In (b)(iv) add "where the standard or amendment is adopted at the end". |
| 60 | Project closure-voting | Old paragraph 6.33 | E | Katherine Coates | Paragraph 6.31 can then be deleted. |
| 61 | Project closure-voting | 6.40 | E | Katherine Coates | Delete document in line 2 and replace with subject matter |
| Section 7: Thought leadership and the research programme | Done | ||||
| 62 | Leading the UK debate | 7.3(d) | E | Katherine Coates | Add new (e) acting as a conduit for U.K. feedback on IASB consultations |
| 63 | Leading the UK debate | 7.2-7.3 | S | Sandra Thompson Pauline Wallace |
The activities described in paragraphs 7.2-7.3 are not 'leading the UK debate' but rather co-ordinating input from others. Leading the debate is doing more about original thinking and different potential solutions. Para 7.4, especially (b) - developing potential ways to improve or remedy deficiencies, and the point deleted from 7.5/7.5(c) on developing thought leadership and 7.5(e) on issuing articles, podcasts or videos is closer to leading the debate. Perhaps merge these two sections into one and add the deleted point [Pauline Wallace] Secretariat needs to do more re-digging in this respect. |
| 64 | Participating proactively in the development of global standards | 7.4-7.5 | E | Katherine Coates | I wonder if we should reorder with (c) becoming (a) and then limit the new paras b and and c by reference to available resources and intention to focus resources most on IASB agenda items? Similarly parts of 7.5 might be subject to available resources etc. |
| 65 | Representing UK views | 7.5(b) | E | Liz Murrall Sandra Thompson |
We are not promoting appointing to the IASB itself but to its various advisory groups. Table says vote in meeting is indicative elsewhere it says tentative Should refer to IASB stakeholder groups – not the IASB itself |
| 66 | Research programme | 7.9(a) | E | Sandra Thompson | Delete 'research' – else is circular |
| 67 | Research programme | 7.9(b) | E | Katherine Coates | Might be redrafted to say "provide effective technical input into IASB proposals forming part of IASBs current agenda" |
| 68 | Research programme | 7.9(b) | E | Sandra Thompson | I think it is more than identifying an issue – it is also looking at/analysing potential solutions – as is stated in 7.8 (but need to be in 7.9 too) |
| 69 | Research programme | 7.10 | E | Katherine Coates | Add "where resources are available" at the end of the section |
| 70 | Main outputs | Old Table below 7.12 | S | Katherine Coates | Section 1 perhaps delete comprehensive as it may not be. Add specified before technical issues. Presumably discussion paper will be prepared by secretariat so add in section 1 but it will incorporate preliminary/final board views Board approval section- I don't think a discussion paper needs the two thirds formal written approval resolution- just a majority resolution |
| 71 | Research papers- approval | Old Table below 7.12 | S | Sandra Thompson | Does the Board need to approve the issue of a research paper as it is a secretarial paper that 'may be' discussed at a board meeting to |
| 72 | Research papers- discussion | Old Table below 7.12 | S | Pauline Wallace | provide input to the secretariat but does not include any views of the Board. Why a research project would not be discussed by the board whereas requests for information (which also do not contain board views) will be discussed at board level. In any event, since the board has to approve the issue of the Research Paper, wouldn't it need to discuss it first? |
| 73 | Need for a formal vote for Discussion Papers | 7.12 | S | Pauline Wallace Sandra Thompson Katherine Coates |
November 2021 meeting: Why are we requiring a formal vote on preliminary views from the Board? Sweep issues: My personal view is that the board should decide on whether a research project should go ahead and, at that stage, determine the extent of its involvement. I do not want to see staff resource committed to projects without the board's approval. November 2021 meeting: If we were including different views without expressing a way forward we will not need to vote. If the Board supports one view we will have a vote. [Pauline Wallace: not sure we will have DPs with one view]. Secretariat should have a look at paragraph 7.12 and determine what to do when we have one view or two views. Sweep issues: in paragraph 19. Not keen on the distinction between formal research projects and other research projects, If anything comes out of the UKEB as a UKEB research project it will have our brand on it. I could not see that any research project would meet the list of factors in paragraph 21. November 2021 meeting: An ordinary vote is OK because a DP does not impose a requirement or effect on stakeholders whereas an endorsement |
| 74 | Research programme- Milestones | 7.13 | S | Phil Aspin Pauline Wallace Annette Liz Murrall Katherine Coates |
decision does, so I will be concerned about adding too much formality for a discussion paper. Sweep issues: the factors in 21 were not particularly helpful. I wondered if we could just give ourselves some flexibility by saying that it would be subject to board approval unless we stated otherwise at the time of the PIP. We can decide as part of the PIP. And I would expect all research projects to meet at least one of the criteria on para 21 - else we shouldn't be spending limited resource on them. I am OK with list of examples of common categories, and with a simple majority vote where one is required. Sweep issues: All research outputs would require Board approval to be published. [it is not a vote to agree on the content] We need to keep the distinction and different types of papers. However, we do not want to be too prescriptive on the types because we are in an early stage and we want to give ourselves some flexibility. If the Board issues some views we need a Discussion paper. I am reluctant to be putting things out without the board having seen it. And make sure views from the Board are incorporated and that would require Board discussion. EFRAG produces lots of different research papers with different titles, rather than sticking to the 3 types. Mandatory milestones expected? Is mandatory here too onerous? We indicate that it will be proportionate in 7.14 so need flexibility eg will there always be outreach or in some cases will it just be internal research? (F) |
| 75 | Research programme- Milestones | 7.13 | S | Katherine Coates | Should allow milestones to be excluded as well as limited for minor projects |
| 76 | Research programme- Milestones | Old paragraph 7.15 | S | Katherine Coates | Should this exemption (i.e. requirement to provide project closure documents) apply to requests for information as well? |
| 77 | Project Initiation plan | 7.19 | Katherine Coates | Same point "on required resources" as for other PIP | |
| 78 | Consultation period | Old paragraph 7.21 | S | Katherine Coates Liz Murrall |
Consultation period of a minimum of 90 days doesn't seem appropriate to research activity Research allows 90 days – business or other. DECA 4 weeks. Consistency. |
| 79 | Desk-based research | 7.25 | E | Katherine Coates | Add "the same as those" before described in line 2 |
| 80 | Discussion papers | Old paragraphs 7.26-7.29 | S | Katherine Coates | We don't need the formal 2/3 vote for discussion papers- only applies to endorsement. Simple majority instead |
| 81 | Research papers and Requests for Information | 7.26 | E | Liz Murrall Pauline Wallace |
We are requiring simple majority of full Board but we will not always have a “full” Board. Agree– we should indicate the Board members "present" at the meeting. |
| 82 | Project closure | 7.30-7.32 | S | Katherine Coates | Is this (i.e. Feedback Statement, Due process Compliance Statement) necessary for a discussion paper? |
| Section 8: Post-implementation reviews | |||||
| 83 | Reference to 'stakeholders' | Section 8- General | E | Mike Wells | Page 97 and elsewhere Are we being consistent in using 'Stakeholders (i.e.'...) like in paragraph |
| 84 | First phase of a UKEB post-implementation review | 8.13 | S | Katherine Coates | If paragraph 8.13 is limited to first phase milestones as seems to be the case in line 1 should (e) (i.e. "Project Closure) be deleted and replaced by decision to move to second stage. Is the request for information in second stage? If so clarify. Should there then be a second stage PIP referenced? |
| 85 | First phase of a UKEB post-implementation review | Old paragraph 8.14 | Liz Murrall | November 2021 meeting: Regulation 11 paragraph 1 says that we must do a post implementation review so not sure how that fits with paragraph 8.14 (i.e. Based on an initial | |
| Katherine Coates Pauline Wallace |
assessment, the UKEB may determine that it would be premature to undertake a review at that time and decide not to conduct a post-implementation review"). Sweep issues: I have concerns around the drafting of 8.8 and 8.9 because we say a significant change in accounting practice occurs when a new accounting standard is issued. But it's also got to be endorsed. These are post implementation reviews. Paragraphs 8.8-8.9 also appear to contradict themselves: Paragraph 8.8 states that The IASB undertakes a post implementation review of each new standard, but then in 8.9 gives the IASB again the flexibility to decide not to. So the IASB doesn't necessarily always undertake a post implementation review. [Annette said: We're actually referring to new standards not to amendments (i.e. amendments to IFRS 15, IFRS 16, IFRS 17]. Add " such decision (including reasons) will be published at the end of the first phase" at the end November 2021 meeting: In what circumstances would we conclude that we do not need to carry out a post implementation review after five years and how do we demonstrate in those circumstances that we have complied with our statutory obligation? Sweep issues: Do we need to define what we mean by "a significant change in accounting practice"? If we conclude that an amendment to |
"significant change in accounting practice" (i.e. A "significant change in accounting practice” usually occurs when a new accounting standard is issued by the IASB. A new standard meets a “significant change in accounting practice” as it will usually have a widespread effect on many entities or a material effect on a few entities"). We have deleted old paragraph 8.10 and clarified the circumstances when the UKEB is required to perform a PIR, making sure that these circumstances are in line with the statutory requirements in Regulation 11. We have also deleted old paragraph 8.11 which stated that: "if the UKEB decides not to undertake a post-implementation review of a particular international accounting standard it may decide to start, instead, a research project following the processes set out in Chapter 7 of this Handbook". |
|||
| Mike Andrew Death (FRC) Sandra Thompson |
a standard does not constitute a significant change, do we need to ratify that at the board? The only constrain for the Regulation is the 5 years. We need to contemplate that time frame on whatever we put here. If the IASB for whatever reason decides to defer their PIR we will need to do something. BEIS has been unhelpful requiring us to do one year before the IASB do something. The PIR requirements for small business in the employment act are not tailored to IFRS. I would take that away and think about implications November 2021 meeting: Suggests adding in (old) paragraph 8.14 a sentence to say or the UKEB may decide to proceed with a PiR. Sandra further notes that the IASB expresses it as "in general no earlier than..." they do not require a maximum time like we do. And they might not do it when we need to do it. Sweep issues: In paragraph 8.8, I disagree that a new standard will always be a 'significant change in accounting practice'. E.g. IFRS 4 was not, nor would a new standard on hyperinflation. The word 'usually' later in the sentence is better (and old paragraph 8.9 suggests not all new IFRS are a significant change in accounting) - suggest amend first part to say 'A "significant change in accounting practice" usually occurs when a new accounting standard is issued by the IASB ...' |
||||
| 86 | Publication of a Request for Information | 8.22 | E | Liz Murrall | Do not understand how this will work – attendance 60% |
| 87 | Request for Information – consultation | 8.23 | E | Liz Murrall | In paragraph 8.23 we require 90 days consultation but elsewhere were referring to weeks so we should be consistent |
| 88 | Project closure-Final report | 8.31 | E | Katherine Coates | In (d) final rather than tentative? |
| Section 9: Advisory groups | |||||
| 89 | Types of advisory groups | 9.4 Table | E | Sandra Thompson Katherine Coates |
Ad hoc AGs may not provide input on a wide range of technical issues - rather it may be on a narrow range. Suggest delete 'wide range of'. For ad hoc should it reference specific technical issues as it is set up for a particular purpose not like standing committee |
| 90 | Types of participants | 9.5 | E | Mike Wells | 'Form' should read 'from'. |
| 91 | Types of participants | 9.5(f) | E | Mike Wells | Is this expressed in sufficiently wide terms? Regulators----those that 'regulate or supervise' rather than only 'supervise' |
| 92 | Diversity in advisory groups | 9.10 | E | Liz Murrall | In 9.10, I do not like diverse genders (look at the wording) but achieves a gender balance. |
| 93 | Alternates on advisory groups | 9.11-9.12 | S | Liz Murrall Mike Wells Pauline Wallace |
Agree with text of paragraph 9.11. But we say that appointments have to be approved but there is nothing about who approves the participation of alternates I like the wording in paragraph 9.11 and the use of exceptional circumstances for “alternates" and ask for approval by the chair I have concerns about alternates. We do not permit alternates for members of the Board so why would we want to keep them here. Alternatively we could allow people to speak to |
| Katherine Cearns Mike Liz Murrall Phil |
the group rather than treating them as alternate members of the group, this would be my preference. I do not want alternates at all. We choose members for their skills and if they want to step down they can be replaced. It is making everything more complicated Agree with Pauline Wallace. You could invite people to attend (observe). If membership approved by the Board what about alternates. if members of advisory groups are in their personal capacity why do we need alternates? |
Done. | |||
| 94 | Membership advisory groups | 9.14 and 9.22 | S | Sandra Thompson Pauline Wallace |
November 2021 meeting: What does 'membership is reviewed on a regular basis' mean? How regular? Who does it? Sweep issues: OK with new words. And that Board decisions re appointments and reappointments to be made in a private meeting. November 2021 meeting a) Who is responsible for reviewing the membership of advisory groups? b) Why do we need the reference to staggered rotation?. This is one reason why we may want shorter terms but there could be others (for example a member was only willing to be appointed for a shorter term but could bring useful insights to the discussion or the anticipated life of the group (if ad hoc) may be significantly less than 3 years). We have sufficient discretion in the preceding sentence and I don't see any benefit in limiting our ability to exercise it |
| c) Shouldn't the board also approve the renewal of a membership term as well as a change? I would like to take out the sentence where it says that "The length of term may be shortened to allow for a staggered rotation of members" because on an ad-hoc group we would like it to last for the length of the project. In certain circumstances I agree we may allow for a shortening of the term but do not give a reason for it (because “staggering rotation" is not the only reason for it) Sweep issues: Any discussions of advisory group members and appointments of new ones should definitely take place in the private session. It is only technical discussions that have to be held in public and this would not be an appropriate topic for the public meetings. We should, however, make the final membership public as soon as it has been agreed. |
(ii) changes to advisory groups arising from such reviews are approved by the Board; • indicate more clearly in paragraph 9.14 that: (i) staggered rotation of members is permitted to ensure continuity of the group; (ii) the length of term for members of advisory groups may be lengthened or shortened. Use of the wording "up to three years" is consistent with that used for the terms of the UKEB Board membership in paragraph 2.1 of the Terms of Reference. The difference is permitting the extension of the membership of an ad-hoc group to the length of the project. • Include a paragraph that “changes applicable to advisory groups (e.g. appointments/re-appointments) will be decided at a private meeting • Include a paragraph which states that information about appointments and re-appointments should be in the public domain. • Make clear that members of advisory groups will be appointed by the Board. |
||||
| Mike Wells | Paragraph 9.14 worried me that it is only talking about how terms could be shortened but there could be cases where we want to lengthen this term (i.e consecutive term of 2 years and somebody is providing particular feedback it would be a shame not being able to extend their term) for three or four years. I think we have his possibility for UKEB members (in a footnote) and I thought we should include it here as well | ||||
| Mike Wells | Are staggering and continuity the only reasons a term might be changed? If not perhaps better expressed as examples. Should wording allow for extending a term (say second term is initially two years but continuing |
||||
| Liz | input on a project considered very useful for another year (fix after 'shortened' add 'or lengthened' and/or (like for UKEB member appointments see footnote p6) could add 'one further term could be added for a period of 12 months') In 9.14 the membership is reviewed on a regular basis, this is to actually ensure orderly rotation but I would have thought that terms would have been set in advance so you can't then review those on a regular basis and also not clear who is reviewing (suggests the chair of the advisory groups). In 9.10, I do not like diverse genders. Do we also mean changes to appointments or changes to terms? |
||||
| Amir | The process of how members are appointed was not clear to me. Especially when old paragraph 9.12 states that "Membership to an advisory body is subject to ratification by the Board” but I am not sure, is it by vote? By agreement? And if the process is different for ad-hoc and for standing groups | ||||
| Mike Ashley | Sweep issues: The appointments and re-appointments process has to be open and transparent. Be clear when we made appointments and who we've appointed. So all of that information will be in the public domain. | ||||
| Katherine Coates Katherine Cearns |
Sweep issues: make clear that members of advisory groups will be appointed by the Board. On the terms (paragraph 9.14) staggered terms might be helpful but that is more an issue for the main Board because you do not know how long a project is going to last for and I would like to keep flexibility |
||||
| 95 | Meetings | 9.16 | E | Katherine Cearns | Add "to the advisory group and UKEB after confidential in line 3 |
| 96 | Meetings | 9.16-17 | E | Liz Murrall | Attended by Board members as approved by the UKEB chair. |
| 97 | Meetings | 9.18-9.19 | S | Katherine Cearns Pauline Wallace |
I am not sure why we would make advisory group meetings public. If you want a public debate you could have an event and ask the advisory group to attend but I am not sure that the advisory group meetings should be in public. Do not want to put people off to come. If you are going to add criteria of when they would be made public I would struggle. [Pauline Wallace agreed]. Some meetings of advisory groups may never want to be made public. [Pauline originally said "You might want to open private advisory meetings to the public I think we should clarify in paragraph 9.20 that that would be a decision from the members of the group". Better to say that meetings of advisory groups would [always] be private (to avoid putting people off |
| 98 | Ad-hoc/Standing advisory–who do they provide advice to? | 9.20(b) | E | Sandra Thompson Pauline Wallace |
Why do standing AGs provide advice to the Board whereas ad hoc ones provide advice to the secretariat? Should they advise both the Board and the secretariat? Should we delete this sentence? Accepted Sandra Thompson's suggestion to delete the last sentence in paragraph 9.20(b). |
| 99 | Specific rules for Ad-hoc/Standing | 9.10-9.14, 9.22 | S | Pauline Wallace Katherine Coates |
Suggestion to develop separate requirements for each group, for example, in terms of who appoints/recruits members or who does an effectiveness review and so on. It seems to me that we should not need board involvement in the appointment of members of ad-hoc groups, for example I am not sure we should start making distinctions between different committees. I think it would better if just have the framework in the Handbook and allow for the Terms of reference for each committee to set out the specifics as we started to do in the Appendix, so rather than trying to straight jacket all of them with the same standards and composition, we have a little more flexibility and anything else that I specific to each group |
| Section 10: Influencing the work of the IFRS Interpretations Committee | |||||
| 100 | Considering whether to respond to a tentative agenda decision | 10.6 | E | Mike Wells | (IFRIC agenda decisions) missing punctuation ';' at end of (a) |
| 101 | Considering whether to respond to a tentative agenda decision | 10.69a) | S | Sandra Thompson | Factors to consider when responding to Tentative Agenda Decisions. Paragraph 10.6(a) should refer to IFRIC not IASB. And suggest clarify this is not an exhaustive list. |
| 102 | Responding to tentative agenda decisions | 10.7 | S | Pauline Wallace | Why do we need paragraph 10.7. Paragraph 10.6 already gives us flexibility to respond to an IFRIC if we wish as it only sets out examples of situations where we might respond and paragraph 10.7 reads rather oddly to me. |
| Section 11: Due Process Compliance Statement | |||||
| 103 | 11.1 | Section 4 (governance) if you agree to retitle. | |||
| 104 | Content | 11.3(b) | Katherine Coates Katherine Coates |
Add "as applicable to the subject matter of the project" at the end Paragraph 11.3(b) references changes to PIP but I don't think the earlier descriptions of PIP processes indicate how changes are reported or approved. |
Questions
| Commentator | Suggestion made | UKEB Secretariat response | |||
|---|---|---|---|---|---|
| Mike Wells | All questions in the Invitation to Comment. Should something like 'If not, why not?', be added immediately after each question. Otherwise, we will find it difficult to understand and benefit from the objection in our redeliberation. |
Proposed questions for public consultation
Our proposed questions for the invitation to comment are shown below.
| Proposed questions |
|---|
| Section 4: Governance activities |
| 1. Do you agree with the processes described for the UKEB's governance activities in paragraphs 4.1–4.28? Where you disagree, please provide your rationale? |
| Section 5: Influencing process |
| 2. Do you agree with the processes described for the influencing process section in paragraphs 5.1–5.35? Where you disagree, please provide your rationale? |
| 3. Do you agree with the milestones in paragraph 5.7, including the mandatory milestones identified? Where you disagree, please provide your rationale? |
| 4. Do you agree that reduced mandatory outreach activities should be allowed in exceptional circumstances as explained in paragraphs 5.20–5.21? Where you disagree, please provide your rationale? |
| Section 6: Endorsement process |
| 5. Do you agree with the processes described for the endorsement process section in paragraphs 6.1–6.46? Where you disagree, please provide your rationale? |
| 6. Do you agree with the milestones in paragraph 6.10, including the mandatory milestones identified? Where you disagree, please provide your rationale? |
| 7. Do you agree that the standard consultation period for a Draft Endorsement Criteria Assessment (DECA) should be 90 days, as explained in paragraph 6.24 of the draft Handbook? Where you disagree, please provide your rationale? |
| 8. Do you agree that shorter comment periods should be allowed for a DECA in exceptional circumstances as explained in paragraph 6.27 of the draft Handbook? Where you disagree, please provide your rationale? |
| Section 7: Thought leadership and research programme |
| 9. Do you agree with the processes described for the thought leadership and research programme section in paragraphs 7.1–7.32? Where you disagree, please provide your rationale? |
| 10. Do you agree with the milestones in paragraph 7.13, including the mandatory milestones identified? Where you disagree, please provide your rationale? |
| 11. Do you agree with the processes described for the post-implementation reviews section in paragraphs 8.1–8.32? Where you disagree, please provide your rationale? | | Section 9: Advisory groups | | 12. Do you agree with the processes described for the advisory groups section in paragraphs 9.1–9.22? Where you disagree, please provide your rationale? | | Section 10: Influencing the work of the IFRS Interpretations Committee | | 13. Do you agree with the processes described for influencing the work of the IFRS Interpretations Committee in paragraphs 10.1–10.13? Where you disagree, please provide your rationale? | | Other | | 14. Are there any other comments you would like to make? |
Footnotes
-
The UKEB was established through The International Accounting Standards and European Public Limited-Liability Company (Amendment etc.) (EU Exit) Regulations 2019 (Statutory Instrument 2019 No. 685 (SI 2019/685): https://www.legislation.gov.uk/uksi/2019/685/made ↩↩↩↩↩↩
-
This term has the meaning given in SI 2019/685 by referring to Article 2 of Regulation (EC) No 1606/2002 of the European Parliament and of the Council of 19 July 2002 on the application of international accounting standards: "...'international accounting standards' shall mean International Accounting Standards (IAS), International Financial Reporting Standards (IFRS) and related Interpretations (SIC-IFRIC interpretations), subsequent amendments to those standards and related interpretations, future standards and related interpretations issued or adopted by the International Accounting Standards Board (IASB)". ↩↩↩↩↩↩
-
The International Accounting Standards (Delegation of Functions) (EU Exit) Regulations 2021 No. 609 (SI 2021/609). https://www.legislation.gov.uk/uksi/2021/609/made/data.pdf ↩↩↩↩↩↩
-
The respective responsibilities of the Secretary of State for BEIS, FRC and UKEB are set out in a Memorandum of Understanding on the UKEB here: https://assets-eu-01.kc-usercontent.com/99102f2b-dbd8-0186-f681-303b06237bb2/0633cede-348c-478f-b714-3cdb30b058be/UKEB-FRC-BEIS-MoU-22May2021.pdf ↩↩↩↩↩↩
-
The International Accounting Standards (Delegation of Functions) (EU Exit) Regulations 2021 No. 609. ↩
-
The Terms of Reference can be found here: https://assets-eu-01.kc-usercontent.com/99102f2b-dbd8-0186-f681-303b06237bb2/bcf857be-0260-40b2-8e73-2c3123694d4e/UKEB-Terms-of-Reference-2021.03.26.pdf ↩
-
While the relevant legislation uses only the term 'adoption' and does not refer to 'endorsement', for the purposes of this Handbook the term 'endorsement' is generally used when referring to the assessment of new (or amended) international accounting standards against the statutory adoption criteria, reflecting general usage. This is not intended to imply the existence of two distinct statutory functions or processes. ↩↩
-
The UKEB's processes for endorsing new (or amended) international accounting standards are described in Section 6 of this Handbook. ↩↩
-
As set out in Sections 5-8 and 10 in the Handbook, public consultation will be flexible and proportionate to the issue being addressed. ↩↩
-
The UKEB's processes for influencing international accounting standards (including the work of the IFRS Interpretations Committee) are described in Sections 5 and 10 of this Handbook. ↩↩
-
The processes for the UKEB's thought leadership and research programme are described in Section 7 of this Handbook. ↩↩
-
Regulation 8 of the International Accounting Standards and European Public Limited-Liability Company (Amendment etc.) (EU Exit) Statutory Instruments Regulation 2019 No. 685 (SI 2019/685), places an obligation to consult those with an interest in the "quality and availability of accounts, including users and preparers of accounts". ↩↩↩
-
These can consist of IASB projects and activities that are steps toward possible publications including research papers, discussion papers, requests for information, requests for views, exposure drafts, draft IFRIC Interpretations, final Amendments, Standards and final IFRIC Interpretations, or post-implementation reviews. ↩↩
-
'Annual improvements' are amendments that meet the criteria in paragraphs 6.10–6.14 in the IASB and IFRS Interpretations Committee Due Process Handbook and are sufficiently minor or narrow in scope that are bundled together in a single Exposure Draft document (even though amendments are unrelated). Narrow-scope amendments do not meet the criteria for annual improvements but meet the criteria in paragraph 5.16 in the same Handbook and are considered 'narrow' in scope. ↩↩↩
-
On Friday 21 May 2021, the Secretary of State for Business, Energy and Industrial Strategy (BEIS) delegated statutory powers to the newly established UK Endorsement Board (UKEB). One of the UKEB's delegated functions is the responsibility for the endorsement and adoption of IFRS for use by UK companies. ↩↩
-
Regulation 5 of SI 2019/685: https://www.legislation.gov.uk/uksi/2019/685/made. See also section 2 in this Handbook. ↩↩
-
This is consistent with Regulation 8 of Statutory Instrument (SI) 2019/685. ↩↩
-
For example, the IASB published the amendment Covid-19- Related Rent Concessions beyond 30 June 2021 (Amendment to IFRS 16) on 31 March 2021. It was effective for annual reporting periods beginning on or after 1 April 2021. Earlier application was permitted, including in financial statements not authorised for issue (or signed) at 31 March 2021. ↩↩
-
If the formal written vote is not to adopt, then only the outcome of the vote will be published. ↩↩↩
-
This is consistent with Regulation 9(3) of Statutory Instrument (SI) 2019/685. ↩↩
-
Section 8 of this Handbook 'Post-implementation Reviews' provides an overview of the process that the UKEB follows for conducting its own post-implementation reviews. ↩↩
-
Refer to paragraphs 6.48-6.59 in the IASB and IFRS Interpretations Committee Due Process Handbook. ↩↩
-
This may be the case for an advisory group providing expert perspectives (for example, in the operation of rate-regulatory schemes) or providing input on the implementation of new requirements in an international accounting standard. ↩↩
-
For example, accounting bodies and auditors have both a close interest in the use and implementation of international accounting standards and both have insights to share on the use of standards and on any concerns arising from that use. ↩↩
-
Refer to paragraph 1.3 in the IASB and IFRS Interpretations Committee Due Process Handbook, IFRS Foundation, (August 2020). The Conceptual Framework describes the objective of and concepts for general purpose financial reporting. It is a practical tool that helps the Board to develop requirements in IFRS Standards based on consistent concepts (refer to paragraph 4.20 in the same Handbook). ↩↩
-
Refer to paragraph 5.16 in the IASB and IFRS Interpretations Committee Due Process Handbook. ↩↩↩
-
For 'Annual improvements' refer to the criteria in paragraphs 6.10-6.14 in the IASB and IFRS Interpretations Committee Due Process Handbook. For narrow-scope' amendments refer to the criteria in paragraph 5.16 of the same Handbook. ↩↩
-
Agenda decisions explain why a standard-setting project has not been added to the IASB's work plan to address a question submitted and, in many cases, include explanatory material that explains how the applicable principles and requirements in IFRS Standards apply to the transaction or fact pattern described in the agenda decision. Refer to paragraphs 8.3-8.7 in the IASB and IFRS Interpretations Committee Due Process Handbook. ↩↩
-
Refer to paragraphs 5.15 to 5.16 in the IASB and IFRS Interpretations Committee Due Process Handbook. ↩
-
A "Due Process Compliance Statement" is only required when issuing a Discussion Paper (refer to Section 7 of this Handbook). ↩
-
A Feedback Statement is a mandatory due process activity as set out in Section 5 (Influencing Process), and in Section 6 (Endorsement Process). In Section 7 (Thought leadership and research programme) it is a mandatory due process activity when an Invitation to Comment has been published
ənly forfor a discussion paper. ↩