6.0 Goodwill subsequent measurement – Project Update
UK ENDORSEMENT BOARD 18 NOVEMBER 2021 AGENDA PAPER 6
Executive Summary
| Project Type | Research |
| Project Scope | Limited scope |
Purpose of the paper
This paper provides the Board with an update on the limited scope research project on the subsequent measurement of goodwill, approved at the October 2021 board meeting.
Summary of the Issue
This paper provides an update on the work undertaken since the October Board meeting.
Research has commenced in three main areas:
- Determination of the useful life of goodwill for amortisation purposes under UK GAAP; and
- Impact of transitioning to a hybrid model for the subsequent measurement of goodwill on the financial position of UK IFRS reporters; and
- Implications for UK IFRS reporters of transitioning to a hybrid model for the subsequent measurement of goodwill, including impact on debt covenants, legal and regulatory compliance, and costs.
Decisions for the Board
The Board is asked for comments on the initial research, the conclusions drawn and proposed next steps.
Recommendation
This paper provides an update and there are no recommendations for the Board.
Appendices
| Appendix 1 | Project update: goodwill measurement |
Background
1The UK Endorsement Board approved the Project Initiation Plan for a limited scope research project on the subsequent measurement of goodwill at its October 2021 board meeting.
2The project responds to and expands on a request from IASB staff to national standard setters to undertake research on the subsequent measurement of goodwill. The research will inform the IASB's redeliberations on its Discussion Paper DP 2020/1 Business Combinations: Disclosures, Goodwill and Impairment (the DP). IASB staff identified two specific areas of analysis for input from national standard setters. These are:
- How the useful life of goodwill is determined for amortisation purposes under national GAAP; and
- The potential impacts of reintroducing amortisation, including impact on financial position, financial stability, and legal and regulatory compliance.
3In addition, UKEB staff identified two further areas for analysis that it anticipated would be useful to the IASB in its ongoing redeliberations. These areas are:
- How a hybrid model1 can provide information that is useful for users of financial statements.
- Cost implications of a hybrid model.
4The IASB currently plans to vote on the proposals from the DP in Q1 2022.
5The IASB is currently redeliberating proposals from the DP. At its October 2021 meeting, the IASB discussed the DP's proposals to enhance the disclosure requirements in IFRS 3 Business Combinations. Specifically, the DP's proposed disclosures on management's objectives for business combinations and management's expected benefits from business combinations were discussed. The IASB tentatively decided that these disclosures should be located in the financial statements. The IASB also discussed practical concerns regarding the proposed disclosures, including whether they would be regarded as forward-looking information in some jurisdictions. The IASB was not asked to make any decisions on these practical concerns at its October 2021 meeting. At future meetings the IASB will continue its redeliberations on the DP's proposed disclosures, including whether to proceed with all of them.
Determination of the useful life of goodwill
6This paper provides an update on the UKEB research project on the subsequent measurement of goodwill since the Project Initiation Plan was approved. Research has commenced in three main areas:
- Determination of the useful life of goodwill for amortisation purposes under UK GAAP; and
- Impact of transitioning to a hybrid model for the subsequent measurement of goodwill on the financial position of UK IFRS reporters; and
- Implications for UK IFRS reporters of transitioning to a hybrid model for the subsequent measurement of goodwill, including impact on debt covenants, legal and regulatory compliance, and costs.
Details of the work commenced in each of these three areas are provided below.
Initial research and outreach
7The focus of our research so far has been on obtaining evidence to help us understand how accounting requirements have been implemented by UK companies. We commenced our work by undertaking some desk-based research, namely analysis of financial statements. As useful life of goodwill is required to be determined by companies using UK GAAP, we sought to identify large private companies with goodwill on their balance sheets. Using the UK's 75 largest private companies as a sample2, we analysed financial statements to gain initial insight into:
- How the useful life of goodwill is determined; and
- The extent of variation in the useful life of goodwill between different entities and sectors.
8Our analysis showed that:
- Of the UK's 75 largest private companies, 24 report under IFRS, a further 15 report under FRS 101, and 36 report under FRS 102. Of the 36 FRS 102 entities, 27 reported goodwill in the balance sheet.
- Analysis of the annual reports of the 27 entities reporting goodwill under FRS 102 showed:
- Factors used to determine the useful life of goodwill included: strength of brand, expected use of acquired assets, any legal, regulatory or contractual provisions that may limit the useful life, and expected life of the operating unit or line of business to which the goodwill relates.
- Approximately half of the entities determined the useful life of goodwill separately for each acquisition and disclosed a range of useful lives of goodwill. The ranges were most commonly 5 – 10 years or 10 – 20 years. One entity disclosed the remaining useful life of goodwill by each acquisition.
- Approximately half of the entities determined the same useful life for goodwill for all acquisitions. The useful life ranged from 5 years to 50 years across different entities, with the mode 10 years and the mean 9.8 years. The useful life was typically shorter in entities in the construction, retail and hospitality sectors. The useful life was typically longer in the luxury goods sector and where acquisitions had delivered technological capability or online presence.
- At least one entity recorded an impairment of goodwill in addition to regular amortisation. The impairment was triggered by a fall in demand for serviced office space, one of the entity's key business lines, due to the pandemic.
Initial conclusions
10Based on our initial research and outreach to the FRC, our initial conclusions are:
- A regime which requires management to determine the useful life of goodwill results in an assessment of the useful life which is specific to the entity and, in some cases, specific to individual acquisitions.
- In the instances we observed, it appears that a hybrid model can provide useful information to users of financial statements.
- The correlation between longer useful life of goodwill and acquisitions relating to technology or online presence highlights the ongoing relevance of goodwill in the new-age economy.
Further work planned
11We are planning to undertake targeted outreach to the 27 FRS 102 goodwill reporters and their auditors in order to identify best practice and to explore:
- Whether there are further factors, in addition to those identified from our initial review of financial statements, which are considered in determining the useful life of goodwill; and
- Whether determining the useful life of goodwill on an acquisition-by-acquisition basis results in a larger number of CGUs for impairment testing purposes; and
- How potential changes in the useful life of goodwill are identified and, when indicated, how the useful life of goodwill is re-estimated; and
- Whether acquisitions of unincorporated businesses are frequent, and therefore whether goodwill arising in single entity accounts is significant and whether its amortisation would have a significant impact on distributable profits and dividend payments; and
- Experience of auditing the useful life of goodwill; and
- Cost and resource implications of determination of the useful life of goodwill.
Questions for the board
12Do Board Members have any comments on research and outreach undertaken to date and initial conclusions reached?
13Do Board Members have any comments on the further work planned?
Transitioning to a hybrid model - financial position
Initial research
14We analysed financial statements for the FTSE 350 to ascertain the total value of goodwill and its value as a proportion of total assets and net assets reported in their financial statements for 2020. This analysis builds on the analysis of goodwill for the FTSE 350 from 2005 - 2019 undertaken earlier this year as part of the UKEB Secretariat response to the DP.
15Our analysis showed that:
- Goodwill for the FTSE 350 has stayed constant at £383bn between 2019 and 2020.3
- Goodwill represented 15.1% of total assets for the FTSE 350 in 2020 (2019: 16.9%).
- Goodwill represented 50.9% of net assets for FTSE 350 entities in 2020 (2019: 38.1%). Goodwill exceeds net assets for 8% of FTSE 350 entities or 27 entities (2019: 11% / 39 entities).
Initial conclusion
16Goodwill continues to represent a significant proportion of total assets and net assets for the FTSE 350. Therefore, restating historic goodwill on transition to a hybrid model has the potential for a significant impact on balance sheet profiles. However, the extent of the impact depends on the age profile of goodwill balances and their useful life.
Next steps
17We intend to approach a sample of entities with significant goodwill balances and multiple acquisitions to ask if they would model a potential transition to the hybrid model.
Questions for the board
18Do Board Members have any comments on research and outreach undertaken to date and initial conclusions reached?
19Do Board Members have any comments on the further work planned?
Transitioning to a hybrid model – other implications
20We have commenced drafting a survey to lenders, preparers and auditors to gather evidence on other implications of transitioning to the hybrid model. The survey will cover the following main areas: impact on debt covenants, cost implications, regulatory implications, and frequency of acquisition of unincorporated businesses4.
21We have approached eight professional membership organisations with a request to distribute the survey to their members on behalf of the UKEB. Six of those organisations have agreed to distribute the survey to their members and a further one organisation has agreed to promote it via social media.
Next Steps
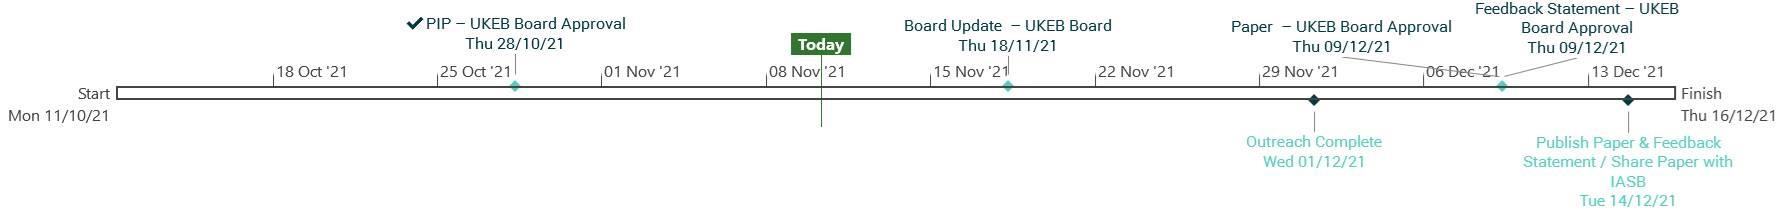
22We have agreed to share our research with IASB staff in December 2021 to allow for timely incorporation into the IASB feedback process. The IASB intends to vote on the proposals in its DP in Q1 2022.
23We will bring a draft paper and feedback statement to the Board's December 2021 meeting for approval to share with the IASB.
Timeline
24The timeline is shown below:
Footnotes
-
The UKEB Secretariat's response to the IASB's DP 2020/1 Business Combinations: Disclosures, Goodwill and Impairment advocated a hybrid model for the subsequent measurement of goodwill. In the hybrid model, an annual amortisation charge would be made over the useful economic life of goodwill and would be supported by impairment testing. ↩
-
Sample taken from Sunday Times Top Track League Table of UK private companies, ranked by turnover, published July 2020. Such companies have a similar financial profile to some IFRS reporters at the lower end of the listed market. ↩
-
However, goodwill for the FTSE 100 has increased from £307bn to £317bn between 2019 and 2020 and goodwill for the FTSE 250 has decreased from £76bn to £66bn between 2019 and 2020. ↩
-
Data on the frequency of acquisitions of unincorporated businesses will provide evidence on whether goodwill in single entity financial statements is frequent or significant and therefore whether the impact of its amortisation on distributable profits and dividends is likely to be significant. ↩