5.0 PIR IFRS 9 – Classification & Measurement - Approve Project Initiation Plan
| Project Type | Influencing |
| Project Scope | Significant |
| Purpose of the paper | This paper presents a draft Project Initiation Plan (PIP) in respect of the IASB's Post Implementation Review (PIR) of IFRS 9 Financial Instruments – Classification and Measurement. |
| Summary of the Issue | The IASB has commenced a PIR of IFRS 9 Financial Instruments, starting with a review of the classification and measurement requirements. Separate reviews of the impairment (Expected Credit Loss) and hedge accounting requirements of IFRS 9 are expected in 2022. The IASB has issued a Request for Information seeking comments by 28 January 2022. The draft PIP sets out the proposed approach to developing the UKEB's response to the IASB. |
| Decisions for the Board | The Board is asked to approve the draft PIP. |
| Recommendation | We recommend the Board approves the draft PIP. |
| Appendices | Appendix 1 Draft Project initiation Plan |
Executive Summary
Project Initiation Plan
1. Background
1In accordance with its due process, the IASB is required to conduct a post implementation review (PIR) of each new IFRS standard and major amendment. The purpose of the PIR is to assess whether the standard or amendment is meeting its objectives, can be applied consistently, that information is useful to users of financial statements, and that implementation costs are as expected.
2The IASB's possible actions following the PIR are to:
- Produce educational materials;
- Conduct follow-up research work for possible standard setting; or
- Take no action.
3In July 2014 the IASB issued IFRS 9 Financial Instruments. The Standard was effective for annual periods commencing on or after 1 January 2018. Insurers may defer the effective date until 1 January 2023 to align with implementation of IFRS 17 Insurance Contracts, providing certain conditions are met.
4IFRS 9 replaced IAS 39 Financial Instruments: Recognition and Measurement. IFRS 9 introduced changes to the IAS 39 accounting requirements in three main areas: classification and measurement, impairment (introduction of an Expected Credit Losses) and hedge accounting.
5The IASB has commenced its review of IFRS 9 by considering the standard's classification and measurement requirements, together with the related disclosure requirements in IFRS 7 Financial Instruments: Disclosures. Separate RFIs addressing IFRS 9's impairment and hedge accounting requirements are expected in 2022.
Overview of the Request for Information
6The IASB's Request for Information (RFI) was published on 30 September 2021 and is open for comment until 28 January 2022.
7This RFI addresses the classification and measurement requirements in IFRS 9, together with the related disclosure requirements in IFRS 7.
8The RFI identifies nine areas on which the IASB are seeking feedback. These include:
- Classification and measurement – general information on the effects:
- Did IFRS 9 successfully align the measurement of assets to their cashflow characteristics/how the entity expects to manage them?
- Did this result in useful information about the amount, timing and uncertainty of future cashflows?
- Business Model for managing financial assets:
- Is the business model test working as intended/applied consistently/giving rise to unexpected effects?
- Spotlight on reclassifications: The IASB would like to understand the nature, and frequency of reclassifications.
- Contractual cashflow characteristics:
- Is the cashflow characteristics assessment working as intended/applied consistently/giving rise to unexpected effects?
- Spotlight: ESG¹ products. The IASB are seeking further information on how IFRS 9 is being applied to such products and whether the resulting classification and measurement provides decision useful information.
- Spotlight: Contractually linked instruments. The IASB would like to understand the fact pattern to which the requirements for contractually linked instruments are being applied, situations in which assessment is complex, and whether IFRS 9 provides sufficient guidance on the scope of such assets.
- Equity instruments and other comprehensive income:
- Is the option to present fair value changes on investments in equity instruments working as intended/applied consistently/giving rise to unexpected effects? For what equity instruments do entities elect to present fair value changes in OCI?
- Spotlight: Recycling gains and losses.
- Financial liabilities and own credit:
- Are the requirements working as intended?
- Are there any other matters related to financial liabilities that this review should consider?
- Modifications to contractual cashflows:
- Are the requirements working as intended and can they be applied consistently?
- Amortised cost and the effective interest method:
- Are the requirements working as intended and can they be applied consistently?
- Spotlight: Interest rates subject to conditions and estimating future cash flows. The IASB seeks further information on how the effective interest rate (EIR) is being calculated in such cases following a recent IFRS Interpretations Committee (IFRIC) question² or in cases where products have ESG features.
- Transition:
- Did the transition requirements work as intended and were there any unexpected challenges in application?
- Other matters – are there any other matters IASB should examine as part of this review?
Prioritisation of issues
9It is possible that not all the issues identified in the RFI are of significant concern to UK stakeholders. We propose that our response to the RFI be responsive to UK stakeholder feedback and therefore focus on areas where stakeholders have particular concerns. This approach will support delivery of a response reflecting UK stakeholder views despite the challenging timetable described in paragraph 17.
Analysis of key issues
10Only limited work on the identification of key issues has been carried out so far. However, initial desk-based research and observation of an industry working group on this topic indicates that ESG Lending, Contractually Linked Instruments and Modifications to Contractual Cashflows are likely to be topics of particular interest to UK stakeholders. Further issues will emerge as priorities during our stakeholder consultation process.
ESG Lending
11We understand that financial assets increasingly include ESG features, and that this is likely to be permanent and growing trend. A simple example of such a product would be a basic bank loan issued at a reduced interest rate which is predicated on the borrower meeting certain ESG targets. Should those ESG targets not be met the interest rate would rise.
12Concern has been expressed that the inclusion of ESG features may make what are otherwise basic lending arrangements ineligible for amortised cost accounting, as, due to the ESG feature, they fail to pass the SPPI³ test. This does not imply that stakeholders think all ESG products should qualify for amortised cost accounting. Some products are more sophisticated and where appropriate should be accounted for at fair value. This debate centres around identifying the appropriate accounting outcome for products that, if not for the ESG feature, would be considered basic lending.
13Some have suggested that the ESG feature forms part of the bank's profit margin (the bank's contribution to sustainable finance), and hence meets the SPPI test. Others argue that the ESG features are part of the pricing of credit risk and pass the SPPI test for this reason. However, currently there is no clear cut, tested, view as to whether such products pass the SPPI test and existing practice varies.
14We understand that preparers would prefer such products to qualify for amortised cost accounting. They note that, where the product represents basic lending, amortised cost provides users with more decision useful information. The EIR interest flows are reported as interest income which in various forms is monitored as a key metric. The expected credit loss requirements of IFRS 9 are considered to provide comprehensive and transparent information on the performance of the product.
Contractually Linked Instruments
15Some preparers consider that the drafting in IFRS 9 does not make sufficiently clear which instruments qualify as Contractually Linked Instruments. This has led to inconsistent application, unnecessarily time consuming analysis and at times counter-intuitive results. We note that the final Contractually Linked Instrument guidance was not subject to an exposure draft during the development of IFRS 9 and therefore this PIR provides an important opportunity for stakeholders to provide feedback on its use.
Modifications to Contractual Cashflows
16The guidance on accounting treatment following the modification of contractual cashflows is inconsistent between assets and liabilities. The assessment for financial assets is further complicated when the contractual change is driven by a debt restructuring or similar forbearance event, where cashflows have already varied from the underlying contract and some loss on the loan may have been recognised through the IFRS 9 impairment process. We are aware this issue caused some confusion at the time of implementation, but acknowledge it may have been resolved as normal practice emerged subsequently. We plan to seek further direction from stakeholders on this topic.
Outreach
UK Stakeholders
17The project timetable is challenging, and this is exacerbated by the consultation period cutting across the holiday season, Board dates which fall outside the normal pattern to accommodate the holiday season, and a time in which many companies are preparing for or undertaking their year-end processes.
18To ensure all stakeholders have sufficient opportunity to share their views we propose the use of both a stakeholder survey and draft comment letter. The stakeholder survey will include open ended questions on the RFI topics and be live from mid-November, while the draft comment letter would be published following the December Board meeting. Combined this provides a general consultation period of approximately 6 weeks running from mid-November to the end of December. This will allow all interested stakeholders to provide input on issues of concern, including those who may find the timing of the draft comment letter inconvenient. We plan to promote the survey and draft comment letter via the Association of Corporate Treasurers (ACT), in addition to the usual channels, to encourage corporate treasurers to share their experiences.
19In addition to this general consultation, we would like to undertake a number of specific outreach events as follows.
- a financial services preparer roundtable;
- an audit firm roundtable;
- discussion or roundtable with users; and
- discussion with relevant financial services regulators.
20At time of writing these events have yet not been set up, and we are conscious that the relevant organisations have multiple demands on their time, including contributing to responses on this RFI with their own firms and other industry bodies.
21We propose to supplement this outreach with desk-based research, including review of the FRC's analysis of IFRS 9 implementation contained in the Corporate Reporting Annual and Thematic reviews.
International Stakeholders
22We are already in touch with the IASB's project team and will explore possibilities for joint outreach.
23EFRAG has recently published their draft comment letter on this project. We plan to reach out to their project team to understand their areas of concern, as due to the cross-border nature of financial services we wish to understand any overlap with issues we are hearing from UK stakeholders. We may speak to other national standard setters should we become aware of similar areas of potential overlap.
Next Steps
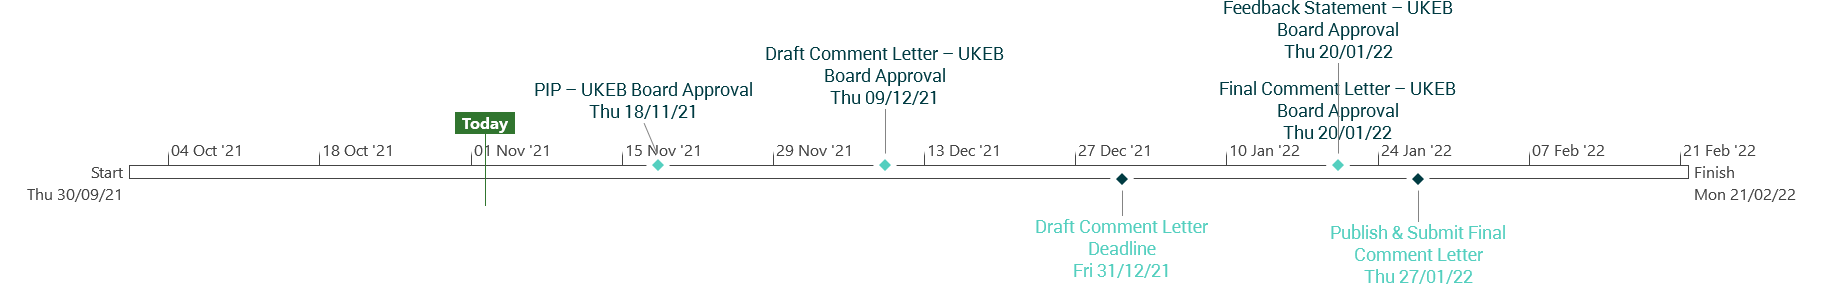
24The key project milestones are as follows:
| Date | Milestone |
|---|---|
| 30 September 2021 | IASB Publish RFI |
| 15 November 2021 | Publish stakeholder survey. |
| 18 November 2021 | Approve PIP |
| 09 December 2021 | Approve Draft Comment Letter |
| 15 December 2021 | Publish Draft Comment Letter. Deadline for responses 31 December 2021. |
| 20 January 2022 | Approve Final Comment Letter |
| Approve Feedback Statement | |
| 28 January 2022 | Submit Comment Letter to IASB |
| Publish Feedback Statement on website. |
Footnotes
-
ESG products are financial products which contain a feature related to the Environmental, Social or Governance practices of the counterparty. These are explained further in paragraphs 11-14 of this paper. ↩
-
IFRIC June 2021, TLTRO III Transactions (IFRS 9 Financial Instruments and IAS 20 Accounting for Government Grants and Disclosure of Government Assistance). ↩
-
To qualify for amortised cost accounting the financial asset must pass both a business model test and a cashflow characteristics (SPPI) test. The SPPI test requires cashflows on the instrument to consist of solely payments of principle and interest consistent with a basic lending arrangement. Basic lending arrangements are said to include consideration for the time value of money, credit and other basic lending risks, certain costs and a profit margin consistent with basic lending. ↩