Project Initiation Plan - Proposed amendments to the IFRS Foundation Due Process Handbook
Purpose
A1This paper sets out the plan to influence the proposed amendments to the IFRS Foundation Due Process Handbook (the Handbook) included in the IFRS Foundation's Exposure Draft (ED) Proposed Amendments to the IFRS Foundation Due Process Handbook. The ED was published on 19 December 2024 with a consultation period ending on 28 March 2025.
A2The UKEB is responding to this ED as the content of the Handbook impacts how the UKEB engages with and influences the IFRS Foundation, its boards and committees, in carrying out its own statutory duties.
A3The IFRS Foundation last updated the Handbook in August 2020. The ISSB started operating in 2022, after the current Handbook was issued. It does not, therefore, reference the ISSB's work directly.
A4For over two years, the ISSB has been applying the due process set by the IFRS Foundation, in the current Handbook, for the International Accounting Standards Board (IASB) to follow. However, the Due Process Oversight Committee (DPOC) of the Trustees of the IFRS Foundation has now decided to formally specify that the IASB and ISSB are applying the same due process, as set out in the Handbook.
A5The DPOC is also using this opportunity to propose targeted enhancements and clarifications to the Handbook, based on the Foundation's recent experiences.
Summary of proposed changes
A6The DPOC is of the view that the current due process is robust and thorough, and that the 2020 amendments are working well. Accordingly, the ED's proposed amendments are enhancements and clarifications, rather than fundamental changes to the Foundation's due process. The most extensive changes are set out in the sections below.
Reflecting the ISSB in the Handbook
A7The proposed amendments update the Handbook to include references to the ISSB. However, the DPOC intends to continue to monitor the need for changes or additions to the due process as it notes the ISSB is still at an early stage in its operations and, both boards are at an early stage in their connectivity work.
SASB Standards
A8The ED also proposes adding a new Annex B¹ setting out the due process for the SASB Standards and the SASB Standards Taxonomy. While they are not IFRS Standards, IFRS S1 requires that entities applying that standard must consider SASB Standards for sustainability-related risks and disclosures.
A9The due process set out in the new annex was approved by the DPOC and published on the Foundation's website in 2022. The due process allows the SASB Standards Board Adviser Group to develop amendments to the SASB standards, for ratification by the ISSB.
A10The ED does not propose any changes to formally incorporate the SASB Standards as ISSB industry-based standards, which have been through full due process.
Reflecting Connectivity
A11A new IFRS Foundation objective is proposed, which is that the IASB and ISSB develop complementary sets of Standards.
A12Several proposed amendments to the Handbook focus on enhancing the integration between the IASB and ISSB; and strengthening the connections between the boards and their respective standards. Together, the amendments aim to provide a cohesive framework for the development and implementation of the two boards' standards, ensuring consistency and clarity for stakeholders.
Post-implementation Reviews
A13The requirements for a Post-implementation Review (PIR) were not substantively amended in the 2020 update. At that time, the IASB had only conducted 3 PIRs. Subsequently, the Foundation has gained more experience from PIRs on major IFRS Accounting Standards. The DPOC monitored these developments, through its oversight of the IASB's PIRs, and proposes reflecting them in the Handbook. The amended requirements will also apply to the ISSB when it undertakes PIRs on its standards.
A14The proposed amendments include setting an objective for PIRs: "to assess whether the effects of applying the new Standard / major amendments are as intended when developed".
A15The ED also proposes starting a PIR "after the requirements have been applied for some time to ensure information is available to assess the requirements' effects in their entirety... (while balancing the need to conduct a review within a reasonable period of time to ensure the relevant board is aware of matters that require attention)".
This will replace the current requirement of commencing work two years after international application (around 30-36 months after the effective date).
Invitation to Comment
A16The Invitation to Comment (ITC) asks two questions:
- Do you agree with how the DPOC proposes to reflect the creation of, and the due process for, the ISSB in the Handbook?
- Do you agree with the proposed enhancements and clarifications to the Handbook?
Project Plan
A17As this project does not respond to a paper issued by either the IASB, ISSB or IFRIC, it is not specifically covered by the UKEB's Due Process Handbook. However, the proposed approach aligns with the due process requirements for technical influencing projects, made proportionate to the non-technical nature by including two slight variations:
- The UKEB will not publish a Draft Comment Letter (DCL). Instead, the Board will agree a list of the main points to be included in the Comment Letter.
- There will be no formal stakeholder outreach via the publication of a DCL. Instead, the list of issues to be referenced in the (Final) Comment Letter will be sent, via email, to the members of the UKEB's Advisory and Working Groups for comments and views, in time for preparation of the UKEB's (F)CL.
A18A proportionate approach has been applied in accordance with paragraphs 3.7 and 5.3 of the UKEB's Due Process Handbook. The Secretariat recommends the 'Limited scope' project plan shown below. The factors considered, in arriving at this project plan, are described in paragraphs A19-A25. A timeline for the key project milestones is presented in paragraph A30.
Project - key activities
| Key activities | Due Process Handbook |
|---|---|
| Board Education Session (complete) | 4.10b |
| Creation of a Project Initiation Plan (this document) | Optional |
| Desk-based research to support the proportionality assessment including: | 5.4-5.8 |
| a) Review of UKEB Due Process Handbook and other organisations due process requirements. | Mandatory |
| b) Review of DPOC papers, presentations and meetings. | 5.9 |
| Stakeholder outreach pre-PIP | Optional |
| a) The list of issues to be considered for inclusion in the UKEB's Comment Letter were discussed with UK and international bodies with an interest in this project, including Government and regulators. | 5.10-5.12 |
| b) In addition, the project was highlighted as an item for noting at the meeting of the UKEB Investor Advisory Group, which was scheduled during the period between the Board Education Session and the February 2025 Board meeting. | Mandatory |
| Stakeholder outreach post PIP | 5.18 |
| a) The list of issues to be included in the UKEB's Comment Letter will be circulated, via email, to all the members of the UKEB Advisory and Working Groups, for comment. | Mandatory |
| b) In addition, the project will be highlighted as an item for noting at the forthcoming meetings of the UKEB Advisory Groups² that are scheduled for the period between the February 2025 and March 2025 Board meetings. | 5.19-5.26 |
| (Final) Comment Letter | Mandatory |
| A (final) comment letter will be created for Board approval, submission to the IASB, and publication on the UKEB website. | |
| Project Closure | |
| A Feedback Statement and Due Process Compliance Statement will be prepared. Once approved by the Board these documents will be published on the UKEB website. |
Proportionality assessment
Significance and size
A19The UKEB is the primary stakeholder for this project, as the IFRS Foundation's due process directly impacts how the UKEB carries out its statutory functions and adheres to its own due process requirements.
Complexity
A20The proposals are intended to formally apply the same due process requirements to the ISSB, as the IASB, and to provide both boards (and the IASB's Interpretations Committee) with an enhanced and clarified due process. As such, we do not believe that the proposals are highly technical or complex.
Expected timeline / urgency
A21There is no indication of any need for urgent resolution or accelerated timeline in the UK.
Expected interest / sensitivity
A22There is no indication of wider UK stakeholder concerns in relation to this project.
Feedback on the proposals from desk-based research / initial outreach
A23Engagement with other UK bodies with responsibility for areas of UK company reporting confirmed that the content of our respective letters is not expected to be contradictory.
A24Review of the UKEB's Due Process Handbook³ (DPH) highlighted the following differences from the proposals in the ED:
- PIRs – the proposed objective of the PIR is "to assess whether the effects of applying the new Standard / major amendments are as intended when developed". This differs from the UKEB's DPH, which states that the objective of our PIRs is to "assess the impact of adoption".
- PIRs – the ED proposes removing the requirement for PIRs to commence after the new requirements have been applied internationally for 2 years. In the UK, legislation⁴ sets out the requirement that PIRs must be carried out for any Standard considered likely to lead to a significant change in accounting practice. A report of the review's conclusions must be published no later than 5 years after the date on which the standard takes effect.
Connectivity
A25The ED proposes amendments to the Handbook to improve connectivity between the boards and their respective sets of Standards.
Recommended UKEB project scope
A26Based on the proportionality assessment above we recommend a 'Limited' project scope, and the approach described in this document reflects this.
Resources allocated
A27To undertake the activities described in this project plan, a Project Director – Governance Lead has been assigned for the brief period of the project. The required resources are allowed for in the 2025/26 UKEB plan and budget.
A28In addition, some input from the economics team has been allocated, to develop the UKEB's recommendations regarding the IFRS Foundation's approach to undertaking impact assessments.
Setting up an ad-hoc advisory body
A29The UKEB will not require a separate ad-hoc advisory body for this project. Existing UKEB advisory and working groups have the necessary skills and expertise to support this project and will be consulted, as outlined in the project plan.
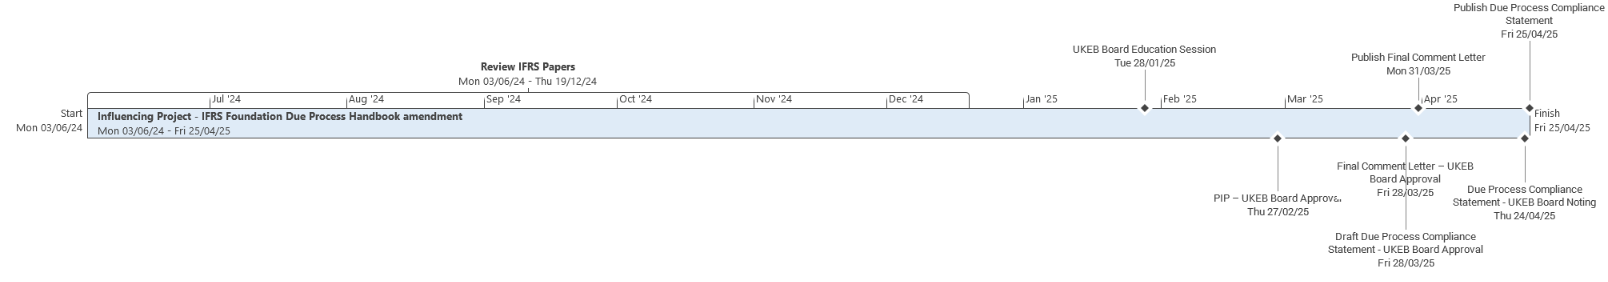
Project Initiation Plan: Proposed amendments to the IFRS Foundation Due Process Handbook (Exposure Draft) - Project timeline.
A30The diagram below is a graphical view of the mandatory milestone activities described above.
Footnotes
-
Annex A - The IFRS Taxonomies due process; Annex B - The SASB Standards and the SASB Standards Taxonomy due process ↩
-
The UKEB Advisory Groups scheduled during the period between the February 2025 and March 2025 Board meetings are the Preparer Advisory Group (PAG) and the Accounting Firms and Institutes Advisory Group (AFIAG). ↩
-
UKEB Due Process Handbook, December 2022 ↩
-
The International Accounting Standards and European Public Limited-Liability Company (Amendment etc.) (EU Exit) Regulations 2019 (SI 2019/685 - Regulation 11) ↩